
 Polypeptide Market | 2026-2036
Polypeptide Market Size, Share, and Industry Trends Forecast 2026-2036
Polypeptide Market Analytics
Switzerland is narrowing its position as a critical European hub for polypeptide manufacturing, with Bachem Holding AG leveraging its Villeneuve facilities to sustain leadership in large-scale peptide synthesis. PolyPeptide Group anchors capacity across three continents, competing through specialized cGMP infrastructure for commercial peptide APIs. Novo Nordisk A/S dominates the insulin peptide segment, extending its manufacturing footprint to match rising diabetes therapy demand.
Polypeptides are short chains of amino acids linked by peptide bonds, typically comprising fewer than one hundred residues, synthesized through solid-phase peptide synthesis or recombinant DNA methods for therapeutic, diagnostic, and research applications. Therapeutic peptides command the largest revenue share due to established oncology and metabolic disorder portfolios, while antimicrobial peptides represent the fastest-growing product category driven by rising antibiotic resistance. Injectable delivery maintains structural dominance, though oral peptide formulations are gaining traction as formulation technologies improve bioavailability.
The FDA, EMA, and China's NMPA enforce divergent purity and impurity profiling standards that directly shape manufacturing investment priorities and facility qualification timelines. REACH and the EU MDR impose additional chemical safety and device combination constraints on peptide-drug conjugates entering European markets. Stakeholders must monitor regulatory harmonization progress between major agencies to anticipate approval pathway efficiencies and manufacturing relocation incentives.
Market Dynamics
The FDA's accelerated approval pathways for peptide therapeutics are compressing development timelines and forcing manufacturers to reconfigure quality systems around real-time release testing rather than batch-based validation.
Growth Catalysts
- Antimicrobial peptide pipelines:Rising antibiotic resistance is pulling investment toward novel peptide-based anti-infectives for hospital-acquired infections.
- China's NMPA biologics reforms:Streamlined IND review timelines are attracting foreign sponsors to conduct pivotal trials domestically.
- Oral peptide bioavailability advances:Permeation enhancers and protease-resistant backbone modifications are unlocking chronic disease markets previously reserved for small molecules.
Market Restraints
- Amino acid feedstock volatility:Prices for protected amino acids fluctuate with agrochemical input costs and Chinese environmental enforcement cycles.
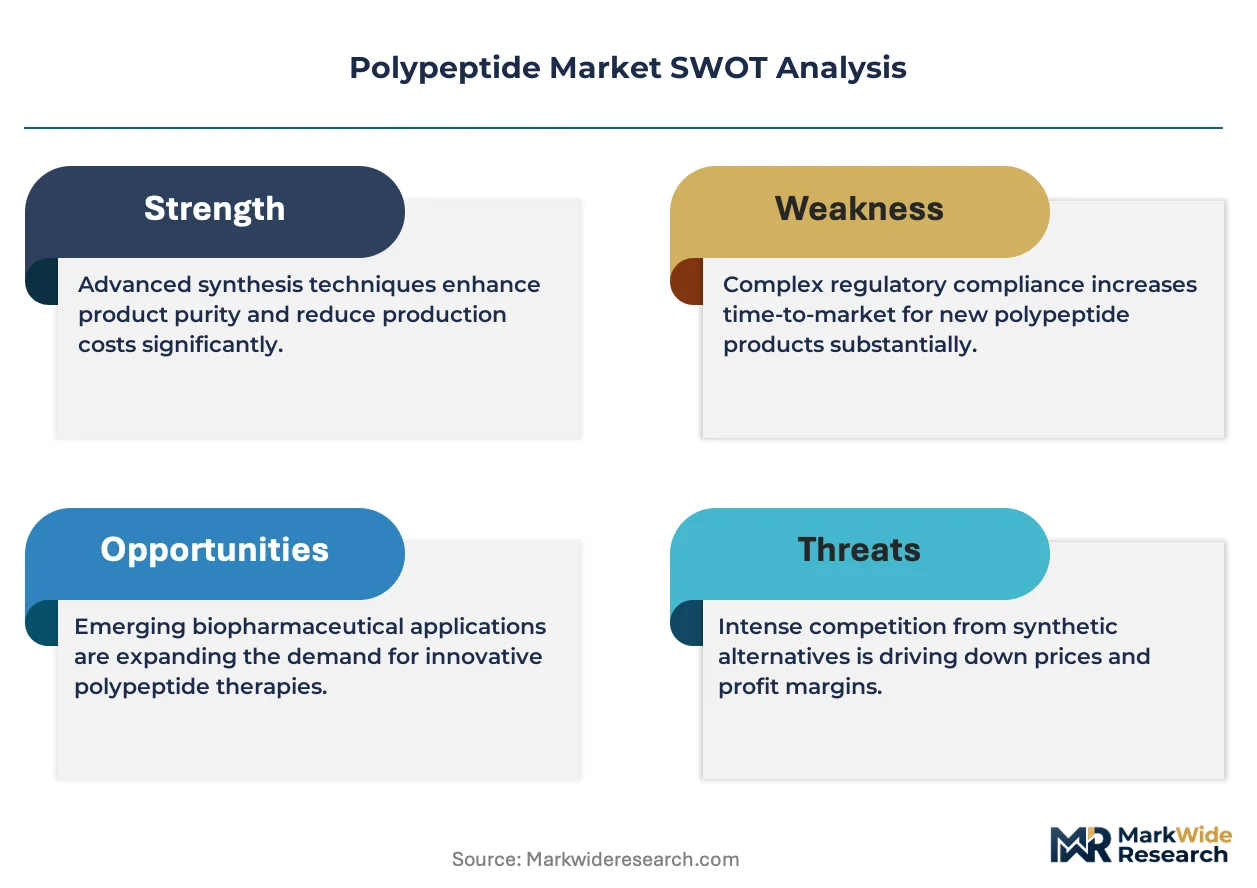
- Swiss manufacturing concentration:Bachem and PolyPeptide Group facilities in Villeneuve and Torrance create single-source exposure for commercial insulin APIs.
- Recombinant protein competition:Biosimilar insulin analogs and GLP-1 receptor agonists from microbial expression systems threaten chemical synthesis volumes.
Strategic Opportunities
- Peptide-drug conjugates:Cytotoxic payloads linked to tumor-targeting peptides offer differentiation in crowded oncology markets.
- India's CDMO expansion:BIS certification alignment with ICH Q7 is positioning Hyderabad and Bangalore clusters for outsourced peptide API production.
- Continuous flow synthesis:Integration of solid-phase reactors with real-time analytical feedback loops promises cycle time compression versus batch operations.
Industry Challenges
- Peptide analytical scientist scarcity:Mass spectrometry and HPLC method development expertise for impurity profiling commands premium compensation in Basel and Boston.
- cGMP facility qualification timelines:EMA and FDA divergent expectations for cleaning validation and hold-time studies extend pre-approval inspection cycles.
- Legacy ERP integration:Electronic batch records and manufacturing execution systems from peptide-specialized vendors require customization for large-pharma interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypeptide Market |
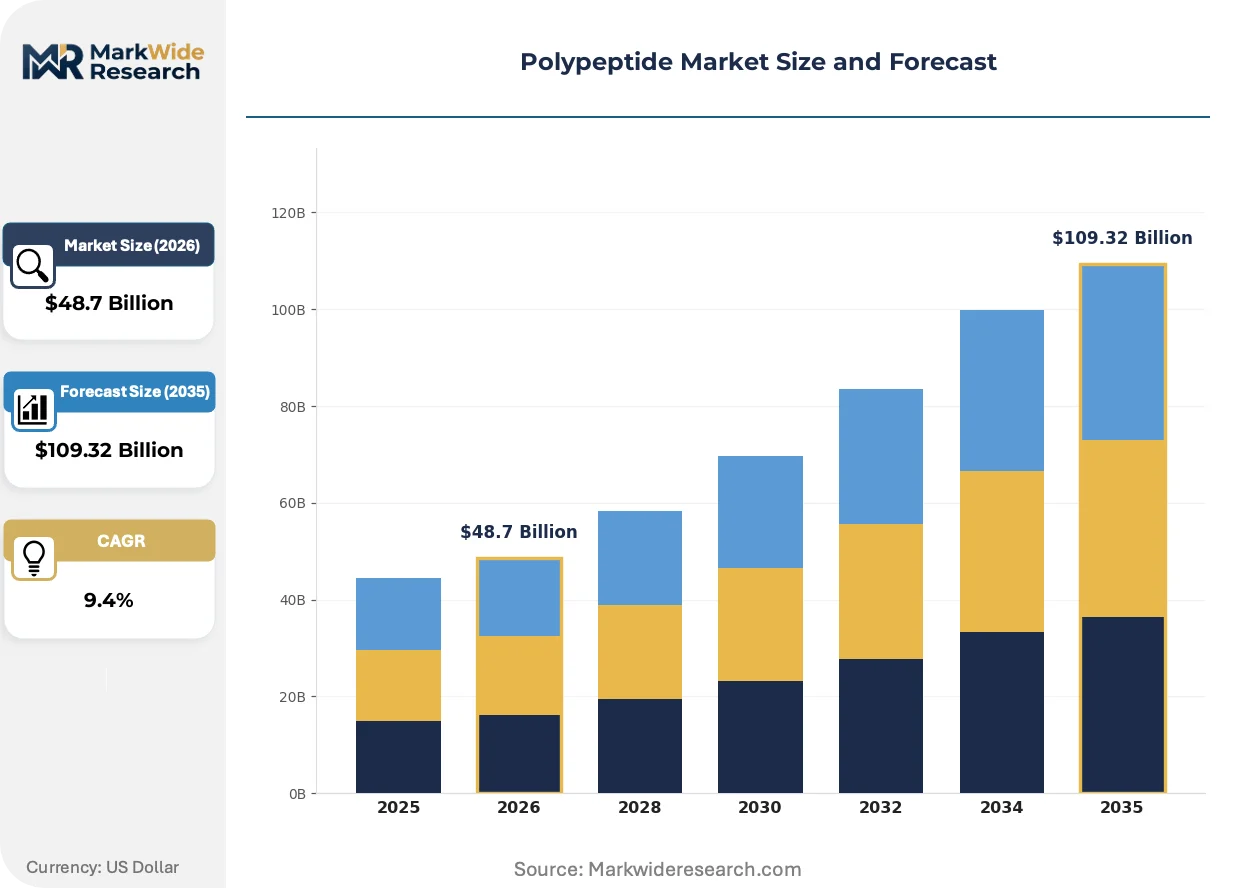
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Peptides, Antimicrobial Peptides, Hormonal Peptides, Signal Peptides Application: Oncology, Cardiovascular Disorders, Diabetes, CNS Disorders End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Manufacturers Delivery Mode: Injectable, Oral, Transdermal, Intranasal |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Bachem Holding AG, PolyPeptide Group, Novo Nordisk A/S, Eli Lilly and Company, Sanofi, Pfizer Inc., GenScript Biotech Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypeptide Market Evolving Landscape
Peptide manufacturing is pivoting from batch-centric operations toward continuous processing and integrated analytical control, with regulatory science struggling to keep pace with technological capability.
Continuous flow solid-phase peptide synthesis is rendering obsolete traditional 10,000-liter resin batch reactors that dominated commercial insulin production for three decades. Novo Nordisk and Eli Lilly are retrofitting Danish and Indianapolis facilities with modular flow systems. This shift is compressing capital intensity per kilogram of API while demanding retraining of process chemists accustomed to offline sampling protocols.
REACH substance registration requirements for novel peptide building blocks are forcing European sponsors to front-load toxicology investment earlier in discovery phases. ECHA's 2023 update to guidance on nanomaterial classification has created uncertainty for peptide-drug conjugates with polymeric linkers. German and French sponsors are responding by relocating early-phase manufacturing to Swissmedic-regulated facilities in Visp and Bubendorf to exploit mutual recognition agreements.
Hospital procurement consortia in the United States are consolidating peptide therapeutic purchasing through 340B program intermediaries, squeezing net realized prices for oncology and metabolic indications. Specialty distributors like AmerisourceBergen and McKesson are capturing inventory risk previously borne by individual hospital pharmacies. This concentration is most visible in diabetes care, where integrated delivery networks in Texas and Florida now negotiate directly with Novo Nordisk for insulin peptide formularies.
Polypeptide Market Segmentation
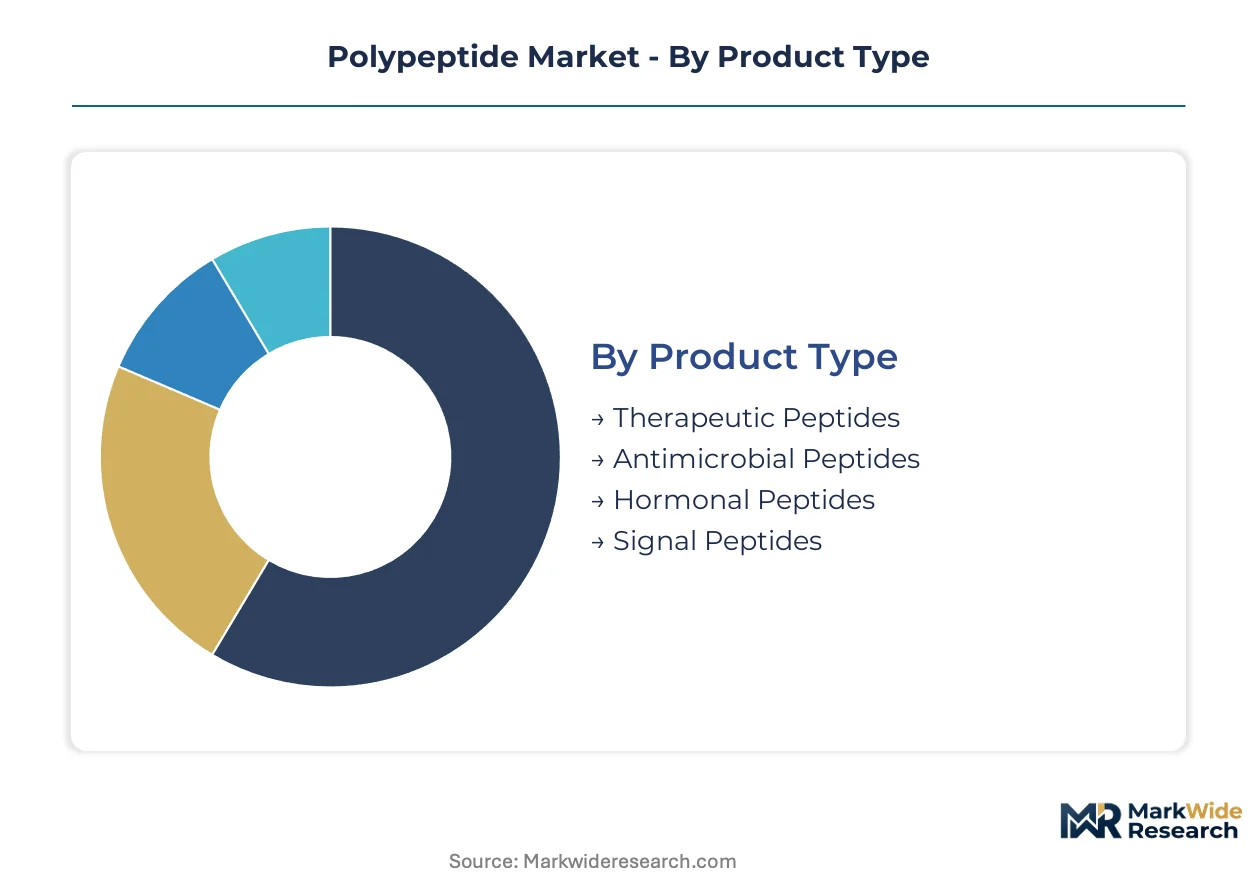
Polypeptide segmentation reveals how therapeutic applications, delivery technologies, and customer procurement patterns fragment manufacturing priorities and regulatory pathways. Distinct purity specifications, stability requirements, and scale economics separate commercial segments.
Product Type:
Therapeutic use-cases span infection control, metabolic regulation, and intercellular signaling, each demanding specialized synthesis routes and impurity thresholds.
- Therapeutic Peptides:Engineered amino acid sequences for disease intervention, typically 10-50 residues, synthesized via solid-phase or recombinant methods. Demand concentrates in diabetes and oncology portfolios from Novo Nordisk and Eli Lilly, where GLP-1 agonists and somatostatin analogs anchor revenue. FDA accelerated approval pathways compress development timelines for these candidates.
- Antimicrobial Peptides:Cationic sequences disrupting bacterial membranes through electrostatic targeting of phospholipid bilayers. Hospital-acquired infection protocols in the United States and Germany are pulling investment toward novel anti-infectives as antibiotic resistance escalates. EMA orphan drug designation accelerates access for resistant-pathogen indications.
- Hormonal Peptides:Endocrine-regulating sequences including insulin, glucagon, and parathyroid hormone analogs. Chinese NMPA biologics reforms streamline IND reviews for metabolic hormone candidates.
- Signal Peptides:Short N-terminal sequences directing protein localization and secretion in cellular machinery. Research tool demand from Boston and Basel academic clusters sustains niche production.
The dominant share belongs to therapeutic peptides, while antimicrobial peptides are closing the gap fastest.
Application:
Clinical indication determines dosing scale, stability requirements, and companion diagnostic integration, creating divergent margin structures across segments.
- Oncology:Cytotoxic peptide-drug conjugates and tumor-targeting sequences require highest purity grades and endotoxin controls. United States integrated delivery networks in Texas and Florida negotiate directly with manufacturers for peptide-drug conjugate formularies.
- Diabetes:Insulin and GLP-1 receptor agonists command the largest production volumes, with Novo Nordisk scaling Danish manufacturing to match chronic therapy demand. Injectable delivery dominates, though oral permeation enhancers are gaining traction.
- Cardiovascular Disorders:Natriuretic peptide analogs and antihypertensive sequences face reimbursement pressure from hospital procurement consortia.
- CNS Disorders:Blood-brain barrier penetration challenges limit peptide uptake, though intranasal delivery advances from Swissmedic-regulated facilities are expanding addressable populations.
Diabetes applications anchor volume, while oncology applications command premium positioning.
End User:
Customer scale and integration depth separate captive manufacturing from outsourced procurement, with qualification timelines varying sharply across buyer types.
- Pharmaceutical Companies:Large sponsors like Eli Lilly and Novo Nordisk maintain in-house peptide synthesis for core franchises while outsourcing specialty sequences. Internal quality systems align with FDA real-time release testing expectations.
- Contract Manufacturers:Bachem and PolyPeptide Group facilities in Villeneuve and Torrance absorb capacity constraints from sponsor pipeline expansion. Swissmedic and FDA dual inspections extend qualification cycles for multi-sourced APIs.
- Biotech Firms:Virtual development models rely entirely on CDMO partnerships, with BIS-certified Hyderabad clusters capturing outsourced peptide API production.
- Research Institutions:Academic demand for custom peptide synthesis supports smaller-scale SPPS operations in Boston and Basel clusters.
Pharmaceutical companies retain the largest procurement scale, though contract manufacturers are expanding capacity fastest.
Delivery Mode:
Route of administration dictates formulation complexity, bioavailability engineering, and patient compliance economics, with innovation concentrated in non-injectable alternatives.
- Injectable:Subcutaneous and intravenous delivery maintains structural dominance for peptides requiring complete bioavailability. Novo Nordisk and Eli Lilly retrofit facilities with continuous flow systems to compress insulin peptide production costs.
- Oral:Permeation enhancers and protease-resistant backbone modifications are unlocking chronic disease markets previously reserved for small molecules. China's NMPA fast-track reviews prioritize oral peptide innovations.
- Transdermal:Microneedle arrays and iontophoresis systems enable non-invasive delivery for smaller peptide sequences.
- Intranasal:Olfactory epithelium targeting offers CNS bypass potential, with Swiss facilities leading formulation development.
Injectable delivery holds the installed base, while oral formulations are advancing most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Switzerland, Denmark, and the United States, where contract synthesis infrastructure and insulin peptide production anchor supply. FDA, EMA, and NMPA regulatory frameworks diverge on purity standards, forcing multi-region qualification strategies.
United States
Integrated delivery networks in Texas and Florida negotiate directly with manufacturers for insulin peptide formularies. FDA accelerated approval pathways compress development timelines for GLP-1 agonists and somatostatin analogs. Indianapolis hosts retrofitting of continuous flow systems for commercial insulin production.
Switzerland
Swissmedic-regulated facilities in Visp and Bubendorf exploit mutual recognition agreements with EMA. REACH substance registration requirements for novel peptide building blocks front-load toxicology investment. Villeneuve anchors large-scale peptide synthesis capacity for European supply.
Denmark
Chronic diabetes therapy demand scales manufacturing footprints to match GLP-1 receptor agonist volume. Danish facilities align quality systems with FDA real-time release testing expectations. Copenhagen clusters process development expertise for recombinant and chemical synthesis integration.
China
NMPA biologics reforms streamline IND review timelines for metabolic hormone candidates. Streamlined regulatory pathways attract foreign sponsors to conduct pivotal trials domestically. Shanghai and Suzhou clusters expand cGMP peptide API capacity for domestic and export markets.
India
BIS certification alignment with ICH Q7 positions Hyderabad and Bangalore for outsourced peptide API production. CDSCO oversight harmonizes with international standards for contract manufacturing qualification. Mumbai anchors commercial distribution infrastructure for antimicrobial peptide supply to hospital procurement networks.
Polypeptide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in synthesis and analytical services. The vendor base stratifies across three tiers: captive pharmaceutical manufacturers, contract development organizations, and research-scale suppliers. Two strategic archetypes dominate—vertically integrated biopharma sponsors and specialized peptide CDMOs. Capacity expansion and regulatory qualification acceleration represent the primary competitive moves across both tiers.
Within the CDMO tier, Bachem Holding AG and PolyPeptide Group exemplify specialized cGMP infrastructure operators. Novo Nordisk A/S anchors the captive manufacturing archetype. These three entities represent divergent scale economics—Bachem and PolyPeptide absorb sponsor pipeline expansion through multi-continental facilities, while Novo Nordisk directs internal capacity toward metabolic franchise verticals. Geographic concentration in Swiss and Danish manufacturing creates interdependence between contract and captive models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Bachem Holding AG |
| PolyPeptide Group |
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| Pfizer Inc. |
| GenScript Biotech Corp. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Swiss cGMP facilities for commercial insulin APIs compresses pricing tier spreads while forcing buyers into long-term offtake commitments to secure allocation. This concentration dynamic simultaneously elevates premium-grade peptide pricing and constrains supply chain reconfiguration options for sponsors lacking backward integration into amino acid feedstocks.
Pricing Analysis
FDA real-time release testing requirements dictate the pricing tier structure across commercial peptide APIs, separating GMP-certified batches from pre-clinical research grades. Three-tier pricing structure across premium, standard, and economy levels reflects endotoxin control stringency and impurity profiling depth. Cost compression in standard-grade segments is intensifying because hospital procurement consortia in Texas and Florida consolidate purchasing through 340B intermediaries. Biotech virtual developers exhibit highest price sensitivity due to milestone-dependent funding, while integrated pharma sponsors absorb premium tiers to protect franchise continuity.
Supply Chain Analysis
Protected amino acid feedstocks draw from Chinese agrochemical bases, Swiss fine-chemical specialists, and Indian fermentation clusters. Solid-phase resin suppliers rest on Japanese polymer manufacturers and German specialty chemical houses. Single-source vulnerability concentrates in Villeneuve and Torrance cGMP facilities for commercial insulin peptide production. Distribution runs through AmerisourceBergen and McKesson specialty channels for hospital-system delivery, with direct manufacturer negotiations penetrating integrated delivery networks in diabetes care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polypeptide market sits in a post-pandemic cyclical recovery driven by reshoring incentives for critical pharmaceutical inputs and FDA backlog clearance accelerating peptide therapeutic approvals.
For Market Incumbents: Insulate core insulin peptide franchises through captive amino acid feedstock agreements and Swissmedic-EMA dual-qualified capacity expansion in Visp or Bubendorf. Recombinant microbial expression systems from microbial fermentation threaten chemical synthesis volumes; backward integration into continuous flow solid-phase reactors preserves cost position against biosimilar encroachment.
For New Entrants and Emerging Players: Establish a beachhead in antimicrobial peptide CMO services for hospital-acquired infection protocols in Germany and the United States. Oral peptide bioavailability formulation partnerships with permeation enhancer specialists offer the most penetrable wedge against injectable incumbents. Pursue BIS certification alignment with ICH Q7 to capture outsourced API production migrating from Swiss concentration.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized cGMP infrastructure operators with FDA and EMA dual inspection readiness. Long-term viability hinges on continuous processing capability and real-time analytical control integration. Watch ECHA nanomaterial classification rulings on peptide-drug conjugates as the inflection signal for toxicology investment front-loading requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Manufacturing Scale-Up | Novo Nordisk and Eli Lilly retrofit Danish and Indianapolis facilities with modular solid-phase reactors compressing cycle times. |
| Dual Regulatory Qualification Pathway | Swissmedic-EMA mutual recognition agreements in Visp and Bubendorf accelerate European market access for peptide APIs. |
| Backward Integration into Amino Acid Supply | Captive feedstock agreements with Chinese and Indian fermentation clusters reduce agrochemical price volatility exposure. |
| Oral Peptide Formulation Partnership | Permeation enhancer collaborations unlock chronic disease markets previously reserved for small-molecule diabetes therapies. |
| Antimicrobial Peptide Pipeline Advancement | EMA orphan drug designation for resistant-pathogen indications pulls investment toward novel anti-infective sequences. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across peptide synthesis, regulatory affairs, and hospital procurement domains. Primary interviews captured drug development executives at metabolic and oncology franchise sponsors, regulatory affairs leads navigating FDA accelerated approval and NMPA biologics reforms, formulary directors at integrated delivery networks, and CMO quality heads managing cGMP qualification timelines. Secondary validation drew from FDA 483 inspection observations, EMA scientific advice letters, ClinicalTrials.gov peptide therapeutic entries, and REACH substance registration databases. Bottom-up volume builds across therapeutic indication and delivery mode segments were triangulated against top-down market sizing from trade flow analysis.
Calibration against historical capacity utilization rates at Villeneuve and Torrance facilities anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, application, end user, and delivery mode, with regional regulatory cluster effects incorporated for FDA, EMA, and NMPA jurisdictions. CAGRs were derived from slope analysis of sponsor pipeline progression rates and manufacturing capacity expansion announcements. Forecast inputs incorporated continuous flow adoption curves and oral peptide bioavailability technology readiness levels.
Stress conditions across amino acid feedstock price volatility, Swiss manufacturing concentration risk, and regulatory harmonization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sponsor pipeline conversion rates and CMO qualification cycle durations. Cross-checking against FDA peptide therapeutic approval velocity and EMA orphan drug designation grants is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Superacids Market
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Neohespiridine Market