
 Calcium Sulphite Market | 2026-2036
Calcium Sulphite Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Sulphite Market Analytics
Water treatment demand from municipal utilities is recalibrating procurement volumes across the calcium sulphite value chain. American Elements leverages its rare earth and advanced materials portfolio to supply high-purity grades for specialized dechlorination systems. Aditya Birla Chemicals anchors South Asian supply through its chlor-alkali and specialty chemicals infrastructure. GFS Chemicals, Inc. differentiates via analytical-grade production protocols serving laboratory and industrial water quality segments.
Calcium sulphite (CaSO₃) is an inorganic salt formed by the reaction of calcium hydroxide with sulfur dioxide, typically containing 65-75% active sulfite content and functioning as a reducing agent and oxygen scavenger in industrial processes. The compound precipitates as a white solid through wet scrubbing methods or neutralization techniques, then finds primary application in removing residual chlorine from treated effluent and in flue gas desulfurization systems. Calcium sulphite powder commands the largest volume share due to its handling efficiency and consistent dissolution rates across water utility installations. Slurry formulations represent the fastest-expanding product category as on-site mixing reduces dust exposure and aligns with bulk delivery contracts. Crystal grades occupy a specialized niche where precise dosing and extended shelf stability justify premium positioning.
EPA discharge standards under the Clean Water Act shape product purity requirements and testing protocols for suppliers serving US water utilities. REACH registration obligations and RoHS substance restrictions in Europe constrain feedstock sourcing and compel documentation of sulfite content in imported materials. China's MEE emission rules and GB standards for industrial wastewater treatment create compliance benchmarks that filter market access for overseas producers. Stakeholders must track regulatory divergence between jurisdictions to align formulation investments with evolving certification demands.
Market Dynamics
EPA discharge mandates under the Clean Water Act are compressing procurement cycles for dechlorination chemicals, forcing water utilities to pre-qualify suppliers against tightening residual chlorine limits and documentation requirements.
Growth Catalysts
- EPA discharge mandates:Tightening residual chlorine limits for municipal effluent are expanding specification-grade calcium sulphite volumes across US water treatment facilities.
- Flue gas desulfurization:Coal-fired power operators in India and China are retrofitting wet scrubbing systems, driving bulk powder procurement for SO₂ capture.
- Slurry delivery systems:On-site mixing infrastructure reduces dust exposure liability and aligns with bulk logistics contracts at large utility scale.
Market Restraints
- Sulfur dioxide feedstock volatility:Pricing swings in SO₂ from petroleum refining and smelting operations compress margin predictability for sulphite manufacturers.
- Substitution by sodium bisulphite:Liquid bisulphite alternatives offer simpler dosing equipment compatibility, displacing calcium sulphite in smaller treatment plants.
- REACH registration burden:European importers face documentation costs and testing protocols that filter out low-volume overseas suppliers.
Strategic Opportunities
- India municipal water expansion:Smart Cities Mission funding is accelerating centralized treatment plant construction in tier-2 urban centers.
- Food-grade certification pathway:GRAS status for sulphite preservatives in wine and processed foods opens pharmaceutical-adjacent purity segments.
- Closed-loop scrubbing:Integrated flue gas and wastewater treatment designs create bundled chemical procurement contracts at industrial parks.
Industry Challenges
- Analytical chemist shortage:Specialized sulfite content verification and EPA compliance testing require certified laboratory personnel that utilities struggle to retain.
- Legacy dosing equipment incompatibility:Slurry pumps and powder feed systems demand capital replacement cycles that delay specification upgrades at aging plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Sulphite Market |
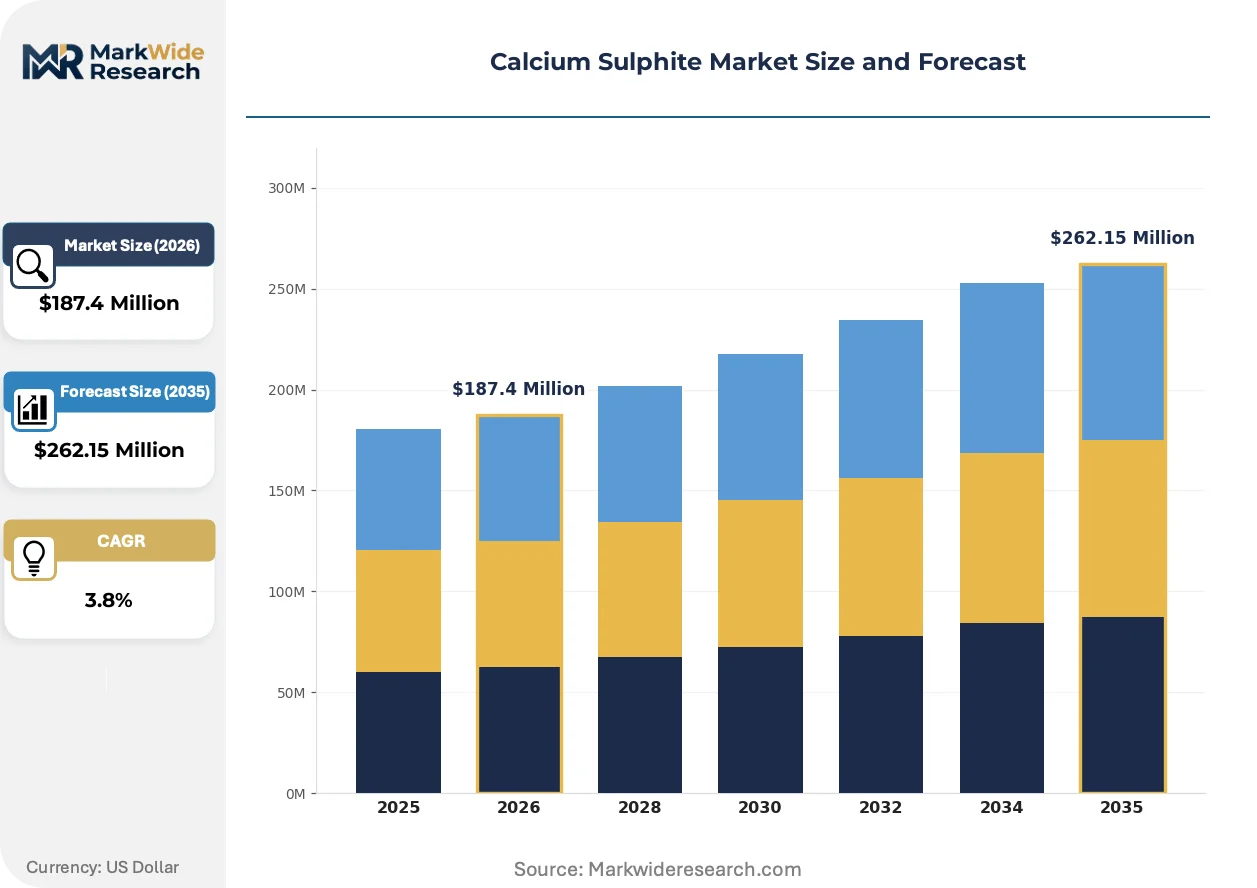
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Sulphite Slurry, Calcium Sulphite Powder, Calcium Sulphite Granules, Calcium Sulphite Crystals Application: Flue Gas Desulfurization, Water Treatment, Paper Manufacturing, Chemical Synthesis End User: Power Generation, Water Utilities, Pulp & Paper, Chemical Industry Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers |
| Companies Covered | Qingdao Sunny Energy-Saving Materials Co., Ltd., Shimmer Chemicals Private Limited, Aditya Birla Chemicals, Pure Tech Inc., NOAH Technologies Corporation, Barium & Chemicals, Inc., American Elements, GFS Chemicals, Inc., Hydrite Chemical Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Sulphite Market Evolving Landscape
Dechlorination chemistry is pivoting from commodity supply toward integrated service models where chemical delivery, dosing equipment, and compliance documentation bundle into multi-year utility contracts.
Encapsulated slow-release calcium sulphite is converging with automated dosing control systems. Municipal operators in Germany and the Netherlands are piloting these formulations to reduce manual handling frequency and stabilize residual chlorine profiles. The technology is converging with predictive maintenance platforms, compressing the traditional spot-buy chemical procurement cycle into subscription-based supply agreements.
China's MEE emission rules are tightening SO₂ discharge limits for coal power and industrial boilers. GB standards for wastewater treatment now mandate sulfite-based dechlorination at designated discharge points. Domestic sulphite producers are responding by expanding crystal-grade capacity to serve precision-dosing requirements at combined heat and power facilities.
Specification-driven procurement is displacing spot-market buying among North American water utilities. Engineering firms and municipal buyers now pre-qualify suppliers against EPA-certified testing protocols before contract award, shifting volume toward integrated chemical-service providers. This pattern is most visible in California and Texas, where regional water quality control boards enforce the strictest residual chlorine monitoring regimes.
Calcium Sulphite Market Segmentation
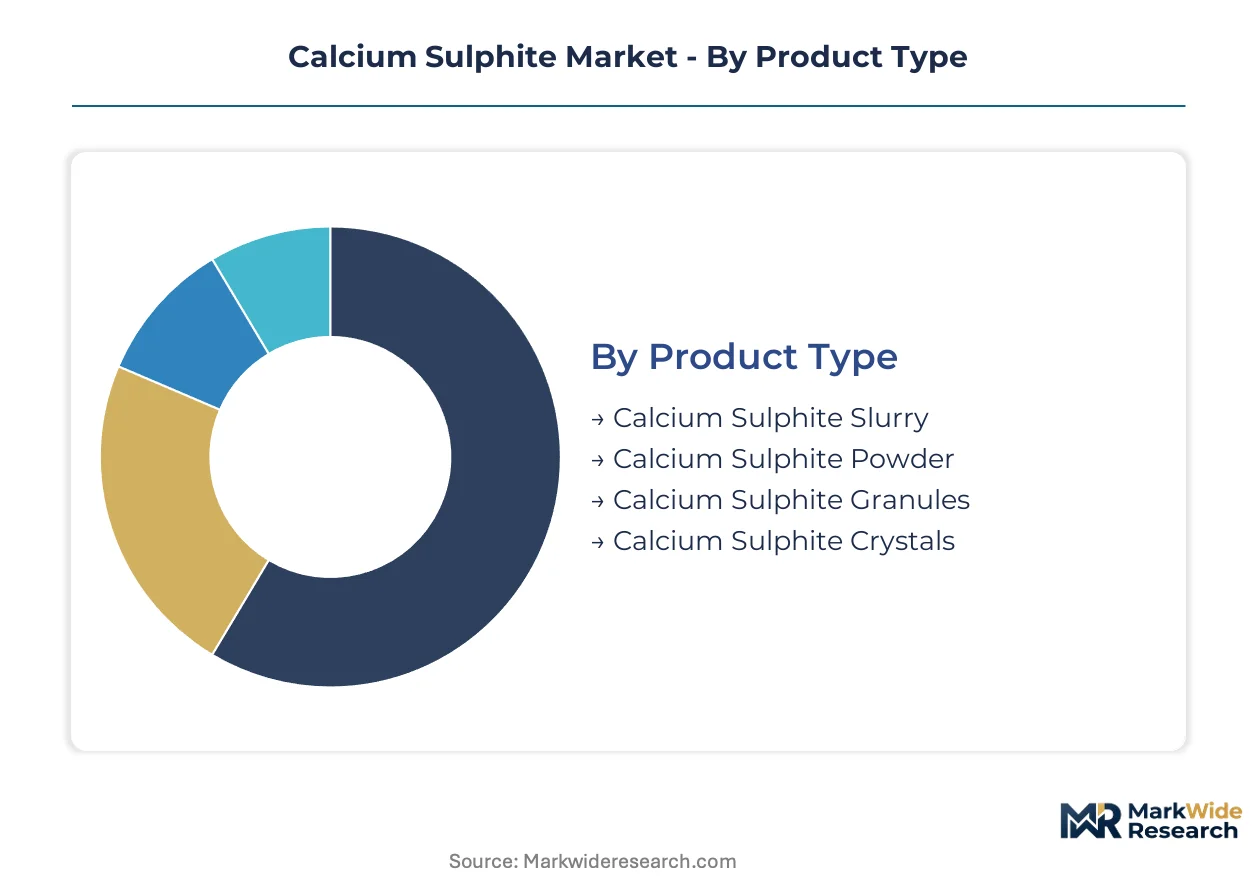
Calcium sulphite procurement patterns diverge sharply across product grades and delivery formats. Water utilities favor powder and slurry forms for dechlorination throughput, while power operators prioritize bulk powder for flue gas scrubbing duty cycles.
Product Type:
Equipment replacement cycles at municipal treatment plants are accelerating specification shifts toward handling-efficient formats that reduce dust exposure liability and align with automated dosing infrastructure.
- Calcium Sulphite Powder:Dry granular form with 65-75% active sulfite content enables precise metering through volumetric feeders. Power generation operators in China and India specify bulk powder for wet scrubbing systems where consistent dissolution rates support SO₂ capture efficiency.
- Calcium Sulphite Slurry:Pre-mixed aqueous suspension eliminates on-site dust generation and integrates with pumped delivery systems. Water utilities across US states are retrofitting slurry-compatible infrastructure under tightening EPA discharge mandates for residual chlorine management.
- Calcium Sulphite Granules:Dense particulate format suits extended-release applications in controlled dosing environments.
- Calcium Sulphite Crystals:High-purity solid form serves laboratory and analytical-grade requirements with precise sulfite content verification.
Calcium sulphite powder sits at the top of the volume ranking, with slurry formulations climbing the fastest as utilities modernize handling infrastructure.
Application:
Cost tier differentiation separates commodity-grade bulk applications from specification-driven segments where purity certification commands premium positioning.
- Water Treatment:Municipal and industrial effluent dechlorination consumes specification-grade sulphite for residual chlorine neutralization. US water utilities under Clean Water Act mandates drive procurement volumes for certified suppliers with EPA-compliant testing protocols.
- Flue Gas Desulfurization:Coal-fired power plants deploy bulk sulphite in wet scrubbing systems for SO₂ emission control. China's MEE emission rules and GB standards are expanding crystal-grade demand at combined heat and power facilities requiring precision dosing.
- Paper Manufacturing:Pulp bleaching and process water treatment utilize sulphite reducing chemistry in integrated mill operations.
- Chemical Synthesis:Reducing agent applications in specialty chemical production require high-purity grades with documented sulfite content.
Water treatment commands the largest application share, while flue gas desulfurization gains share fastest on power sector retrofit cycles.
End User:
Customer type concentration shapes contract structures, with municipal utilities favoring multi-year service agreements and industrial operators prioritizing spot-market flexibility.
- Power Generation:Coal-fired and combined-cycle operators procure bulk powder for flue gas scrubbing under tightening emission limits. India's Smart Cities Mission and centralized treatment expansion are accelerating sulphite procurement for bundled energy-water infrastructure.
- Water Utilities:Municipal treatment facilities specify dechlorination chemicals against EPA-certified protocols with mandatory residual chlorine documentation.
- Pulp & Paper:Integrated mills consume sulphite for process water and bleaching operations with captive chemical sourcing.
- Chemical Industry:Specialty manufacturers require analytical-grade sulphite for precise reducing-agent applications.
Power generation leads end-user volume, with water utilities expanding most quickly on municipal infrastructure investment cycles.
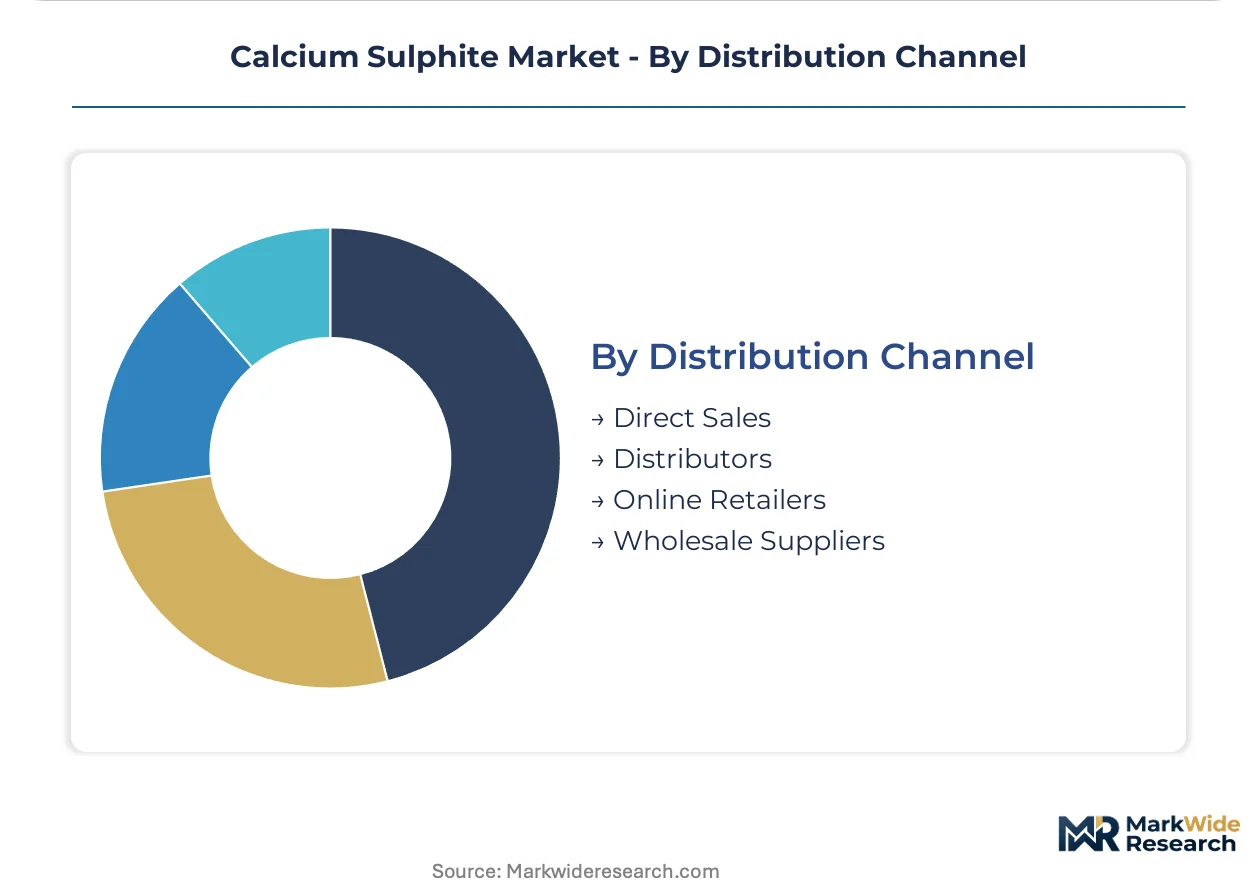
Distribution Channel:
Supply chain configuration determines margin capture, with direct sales preserving value for bulk contracts and distributor networks extending geographic reach.
- Direct Sales:Bulk procurement contracts between sulphite manufacturers and large utility or power operators eliminate intermediary margins. California and Texas regional water quality control boards drive pre-qualified supplier relationships with integrated chemical-service providers.
- Distributors:Regional chemical distributors serve mid-size treatment plants and industrial accounts with inventory pooling and technical support.
- Wholesale Suppliers:Volume aggregators supply commodity-grade sulphite for non-critical applications with price-sensitive procurement.
- Online Retailers:Digital channels serve laboratory, small-scale, and emergency procurement with limited technical service.
Direct sales dominates value capture, with distributor networks expanding fastest into tier-2 utility markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting calcium sulphite production toward jurisdictions with lower compliance burdens and abundant sulfur dioxide feedstock. Manufacturers are relocating wet-scrubbing chemical operations to exploit gaps between EPA-mandated testing protocols and less stringent emerging-market standards.
United States
Water utilities in California and Texas are retrofitting dechlorination infrastructure under tightening EPA discharge mandates. Regional water quality control boards enforce the strictest residual chlorine monitoring regimes, forcing municipal buyers toward pre-qualified suppliers with certified testing protocols. The Southwest and Gulf Coast corridor concentrates specification-grade procurement volumes.
China
Coal-fired power operators are retrofitting flue gas desulfurization systems under MEE emission rules tightening SO₂ discharge limits. GB standards for industrial wastewater treatment now mandate sulfite-based dechlorination at designated discharge points. The Yangtze River Delta and Shandong Peninsula host expanding crystal-grade capacity serving combined heat and power facilities.
India
Smart Cities Mission funding accelerates centralized treatment plant construction in tier-2 urban centers across Maharashtra and Gujarat. Chlor-alkali infrastructure anchors domestic sulphite supply chains serving bundled energy-water infrastructure projects. The Western and Southern industrial corridors drive bulk powder procurement for municipal dechlorination.
Germany
Municipal operators pilot encapsulated slow-release formulations integrated with automated dosing control systems. REACH registration obligations and RoHS substance restrictions constrain feedstock sourcing for imported materials. The Rhine-Ruhr and Bavarian industrial clusters concentrate precision-dosing technology development for predictive maintenance platforms.
Japan
Power utilities deploy advanced wet scrubbing chemistry under METI efficiency mandates for coal-plant emissions. JIS standards govern sulfite content verification protocols for industrial water treatment applications. The Chubu and Kansai regions host specialized reducing-agent production serving precision chemical synthesis.
Calcium Sulphite Market Competitive Landscape
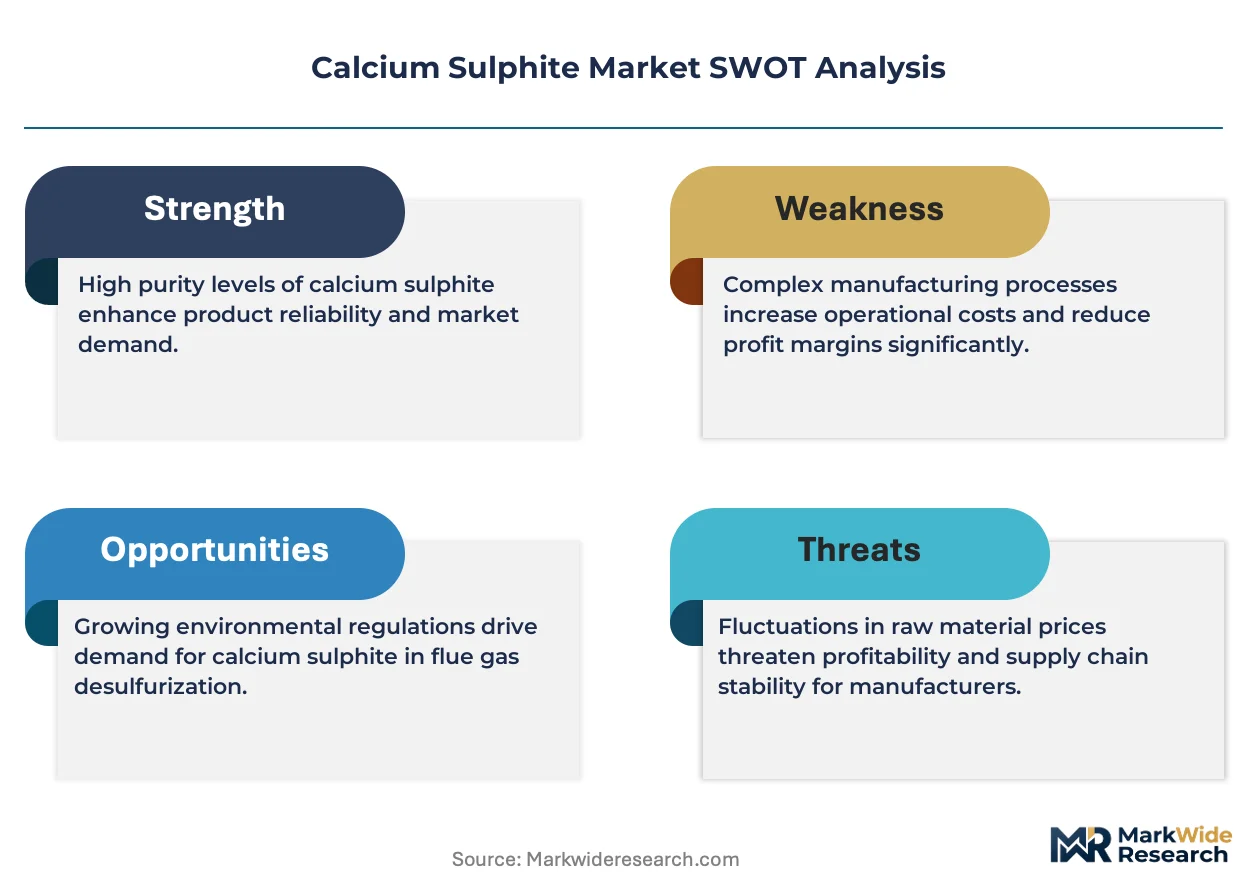
Capacity expansion dominates the current landscape as sulphite manufacturers scale crystal-grade and slurry-format output to match utility procurement cycles. The vendor base stratifies across three tiers: integrated chemical majors with captive sulfur dioxide supply, regional specialists serving municipal water contracts, and laboratory-grade producers targeting analytical verification segments. Strategic archetypes include backward-integrated refiners controlling feedstock costs, formulation innovators bundling dosing equipment with chemical supply, and compliance-focused service providers managing EPA documentation workflows. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players adding slurry-mixing infrastructure and food-grade certification pathways.
Among Asia-Pacific-based suppliers, Qingdao Sunny Energy-Saving Materials Co., Ltd. and Shimmer Chemicals Private Limited occupy positions within the regional specialist tier, while Aditya Birla Chemicals anchors the integrated chemical major archetype through its chlor-alkali infrastructure. American Elements and GFS Chemicals, Inc. exemplify the specification-grade and analytical-grade segments respectively in North American supply chains.
| Leading Market Players |
|---|
| Qingdao Sunny Energy-Saving Materials Co., Ltd. |
| Shimmer Chemicals Private Limited |
| Aditya Birla Chemicals |
| Pure Tech Inc. |
| NOAH Technologies Corporation |
| Barium & Chemicals, Inc. |
| American Elements |
| GFS Chemicals, Inc. |
| Hydrite Chemical Co. |
| Others |
Value Network & Pricing Analysis
Sulfur dioxide spot indices from petroleum refining and smelting operations cascade through calcium sulphite manufacturing into three distinct pricing tiers: specification-grade crystal and slurry formats command premiums from municipal utilities under EPA mandates, while bulk powder trades at commodity benchmarks for power sector procurement.
Pricing Analysis
Distributor margins compress value capture at mid-size water treatment plants, while direct-to-utility contracts preserve pricing power for integrated suppliers. Three-tier pricing structure across specification-grade, standard-grade, and economy-grade separates certified EPA-compliant product from bulk industrial powder. Pricing pressure stems from sulfur dioxide feedstock volatility in petroleum refining byproduct markets. Municipal utilities exhibit lowest price sensitivity due to compliance-driven procurement mandates, while smaller industrial accounts prioritize spot-market flexibility.
Supply Chain Analysis
Single-source vulnerability sits with sulfur dioxide feedstock concentrated in petroleum refining corridors of the United States, China, and India. Calcium sulphite production draws from SO₂ scrubbing operations, lime neutralization capacity, and crystallization infrastructure. Tariff exposure on imported sulphite materials from China constrains European supply options under REACH documentation burdens. Distribution runs through direct sales for bulk utility contracts and regional chemical distributors for mid-size treatment facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium sulphite functions as a regulatory compounder where EPA discharge mandates under the Clean Water Act create sustained demand visibility for specification-grade suppliers.
For Market Incumbents: Anchor compliance documentation workflows as a defensive moat against sodium bisulphite substitution threats. Invest in slurry-mixing infrastructure at utility-adjacent locations to compress logistics costs and lock in multi-year service contracts. Pursue backward integration into captive sulfur dioxide supply from petroleum refining partnerships to insulate margin pressure from feedstock volatility. For New Entrants and Emerging Players: Tier-2 municipal utilities in India under Smart Cities Mission funding represent the most penetrable buyer archetype, with bundled chemical-service contracts displacing spot-market procurement. Target food-grade certification pathways for pharmaceutical-adjacent purity segments where GRAS status opens premium positioning. Lead with automated dosing equipment integration to differentiate from commodity sulphite suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing EPA-certified testing protocols and established utility relationships. Long-term viability centers on suppliers with integrated chemical-service capabilities spanning delivery, dosing infrastructure, and compliance documentation. Monitor MEE emission rule enforcement in China as the signal to watch for crystal-grade capacity expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Slurry Infrastructure Expansion | On-site mixing capacity reduces dust liability and aligns with California and Texas utility procurement cycles. |
| Backward Integration into SO₂ Supply | Captive feedstock from petroleum refining partnerships insulates margin compression from smelting operation volatility. |
| Food-Grade Certification Pathway | GRAS status for sulphite preservatives unlocks pharmaceutical-adjacent purity segments with premium pricing power. |
| Integrated Service Contracting | Bundled chemical delivery, dosing equipment, and EPA documentation compresses procurement cycles into subscription models. |
| Crystal-Grade Capacity Addition | Precision-dosing formats serve combined heat and power facilities under China's tightening GB standards. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with municipal utility procurement managers, power plant chemical engineers, chlor-alkali plant managers, and regional chemical distributors. Secondary validation draws from EPA discharge monitoring reports, MEE emission compliance filings, customs trade data for sulphite imports, and SEC 10-K disclosures from integrated chemical majors. Bottom-up volume estimates triangulate with top-down market sizing across product grades and end-use applications.
Granularity-level modeling disaggregates volume and value by product format, application sector, end-user category, and regional regulatory cluster throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against macro drivers including utility capital expenditure cycles and power sector retrofit timelines. Industry-specific inputs include EPA residual chlorine limit enforcement trajectories and MEE SO₂ discharge compliance schedules.
Underlying measurement precision varies by segment; specification-grade water treatment applications carry tighter precision than commodity flue gas desulfurization volumes due to documented procurement data availability. Forecasts reflect assumptions regarding regulatory enforcement continuity, feedstock price stability, and substitution technology penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Conductive Plastic Compounds Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Eggshell Membrane Derivatives Market