
 Methane Sulfonyl Chloride Market | 2026-2036
Methane Sulfonyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Methane Sulfonyl Chloride Market Analytics
Pharmaceutical synthesis is consolidating as the dominant demand vertical for methane sulfonyl chloride, displacing traditional dye intermediate offtake in several manufacturing clusters. Arkema Group leverages its integrated sulfonyl chloride portfolio to anchor European supply for GMP-grade reagents. Shilpa Chemspec International Pvt. Ltd. competes on cost-optimized batch production for agrochemical intermediates across South Asian markets. Sigma Aldrich, Inc. differentiates through high-purity catalog distribution serving academic and contract research institutions.
Methane sulfonyl chloride is a reactive organosulfur compound with the formula CH3SO2Cl, functioning as a sulfonylating agent in nucleophilic substitution reactions at temperatures typically between 0°C and 25°C. Its primary commercial purpose centers on introducing methylsulfonyl functional groups into pharmaceutical intermediates, crop protection molecules, and chromophore systems. Reagent-grade formulations command premium positioning due to stringent purity thresholds for API synthesis, while agrochemical intermediates represent the fastest-expanding application segment driven by sulfonylurea herbicide development. Liquid form dominates industrial handling protocols, though crystalline variants capture margin pools in specialized electronics etching applications.
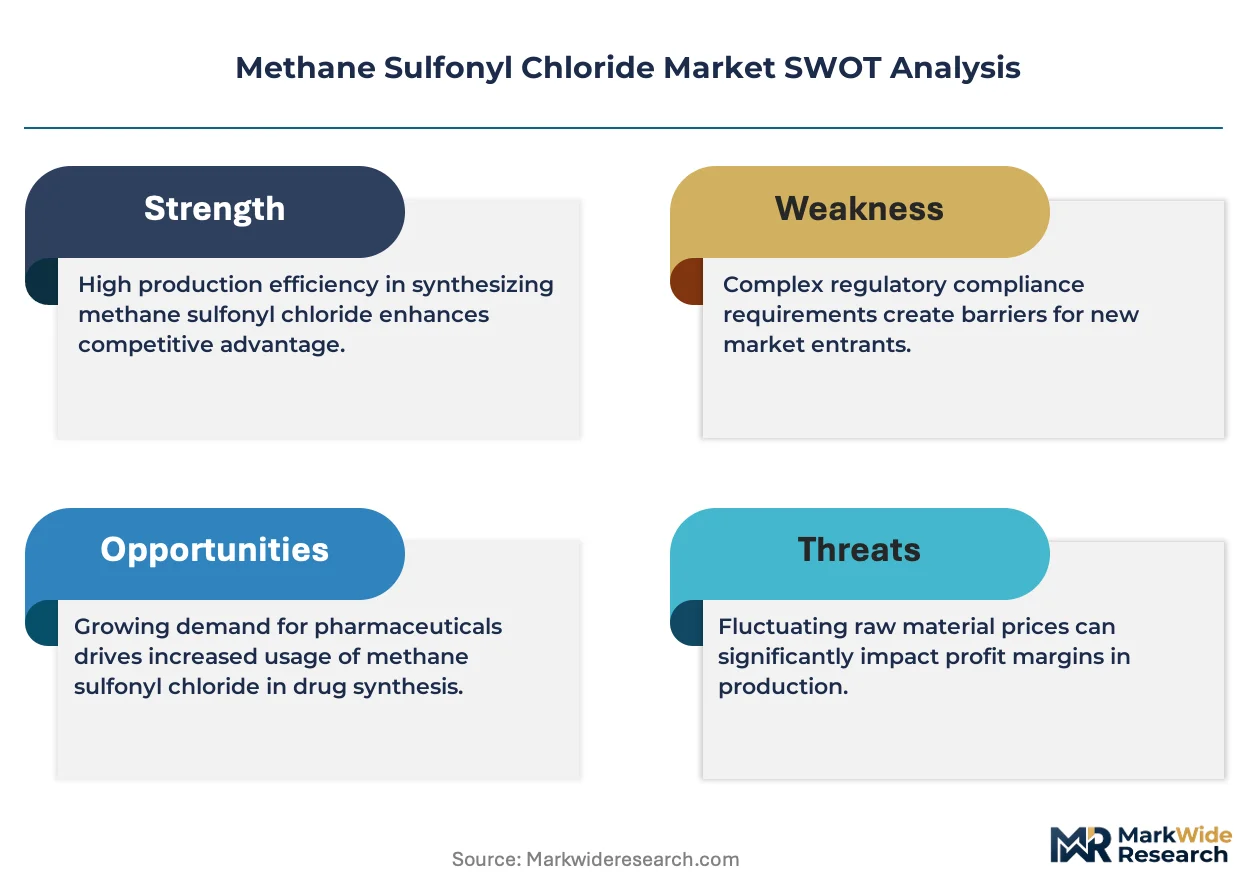
EPA oversight in the United States and REACH registration requirements in Europe impose toxicity documentation and emission thresholds on methane sulfonyl chloride handlers, directly elevating compliance costs for importers without domestic synthesis capability. China's MEE enforces wastewater discharge limits on thionyl chloride derivative production, reshaping plant location decisions for regional suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized synthesis or qualified importer status offers the more durable cost structure.
Market Dynamics
Pharmaceutical manufacturers are consolidating sulfonylation reagent procurement around methane sulfonyl chloride, while REACH and China's MEE tighten emission controls on chlorosulfonyl compound production, forcing capital reallocation toward closed-loop process technologies.
Growth Catalysts
- Sulfonylurea herbicide development:Agrochemical formulators are expanding methylsulfonyl functional group incorporation into crop protection molecules, driving volume offtake from fine chemical producers in China and India.
- REACH registration thresholds:ECHA documentation requirements for chlorosulfonyl compounds are filtering out marginal European suppliers, concentrating qualified supply among integrated manufacturers with captive thionyl chloride production.
- Closed-loop scrubbing systems:German and Swiss chemical clusters are retrofitting HCl capture and SO2 recovery infrastructure, enabling sustained production permits under tightening EU Green Deal emission benchmarks.
Market Restraints
- Thionyl chloride feedstock volatility:Sulfur and chlorine input cost swings compress margin predictability for non-integrated methane sulfonyl chloride producers lacking backward control over chlorinating agent supply.
- Jiangsu and Shandong supply concentration:Fine chemical manufacturing clusters in these Chinese provinces dominate exportable capacity, creating geographic risk exposure for qualified importers dependent on single-origin supply.
- Dimethyl sulfate substitution:Methylation reagents with lower toxicity profiles are displacing methane sulfonyl chloride in select dye intermediate applications where sulfonylation precision is less critical.
Strategic Opportunities
- Indian agrochemical intermediates:CDSCO streamlined approval pathways for crop protection active ingredients are accelerating sulfonylurea herbicide registration, creating import substitution demand for domestic methane sulfonyl chloride synthesis.
- GMP-grade reagent certification:FDA and EMA audit-ready manufacturing protocols enable premium positioning in contract API synthesis, where purity thresholds exceed standard industrial grades.
- Electronics etching applications:Crystalline methane sulfonyl chloride variants are capturing specialized demand in semiconductor wafer processing, linking chemical supply to METI-supported Japanese electronics materials clusters.
Industry Challenges
- Process safety engineering expertise:Chlorosulfonyl compound handling requires specialized occupational safety protocols; talent scarcity in HAZOP assessment and pressure vessel design constrains plant expansion timelines.
- Multi-jurisdiction registration synchronization:REACH, EPA TSCA, and China MEE filing timelines diverge, extending product qualification cycles for suppliers seeking qualified importer status across three regulatory domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methane Sulfonyl Chloride Market |
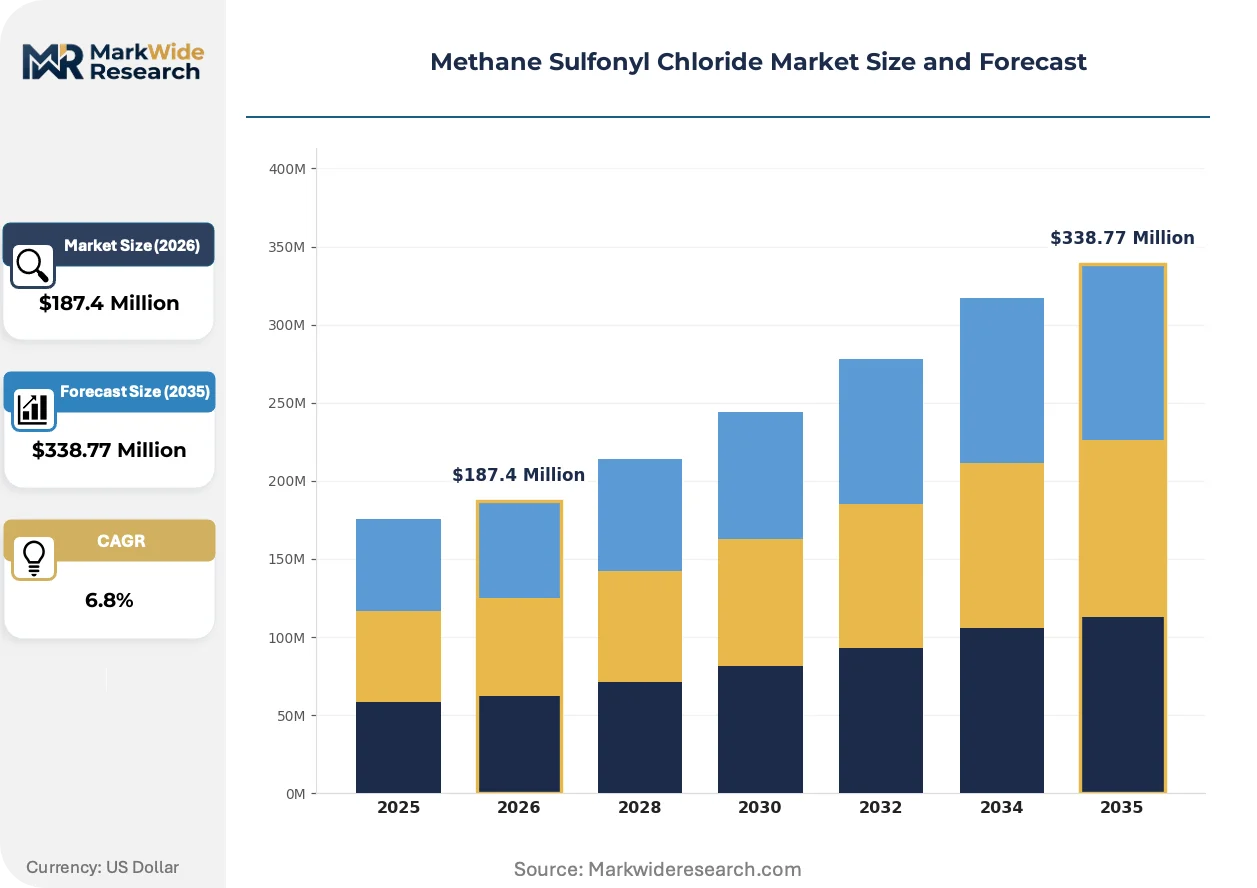
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Intermediates, Solvents, Additives Application: Pharmaceuticals, Agrochemicals, Dyes, Polymers End Use Industry: Chemicals, Agriculture, Automotive, Electronics Form: Liquid, Solid, Powder, Crystalline |
| Companies Covered | Arkema Group, Shilpa Chemspec International Pvt. Ltd., GFS Chemicals, Inc., Varsal, Inc., Sigma Aldrich, Inc., EMCO Dyestuff Pvt. Ltd., Xiaochang Jinji Chemical Co., Ltd., DuPont, Hohhot Guangxin Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methane Sulfonyl Chloride Market Evolving Landscape
Continuous flow reactor technology is displacing batch sulfonylation in pharmaceutical intermediate production, while regulatory data requirements fragment across jurisdictions and buyer procurement models consolidate around qualified supplier lists.
Microreactor-based sulfonylation platforms are absorbing capital investment from European and North American pharmaceutical contract manufacturers seeking precise temperature control during exothermic methane sulfonyl chloride reactions. These systems enable scale-up from gram to ton quantities without batch-to-batch variability, compressing technology transfer timelines for multi-step API synthesis. Arkema Group and similar integrated suppliers are absorbing this equipment shift through pilot facility partnerships with academic research institutions.
REACH authorization list expansion is forcing downstream users to document substitution analysis for chlorosulfonyl derivatives in professional and consumer applications. ECHA's 2024-2025 substance evaluation roadmap elevates scrutiny on persistent organic pollutant formation during methane sulfonyl chloride incineration, compelling waste treatment contractors to install dedicated scrubbing infrastructure. Agrochemical formulators in Germany and France are absorbing compliance costs through reformulated product lines rather than supply chain relocation.
Qualified supplier list consolidation among top-20 pharmaceutical CDMOs is narrowing methane sulfonyl chloride procurement to three to five certified vendors per manufacturing region. This behavioral shift rewards integrated producers with dedicated regulatory affairs functions capable of maintaining multi-jurisdiction dossiers. The concentration is most visible in Switzerland and Singapore, where Lonza and similar contract manufacturers have consolidated reagent purchasing around audit-ready suppliers with ISO 14001-certified environmental management systems.
Methane Sulfonyl Chloride Market Segmentation
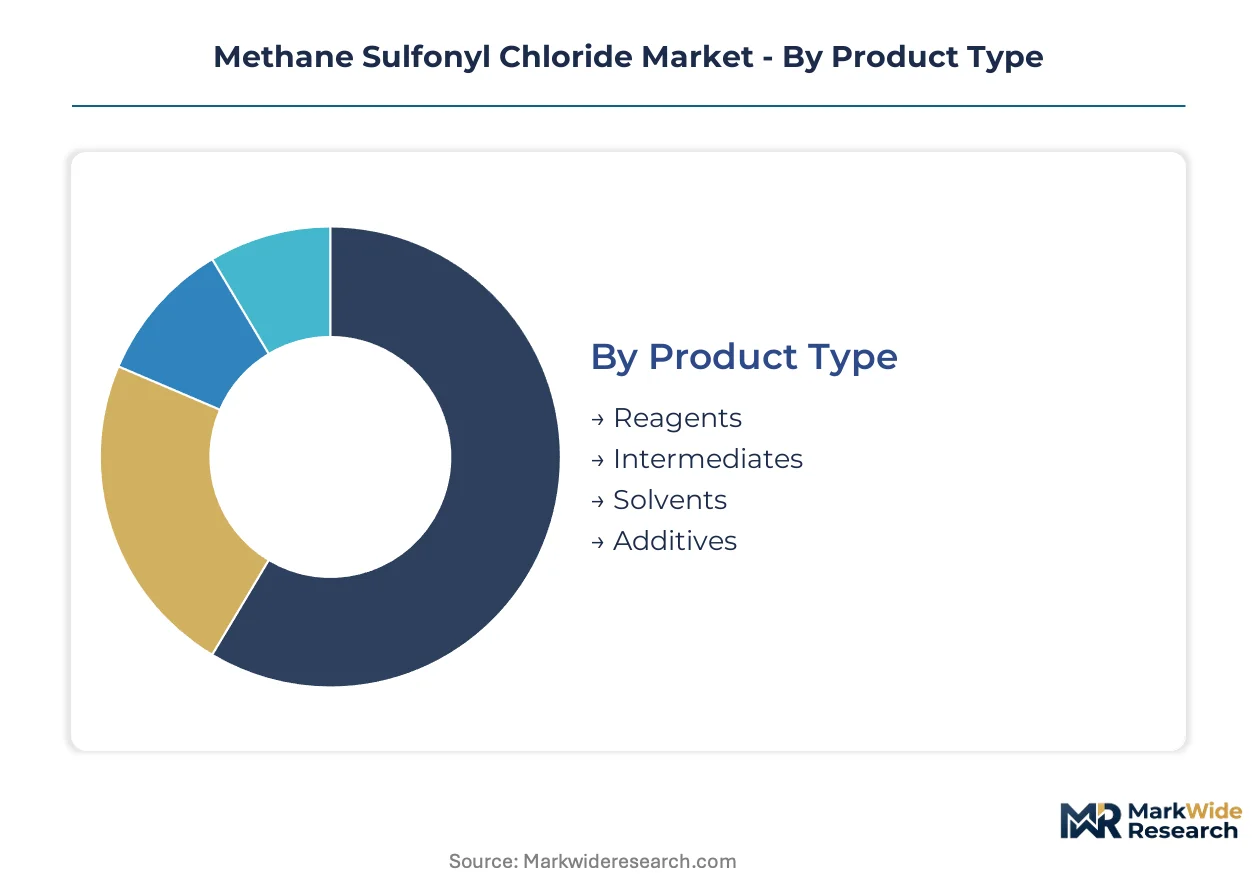
Methane sulfonyl chloride procurement patterns diverge sharply across product grades and application intensities. Pharmaceutical formulators demand GMP-certified reagents with documented impurity profiles, while agrochemical buyers prioritize volume-scale intermediates where specification tolerances relax.
Product Type:
Reagent-grade segments anchor standalone synthesis workflows, while intermediate grades embed deeper into multi-step chemical manufacturing chains.
- Reagents:High-purity formulations meeting pharmacopeial specifications for API sulfonylation reactions. Demand concentrates at Lonza and Thermo Fisher manufacturing sites in Switzerland and Massachusetts, where FDA audit protocols mandate batch-level impurity documentation.
- Intermediates:Technical-grade material feeding captive sulfonylurea herbicide production at Indian agrochemical complexes. Steepest expansion trajectory as CDSCO accelerates crop protection registration timelines.
- Solvents:Diluted formulations for process chemistry applications requiring controlled exotherm management.
- Additives:Minor volume category serving polymer modification and specialty coating formulations.
Volume placements concentrate in Intermediates; the faster expansion belongs to Reagents.
Application:
Cost tier stratification separates precision-driven pharmaceutical synthesis from commodity-scale agrochemical and dye manufacturing.
- Pharmaceuticals:Sulfonylation of nucleophilic centers in kinase inhibitor and antiviral intermediate construction. Gaining share fastest as contract API manufacturers consolidate qualified supplier lists around REACH-registered European sources.
- Agrochemicals:Methylsulfonyl incorporation into sulfonylurea herbicides targeting broadleaf weed control. Volume concentrates at UPL and PI Industries formulation plants in Gujarat and Maharashtra.
- Dyes:Traditional chromophore modification applications facing substitution pressure from dimethyl sulfate in less demanding colorant systems.
- Polymers:Niche sulfonation of engineering thermoplastics for flame-retardant and surface-activity modifications.
Revenue margins peak in Pharmaceuticals; Agrochemicals capture the largest absolute tonnage.
End Use Industry:
Customer maturity separates established chemical manufacturing from emerging electronics materials adoption.
- Chemicals:Integrated fine chemical producers consuming methane sulfonyl chloride for multi-step intermediate synthesis. Arkema's Pierre-Bénite facility exemplifies backward integration into thionyl chloride feedstock.
- Agriculture:Formulation houses sourcing technical-grade material for sulfonylurea active ingredient construction. Expanding most quickly as Indian and Brazilian regulators streamline crop protection registration.
- Automotive:Minimal direct consumption; indirect exposure through polymer additives in underhood applications.
- Electronics:Crystalline-grade demand from Japanese semiconductor etching chemical suppliers supported by METI materials innovation programs.
Chemicals dominates procurement volumes; Electronics represents the steepest growth trajectory.
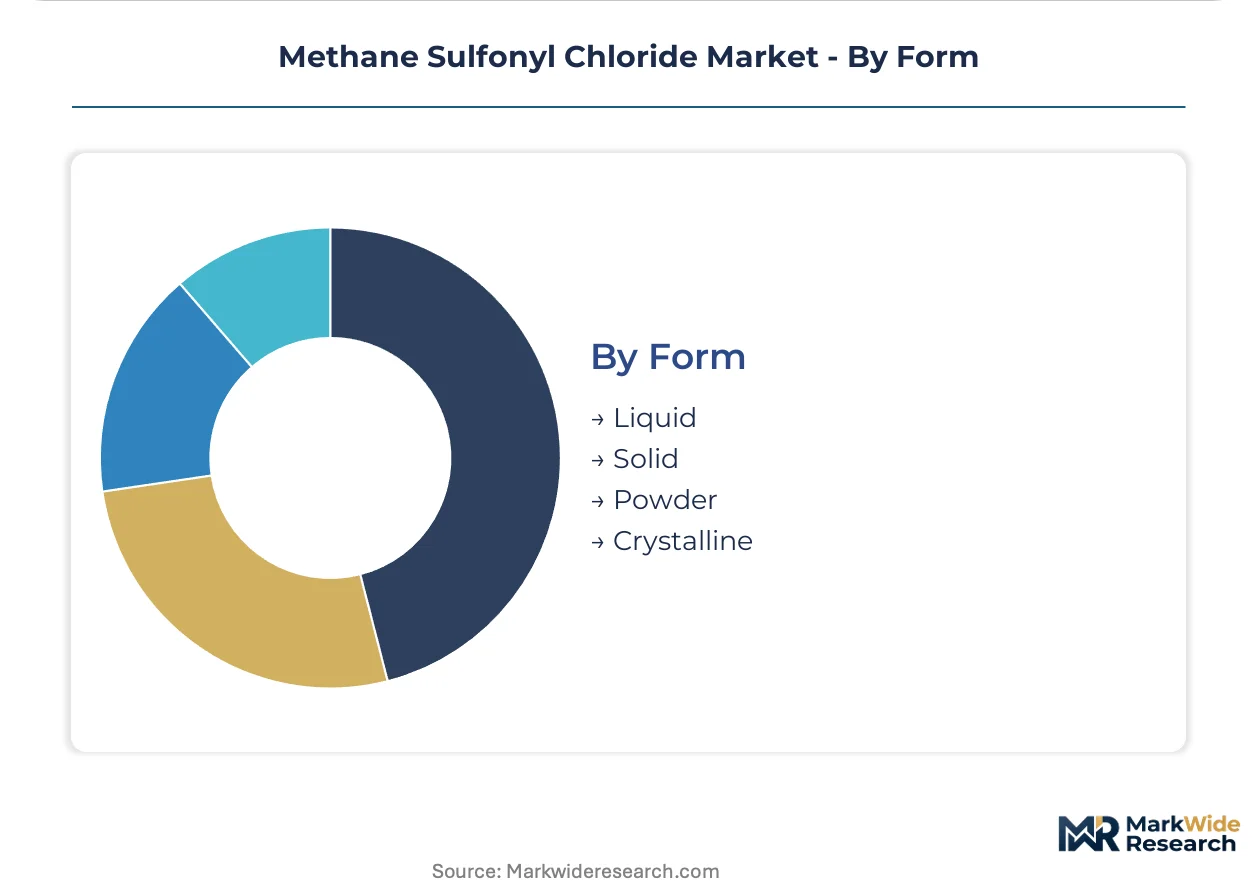
Form:
Supply concentration favors liquid handling infrastructure, while solid and crystalline variants command specialized logistics premiums.
- Liquid:Standard industrial presentation in corrosion-resistant containers for batch sulfonylation reactions. Jiangsu and Shandong production clusters ship primarily in this format to qualified importers.
- Solid:Stabilized formulations for extended shelf-life requirements in remote pharmaceutical manufacturing locations.
- Powder:Limited commercial presence due to hydrolytic instability and occupational exposure concerns.
- Crystalline:Ultra-high-purity solid for electronics etching and analytical standard applications. Premium positioning at Sigma Aldrich distribution centers serving academic and contract research institutions.
Liquid commands the tonnage majority; Crystalline achieves the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Jiangsu and Shandong provinces concentrate methane sulfonyl chloride manufacturing capacity through preferential tax treatment and streamlined environmental permitting. These zones anchor exportable supply for qualified importers serving pharmaceutical and agrochemical formulators worldwide.
China
Domestic fine chemical producers scale captive methane sulfonyl chloride output for sulfonylurea herbicide intermediates and dye manufacturing. MEE wastewater discharge limits on thionyl chloride derivatives reshape plant location decisions toward coastal industrial parks with integrated treatment infrastructure. Xiaochang Jinji Chemical and Hohhot Guangxin Chemical operate production clusters in Hubei and Inner Mongolia respectively.
United States
Pharmaceutical contract manufacturers consolidate procurement around EPA-registered suppliers with documented toxicity profiles for API sulfonylation. FDA audit protocols for GMP-grade reagents elevate compliance costs for importers lacking domestic synthesis capability. Massachusetts and New Jersey host Thermo Fisher distribution nodes serving academic and contract research institutions.
India
Agrochemical formulators at UPL and PI Industries expand methylsulfonyl incorporation into crop protection molecules following CDSCO streamlined registration pathways. DGFT import substitution incentives accelerate domestic methane sulfonyl chloride synthesis proposals in Gujarat and Maharashtra. Shilpa Chemspec International anchors cost-optimized batch production for regional South Asian markets.
Germany
REACH authorization requirements filter marginal suppliers from chlorosulfonyl compound distribution, concentrating qualified supply among integrated manufacturers. EU Green Deal emission benchmarks drive retrofit investment into HCl capture and SO2 recovery infrastructure at Ludwigshafen and Leverkusen chemical clusters. German pharmaceutical CDMOs narrow procurement to audit-ready vendors with ISO 14001 certification.
Switzerland
Lonza and similar contract manufacturers consolidate reagent purchasing around suppliers maintaining multi-jurisdiction regulatory dossiers. Swissmedic GMP enforcement aligns with EMA audit protocols to privilege European-registered methane sulfonyl chloride sources. Basel and Geneva host qualified supplier concentration for kinase inhibitor and antiviral intermediate synthesis.
Methane Sulfonyl Chloride Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates commanding pharmaceutical-grade supply while regional batch producers capture agrochemical intermediate volumes. The vendor base organizes into three archetypes: backward-integrated thionyl chloride producers, catalog distributors with high-purity positioning, and cost-optimized Asian batch specialists. Competitive moves center on regulatory dossier maintenance across REACH, EPA TSCA, and China MEE jurisdictions, alongside continuous flow reactor partnerships with academic institutions.
Within the integrated producer tier, Arkema Group represents European supply anchoring through its Pierre-Bénite facility and captive feedstock control. Among catalog distribution specialists, Sigma Aldrich occupies premium positioning for reagent-grade formulations serving research institutions. At the cost-optimized end, Shilpa Chemspec International exemplifies South Asian batch production scale for agrochemical intermediate offtake. These three patterns illustrate how geographic regulatory alignment and customer maturity stratify competitive positioning.
| Leading Market Players |
|---|
| Arkema Group |
| Shilpa Chemspec International Pvt. Ltd. |
| GFS Chemicals, Inc. |
| Varsal, Inc. |
| Sigma Aldrich, Inc. |
| EMCO Dyestuff Pvt. Ltd. |
| Xiaochang Jinji Chemical Co., Ltd. |
| DuPont |
| Hohhot Guangxin Chemical |
| Others |
Value Network & Pricing Analysis
Backward integration into captive thionyl chloride production anchors both supply security and pricing power for methane sulfonyl chloride manufacturers, as REACH registration costs and MEE wastewater compliance create asymmetric barriers that favor integrated European and Chinese producers over dependent importers. Arkema's Pierre-Bénite facility exemplifies this pattern, where in-house chlorinating agent supply insulates margin structures from sulfur and chlorine feedstock volatility that compresses non-integrated competitors.
Pricing Analysis
Short lead-time premiums distinguish pharmaceutical reagent procurement from agrochemical intermediate contracting, with GMP-grade formulations commanding substantial markups for audit-ready batch documentation. Three-tier pricing structure across reagent, intermediate, and technical grades separates purity-certified pharmaceutical supply from volume-scale agrochemical offtake. Cost compression in standard industrial grades is intensifying because Jiangsu and Shandong producers are expanding captive capacity for sulfonylurea herbicide synthesis. Agrochemical formulators exhibit highest price sensitivity due to commoditized crop protection margins, while contract API manufacturers prioritize qualification status over unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for spent reagent containers and HCl recovery systems shapes supply chain economics, with German and Swiss clusters retrofitting closed-loop scrubbing to sustain production permits. Manufacturing concentrates in China, Germany, and India, with Jiangsu province and Ludwigshafen anchoring exportable capacity. Production draws from thionyl chloride, sulfur, and chlorine feedstocks whose cost swings transmit directly to methane sulfonyl chloride margins. Single-source vulnerability concentrates in Jiangsu and Shandong export nodes, where MEE discharge restrictions could disrupt qualified importer supply. Distribution runs through qualified supplier lists maintained by pharmaceutical CDMOs and agrochemical formulators with documented REACH and EPA registrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH authorization thresholds and ECHA documentation requirements erect durable moats around integrated producers with dedicated regulatory affairs functions, filtering marginal suppliers from chlorosulfonyl compound distribution.
For Market Incumbents: Deepen captive thionyl chloride integration to secure feedstock cost predictability against sulfur and chlorine volatility that erodes non-integrated margins. Expand GMP-grade certification investment to defend positioning as pharmaceutical CDMOs consolidate procurement around audit-ready vendors with ISO 14001 environmental management systems. Arkema's Pierre-Bénite model demonstrates how backward integration insulates against Jiangsu supply concentration risk. For New Entrants and Emerging Players: Continuous flow reactor technology partnerships with academic institutions offer a technology-first wedge into pharmaceutical intermediate supply, bypassing batch production scale requirements that favor established Chinese producers. Target Indian agrochemical formulators at UPL and PI Industries facilities in Gujarat and Maharashtra, where CDSCO streamlined registration is accelerating sulfonylurea herbicide demand ahead of domestic synthesis capacity. Pursue joint development agreements with contract manufacturers seeking precise temperature control for exothermic sulfonylation reactions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking REACH-registered European sulfonyl chloride assets. Long-term viability hinges on regulatory dossier maintenance capabilities across REACH, EPA TSCA, and China MEE jurisdictions, favoring targets with dedicated multi-jurisdiction compliance functions. Monitor ECHA substance evaluation roadmap expansion for early signals of additional chlorosulfonyl derivative scrutiny that could accelerate qualified supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thionyl Chloride | Captive feedstock control at Arkema's Pierre-Bénite facility insulates margin structures from sulfur cost volatility. |
| GMP-Grade Reagent Certification | FDA and EMA audit-ready protocols enable premium positioning in Lonza's kinase inhibitor synthesis supply chain. |
| Continuous Flow Reactor Partnerships | Microreactor platforms with academic institutions compress technology transfer timelines for pharmaceutical CDMOs. |
| Closed-Loop Scrubbing Infrastructure | HCl capture and SO2 recovery systems at Ludwigshafen sustain production permits under EU Green Deal benchmarks. |
| Indian Domestic Synthesis Expansion | DGFT import substitution incentives accelerate Gujarat and Maharashtra proposals for agrochemical intermediate supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning plant managers at thionyl chloride production facilities, procurement leads at pharmaceutical CDMOs, regulatory affairs directors managing REACH dossiers, and distribution channel partners handling qualified supplier logistics. Cefic chemical industry reports, ECHA registration databases, SEC 10-K filings from integrated chemical producers, and China customs export records provided validation layers. Bottom-up capacity assessments across Jiangsu and Shandong production clusters reconciled with top-down demand modeling from pharmaceutical and agrochemical formulation sectors.
Data-stream reconciliation across volume shipments, import declarations, and end-use consumption patterns enabled cross-validation of production and demand estimates throughout the forecast period. Segmentation modeling incorporated grade tier distinctions between reagent and intermediate classifications, end-use industry splits across pharmaceuticals, agrochemicals, and electronics materials, packaging format differences between liquid and crystalline presentations, and regional production hub concentration in Chinese coastal industrial parks. CAGRs were derived from trend extrapolation of sulfonylurea herbicide registration timelines and pharmaceutical outsourcing intensity indices.
Several conditions sit outside the modeled scope, including potential substitution by dimethyl sulfate in dye intermediate applications and unannounced MEE wastewater discharge restriction expansions. Forecasts reflect assumptions regarding sustained REACH registration validity and continued CDSCO regulatory streamlining. Practitioners should monitor ECHA authorization list additions and thionyl chloride feedstock cost movements for early signals of margin compression or supply qualification disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Furniture Foam Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market