
 Propoxylates Market | 2026-2036
Propoxylates Market Size, Share, and Industry Trends Forecast 2026-2036
Propoxylates Market Analytics
Buyer concentration across the personal care and coatings sectors is rebalancing as mid-sized formulators diversify supply sources away from dominant multinationals. BASF SE leverages its integrated propylene oxide feedstock position to sustain cost advantages across European production hubs. Dow Chemical Company anchors North American supply through its Gulf Coast manufacturing complex, while Huntsman Corporation differentiates via specialty alkoxylate grades for industrial surfactant applications.
Propoxylates are alkoxylated derivatives produced by adding propylene oxide to alcohol, polyol, or amine initiators, yielding products with tunable hydrophilic-lipophilic balance values typically ranging from 3 to 30; these intermediates function primarily as surfactant precursors, solvents, and emulsifiers across formulated consumer and industrial products. Propoxylated glycerol and propoxylated sorbitol segments command premium positioning in pharmaceutical and personal care applications where low residual oxide specifications determine market access. The emulsifier and surfactant applications absorb the majority of volume flows, with solvent-grade propylene carbonate carving out a distinct margin pool in coatings and electronics cleaning formulations.
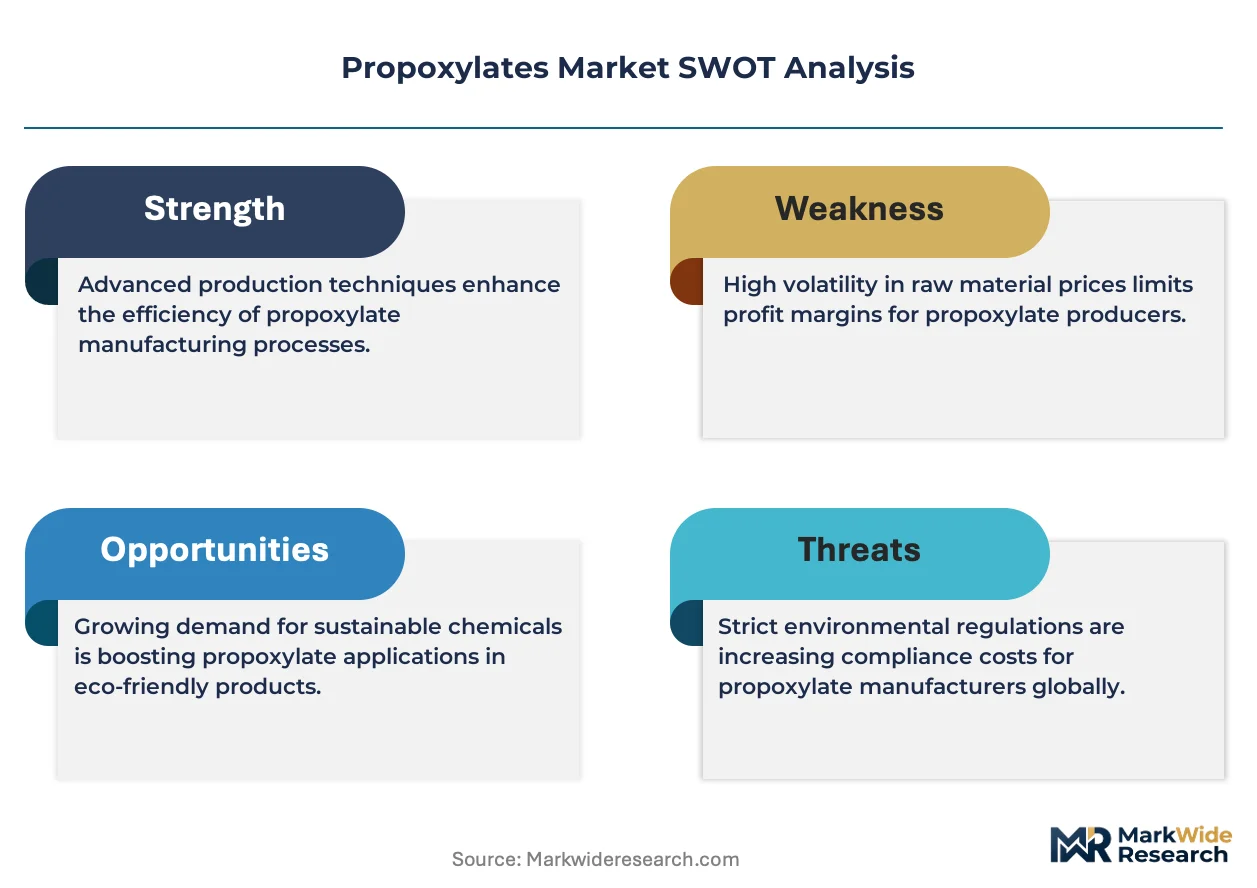
EPA chemical safety evaluations under TSCA and REACH registration requirements in Europe constrain market entry for producers lacking comprehensive toxicological dossiers and analytical certification capabilities. FDA oversight of indirect food contact applications and BIS quality standards in India further segment product grades by purity tier and end-use eligibility. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these regulations are redirecting formulator R&D budgets toward propoxylate-based alternatives in multiple end-use categories.
Market Dynamics
Propoxylate supply chains face structural recalibration as REACH and TSCA compliance costs bifurcate the producer base between dossier-capable multinationals and regional specialists lacking toxicological certification infrastructure.
Growth Catalysts
- REACH purity mandates:European formulators now specify sub-5 ppm residual oxide thresholds for pharmaceutical-grade propoxylates, creating tiered demand for certified intermediates.
- PFAS substitution waves:Fluorinated surfactant restrictions under EPA action plans and EU F-Gas Regulation are redirecting coatings R&D budgets toward propoxylate-based alternatives.
- China domestic capacity scaling:Jiangsu and Shandong province producers are expanding propoxylated polyol output to serve regional detergent and personal care supply chains.
Market Restraints
- Propylene oxide feedstock volatility:PO price swings tied to refinery propylene co-product economics compress margin predictability for non-integrated alkoxylators.
- Gulf Coast supply concentration:North American propoxylate output clusters along Texas-Louisiana chemical corridors, exposing buyers to hurricane disruption and logistics bottlenecks.
- Alkoxylate process limitations:Narrow molecular weight distribution requirements for pharmaceutical emulsifiers constrain batch reactor throughput and yield rates.
Strategic Opportunities
- India BIS quality tier penetration:Unmet demand for ISI-certified propoxylates in Mumbai and Ahmedabad surfactant clusters offers first-mover positioning for compliant importers.
- Bio-based propylene oxide pathways:Glycerol-to-PO and hydrogen peroxide oxidation technologies are converging to enable mass-balance certified propoxylate grades.
- Direct-to-formulator digital channels:Specialty chemical marketplaces are bypassing traditional distributor markups for mid-volume personal care compounders.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography and mass spec expertise for residual oxide quantification is concentrated among aging specialist workforces in Germany and Switzerland.
- Multi-jurisdiction dossier maintenance:Simultaneous REACH, TSCA, and NMPA registration timelines strain regulatory affairs bandwidth for mid-cap producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propoxylates Market |
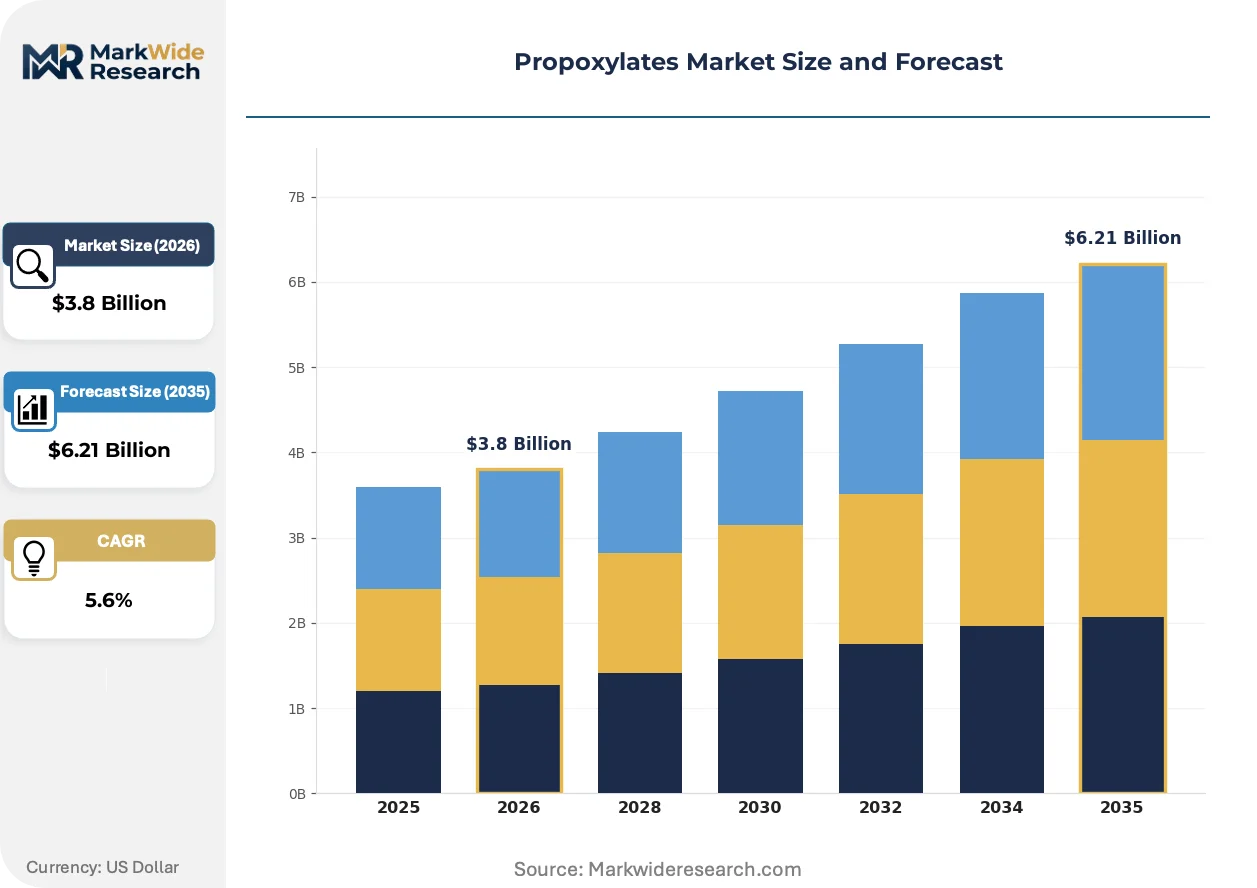
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Propylene Glycol, Propylene Carbonate, Propoxylated Glycerol, Propoxylated Sorbitol End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Coatings Application: Emulsifier, Solvent, Surfactant, Stabilizer Form: Liquid, Powder, Granule, Paste |
| Companies Covered | BASF SE, Dow Chemical Company, Huntsman Corporation, INEOS Group, Lubrizol, Arkema, Carbosynth, LEVACO Chemicals, LEUNA-Tenside GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propoxylates Market Evolving Landscape
Continuous flow alkoxylation reactor technology is compressing batch cycle times and enabling real-time molecular weight control, reshaping capital deployment patterns across surfactant intermediate manufacturing.
Continuous processing architecture is automating temperature and pressure modulation in propoxylation reactions. Personal care formulators in Germany and France are adopting these intermediates for mild surfactant systems requiring tight polydispersity indices. The technology is automating quality variance reduction that previously required post-reaction distillation.
REACH registration dossier requirements for alkoxylated substances are tightening toxicological data thresholds. European producers must now submit extended one-generation reproductive toxicity studies for high-volume propoxylates. Specialty pharmaceutical-grade suppliers are responding by segregating dedicated reactor trains to prevent cross-contamination.
Personal care brands are consolidating surfactant procurement around full-formulation service contracts rather than discrete intermediate purchasing. This disintermediation is compressing standalone propoxylate distributor margins in the United States. Contract manufacturers with in-house alkoxylation capabilities are capturing volume previously flowing through merchant chemical distribution.
Propoxylates Market Segmentation
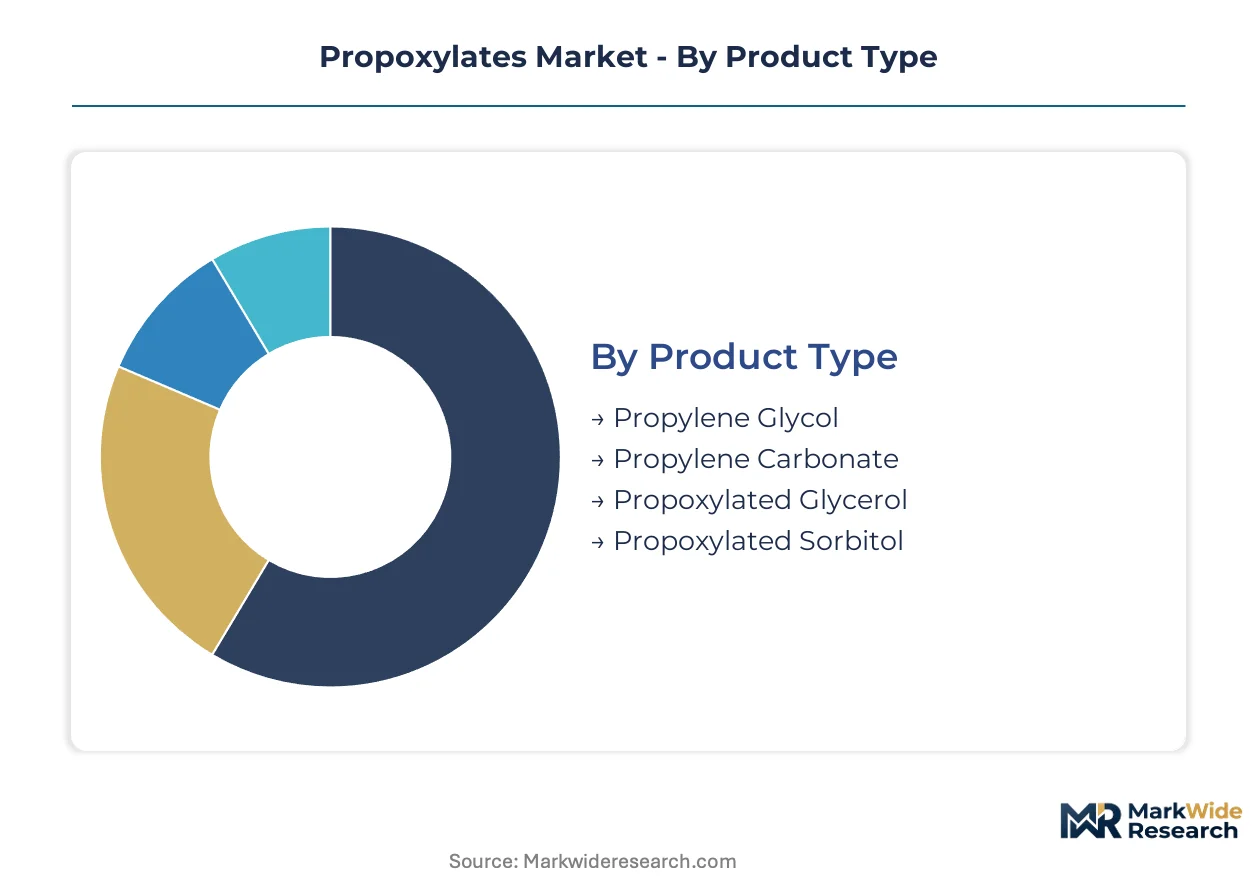
Propoxylate value chains fragment across four intersecting dimensions, each imposing distinct purity specifications and regulatory compliance burdens. Product type determines feedstock integration economics, while end-use industry governs certification tier requirements and margin capture potential.
Product Type:
Specialty alkoxylate capacity concentrates among producers with dedicated reactor trains and analytical certification infrastructure.
- Propylene Glycol:The workhorse intermediate serves automotive antifreeze, polyester resin, and pharmaceutical solvent applications. Demand clusters in China and the US Gulf Coast, where integrated PO producers leverage captive feedstock economics against merchant market volatility.
- Propylene Carbonate:This cyclic carbonate delivers high dielectric constant and low toxicity for lithium battery electrolytes and industrial degreasing. Battery-grade specifications from NMPA and EMA are tightening residual glycol thresholds, favoring producers with continuous flow reactor technology.
- Propoxylated Glycerol:Low-irritation surfactant precursor for mild personal care formulations.
- Propoxylated Sorbitol:Sugar-derived backbone for pharmaceutical emulsifiers and food-grade dispersants.
Today's leader: Propylene Glycol. Tomorrow's challenger: Propylene Carbonate.
End Use Industry:
Formulator procurement patterns diverge sharply between price-sensitive commodity buyers and specification-driven premium segments.
- Personal Care:Mild surfactant systems for facial cleansers and baby shampoos demand sub-5 ppm residual oxide certifications under REACH. German and French formulators are consolidating suppliers around full-formulation service contracts, disintermediating standalone propoxylate distributors.
- Pharmaceuticals:Parenteral emulsions and oral drug delivery systems require extended one-generation reproductive toxicity dossiers under EMA guidelines. Dedicated reactor segregation and dedicated analytical chemists concentrate supply among Swissmedic-certified specialists in Basel and Munich.
- Food & Beverage:FDA indirect food contact clearances and FSSAI quality tiers segment propoxylated sorbitol grades for flavor encapsulation and clouding agents.
- Coatings:PFAS substitution waves under EPA action plans and EU F-Gas Regulation are redirecting R&D budgets toward propoxylate-based flow and leveling agents.
Personal Care commands current margin premiums; Pharmaceuticals is climbing the fastest as regulatory barriers steepen.
Application:
Volume flows concentrate where alkoxylate functionality replaces restricted chemistries or enables water-based formulation shifts.
- Surfactant:Anionic and nonionic surface-active agents derived from propoxylated alcohols dominate detergent and personal care formulations. China domestic producers in Jiangsu province are scaling capacity to serve regional supply chains, compressing import dependence.
- Emulsifier:Oil-in-water stabilizers for pharmaceuticals and cosmetics require narrow polydispersity indices achievable through continuous flow reactor technology.
- Solvent:Propylene carbonate serves electronics cleaning and paint stripping applications with favorable toxicity profiles against chlorinated alternatives.
- Stabilizer:Polyurethane foam and polymer processing aids leverage propoxylate backbone compatibility.
Surfactant applications anchor current volume; Emulsifier specifications are gaining share fastest as pharmaceutical-grade demand intensifies.
Form:
Physical state determines logistics economics and formulation integration pathways across customer scale tiers.
- Liquid:Bulk tanker and drum deliveries dominate merchant chemical distribution, favored by large-scale coatings and detergent compounders with automated dosing systems.
- Powder:Spray-dried grades enable dry blend personal care and food applications with extended shelf stability.
- Granule:Low-dust handling characteristics serve pharmaceutical tableting and controlled-release formulations.
- Paste:High-viscosity concentrates for specialized industrial lubricant and textile processing applications.
Liquid form retains volume leadership; Powder grades are expanding most quickly as dry formulation trends accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist chemists in Basel and Ludwigshafen anchor European analytical certification capacity, while Jiangsu province process engineers drive Asian production scaling.
United States
Coatings formulators in Texas and Louisiana are absorbing propoxylate volumes displaced by fluorinated surfactant restrictions. EPA TSCA Section 5 premanufacture notifications now require extended toxicological data for alkoxylated imports. The Gulf Coast petrochemical corridor concentrates propylene oxide feedstock integration and alkoxylation reactor capacity.
Germany
Personal care brands in Düsseldorf and Hamburg are consolidating procurement around full-formulation service contracts. REACH Annex VIII dossier requirements now mandate reproductive toxicity studies for high-volume propoxylates. BASF's Ludwigshafen complex maintains integrated propylene oxide-to-alkoxylate production trains.
China
Domestic surfactant producers in Jiangsu and Shandong provinces are expanding propoxylated polyol output for regional detergent supply chains. NMPA pharmaceutical-grade registration timelines are lengthening for imported alkoxylates. Yangtze River Delta chemical parks are capturing volume previously sourced from European merchants.
India
Mumbai and Ahmedabad surfactant clusters are generating unmet demand for ISI-certified propoxylate intermediates. BIS quality tier specifications now segment pharmaceutical-grade from industrial-grade alkoxylates. Gujarat's specialty chemical corridor is attracting capacity investments from dossier-capable multinationals.
Switzerland
Swissmedic-certified specialists in Basel concentrate supply for parenteral emulsion applications. Dedicated reactor segregation requirements under EMA guidelines favor producers with segregated production infrastructure. The country's analytical chemist workforce dominates residual oxide quantification expertise for European pharmaceutical-grade certification.
Propoxylates Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification requirements. The producer base bifurcates between REACH-dossier multinationals and regional merchants lacking toxicological infrastructure. Three archetypes dominate: integrated petrochemical majors with captive propylene oxide supply, specialty alkoxylators with dedicated pharmaceutical-grade reactor trains, and regional distributors serving price-sensitive industrial formulations. Capacity expansion and M&A consolidation represent the dominant competitive vectors as compliance costs escalate.
Within the integrated major tier, BASF SE and Dow Chemical Company exemplify archetypes of feedstock-integrated production. Among specialty alkoxylators, Huntsman Corporation occupies a position emphasizing differentiated industrial surfactant grades. These three entities represent the spectrum from commodity-scale propylene glycol output to narrow-specification pharmaceutical emulsifier production.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Huntsman Corporation |
| INEOS Group |
| Lubrizol |
| Arkema |
| Carbosynth |
| LEVACO Chemicals |
| LEUNA-Tenside GmbH |
| Others |
Value Network & Pricing Analysis
REACH purity mandates gate qualified supply and premium-tier pricing access, bifurcating the producer base between dossier-capable multinationals and uncertified regional merchants. Formulators in Germany and France now pay substantial premiums for sub-5 ppm residual oxide certifications, while price-sensitive industrial buyers in China and India source uncertified grades through fragmented distributor networks.
Pricing Analysis
Bundled full-formulation service contracts versus unbundled intermediate sales split the pricing landscape. Three-tier pricing structure across pharmaceutical-grade, personal care-grade, and industrial-grade levels anchors differentiation, with certification tier and volume scale as primary price drivers. Pricing pressure stems from China domestic capacity scaling compressing import parity for standard grades. Industrial surfactant compounders exhibit highest price sensitivity, while Swissmedic-certified pharmaceutical buyers accept substantial premiums for dedicated reactor segregation.
Supply Chain Analysis
Single-source vulnerability sits with propylene oxide feedstock concentration along the US Gulf Coast and in China's Yangtze River Delta chemical parks. Production draws from Germany, the United States, and China as primary supply nodes, with propylene oxide, alcohol initiators, and specialized catalysts as critical inputs. Hurricane exposure across Texas-Louisiana corridors and NMPA registration delays for imports constitute structural supply risks. Distribution runs through integrated majors serving large formulators directly, with specialty distributors handling mid-volume personal care compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA PFAS action plans and EU F-Gas Regulation redirecting coatings R&D budgets toward propoxylate-based alternatives and accelerating demand displacement.
For Market Incumbents: Acquire dedicated reactor train assets and analytical certification infrastructure to defend pharmaceutical-grade positioning against emerging pure-play specialists. BASF and Dow should extend backward integration into bio-based propylene oxide pathways to neutralize feedstock volatility threats from merchant PO markets. Huntsman's specialty alkoxylator model demonstrates margin defense through narrow-specification industrial grades requiring continuous flow reactor technology. For New Entrants and Emerging Players: Enter via ISI-certified propoxylate supply to Mumbai and Ahmedabad surfactant clusters, where unmet demand exceeds domestic BIS-compliant capacity. India's pharmaceutical-grade segment offers penetrable white space given lengthening NMPA import timelines and concentrated Swiss-German supply. Direct-to-formulator digital channels bypass traditional distributor markups for mid-volume personal care compounders seeking full-formulation partnerships. For Investors and Strategic Acquirers: Roll-up economics work for REACH-dossier regional specialists because compliance cost escalation is driving consolidation toward scale-efficient regulatory affairs bandwidth. Five-to-ten year viability hinges on mass-balance certification capabilities for bio-based PO pathways. Watch for inflection when continuous flow reactor technology patents expire and enable second-mover capacity additions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Propylene Oxide | Glycerol-to-PO pathways enable mass-balance certified grades for REACH-compliant formulators in Germany. |
| Continuous Flow Reactor Technology Deployment | Real-time molecular weight control compresses batch cycle times for narrow polydispersity pharmaceutical emulsifiers. |
| REACH Dossier Acquisition of Regional Specialists | Consolidating toxicological certification infrastructure defends margin tiers against pure-play emerging competitors. |
| Direct-to-Formulator Digital Channel Establishment | Specialty chemical marketplaces bypass distributor markups for mid-volume personal care compounders in France. |
| Swissmedic-Certified Reactor Train Segregation | Dedicated production infrastructure captures parenteral emulsion premiums under EMA reproductive toxicity guidelines. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Plant managers at integrated PO-to-alkoxylate facilities, procurement leads at personal care formulators, distribution channel partners, and technical R&D directors contributed primary perspectives. Secondary sources included customs and trade data, Cefic sector reports, SEC 10-K filings, and REACH registration dossiers. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Granularity was maintained at product type, end-use industry, application, and regional production hub levels across the projection horizon. CAGRs were derived from segment-level growth rate synthesis and cross-referenced against macroeconomic indicators. Feedstock integration economics, regulatory compliance cost trajectories, and substitution elasticity for PFAS-restricted chemistries informed forecast inputs.
Inputs from regulatory filings and trade databases were available through the study window; gaps in real-time capacity utilization data introduce uncertainty bands around near-term supply projections. Forecasts reflect documented assumptions regarding REACH implementation timelines and China domestic scaling trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Toner Resins Market
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Sheet Moulding Compound (SMC) Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market