
 Global Powder Injection Molding (PIM) Market | 2026-2036
Global Powder Injection Molding (PIM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Powder Injection Molding (PIM) Market Intelligence
The European Union's Medical Device Regulation (MDR) is shifting the material and process validation requirements for component manufacturers, increasing compliance costs. In this environment, GKN PLC leverages its extensive global manufacturing footprint to serve multinational medical and automotive clients requiring certified parts. Indo-MIM Pvt. Ltd. specializes in high-volume, complex metal injection molding for diverse end-markets, including consumer electronics. Höganäs AB sustains its market position through its dedicated focus on metal powder development and production.
Powder injection molding is a net-shape manufacturing process that combines the design flexibility of plastic injection molding with the material properties of high-performance metals or ceramics. The process involves mixing fine powders with a polymer binder to create a feedstock, which is then injection molded, debound, and sintered to achieve near-full density and superior mechanical strength. Metal Injection Molding (MIM) constitutes the largest product segment, driven by its extensive use in industrial machinery. The aerospace components application, while smaller, represents the fastest-growing segment due to stringent performance demands.
Compliance with standards from the US Food and Drug Administration (FDA) and the EU's MDR is critical for market access in the high-value medical device segment. In parallel, material standards such as ISO specifications and China's GB standards govern powder quality and component testing across industrial applications. Component producers must now decide whether to invest in advanced in-house quality control systems or rely on specialized third-party validation services to ensure conformity.
Market Dynamics
The powder injection molding market is defined by the tension between expanding design possibilities and escalating regulatory scrutiny. Innovations in feedstock and sintering enable more intricate components for medical and aerospace applications, while stricter validation mandates from bodies like the FDA and EU increase compliance costs.
Growth Catalysts
- Advanced Manufacturing Initiatives:Government programs in Germany and Japan promoting Industry 4.0 and advanced manufacturing are accelerating the adoption of PIM for high-precision industrial and automotive components.
- Medical Device Miniaturization:Demand from the medical sector for smaller, more complex surgical tools and diagnostic equipment drives the use of MIM, which excels at producing intricate, net-shape parts.
- Aerospace Performance Demands:The aerospace industry's requirement for lightweight, high-strength components made from superalloys and titanium is a significant catalyst for PIM process development and material qualification.
Market Restraints
- High Initial Capital Outlay:The substantial investment required for molding machines, debinding equipment, high-temperature sintering furnaces, and complex tooling presents a significant barrier to entry for new or smaller firms.
- Feedstock Cost and Availability:The price volatility and supply constraints for specialized, highly pure metal powders, particularly for refractory metals and titanium alloys, can impact production costs and margins.
- Part Size Limitations:While improving, the PIM process remains generally limited to smaller, lighter components, making it unsuitable for large structural applications where forging or casting are more economical.
Strategic Opportunities
- Electric Vehicle Components:The transition to electric mobility creates opportunities for PIM in producing complex, high-volume parts like connectors, busbars, and small gears for motors and transmissions.
- Multi-Material Molding:The development of co-molding techniques allows for the creation of single components with distinct material properties, such as a part with both hard and soft magnetic sections.
- Consumer Wearables Market:High-end consumer electronics, including smartwatches and augmented reality glasses, offer a volume market for small, aesthetically critical, and complex PIM components.
Industry Challenges
- Process Standardization Gaps:A lack of universally accepted process standards for debinding and sintering can lead to variability in component quality and performance between different PIM producers.
- Skilled Labor Scarcity:The industry faces a shortage of engineers and technicians with the specific multidisciplinary expertise in metallurgy, polymer science, and process control required for PIM operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Powder Injection Molding (PIM) Market |
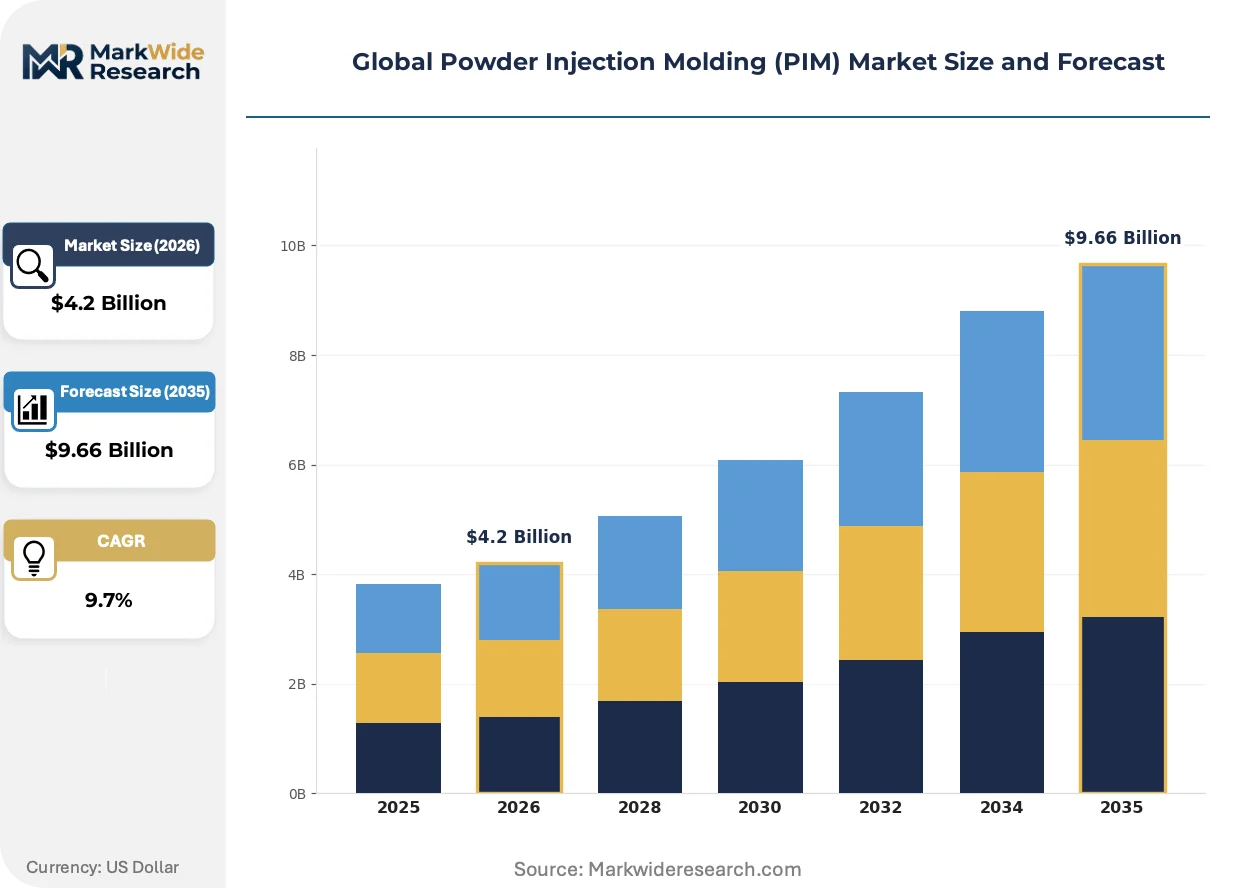
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $9.66 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Injection Molding, Ceramic Injection Molding, Composite Injection Molding, Polymer Injection Molding Technology: Sintering, Debinding, Gas Atomization, Extrusion, Injection Molding Machines Application: Consumer Electronics, Aerospace Components, Industrial Machinery, Medical Devices, Electrical Equipment End User: Tool Manufacturers, Precision Engineering Firms, Medical Instrument Makers, Electronic Component Producers |
| Companies Covered | Schunk Sintermetalltechnik GmbH, Parmaco Metal Injection Molding AG, Höganäs AB, GKN PLC, Advanced Materials Technologies Pte Ltd, Indo-MIM Pvt. Ltd., ARC Group Worldwide, Inc., MPP GmbH, Arburg GmbH + Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Powder Injection Molding (PIM) Market Strategic Shifts & Innovations
Material science advancements and evolving end-market requirements are reshaping component design and manufacturing strategies. The convergence of sophisticated process technologies with stringent quality mandates is defining the competitive landscape for PIM producers, particularly in high-value regulated sectors.
Gas atomization is a technology that produces exceptionally fine and spherical metal powders essential for achieving high packing density and flowability in feedstock. Aerospace and medical device manufacturers are prime adopters, demanding these powders for their most critical, high-performance parts. This advanced powder production method is converging with sophisticated mold-flow simulation software, enabling the first-time-right manufacturing of components with unprecedented geometric complexity.
The European Union's Medical Device Regulation (MDR) imposes significantly stricter lifecycle traceability and clinical evidence requirements. This directive elevates the compliance burden on component manufacturers, necessitating more rigorous process validation and documentation. Consequently, medical OEMs are consolidating their supply chains, favoring PIM partners who can provide comprehensive quality assurance and pre-validated material systems compliant with both EU and FDA standards.
A notable shift in purchasing behavior is occurring as buyers in industrial sectors move away from purely cost-driven procurement. Customers now place a higher value on supply chain resilience and a supplier's demonstrated ability to meet stringent quality certifications, such as ISO specifications. This trend is particularly evident in North America and Europe, where recent disruptions have highlighted the risks of over-reliance on single-source or low-cost supply chains.
Global Powder Injection Molding (PIM) Market Segmentation
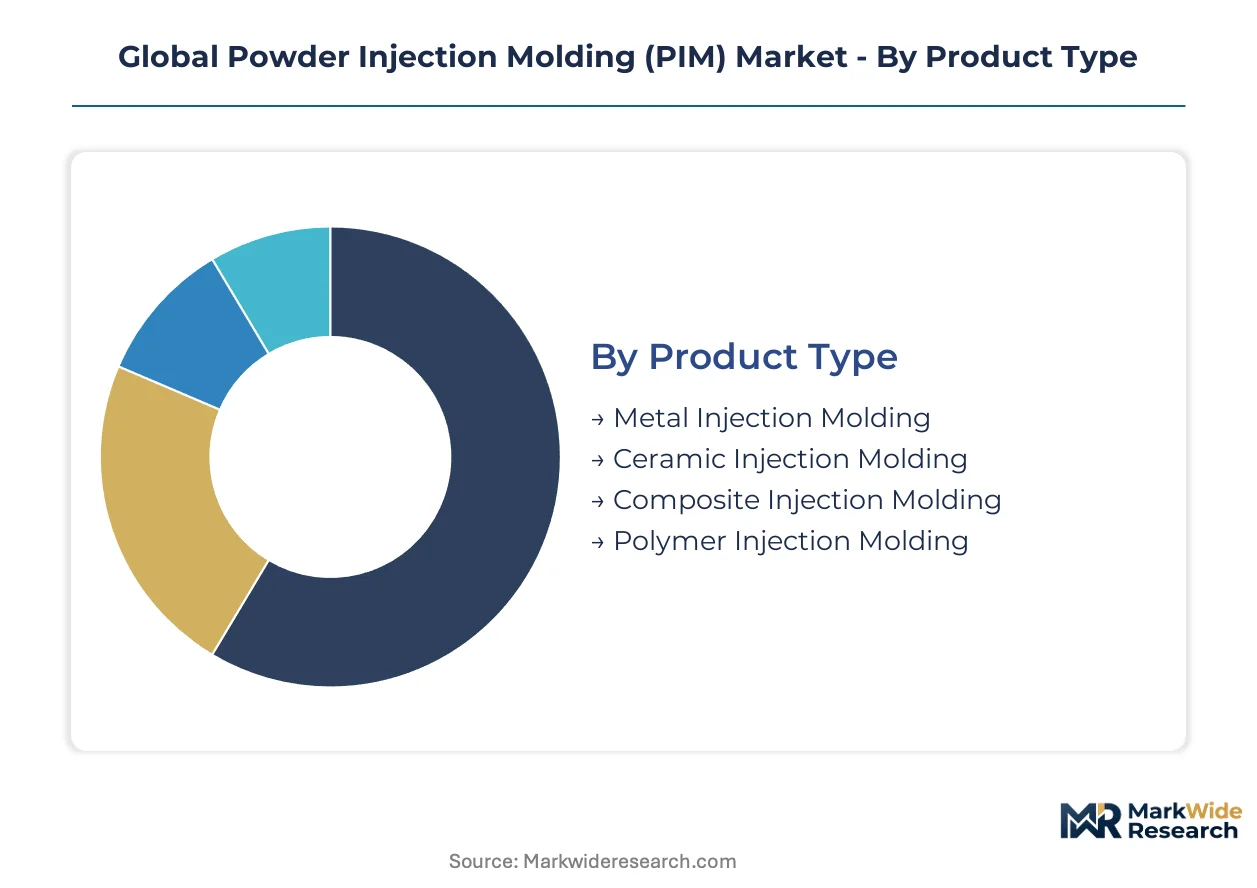
The Powder Injection Molding (PIM) market exhibits diverse segmentation, reflecting the varied material properties and processing requirements across different end-use sectors. Understanding these segments is critical for producers to align their material science innovations and manufacturing capabilities with specific market demands, particularly in regulated industries.
Product Type:
The upgrade cycles in medical devices and consumer electronics are driving product type evolution, favoring materials that offer enhanced performance and miniaturization.
- Metal Injection Molding (MIM):This segment involves combining fine metal powders with a polymer binder to form complex geometries, achieving high mechanical strength after sintering. Demand concentrates in industrial machinery and automotive components, where precision and durability are paramount.
- Ceramic Injection Molding (CIM):CIM utilizes ceramic powders for parts requiring exceptional hardness, wear resistance, and thermal stability, often for high-temperature or corrosive environments. Medical device manufacturers and aerospace firms increasingly adopt CIM for biocompatible implants and specialized engine components.
- Composite Injection Molding:This process integrates different material powders to achieve hybrid properties, such as enhanced strength-to-weight ratios or specific electrical characteristics.
- Polymer Injection Molding:While distinct from PIM's metal/ceramic focus, this category encompasses the polymer binder component itself, which is crucial for feedstock preparation and initial part formation.
Volume placements concentrate in Metal Injection Molding; the faster expansion belongs to Ceramic Injection Molding.
Technology:
Supply concentration in advanced processing techniques is dictating material quality and component performance across the PIM market.
- Sintering:This critical thermal process densifies the debound part, removing porosity and imparting final mechanical properties like hardness and strength. Aerospace and medical device applications demand highly controlled sintering processes to meet stringent material specifications.
- Gas Atomization:Gas atomization produces exceptionally fine, spherical metal powders with high purity, essential for achieving superior flowability and packing density in PIM feedstock. Producers in Germany and Japan are investing in this technology for high-performance superalloys and titanium.
- Debinding:Debinding removes the polymer binder from the molded green part before sintering, a crucial step influencing final part integrity and dimensional accuracy.
- Extrusion:Extrusion is used in feedstock preparation, mixing powders with binders to create a homogeneous material suitable for injection molding.
- Injection Molding Machines:These specialized machines form the feedstock into the desired complex shape, offering high precision and repeatability in production.
The market operates on a technological foundation where Sintering underpins final part quality; Gas Atomization is gaining share fastest due to material advancements.
Application:
Application diversity shapes the PIM market, with high-volume industrial uses contrasting with specialized, high-performance sectors.
- Industrial Machinery:This segment utilizes MIM parts for gears, cams, and other intricate components requiring high wear resistance and precision in manufacturing equipment. The robust demand from industrial centers in the United States and Europe drives significant PIM volume.
- Aerospace Components:PIM produces lightweight, high-strength parts for aircraft engines, control systems, and structural elements using advanced alloys. The requirement for stringent performance in this sector, particularly from manufacturers in the US and France, fuels significant process development.
- Consumer Electronics:PIM is employed for small, complex components in devices like smartwatches and smartphones, offering design freedom and aesthetic quality.
- Medical Devices:PIM enables the production of intricate surgical instruments, orthopedic implants, and diagnostic equipment, meeting strict biocompatibility and performance standards.
- Electrical Equipment:PIM components are found in connectors, sensors, and magnetic parts for various electrical systems, benefiting from precision and material versatility.
High volume demand originates from Industrial Machinery; Aerospace Components are undergoing the steepest expansion trajectory.
End User:
Procurement patterns among end users are shifting towards suppliers capable of meeting both technical specifications and regulatory compliance in high-value sectors.
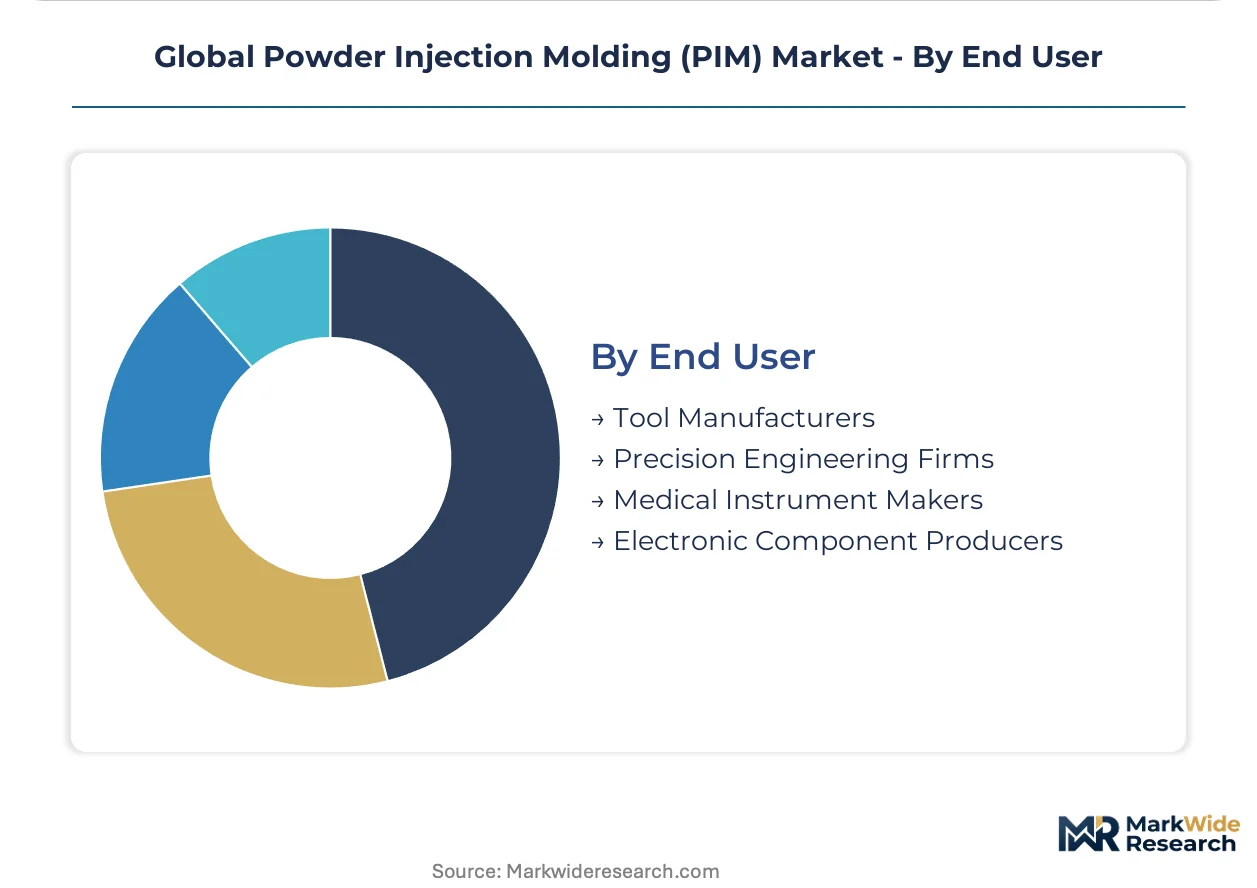
- Precision Engineering Firms:These firms require PIM parts for custom machinery, tooling, and specialized industrial equipment, emphasizing tight tolerances and material consistency.
- Medical Instrument Makers:Manufacturers of surgical tools, implants, and diagnostic devices rely on PIM for biocompatible materials and intricate designs, adhering to FDA and EU MDR standards.
- Tool Manufacturers:PIM supplies components for various hand tools, power tools, and specialized manufacturing jigs, where durability and specific geometries are essential.
- Electronic Component Producers:This segment uses PIM for small, complex parts in connectors, housings, and heat sinks, requiring high precision and material conductivity.
Volume is primarily driven by Precision Engineering Firms; Medical Instrument Makers are exhibiting the most rapid growth in adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced manufacturing clusters, often supported by governmental incentives, drive the global Powder Injection Molding market by concentrating production and innovation. These specialized zones foster a robust ecosystem for material science advancements and high-precision component manufacturing. The demand for intricate PIM parts is intensifying across diverse end-use sectors.
Germany
Demand for PIM components in Germany stems from its strong automotive and industrial machinery sectors, requiring high-precision parts. German Industry 4.0 initiatives actively promote the adoption of advanced manufacturing processes like PIM. Production centers in Baden-Württemberg and Bavaria specialize in complex metal and ceramic parts for critical applications.
Japan
Japanese precision engineering firms and consumer electronics manufacturers drive significant demand for miniature and high-performance PIM components. The Ministry of Economy, Trade and Industry (METI) supports advanced materials research and development, including PIM technologies. Industrial clusters in the Kanto region, particularly around Tokyo, lead in PIM innovation for diverse markets.
United States
The United States medical device sector and aerospace industry significantly propel PIM demand for intricate surgical tools and high-strength, lightweight components. Compliance with US Food and Drug Administration (FDA) standards is critical for market access in high-value medical applications. Manufacturing hubs in the Midwest and Northeast concentrate on advanced PIM production for these regulated sectors.
China
China's rapid expansion in consumer electronics and electric vehicle manufacturing generates substantial volume demand for PIM parts. Adherence to GB standards for material quality and component testing is mandatory for market entry. The Yangtze River Delta region, including cities like Shanghai and Suzhou, represents a major PIM production and consumption hub.
India
The Indian automotive and industrial machinery sectors increasingly utilize PIM for cost-effective, complex components, supporting domestic manufacturing growth. The Production-Linked Incentive (PLI) scheme encourages local production and technological advancements in various industries. Bengaluru, a major technology and manufacturing center, is witnessing rising PIM adoption for precision engineering applications.
Global Powder Injection Molding (PIM) Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure within the Powder Injection Molding industry. Large, vertically integrated players offer comprehensive solutions across the value chain. Strategic archetypes include material developers, contract manufacturers, and equipment providers. Geographic expansion and technology licensing represent dominant competitive moves.
Among European-based specialists, Höganäs AB exemplifies a materials-centric approach, focusing on advanced metal powder development. GKN PLC represents a diversified global manufacturing footprint, serving multinational medical and automotive clients. Indo-MIM Pvt. Ltd. occupies a strong position in high-volume, complex metal injection molding for diverse end-markets, including consumer electronics.
| Leading Market Players |
|---|
| Schunk Sintermetalltechnik GmbH |
| Parmaco Metal Injection Molding AG |
| Höganäs AB |
| GKN PLC |
| Advanced Materials Technologies Pte Ltd |
| Indo-MIM Pvt. Ltd. |
| ARC Group Worldwide, Inc. |
| MPP GmbH |
| Arburg GmbH + Co KG |
| Others |
Cost & Logistics Intelligence
Metal powder commodity prices, including nickel and titanium, cascade through the PIM supply chain, influencing feedstock costs and ultimately component pricing tiers. This market balances the high cost of specialized materials with the value derived from intricate, high-performance parts. Supply chain resilience and regulatory compliance significantly shape procurement strategies among end-users.
Pricing Analysis
Lead-time-driven pricing offers a premium for rapid delivery of specialized PIM components, while standard orders receive contract-based rates. Pricing differentiates based on certification level, particularly FDA and EU MDR compliance for medical devices, and the degree of component customization. Pricing pressure stems from raw material price volatility for superalloys and titanium. Medical instrument makers exhibit the lowest price sensitivity due to stringent performance requirements, while industrial machinery firms are more cost-conscious for high-volume applications.
Supply Chain Analysis
Domestic-content mandates in the United States and Germany reshape sourcing strategies for critical PIM components. Geographic supply concentrates in advanced manufacturing hubs like Germany, Japan, and the United States, with significant volume production also in China and India. Raw material dependencies include highly pure metal powders (e.g., nickel, cobalt, titanium) and specialized polymer binders. Commodity price volatility for these metal powders represents a significant structural risk. Distribution runs through direct-to-OEM channels for high-value aerospace and medical applications, with specialized distributors serving smaller firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Powder Injection Molding market presents a cost-of-compliance narrative, where the European Union's Medical Device Regulation (MDR) creates a significant barrier-to-entry moat for compliant players. This regulatory environment favors established firms with robust quality systems.
For Market Incumbents: To counter emerging low-cost competition, PIM incumbents must deepen vertical integration into feedstock production, especially for specialized metal powders. Invest in advanced in-house quality control systems to streamline compliance with FDA and EU MDR standards. Diversify global manufacturing footprint beyond Germany and Japan to mitigate geopolitical supply risks. Focus R&D on next-generation multi-material molding capabilities.
For New Entrants and Emerging Players: Launch via specialized contract manufacturing partnerships in high-growth niches like electric vehicle components or consumer wearables. Target regions with less stringent regulatory hurdles initially, such as specific industrial applications in Southeast Asia. Focus on developing proprietary debinding processes to offer superior dimensional accuracy. Emphasize rapid prototyping services as a go-to-market angle for design-intensive clients.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized PIM specialists with strong intellectual property in material science or process innovation, particularly in Germany and the United States. Long-term viability is strong over a 5-10 year window, driven by medical device miniaturization and aerospace performance demands. The signal to watch is the consolidation activity among smaller, specialized PIM producers struggling with regulatory compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Debinding | Increases throughput and consistency for intricate components, meeting rising demand from medical device manufacturers. |
| Certification Investment for EU MDR | Ensures market access and strengthens competitive positioning in the high-value European medical device segment. |
| R&D in Superalloy Powder Development | Enables production of lightweight, high-strength parts for the rapidly expanding aerospace components application. |
| Global Footprint Diversification | Mitigates single-region supply chain risks and accesses new customer bases in growing automotive and electronics markets. |
| Strategic Partnership for Multi-Material Molding | Expands product offerings to include components with hybrid properties, catering to evolving end-user design requirements. |
Research Approach
Industry association reports, government economic data, and company financial filings formed the secondary backbone of this analysis. Primary research included interviews with PIM process engineers, materials scientists, medical device procurement specialists, and automotive component designers. This approach ensured a robust bottom-up and top-down triangulation of market insights.
Bottom-up analysis aggregated data from key PIM product types, technologies, applications, end-users, and regional demand centers across the analysis window. This framework modeled market expansion by considering specific PIM material advancements and end-market adoption rates. Compound annual growth rates were derived from historical trends and projected technological advancements, incorporating inputs like metal powder consumption and medical device manufacturing output.
Raw material price shocks, regulatory shifts, and geopolitical trade tensions are the dominant revision risks for future market projections. Forecasts reflect assumptions documented through extensive primary and secondary research. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Joint Compound Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Phenylacetyl Chloride Market