
 Dextran Sulfate Sodium Market | 2026-2036
Dextran Sulfate Sodium Market Size, Share, and Industry Trends Forecast 2026-2036
Dextran Sulfate Sodium Market Outlook
Aftermarket technical service revenue is tilting toward application-specific formulation support as buyers seek validated protocols for antiviral assays. MP Biomedicals leverages its catalog breadth to anchor laboratory supply relationships across North American research institutes. Polysciences specializes in custom molecular weight fractions, competing on specification flexibility rather than commodity volumes. Pharmacosmos AS controls quality documentation for pharmaceutical-grade batches, sustaining premium positioning in European injectable markets.
Dextran sulfate sodium is a sulfuric acid ester of dextran, typically manufactured with sulfate substitution degrees of 15-20% and molecular weights spanning 5,000 to 500,000 Daltons, functioning primarily as an anticoagulant mimic and viral attachment inhibitor in biomedical applications. Pharmaceutical grade material commands the dominant margin pool due to endotoxin and residual solvent specifications that exclude lower-tier suppliers, while laboratory grade volumes grow fastest as CRISPR and cell culture workflows multiply protocol consumption. Application segmentation shows antiviral research and drug delivery vectors absorbing disproportionate R&D investment, with laboratory research representing the mature, price-sensitive baseline.
FDA heparin adulteration controls and EMA pharmacopeial monographs for polysaccharide derivatives are elevating analytical burden on manufacturers, compressing margins for undifferentiated grades while rewarding ISO-certified producers with validated impurity profiles. The USP-NF and EP reference standards for dextran sulfate molecular weight calibration create additional compliance gateways that favor established analytical laboratories. Stakeholders must monitor evolving EPA discharge rules for sulfate ester manufacturing effluent, as environmental compliance costs will reshape supplier economics faster than end-demand shifts.
Market Dynamics
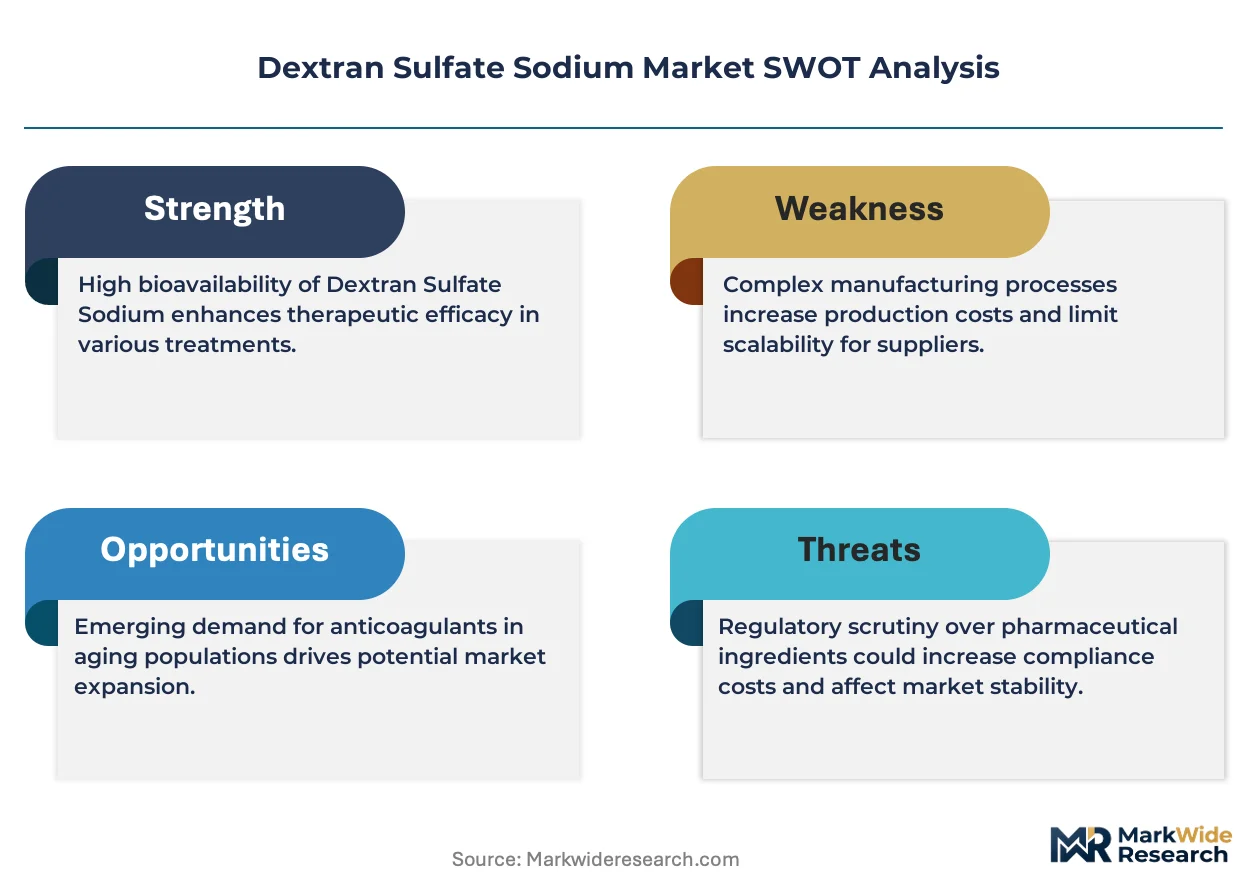
FDA and EMA pharmacopeial tightening on polysaccharide derivatives is compressing supplier margins while rewarding ISO-certified producers with validated impurity profiles. This regulatory elevation is restructuring competitive advantage toward analytical laboratories with documented endotoxin control.
Growth Catalysts
- Antiviral assay protocols:CRISPR and cell culture workflows are multiplying laboratory-grade consumption across North American research institutes.
- REACH compliance evolution:ECHA purity benchmarks are accelerating pharmaceutical-grade qualification cycles for sulfate dextran sources in European injectable markets.
- Heparin alternative demand:FDA guidance on anticoagulant substitutes is pulling pharmaceutical companies toward validated dextran sulfate sodium formulations.
Market Restraints
- Raw material volatility:Dextran feedstock prices fluctuate with agricultural dextrose markets, squeezing contract manufacturer margins.
- Supplier concentration:Pharmaceutical-grade batch documentation capabilities cluster among established European analytical laboratories, limiting new entrant access.
- Endotoxin specification barriers:Residual solvent and pyrogen testing requirements exclude lower-tier suppliers from premium margin pools.
Strategic Opportunities
- Drug delivery vector expansion:Nanoparticle formulation research is opening new specification requirements for custom molecular weight fractions.
- EPA discharge rule preparation:Early compliance investment in sulfate ester manufacturing effluent controls will reshape supplier economics ahead of competitors.
- Contract manufacturing qualification:United States and Germany-based CMOs are actively sourcing alternative dextran sulfate sodium suppliers for injectable applications.
Industry Challenges
- Analytical talent scarcity:Validated impurity profiling and molecular weight calibration expertise concentrates among aging specialists in established laboratories.
- Certification timeline compression:USP-NF and EP reference standard alignment demands extended validation cycles that delay revenue recognition.
- Legacy equipment integration:New sulfate substitution control systems must interface with existing GMP manufacturing infrastructure without process disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dextran Sulfate Sodium Market |
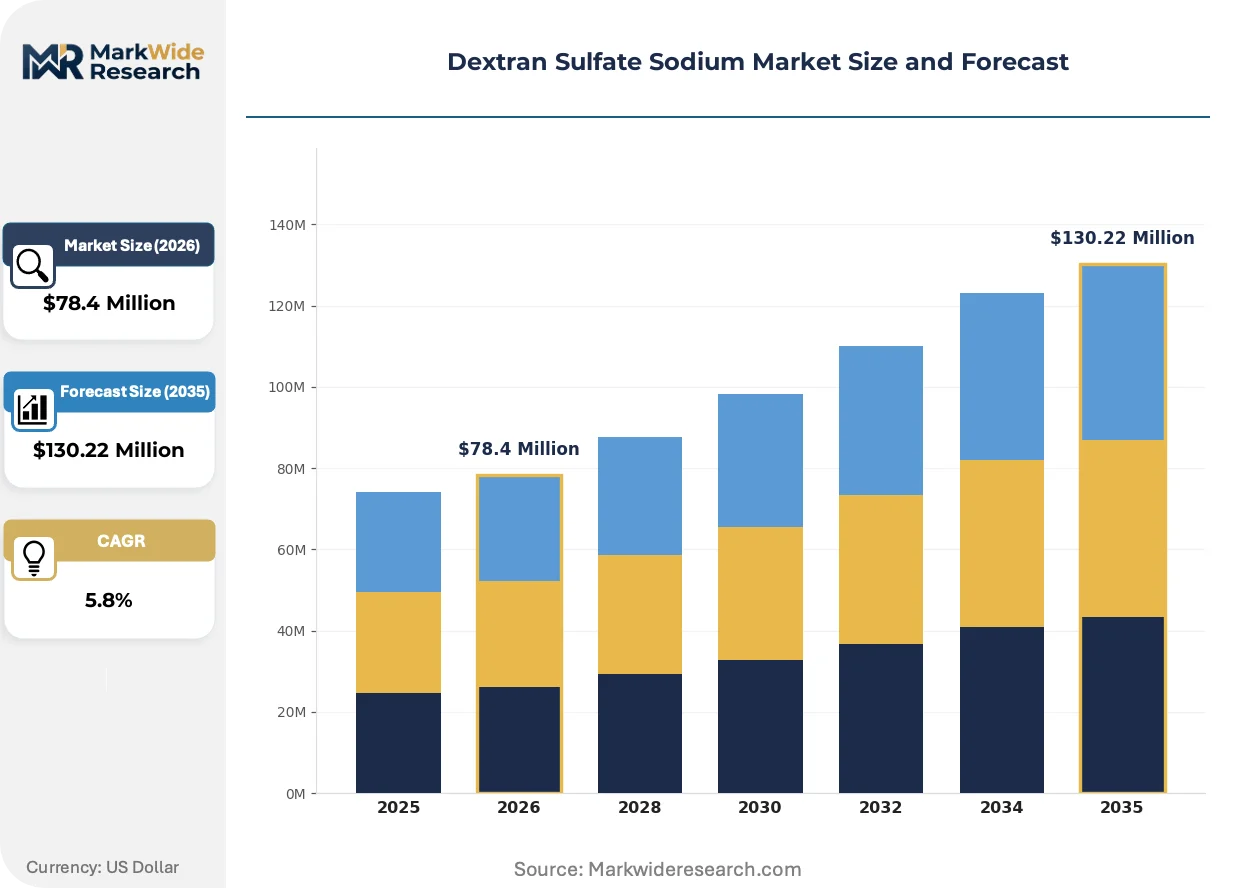
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $130.22 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Industrial Grade, Laboratory Grade, Cosmetic Grade Application: Anticoagulant, Antiviral Agent, Drug Delivery, Laboratory Research End User: Pharmaceutical Companies, Research Laboratories, Healthcare Institutions, Cosmetic Manufacturers Delivery Mode: Injectable, Oral, Topical, Intranasal |
| Companies Covered | MP Biomedicals, Polysciences, AMRESCO, BOC Sciences, Sisco Research Laboratories, Watson International, Pharmacosmos AS, MEITO SANGYO CO LTD, Swati Spentose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dextran Sulfate Sodium Market Strategic Shifts
Specification flexibility is displacing commodity volume competition as buyers prioritize validated protocols over catalog breadth. Three developments are restructuring how value accumulates across the value chain.
Precision molecular weight fractionation is migrating from laboratory curiosity to commercial necessity. Biopharmaceutical formulation groups now specify narrow polydispersity ranges for drug delivery vectors. This capability compression is eliminating undifferentiated grade suppliers from injectable application pipelines.
EMA pharmacopeial monographs for polysaccharide derivatives are elevating analytical burden on manufacturers. European contract manufacturers now demand batch-specific endotoxin documentation before qualification. Pharmaceutical-grade material suppliers with ISO-certified impurity profiles are capturing disproportionate margin expansion.
Technical service unbundling is fragmenting traditional supply relationships. Research institutes now purchase validated antiviral assay protocols separately from material supply. North American buyers are driving this disintermediation, forcing catalog distributors to develop application-specific formulation support capabilities or surrender margin to specialized consultancies.
Dextran Sulfate Sodium Market Segmentation
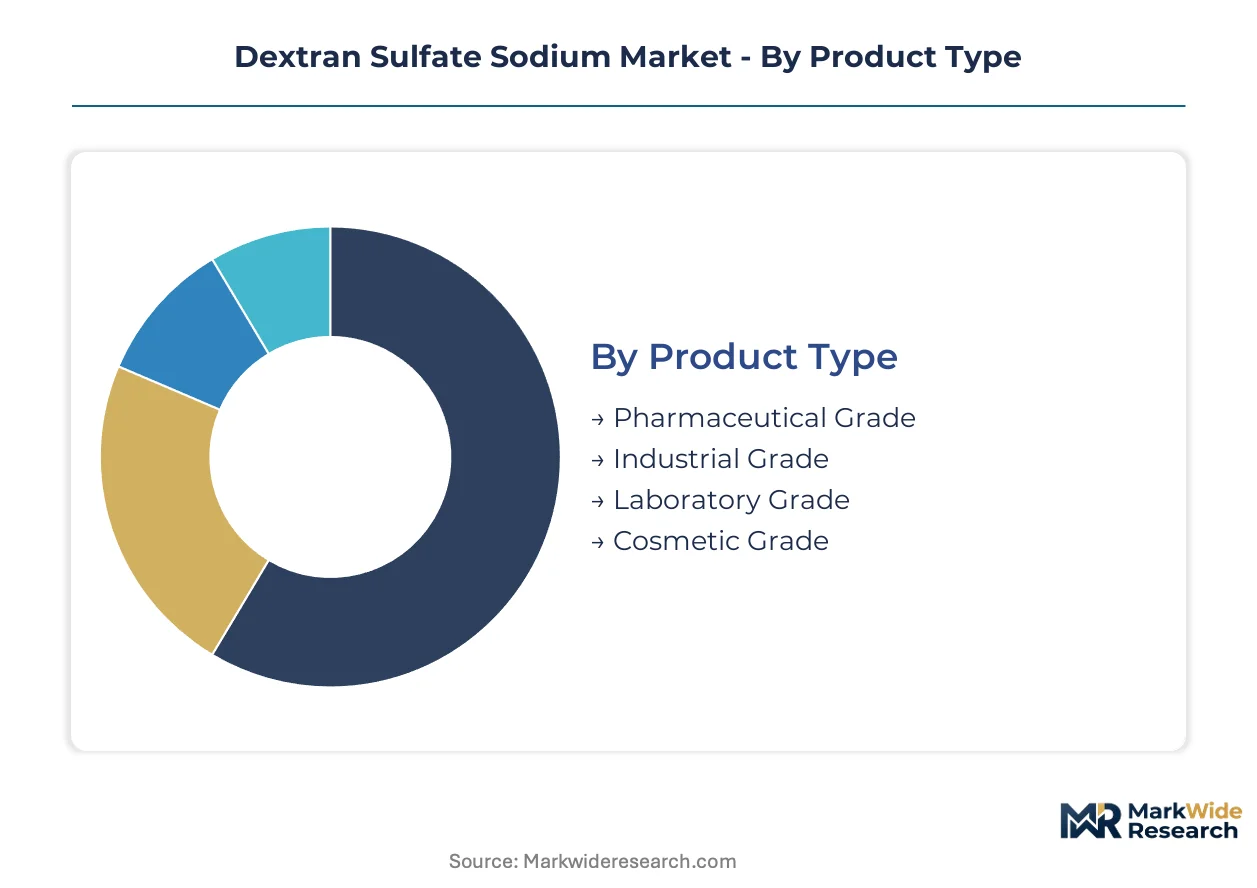
Specification requirements diverge sharply across dextran sulfate sodium grades, with pharmaceutical and laboratory tiers commanding distinct validation protocols. Application-specific formulation support now determines supplier selection more than catalog breadth alone.
Product Type:
After-sales technical service intensity peaks with pharmaceutical grade material, where batch documentation and endotoxin validation require sustained analytical partnership.
- Pharmaceutical Grade:Sulfate substitution degrees of 15-20% and molecular weights spanning 5,000 to 500,000 Daltons meet USP-NF and EP reference standards. Demand concentrates in Germany and the United States as contract manufacturers qualify new sources for injectable applications under tightening FDA guidance on heparin alternatives.
- Laboratory Grade:Lower endotoxin thresholds than industrial material but without pharmaceutical batch certification. CRISPR and cell culture workflows across North American research institutes are multiplying protocol consumption fastest.
- Industrial Grade:Commodity specifications serve bulk chemical applications without biomedical validation requirements.
- Cosmetic Grade:Purified for topical formulation stability rather than systemic safety profiles.
Pharmaceutical grade holds the largest share; momentum sits with laboratory grade.
Application:
Cost tier stratification separates validated therapeutic applications from exploratory research uses.
- Antiviral Agent:Viral attachment inhibition protocols require documented sulfate substitution consistency. North American buyers now purchase validated assay protocols separately from material supply.
- Drug Delivery:Nanoparticle formulation research is opening specification requirements for custom molecular weight fractions with narrow polydispersity ranges.
- Anticoagulant:Heparin alternative demand pulls pharmaceutical companies toward validated formulations under FDA adulteration controls.
- Laboratory Research:Mature, price-sensitive baseline consumption across cell culture and molecular biology workflows.
Antiviral applications hold the largest share; drug delivery vectors are climbing the fastest.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding ISO-certified impurity profiles that research laboratories rarely require.
- Pharmaceutical Companies:Dominate premium margin pools through endotoxin and residual solvent specifications that exclude lower-tier suppliers. REACH compliance evolution in Europe accelerates qualification cycles.
- Research Laboratories:Catalog distributors serving this segment must develop application-specific formulation support capabilities or surrender margin to specialized consultancies.
- Healthcare Institutions:Procurement concentrates on validated injectable formulations with documented batch traceability.
- Cosmetic Manufacturers:Specification flexibility requirements compete on molecular weight customization rather than purity documentation depth.
Pharmaceutical companies hold the largest share; research laboratories are gaining share fastest.
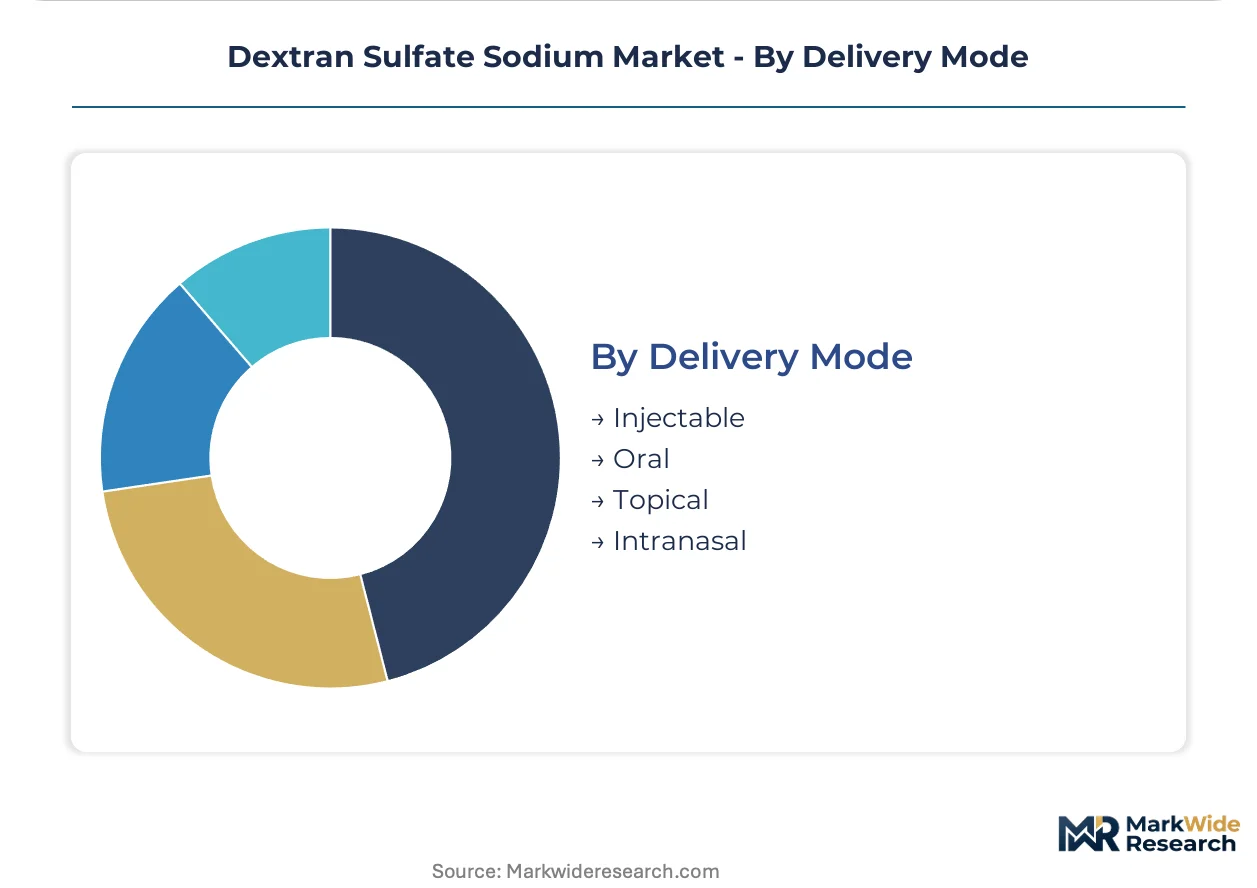
Delivery Mode:
Supply concentration among established European analytical laboratories limits new entrant access to injectable qualification pathways.
- Injectable:Most stringent endotoxin and pyrogen testing requirements. EMA pharmacopeial monographs elevate analytical burden, compressing margins for undifferentiated grades.
- Oral:Intermediate validation tier between injectable safety requirements and topical cosmetic standards.
- Topical:Cosmetic and dermatological applications prioritize formulation stability over systemic absorption profiles.
- Intranasal:Emerging delivery vector for antiviral prophylaxis with evolving mucosal irritation testing protocols.
Injectable delivery holds the largest share; intranasal formulations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: Germany and the United States concentrate pharmaceutical-grade procurement for injectable applications, while Asian markets absorb laboratory-grade volumes for cell culture workflows at faster clip.
United States
FDA guidance on heparin alternatives and anticoagulant adulteration controls are pulling pharmaceutical companies toward validated dextran sulfate sodium formulations. The agency's evolving pharmacopeial standards for polysaccharide derivatives compress margins for undifferentiated grades. Contract manufacturers in Greater Boston and the Research Triangle Park are actively qualifying new sulfate dextran sources for injectable drug delivery vectors.
Germany
EMA pharmacopeial monographs and REACH compliance evolution are accelerating pharmaceutical-grade qualification cycles for European injectable markets. ECHA purity benchmarks for sulfate ester derivatives tighten endotoxin documentation requirements. Industrial clusters in North Rhine-Westphalia and Bavaria host ISO-certified analytical laboratories with validated impurity profiles that dominate premium margin capture.
Japan
PMDA oversight of heparin substitutes and polysaccharide-based anticoagulants shapes procurement specifications for domestic pharmaceutical manufacturers. METI industrial standards for biomedical-grade chemicals influence supplier selection criteria. The Kanto region around Tokyo concentrates formulation R&D facilities demanding narrow polydispersity molecular weight fractions for drug delivery research.
India
CDSCO import substitution policies and domestic pharmaceutical manufacturing expansion are creating qualification opportunities for local sulfate dextran producers. The country's national pharmaceutical regulator is aligning with USP-NF reference standards for molecular weight calibration. Maharashtra and Gujarat host contract research organizations scaling CRISPR and cell culture workflows that multiply laboratory-grade consumption.
China
NMPA pharmacopeial tightening on polysaccharide derivatives and heparin alternative guidance are elevating analytical burden on domestic manufacturers. SAMR quality documentation requirements for injectable-grade materials exclude lower-tier suppliers. The Yangtze River Delta and Pearl River Delta clusters concentrate biopharmaceutical formulation groups specifying custom molecular weight fractions for nanoparticle research.
Dextran Sulfate Sodium Market Competitive Environment
Capability concentration sits with analytical laboratories possessing validated impurity profiles; scale advantage sits with catalog distributors serving high-volume research workflows. The market structures around three tiers: ISO-certified producers commanding pharmaceutical-grade premiums, specialized fractionators competing on molecular weight specification flexibility, and commodity suppliers serving industrial applications. Dominant competitive moves include strategic partnerships with contract manufacturers for injectable qualification and portfolio diversification into application-specific formulation support services.
Within the ISO-certified documentation tier, Pharmacosmos AS exemplifies European producers sustaining premium positioning through batch-specific endotoxin validation. MP Biomedicals occupies a position among North American catalog distributors leveraging breadth to anchor laboratory supply relationships across research institutes. Polysciences represents specialists in custom molecular weight fractions, competing on specification flexibility rather than commodity volumes in drug delivery vector applications.
| Leading Market Players |
|---|
| MP Biomedicals |
| Polysciences |
| AMRESCO |
| BOC Sciences |
| Sisco Research Laboratories |
| Watson International |
| Pharmacosmos AS |
| MEITO SANGYO CO LTD |
| Swati Spentose |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp chemical corridor freight costs compress margins for dextran sulfate sodium shipments into German pharmaceutical clusters, amplifying price differentiation between ISO-certified European producers and catalog distributors serving North American research institutes. Contract manufacturers in the United States absorb elevated logistics premiums to secure validated batch documentation, while Asian laboratory-grade buyers exploit regional supply proximity to negotiate volume discounts.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade procurement, with contract manufacturers locking in eighteen-to-twenty-four month supply commitments to secure endotoxin-validated batches. Three-tier pricing structure across pharmaceutical, laboratory, and industrial grades separates premium documentation tiers from commodity specifications. Cost compression in laboratory-grade segments intensifies as CRISPR protocol standardization erodes customization premiums. Research institutes exhibit highest price sensitivity, while injectable drug developers accept substantial premiums for validated impurity profiles.
Supply Chain Analysis
Agricultural dextrose feedstock from corn processing facilities in the United States, Brazil, and China anchors upstream cost volatility for dextran fermentation. Sulfuric acid esterification reagents and molecular weight fractionation membranes constitute critical component dependencies. Single-source vulnerability concentrates in ISO-certified analytical laboratories controlling pharmaceutical-grade batch documentation. Distribution runs through specialized chemical distributors with cold-chain capabilities for endotoxin-sensitive materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dextran sulfate sodium market exhibits cyclical recovery characteristics as FDA heparin alternative guidance and EMA pharmacopeial tightening synchronize regulatory upgrade cycles across major pharmaceutical procurement regions.
For Market Incumbents: Entrench analytical documentation capabilities through investment in USP-NF and EP reference standard alignment, defending against emerging Asian producers acquiring European certification expertise. Prioritize captive supply of narrow polydispersity fractionation capacity to preempt substitution by synthetic polysaccharide alternatives. For New Entrants and Emerging Players: Indian CDSCO-aligned contract research organizations scaling CRISPR workflows represent the most penetrable entry point for laboratory-grade volume capture. Qualification partnerships with Maharashtra-based pharmaceutical manufacturers offer pathway to pharmaceutical-grade credibility. Lead with application-specific formulation support services rather than catalog breadth competition. For Investors and Strategic Acquirers: ISO-certified European analytical laboratories with validated endotoxin control systems command durable scarcity premiums through regulatory compliance cycles. Long-term viability hinges on EPA discharge rule positioning ahead of sulfate ester manufacturing effluent compliance deadlines. Monitor ECHA purity benchmark evolution as inflection indicator for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dextran Fermentation | Corn processing partnerships in Iowa and Illinois secure feedstock cost stability against agricultural commodity swings. |
| Pharmacopeial Certification Investment | USP-NF and EP reference standard alignment opens injectable qualification pathways for German contract manufacturers. |
| Application-Specific Technical Service Expansion | Validated antiviral assay protocols capture margin from disintermediating specialized consultancies in North America. |
| EPA Discharge Compliance Pre-positioning | Early sulfate ester effluent control investment reshapes supplier economics ahead of regulatory enforcement. |
| Long-term Supply Agreement with CMOs | Eighteen-month offtake commitments with Boston-area injectable developers lock in pharmaceutical-grade volume. |
Study Parameters
Desk research of FDA guidance documents, EMA pharmacopeial monographs, and USP-NF reference standards preceded structured interviews with pharmaceutical procurement directors, contract manufacturing executives, and analytical laboratory technical leads. Secondary validation drew from customs trade data, SEC filings of public chemical distributors, and EPA discharge rule dockets. Bottom-up volume estimates from individual producer capacity triangulated against top-down consumption projections derived from CRISPR protocol publication rates and heparin alternative clinical trial registrations.
Assumptions held fixed include current FDA heparin adulteration control stringency and ECHA REACH compliance evolution trajectory, while variables tested included EPA enforcement timing and corn futures price volatility. Segmentation modeling spanned grade tier, application, end-user type, and delivery mode across the projection horizon. CAGRs derived from regression analysis against biomedical research funding flows and pharmaceutical R&D expenditure patterns, with molecular weight fractionation capability diffusion rates serving as industry-specific demand elasticity input.
Practitioners should monitor EPA sulfate ester effluent rulemaking progress and EMA polysaccharide derivative monograph revision schedules for early signals of compliance cost inflection. Forecasts reflect assumptions about regulatory continuity and agricultural feedstock supply stability. Cross-checking against NIH research grant disbursement trends and pharmaceutical company 10-K R&D expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Lauramidopropyl Betaine Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Global Stannic Chloride Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Resin Capsule Market