
 Low Density Sheet Moulding Compound (SMC) Market | 2026-2036
Low Density Sheet Moulding Compound (SMC) Market Size, Share, and Industry Trends Forecast 2026-2036
Low Density Sheet Moulding Compound (SMC) Market Insights
Resin formulation expertise is bifurcating the competitive landscape into specialists and generalists. IDI Composites International leverages its compounding heritage across unsaturated polyester and vinyl ester platforms. Polynt anchors European supply through backward integration into resin synthesis. Teijin competes via high-performance epoxy variants targeting aerospace qualification pathways.
Low density sheet moulding compound denotes a fiber-reinforced thermoset material formulated with hollow glass microspheres or chemical blowing agents to achieve specific gravities below 1.3, manufactured through compression or transfer molding cycles for complex structural geometries. The compound serves automotive and electrical sectors requiring metal replacement with paintable surface finish. Unsaturated polyester resin systems occupy the dominant volume position owing to cost-performance balance in automotive Class A panels. Compression molding technology leads equipment installed base, while injection molding variants capture fastest growth in electrical component miniaturization. Epoxy formulations command premium positioning in aerospace parts where flame-smoke-toxicity certification creates margin concentration.
FDA, EPA, and EU REACH frameworks govern monomer emissions, workplace exposure limits, and substance authorization across manufacturing and end-use phases. The EU Green Deal accelerates low-density SMC substitution for metal in electric vehicle architectures by embedding recycled content mandates and lifecycle carbon thresholds. Stakeholders must monitor evolving automotive OEM material qualification protocols and resin system recyclability certifications as gatekeepers to platform adoption.
Market Dynamics
Automotive OEMs are compressing material qualification timelines as EPA Corporate Average Fuel Economy standards and EU CO2 fleet emission rules tighten simultaneously. This dual-regulatory pressure is forcing resin formulators to accelerate low-density SMC validation cycles for Class A body panel substitution programs.
Growth Catalysts
- EU Green Deal recycled content mandates:Electric vehicle architectures in Germany require lifecycle carbon thresholds that favor hollow glass microsphere formulations over stamped metal. OEM procurement teams are embedding these specifications into platform RFPs.
- Compression molding cycle optimization:Equipment manufacturers are delivering faster cure chemistries that reduce automotive panel production time. Tier-1 suppliers are capturing tooling efficiency gains across unsaturated polyester systems.
- China:MIIT dual carbon goals are accelerating SMC adoption in domestic EV platforms. Local resin compounders are scaling capacity for battery enclosure applications with specific gravity targets below 1.2.
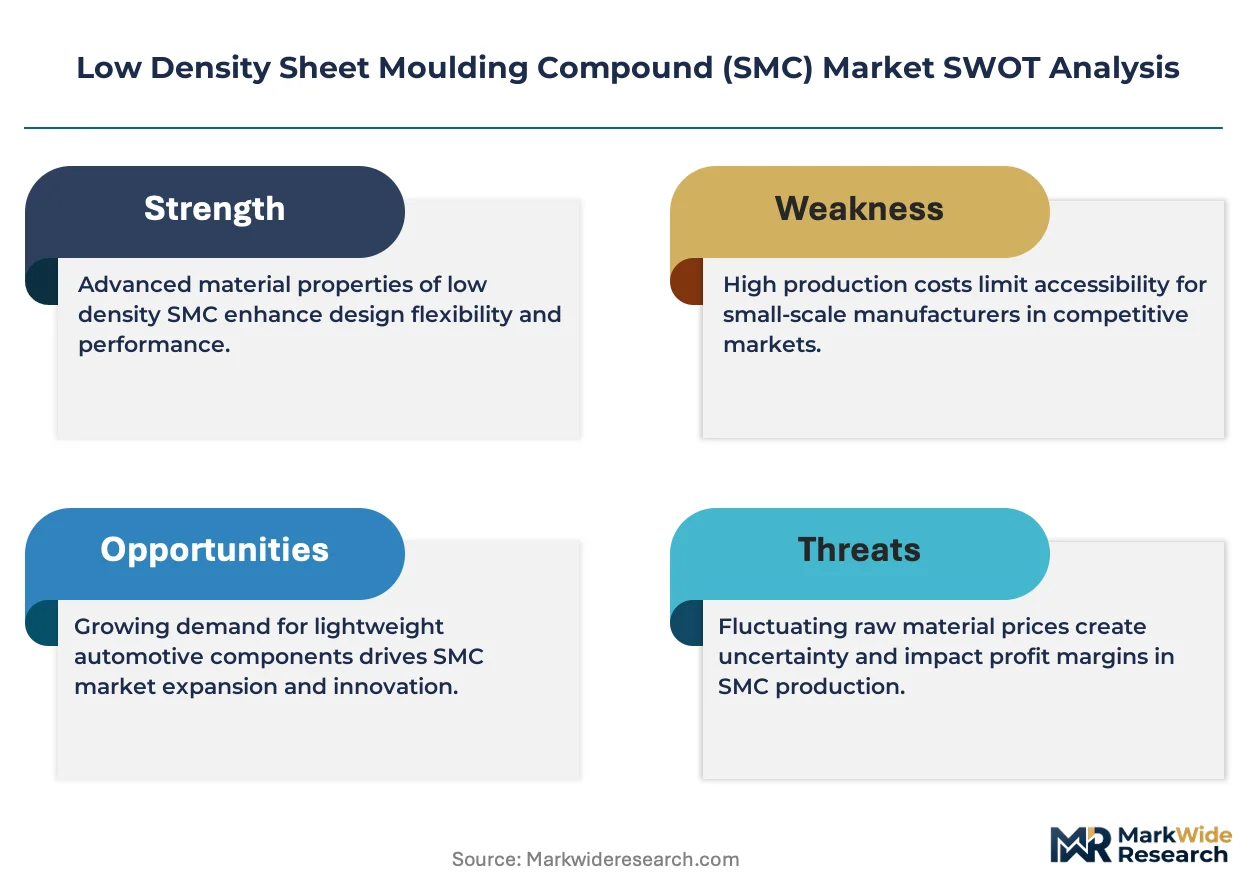
Market Restraints
- Styrene monomer price volatility:Unsaturated polyester resin systems remain exposed to benzene-derivative feedstock swings. Formulators lack short-term hedging instruments for this input cost concentration.
- Epoxy resin supply concentration:Aerospace-grade formulations depend on Asian bisphenol-A epichlorohydrin supply chains. Flame-smoke-toxicity certified material faces extended lead times during regional production disruptions.
- Thermoplastic composite substitution:Long-fiber thermoplastic (LFT) materials are capturing select automotive structural applications. SMC retains surface finish advantages but loses on reprocessing flexibility.
Strategic Opportunities
- India PLI scheme automotive incentives:Domestic manufacturing-linked subsidies are attracting SMC compounders to establish regional compounding facilities. Localized supply reduces landed cost disadvantages against metal stamping.
- Electrical component miniaturization:Transfer molding variants are penetrating switchgear and breaker housings. Hollow glass microsphere loadings enable thinner wall sections without dielectric property degradation.
- EU REACH substance authorization pathways:Pre-registration of novel blowing agent chemistries creates first-mover positioning. Early movers are securing downstream user commitments ahead of sunset date transitions.
Industry Challenges
- Aerospace flame-smoke-toxicity certification timelines:FAA and EASA qualification protocols for epoxy SMC variants extend 18-24 months. Program delays compress revenue recognition windows for specialty resin suppliers.
- Legacy paint line compatibility:Low-density SMC surface energy characteristics require e-coat process recalibration. OEM paint shops are resisting substrate diversification without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Density Sheet Moulding Compound (SMC) Market |
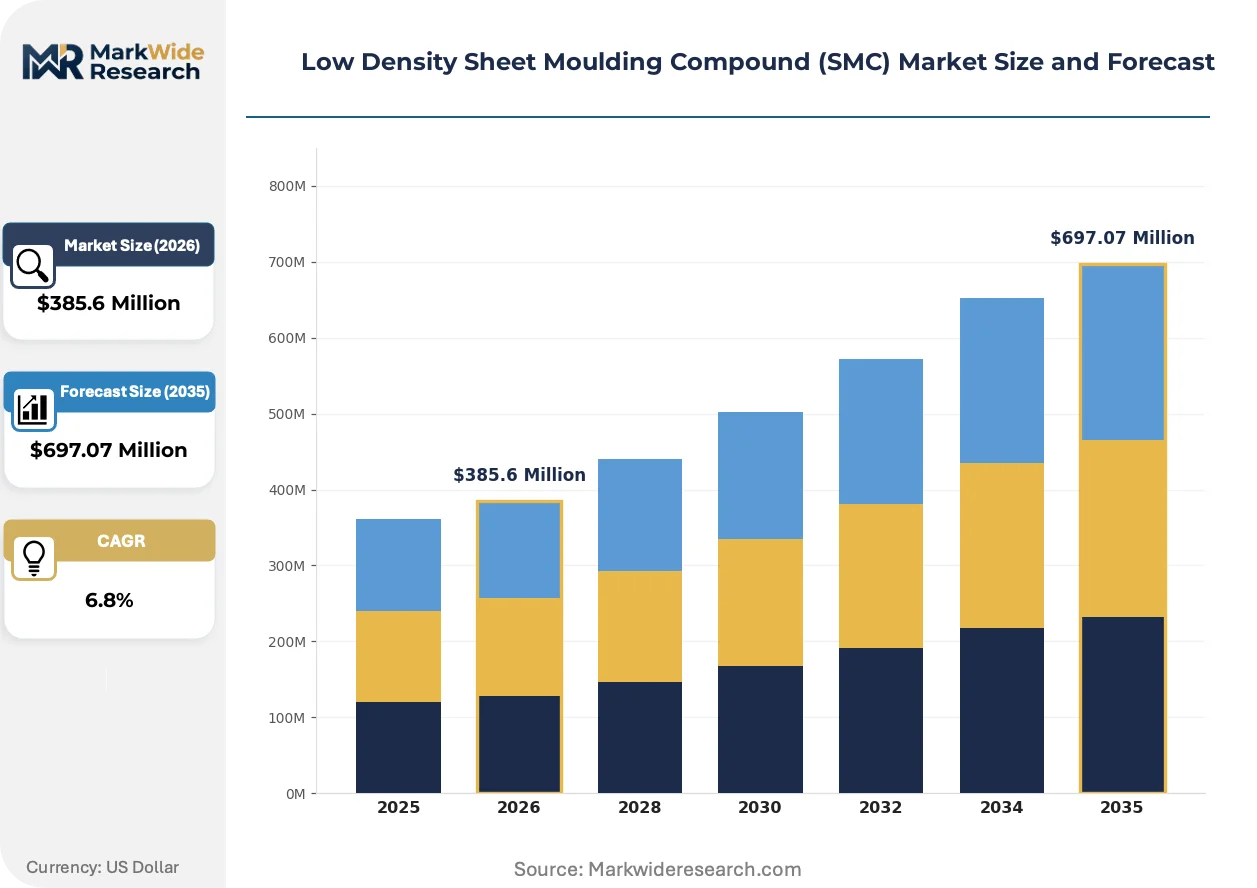
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Resin, Thermoplastic, Unsaturated Polyester, Vinyl Ester, Epoxy, Phenolic Technology: Compression Molding, Transfer Molding, Injection Molding, Reaction Injection Molding Application: Electrical Components, Industrial Equipment, Consumer Goods, Aerospace Parts, Marine Components, Sporting Goods End User: Automobile Manufacturers, Electrical Equipment Makers, Aerospace Firms, Marine Builders, Sporting Goods Producers |
| Companies Covered | IDI Composites International, Polytec Group, Core Molding Technologies, Ningbo HAMC Group, Changzhou Huari New Material, Polynt, Menzolit GmbH, Lorenz, Teijin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Density Sheet Moulding Compound (SMC) Market Trends and Innovations
Material science convergence with process control automation is redefining low-density SMC value propositions. Formulators are integrating real-time viscosity monitoring with predictive cure modeling to compress development cycles.
Injection molding variants for electrical encapsulation are miniaturizing component geometries previously constrained by thermoset flow limitations. Switchgear manufacturers in Japan and South Korea are adopting these systems for 800V EV infrastructure components. The technology is miniaturizing housing wall thicknesses below 2mm while maintaining IEC dielectric withstand requirements.
REACH substance restriction proposals on styrene emissions are compelling German compounders to validate low-VOC vinyl ester alternatives. Workplace exposure limit tightening across EU member states is accelerating capital deployment into closed-mold transfer systems. Automotive Class A panel producers in Stuttgart and Wolfsburg are piloting these chemistries ahead of anticipated 2027 regulatory thresholds.
Buyer concentration among top-tier automotive OEMs is consolidating material qualification pathways. Tier-2 compounders are losing direct platform access as Volkswagen, BMW, and Mercedes-Benz centralize resin system approvals at the group level. This pattern is most visible in Germany, where procurement teams are reducing approved supplier lists from twelve to four primary SMC sources per vehicle architecture.
Low Density Sheet Moulding Compound (SMC) Market Segmentation
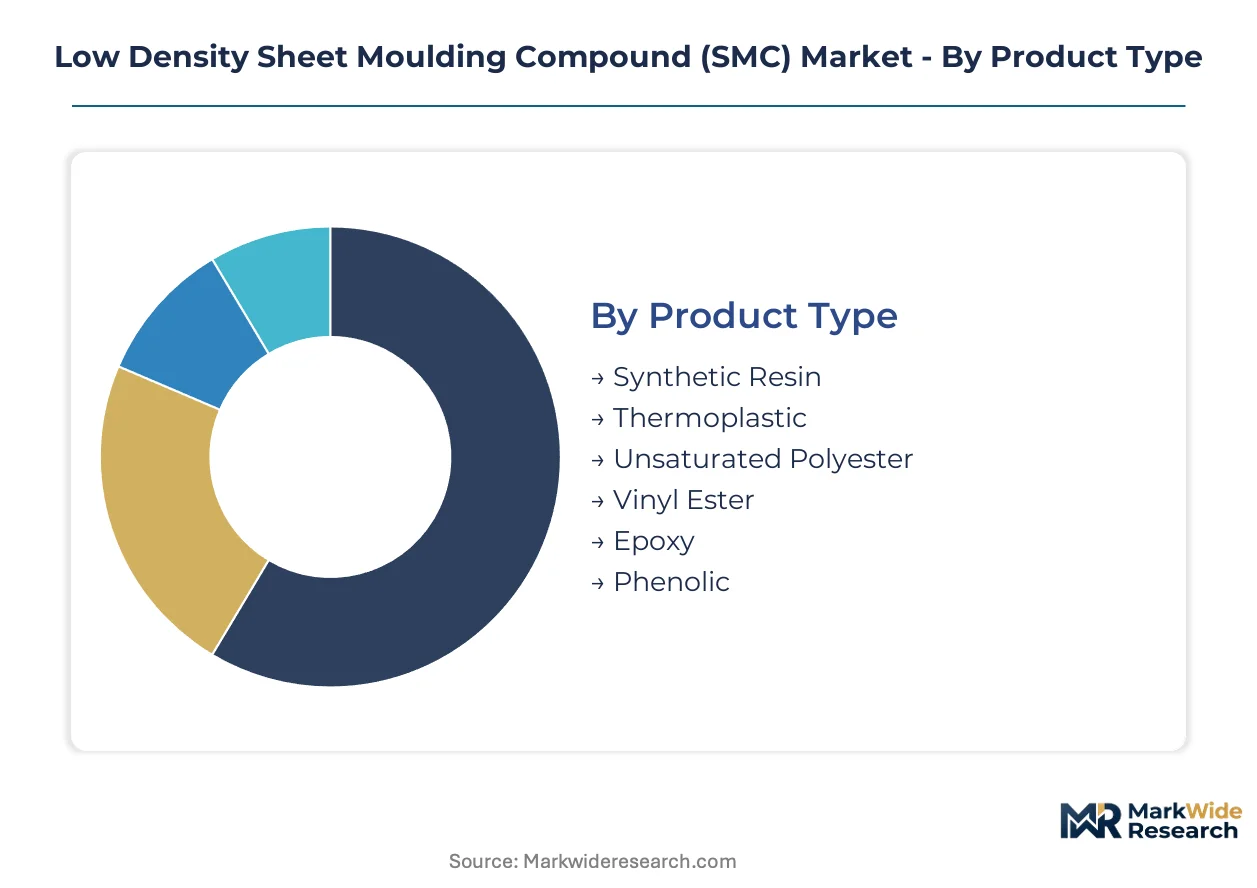
Low density SMC procurement splits along resin chemistry, molding platform, and end-use qualification tier. Each segmentation axis carries distinct regulatory, tooling, and margin implications for compounders and molders.
Product Type:
REACH substance authorization and FAA flame-smoke-toxicity certification create divergent compliance burdens across resin platforms. Formulators optimize density reduction through microsphere loading and blowing agent selection within each chemistry class.
- Unsaturated Polyester:Dominant automotive formulation leveraging styrene-based cure systems for Class A surface finish. Volkswagen, BMW, and Mercedes-Benz procurement teams in Germany concentrate volume awards here due to paint line compatibility and cost-performance balance. EPA Corporate Average Fuel Economy standards sustain substitution programs for stamped steel closure panels.
- Vinyl Ester:Corrosion-resistant backbone chemistry gaining share in battery enclosure applications. Chinese MIIT dual carbon goals accelerate adoption in domestic EV architectures where specific gravity targets below 1.2 intersect with chemical resistance requirements. EU workplace exposure limit tightening on styrene emissions compounds interest in low-VOC alternatives.
- Epoxy:Aerospace-grade systems commanding premium positioning through bisphenol-A epichlorohydrin synthesis pathways. Flame-smoke-toxicity certification under FAA and EASA protocols extends qualification timelines to 18-24 months.
- Synthetic Resin:Broad formulation category spanning modified polyester and hybrid chemistries for general industrial applications.
- Thermoplastic:Blended systems offering reprocessing flexibility at density reduction trade-offs versus thermoset alternatives.
- Phenolic:High-heat resistance chemistry for electrical insulation applications requiring arc track resistance.
Unsaturated Polyester handles the majority of throughput; Vinyl Ester is expanding most quickly on share.
Technology:
Equipment installed base and cycle time economics drive platform selection. Molders balance capital intensity against part complexity and annual volume requirements.
- Compression Molding:Mature platform dominating automotive panel production through matched-die tooling. German Tier-1 suppliers capture efficiency gains from faster cure chemistries reducing cycle times across Stuttgart and Wolfsburg manufacturing clusters. Tooling amortization favors annual volumes above 50,000 units.
- Transfer Molding:Closed-mold variant penetrating electrical encapsulation for 800V EV infrastructure components. Japanese and South Korean switchgear manufacturers miniaturize housing wall thicknesses below 2mm while maintaining IEC dielectric withstand requirements.
- Injection Molding:Emerging platform for complex geometries with flow limitations constraining traditional SMC. China-based compounders scale capacity for battery enclosure applications.
- Reaction Injection Molding:Low-pressure system for large-area parts with moderate structural requirements.
Compression Molding retains the dominant equipment base; Transfer Molding climbs the fastest on new installation share.
Application:
Surface finish requirements and load-bearing specifications determine microsphere loading limits and resin system selection. Each application tier imposes distinct qualification protocols on compounders.
- Electrical Components:Dielectric property preservation at reduced density drives hollow glass microsphere formulation optimization. Transfer molding variants enable thinner wall sections in switchgear and breaker housings without IEC withstand degradation.
- Aerospace Parts:Flame-smoke-toxicity certification creates margin concentration for epoxy formulations. FAA and EASA qualification protocols compress revenue recognition windows for specialty resin suppliers.
- Automotive Body Panels:Class A surface finish requirements sustain unsaturated polyester dominance. OEM paint shop compatibility demands constrain substrate diversification without guaranteed volume commitments.
- Industrial Equipment:General structural applications with moderate cosmetic requirements.
- Marine Components:Corrosion resistance and buoyancy specifications favor vinyl ester systems.
- Consumer Goods:Cost-sensitive applications with reduced structural performance thresholds.
- Sporting Goods:Weight reduction priorities in recreational equipment.
Electrical Components generates the highest volume throughput; Aerospace Parts shows the steepest expansion trajectory on qualification completion.
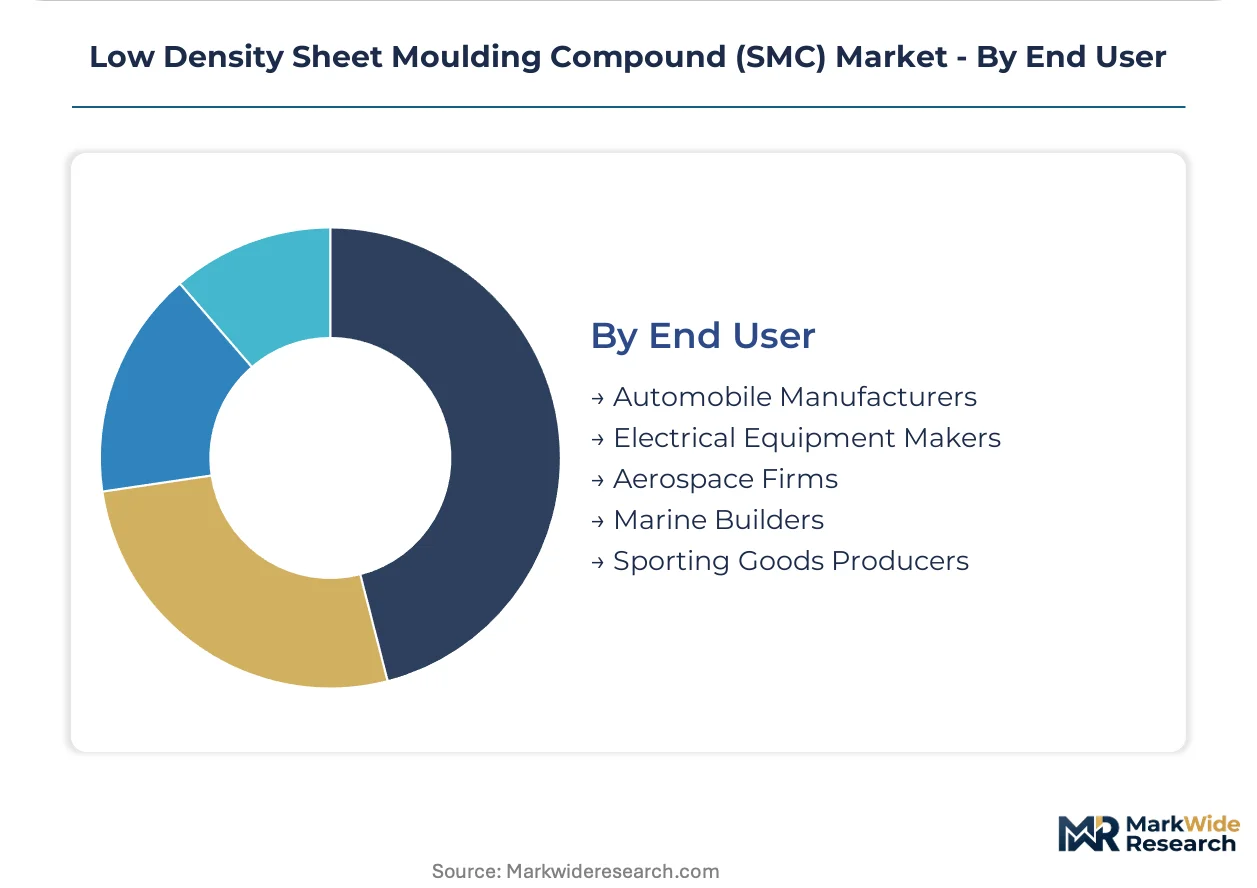
End User:
Buyer concentration and material qualification centralization reshape supplier access patterns. Tier-2 compounders face narrowing platform entry as procurement consolidates.
- Automobile Manufacturers:Centralized resin system approvals at Volkswagen, BMW, and Mercedes-Benz group level reduce approved supplier lists from twelve to four primary SMC sources per vehicle architecture. India PLI scheme automotive incentives attract regional compounding facility establishment.
- Electrical Equipment Makers:800V EV infrastructure buildout drives switchgear housing demand. IEC dielectric standards govern microsphere loading limits and wall thickness miniaturization.
- Aerospace Firms:Extended qualification timelines and flame-smoke-toxicity certification requirements favor established epoxy compounders with aerospace heritage.
- Marine Builders:Corrosion resistance specifications in hull and deck applications.
- Sporting Goods Producers:Weight-driven material selection with reduced regulatory compliance burden.
Automobile Manufacturers command the dominant procurement volume; Electrical Equipment Makers are gaining share fastest on EV infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates low-density SMC consumption in automotive Class A body panels, while China directs procurement toward battery enclosures and electrical infrastructure. The United States splits demand across aerospace qualification programs and commercial vehicle lightweighting. Japan and India represent emerging volume centers with distinct application profiles.
United States
EPA Corporate Average Fuel Economy standards compress material qualification timelines for stamped steel substitution in closure panels. The FAA maintains 18-24 month flame-smoke-toxicity certification protocols for epoxy SMC variants in commercial aerospace programs. Tier-1 suppliers in Michigan and Ohio manufacturing clusters capture tooling efficiency gains from faster cure chemistries.
Germany
Volkswagen, BMW, and Mercedes-Benz procurement teams centralize resin system approvals at the group level, reducing approved supplier lists from twelve to four primary sources per vehicle architecture. EU REACH workplace exposure limit tightening on styrene emissions accelerates validation of low-VOC vinyl ester alternatives. Stuttgart and Wolfsburg manufacturing clusters pilot closed-mold transfer systems ahead of anticipated 2027 regulatory thresholds.
China
MIIT dual carbon goals accelerate SMC adoption in domestic EV platforms with specific gravity targets below 1.2 for battery enclosure applications. GB standards and SAMR oversight govern monomer emissions and workplace exposure limits across compounding facilities. Local resin compounders in the Yangtze River Delta scale capacity for 800V EV infrastructure component supply.
Japan
METI industrial policy supports switchgear housing miniaturization for 800V EV infrastructure buildout. JIS standards govern dielectric property preservation at reduced density in electrical encapsulation applications. Manufacturers in the Chubu region adopt transfer molding variants enabling wall thickness reduction below 2mm while maintaining IEC withstand requirements.
India
PLI scheme automotive incentives attract SMC compounders to establish regional compounding facilities for domestic manufacturing-linked subsidies. BIS standards and CEA regulations frame material qualification protocols for electrical component applications. Maharashtra and Gujarat industrial corridors reduce landed cost disadvantages against metal stamping through localized supply chain development.
Low Density Sheet Moulding Compound (SMC) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into resin synthesis separating compounders from pure molders. The competitive landscape bifurcates between unsaturated polyester generalists serving automotive volume and epoxy specialists pursuing aerospace qualification pathways. Strategic moves concentrate on capacity expansion in China and India alongside portfolio diversification into vinyl ester alternatives.
Within the integrated leader tier, IDI Composites International and Polynt exemplify compounding heritage across multiple resin platforms. Teijin occupies a position among high-performance specialists targeting aerospace certification pathways. Menzolit GmbH and Lorenz represent European fabrication expertise with regional supply chain anchoring. Core Molding Technologies and Polytec Group sit within the automotive-focused molder tier, while Ningbo HAMC Group and Changzhou Huari New Material exemplify China-based capacity scaling for domestic EV platform supply.
| Leading Market Players |
|---|
| IDI Composites International |
| Polytec Group |
| Core Molding Technologies |
| Ningbo HAMC Group |
| Changzhou Huari New Material |
| Polynt |
| Menzolit GmbH |
| Lorenz |
| Teijin |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month aerospace qualification timelines concentrate pricing power among epoxy compounders with FAA and EASA flame-smoke-toxicity heritage, while automotive contract structures reward unsaturated polyester volume commitments with tooling amortization efficiencies. This lead-time asymmetry between certification tiers enables premium capture in aerospace segments and cost-competitive positioning in automotive Class A panel supply.
Pricing Analysis
Long-term offtake agreements dominate automotive procurement, with Volkswagen, BMW, and Mercedes-Benz embedding multi-year volume commitments into platform RFPs that lock in styrene-based unsaturated polyester pricing. Price differentiation rests on flame-smoke-toxicity certification tier and hollow glass microsphere loading precision, with aerospace-grade epoxy commanding substantial premiums over general industrial formulations. Cost compression in automotive tiers intensifies as Chinese compounders scale battery enclosure capacity below specific gravity 1.2 targets. Tier-2 molders exhibit highest price sensitivity due to paint line recalibration risks and guaranteed volume shortfalls, while aerospace primes accept premium positioning for qualification certainty.
Supply Chain Analysis
Forty-five-to-sixty day raw material inventory cycles expose formulators to benzene-derivative feedstock volatility, particularly styrene monomer swings that lack hedging instrument coverage. Supply concentrates in Germany, China, and the United States, with bisphenol-A epichlorohydrin chains anchored in Asian epoxy resin production. Raw material dependencies encompass styrene monomers, hollow glass microspheres, and vinyl ester resins. Single-source vulnerability runs through aerospace-grade epoxy certification pathways where regional production disruptions extend lead times unpredictably. Distribution feeds from compounding facilities through Tier-1 automotive suppliers and direct electrical equipment OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in low-density SMC are converging around centralized OEM qualification protocols that treat resin systems as architectural infrastructure rather than commodity inputs. Volkswagen's supplier list compression from twelve to four approved sources per vehicle architecture exemplifies this interoperability lock-in.
For Market Incumbents: Shield automotive market share through backward integration into hollow glass microsphere supply and accelerated vinyl ester validation ahead of EU REACH workplace exposure thresholds. Long-fiber thermoplastic substitution in structural applications threatens unsaturated polyester volume; defend through paint line compatibility guarantees and closed-mold transfer system investments that reduce styrene emissions below anticipated regulatory ceilings. For New Entrants and Emerging Players: Anchor in India's PLI scheme automotive corridor, where domestic manufacturing-linked subsidies reduce landed cost disadvantages against metal stamping. Battery enclosure applications for domestic EV platforms offer the most penetrable entry point, with specific gravity targets below 1.2 creating formulation differentiation opportunities. Pursue joint development agreements with Yangtze River Delta compounders to access MIIT dual carbon procurement channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming thermoset divisions that possess latent aerospace qualification infrastructure. Five-to-ten year viability hinges on EU Green Deal recycled content mandate compliance and circular economy certification adoption. Monitor FAA and EASA flame-smoke-toxicity approval completion rates as inflection indicators for specialty epoxy margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Polynt's captive supply of unsaturated polyester raw materials insulates margin from styrene volatility. |
| Closed-Mold Transfer System Deployment | German compounders in Stuttgart and Wolfsburg pilot low-VOC vinyl ester ahead of 2027 EU thresholds. |
| Aerospace Flame-Smoke-Toxicity Certification | Teijin's epoxy qualification pathway captures premium positioning through FAA and EASA protocol completion. |
| Regional Compounding Facility Establishment | India PLI scheme incentives attract capacity to Maharashtra and Gujarat industrial corridors. |
| Long-Term Automotive Platform Supply Agreement | Tier-1 suppliers lock in tooling amortization across Volkswagen, BMW, and Mercedes-Benz architectures. |
Research Methodology
The analysis maps unsaturated polyester, vinyl ester, and epoxy formulation sub-sectors, each validated through resin formulator technical directors, Tier-1 automotive procurement managers, electrical equipment OEM material engineers, and aerospace qualification specialists. Primary interview intelligence combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases enabled bottom-up and top-down triangulation across the value chain.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled resin chemistry, molding platform technology, end-use application tier, and regional production hub segmentation dimensions. CAGRs derived from regression analysis of historical capacity utilization, OEM platform launch schedules, and regulatory compliance timeline acceleration. Forecast inputs incorporated MIIT dual carbon policy implementation pace and EU REACH substance authorization sunset date transitions.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA Corporate Average Fuel Economy enforcement and EU CO2 fleet emission rule tightening; material deviation in automotive lightweighting program funding or styrene monomer supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Polyoxin Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Hypalon Market