
 Lithium Compound Market | 2026-2036
Lithium Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Compound Market Intelligence
UN 38.3 lithium battery testing certification is redrawing competitive boundaries for compound suppliers seeking downstream qualification. Albemarle Corporation leverages its integrated brine-to-cathode material pipeline across Chile and the United States to sustain long-term offtake agreements with Korean cathode makers. Ganfeng Lithium Co., Ltd. anchors its position through captive access to Australian spodumene concentrate and expanding hydroxide capacity in Jiangxi province.
Lithium compounds encompass chemically processed derivatives—principally carbonate, hydroxide, chloride, and specialized salts—refined from brine evaporation or hard-rock flotation to achieve purity thresholds exceeding 99.5% for battery applications, with hydroxide specifically enabling high-energy-density nickel-cobalt-manganese cathodes. Battery grade commands premium positioning as cathode producers enforce stricter impurity protocols for electric vehicle cells, while technical grade serves mature industrial lubricant and glass-ceramic markets with flatter margin trajectories. Energy storage applications represent an emerging demand vector as grid-scale battery deployments expand beyond automotive pull.
The EPA oversees domestic lithium extraction wastewater discharge under the Clean Water Act, while REACH and the EU Battery Regulation mandate carbon footprint disclosure and recycled content minimums for European-bound material. China's MEE enforces dual carbon compliance on new refining capacity, effectively limiting greenfield project approvals to ventures with renewable energy offtake. Stakeholders must track evolving cathode chemistry roadmaps and qualification timelines to align compound specifications with shifting OEM procurement criteria.
Market Dynamics
Automotive OEMs are consolidating cathode chemistry roadmaps around high-nickel NCM formulations, forcing lithium hydroxide specifications to tighten faster than incumbent refining capacity can adapt.
Growth Catalysts
- EU Battery Regulation:Mandated recycled content minimums and carbon footprint disclosure are redirecting European-bound supply toward qualified hydroxide producers with integrated brine assets.
- High-nickel cathode chemistries:NCM 811 and 9-series formulations require battery-grade lithium hydroxide with sub-100 ppm sodium specifications, locking in premium compound demand from Korean cathode makers.
- Chile's Atacama operations:Salar brine evaporation yields the lowest-cost lithium carbonate globally, sustaining cost-competitive feedstock for downstream hydroxide conversion.
Market Restraints
- Spodumene concentrate volatility:Australian hard-rock mining costs swing with diesel and labor inputs, transmitting margin pressure to Chinese hydroxide converters.
- Water scarcity in Chile:Salar brine extraction competes with agricultural and municipal water rights, constraining expansion permits under Chile's environmental courts.
- Direct lithium extraction:DLE technologies threaten to bypass conventional evaporation ponds, potentially obsoleting billions in sunk-cost brine infrastructure.
Strategic Opportunities
- Grid-scale energy storage:Utility-scale battery deployments outside automotive pull are creating parallel demand for technical-grade carbonate with relaxed purity thresholds.
- US Inflation Reduction Act:Critical mineral domestic content incentives are attracting refining investment to Texas and North Carolina chemical corridors.
- Solid-state battery electrolytes:Sulfide and oxide solid electrolytes require ultra-dry lithium salts, opening specialty compound specifications beyond conventional hydroxide.
Industry Challenges
- UN 38.3 certification timelines:New compound batches require 6-12 months of cell testing before cathode maker qualification, compressing effective contract windows.
- Process engineer scarcity:Brine chemistry and spodumene acid-roasting expertise concentrates among retiring Chilean and Australian operators, constraining greenfield project staffing.
- Legacy refinery retrofit costs:Converting carbonate-dominant plants to hydroxide output requires sulfuric acid handling upgrades and crystallizer circuit rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Compound Market |
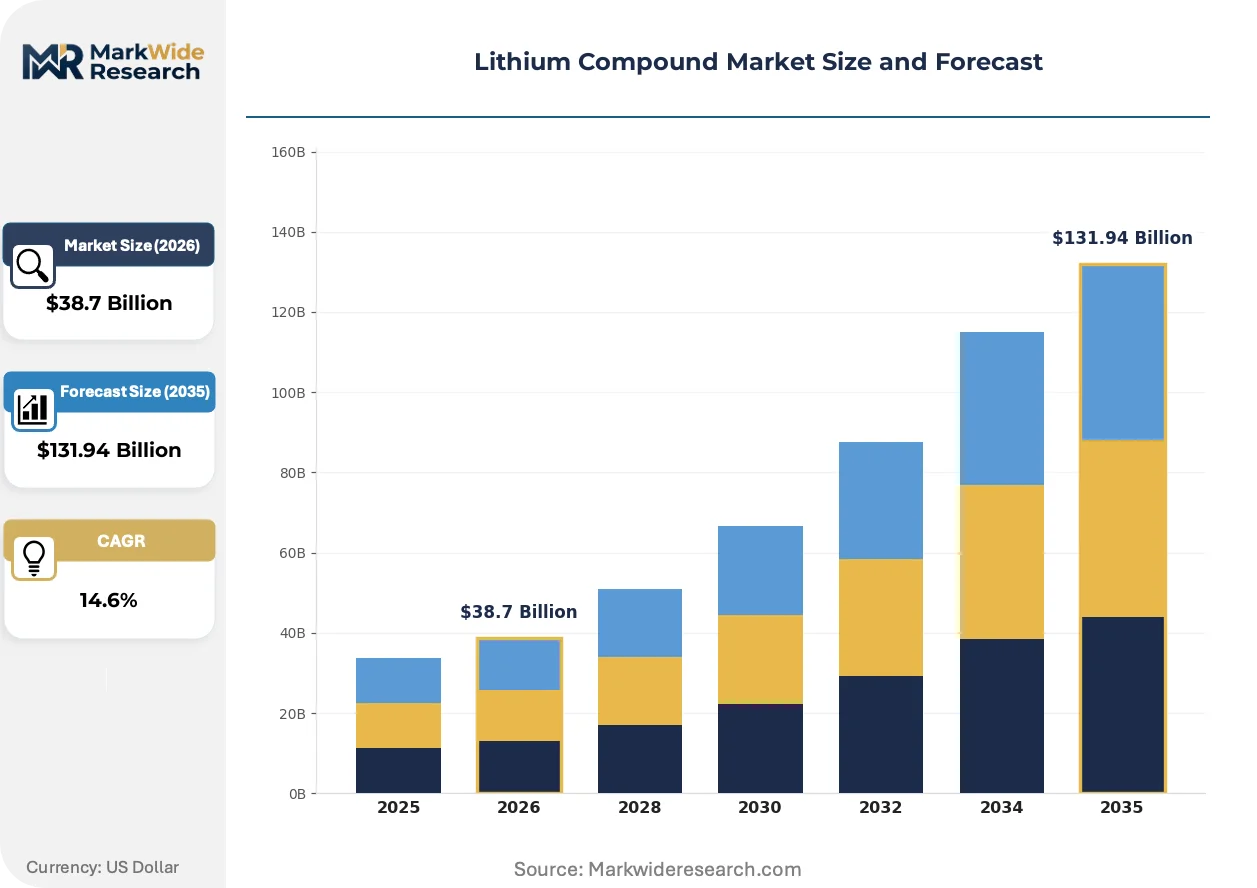
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $131.94 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Carbonate, Lithium Hydroxide, Lithium Chloride, Lithium Salts End Use Industry: Aerospace, Electronics, Automotive, Energy Storage Packaging Type: Bags, Drums, Bulk, Containers Grade: Technical Grade, Battery Grade, Pharmaceutical Grade, Industrial Grade |
| Companies Covered | Albemarle Corporation, Livent Corporation, Sociedad Química y Minera de Chile, Tianqi Lithium Corporation, Ganfeng Lithium Co., Ltd., FMC Corporation, Lithium Americas Corp., Neometals Ltd, Orocobre Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Compound Market Strategic Shifts & Innovations
Process intensification and direct shipping ore strategies are compressing the traditional mine-to-refinery timeline, while regulatory carbon accounting is embedding emissions tracking into compound specifications.
Direct lithium extraction using selective adsorbents and membrane technologies is supplanting multi-year solar evaporation in greenfield project designs. European cathode producers are piloting DLE-sourced hydroxide to meet EU Battery Regulation carbon thresholds. The technology is enabling brine developers to promise 90-day production cycles versus 18-24 months for conventional evaporation.
China's MEE dual carbon compliance framework is tightening wastewater discharge limits for Jiangxi province refineries. New hydroxide capacity approvals now require documented renewable energy offtake agreements. Korean cathode makers are responding by diversifying qualification programs toward Australian and Chilean sources with cleaner production profiles.
Automotive OEMs are consolidating supplier panels from 8-12 qualified compound sources to 3-4 strategic partners with captive upstream access. Long-term offtake contracts now span 5-7 years with fixed-volume, floating-price structures. This concentration is most visible in European and North American procurement offices managing Korean and Japanese cathode supply chains.
Lithium Compound Market Segmentation
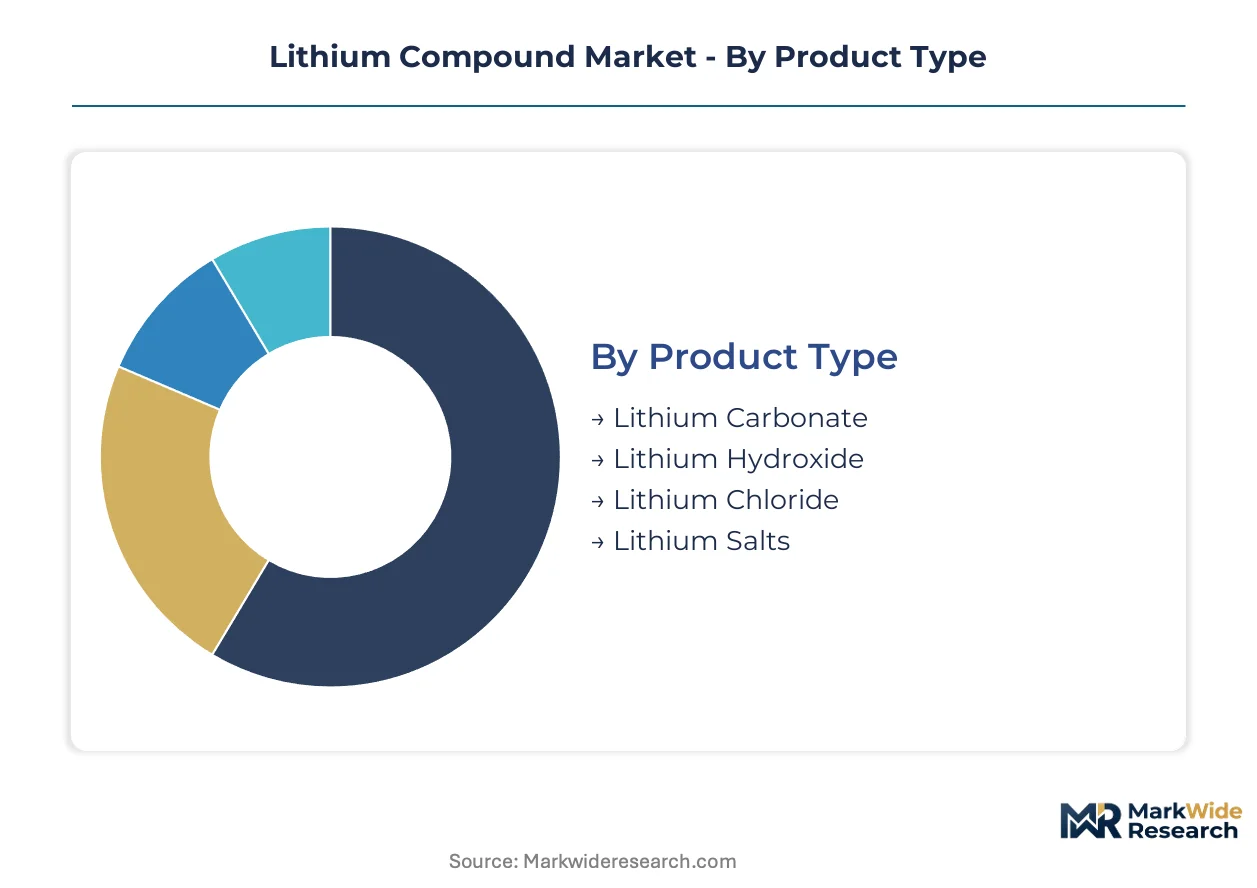
Lithium compound segmentation separates margin capture from volume throughput. Battery-grade hydroxide commands premium positioning against technical-grade carbonate, while packaging configurations determine logistics economics across brine-to-cathode supply chains.
Product Type:
Highest margins concentrate in battery-grade hydroxide where cathode qualification timelines create supply scarcity.
- Lithium Hydroxide:Monohydrate and anhydrous forms refined to sub-100 ppm sodium specifications enable NCM 811 and 9-series cathodes. Korean cathode makers in Gumi and Cheonan lock in multi-year offtake agreements with Chilean brine operators to secure qualified supply.
- Lithium Carbonate:Primary feedstock derived from Atacama salar evaporation or Australian spodumene acid roasting. Technical-grade carbonate serves industrial glass-ceramic and lubricant grease markets with flatter pricing trajectories than battery-grade derivatives.
- Lithium Chloride:Intermediate compound for lithium metal production and molten salt electrolytes. Chinese refineries in Jiangxi province dominate conversion capacity for specialty battery chemistry applications.
- Lithium Salts:Specialized derivatives including lithium bis(trifluoromethanesulfonyl)imide for electrolyte additives and lithium hexafluorophosphate precursor materials. Solid-state battery developers in Japan and Germany pilot sulfide and oxide electrolyte formulations requiring ultra-dry salt specifications.
The dominant share belongs to Lithium Carbonate, while Lithium Hydroxide is closing the gap fastest.
End Use Industry:
Application concentration determines purity thresholds and contract structures across downstream sectors.
- Automotive:Electric vehicle OEM procurement offices enforce UN 38.3 certification and carbon footprint disclosure under EU Battery Regulation. Long-term offtake contracts span 5-7 years with fixed-volume, floating-price mechanisms.
- Energy Storage:Utility-scale battery deployments outside automotive pull create parallel demand for technical-grade carbonate with relaxed purity thresholds. Grid operators in Texas and California prioritize cost efficiency over cathode-grade specifications.
- Electronics:Consumer device batteries and industrial power tools require mid-tier hydroxide specifications. Japanese electronics manufacturers maintain qualified supplier panels with 2-3 compound sources per cathode chemistry.
- Aerospace:Specialized thermal management systems and satellite battery applications demand ultra-high-purity lithium salts. NASA and ESA procurement specifications exceed standard battery-grade thresholds for mission-critical applications.
Automotive commands the largest volume position, though Energy Storage is expanding most quickly.
Packaging Type:
Logistics configuration shapes working capital requirements and contamination risk profiles.
- Bulk:Dedicated vessel and railcar shipments for integrated cathode plants with direct pipeline feed. Korean POSCO and LG Chem facilities at Gwangyang and Cheongju receive bulk hydroxide to minimize handling stages.
- Containers:ISO tank containers enable multimodal transport from Chilean Antofagasta port to European Rotterdam and Asian Busan terminals. Flexitank configurations reduce per-kilogram logistics costs for mid-volume cathode producers.
- Drums:Steel and fiber drums with nitrogen purging preserve moisture-sensitive hydroxide specifications. Qualified drum suppliers in China and Germany maintain UN-certified packaging for hazardous material air freight.
- Bags:Multi-layer laminated bags for technical-grade carbonate serving glass-ceramic and lubricant compounders. Lower barrier specifications accommodate shorter supply chains and faster inventory turnover.
Bulk shipments dominate integrated supply chains, while Container flexibility is gaining share fastest.
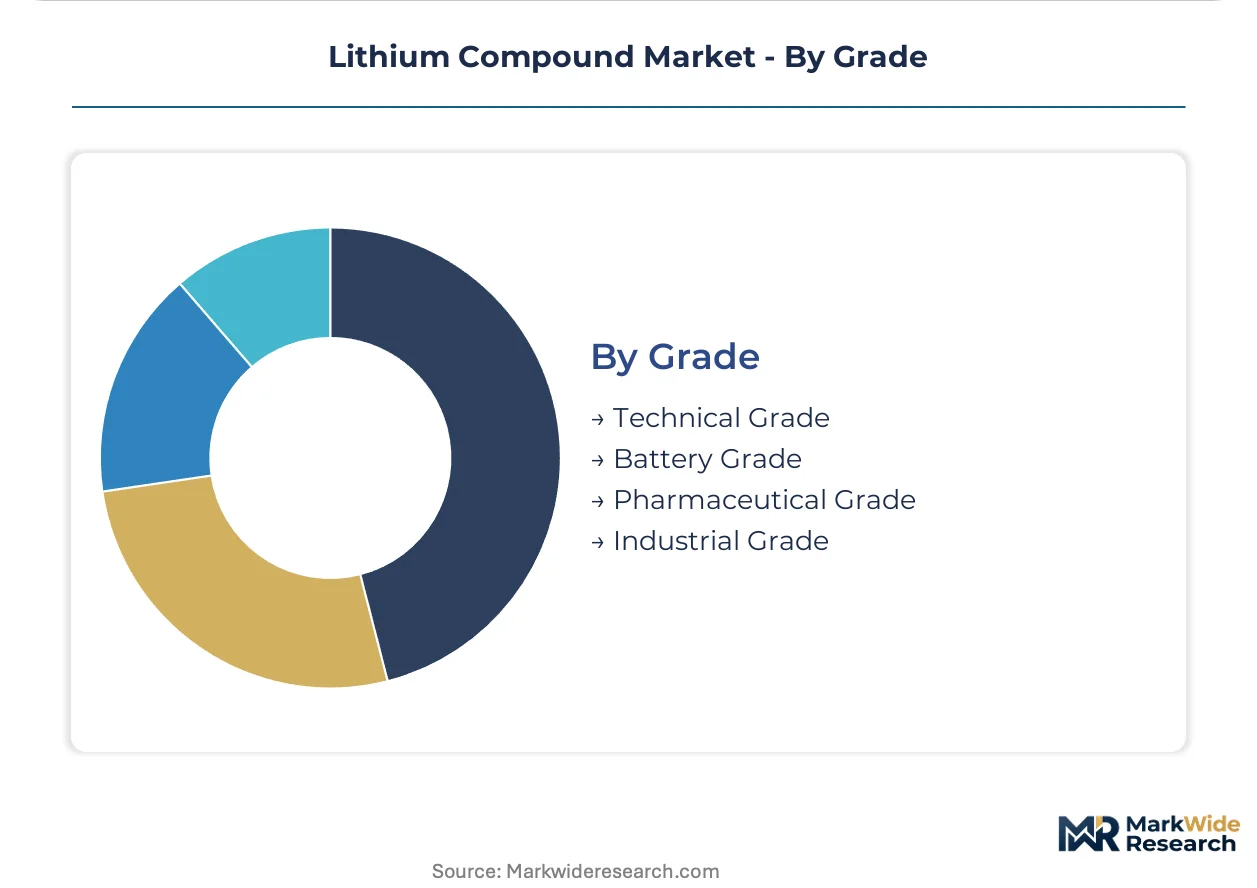
Grade:
Purity tiering creates three distinct margin bands with minimal crossover in procurement patterns.
- Battery Grade:Minimum 99.5% purity with strict impurity protocols for sodium, calcium, and magnesium. REACH and EU Battery Regulation carbon disclosure requirements redirect European-bound supply toward qualified producers with integrated brine assets.
- Technical Grade:99.0-99.5% purity serving mature industrial lubricant and glass-ceramic markets. China's GB standards and NMPA oversight apply less stringent thresholds than battery applications.
- Industrial Grade:Lower purity specifications for metallurgical fluxes and air treatment systems. Price-sensitive buyers in construction materials and chemical processing prioritize volume over refinement.
- Pharmaceutical Grade:USP and EP-compliant lithium carbonate for bipolar disorder treatment and medical device applications. FDA and EMA batch testing requirements create specialized qualification pathways distinct from battery supply chains.
Battery Grade holds the dominant share, with Technical Grade climbing the fastest in absolute tonnage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's critical mineral domestic content incentives are redirecting refining investment toward North American chemical corridors. Australian spodumene concentrate flows and Chilean brine evaporation operations anchor supply-side geography. Korean and Japanese cathode makers drive demand concentration through long-term offtake contracting.
Australia
Hard-rock spodumene mining in Western Australia's Greenbushes and Pilbara regions feeds Chinese hydroxide converters. The country's environmental protection frameworks govern tailings management and water licensing for lithium extraction. Perth-based mining services clusters support acid-roasting expertise concentrated among retiring operator cohorts.
Chile
Atacama salar brine evaporation yields the lowest-cost lithium carbonate globally for downstream hydroxide conversion. Chile's environmental courts constrain expansion permits through water rights competition with agricultural and municipal users. Antofagasta port infrastructure handles bulk shipments to Asian and European cathode plants.
China
Jiangxi province refineries process Australian spodumene concentrate into battery-grade hydroxide for Korean cathode makers. The MEE dual carbon compliance framework limits greenfield approvals to ventures with documented renewable energy offtake. Ganfeng Lithium anchors capacity expansion in the province's chemical processing corridors.
South Korea
Gumi and Cheonan cathode plants enforce UN 38.3 certification and sub-100 ppm sodium specifications on hydroxide suppliers. The MFDS oversees chemical safety in battery material processing. POSCO and LG Chem facilities at Gwangyang receive bulk hydroxide via dedicated pipeline feed to minimize handling stages.
United States
Texas and North Carolina chemical corridors attract refining investment under IRA critical mineral incentives. The EPA oversees wastewater discharge under the Clean Water Act for domestic extraction operations. Albemarle Corporation leverages integrated brine-to-cathode pipelines across Chile and domestic processing assets.
Lithium Compound Market Key Industry Players
Player mix skews toward integrated brine operators and Chinese hard-rock converters with captive concentrate access. Tiering separates qualified battery-grade suppliers from technical-grade commodity producers. Two strategic archetypes dominate: integrated upstream-downstream operators controlling salar or mine assets, and specialized hydroxide refiners dependent on spot concentrate markets. Competitive moves center on multi-year offtake contracting and qualification timeline compression through pre-certified compound batches.
Within the integrated operator tier, Albemarle Corporation and Sociedad Química y Minera de Chile exemplify the brine-to-cathode archetype with Chilean salar assets. Ganfeng Lithium Co., Ltd. occupies a parallel position among Chinese converters with Australian spodumene concentrate access and Jiangxi province hydroxide capacity. These three entities represent the supply concentration that automotive OEMs target in their supplier panel consolidation from 8-12 qualified sources toward 3-4 strategic partners.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Livent Corporation |
| Sociedad Química y Minera de Chile |
| Tianqi Lithium Corporation |
| Ganfeng Lithium Co., Ltd. |
| FMC Corporation |
| Lithium Americas Corp. |
| Neometals Ltd |
| Orocobre Limited |
| Others |
Cost & Logistics Intelligence
Six-to-twelve-month UN 38.3 certification timelines compress effective contract windows and amplify pricing power for qualified battery-grade hydroxide suppliers with captive brine or spodumene assets. This lead-time rigidity concentrates margin capture among integrated operators while forcing spot-market buyers into premium positions for unqualified material.
Pricing Analysis
Certification level creates the primary spread between battery-grade and technical-grade lithium compounds. Three-tier pricing structure across battery-grade hydroxide, technical-grade carbonate, and industrial-grade derivatives dominates contract structures. Pricing pressure stems from spodumene concentrate volatility transmitting margin compression to Chinese converters. Grid-scale energy storage buyers exhibit highest price sensitivity, while automotive OEM procurement offices prioritize qualification certainty over unit cost.
Supply Chain Analysis
Strategic stockpiling of Australian spodumene concentrate and Chilean carbonate feedstock dominates inventory strategy among Korean cathode makers seeking supply security. Supply concentrates in Chile's Atacama salar, Western Australia's Greenbushes-Pilbara belt, and Jiangxi province refineries. The chain draws from hard-rock mining inputs, brine evaporation infrastructure, and sulfuric acid roasting capacity. Single-source vulnerability runs through Chilean water rights constraints under environmental court oversight. Distribution runs through Antofagasta port bulk shipments and ISO tank container multimodal routes to Asian and European cathode plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized brine chemistry and spodumene acid-roasting expertise concentrates among retiring operator cohorts in Chile and Australia, constraining greenfield project staffing and amplifying acquisition premiums for qualified technical teams.
For Market Incumbents: Secure multi-year offtake contracts with Korean cathode makers before direct lithium extraction technologies mature and threaten conventional evaporation pond economics. Defend margin position by accelerating backward integration into renewable energy offtake agreements to satisfy China's MEE dual carbon compliance for Jiangxi province capacity expansions. For New Entrants and Emerging Players: Anchor in grid-scale energy storage applications where technical-grade carbonate specifications accommodate relaxed purity thresholds and faster qualification timelines. Target Texas and North Carolina chemical corridors under IRA critical mineral incentives, leveraging the US EPA's Clean Water Act framework as a regulatory entry pathway distinct from EU REACH complexity. For Investors and Strategic Acquirers: Long-term, this sits as a captive-asset play because automotive OEM supplier panel consolidation from 8-12 qualified sources toward 3-4 strategic partners concentrates offtake value among integrated brine-to-cathode operators. Watch direct lithium extraction commercialization rates as the inflection signal for obsolescence risk in conventional evaporation infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Korean cathode makers at Gumi and Cheonan lock in 5-7 year offtake contracts with Chilean brine operators. |
| Backward Integration | Automotive OEMs consolidate supplier panels toward partners with captive Australian spodumene or Chilean salar assets. |
| Green Manufacturing Transition | China's MEE dual carbon compliance limits Jiangxi province approvals to ventures with documented renewable energy offtake. |
| Capacity Expansion | Texas and North Carolina chemical corridors attract refining investment under IRA critical mineral domestic content incentives. |
| Joint Venture | European cathode producers pilot DLE-sourced hydroxide partnerships to meet EU Battery Regulation carbon thresholds. |
Research Approach
A standing panel of cathode plant procurement managers, brine operation technical directors, spodumene acid-roasting engineers, and lithium trading desk analysts provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings, Chilean environmental court dockets, and Chinese MEE discharge permit records. Bottom-up capacity modeling and top-down demand triangulation from electric vehicle production databases anchored volume estimates.
Consistency checks against external benchmarks validated output robustness across the projection horizon. The analytical framework modeled segmentation across product type, end-use industry, packaging configuration, and grade tier. CAGRs derived from slope analysis of annual volume trajectories, incorporating cathode chemistry roadmap shifts and regulatory qualification timeline compression as lithium-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained high-nickel cathode adoption and stable Chilean water rights adjudication; material deviation would warrant model refresh. Revision becomes warranted when direct lithium extraction capacity crosses commercial viability thresholds or EU Battery Regulation recycled content mandates accelerate ahead of qualified supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Conductive Plastic Compounds Market
Specialty Compounds
White Carbon Black Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Solketal Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Air-Laid Product Market