
 North America Green Buildings Market | 2026-2036
North America Green Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Green Buildings Market Insights
Canada's mass timber manufacturing corridor is fragmenting as domestic capacity expands alongside cross-border supply chains. Owens Corning anchors North American insulation supply through vertically integrated fiberglass operations. BASF SE competes in high-performance coatings and sealants for energy-efficient envelopes. Siemens leads building automation integration, leveraging digital twin platforms to optimize operational carbon.
Green buildings in North America are structures designed, constructed, and operated to minimize environmental impact through reduced energy consumption, lower water use, sustainable material sourcing, and improved indoor environmental quality, typically achieving performance thresholds of 30-50% less energy use than conventional code-compliant buildings. Their primary commercial purpose is to reduce operational carbon intensity while lowering lifecycle utility costs for owners and occupants. The certification level dimension stratifies market access, with LEED maintaining dominant share in commercial specifications while the Living Building Challenge captures premium margins in institutional and showcase projects. The construction method segment shows modular and pre-fabricated approaches gaining share as labor scarcity and waste reduction targets reshape project delivery economics.
The U.S. Environmental Protection Agency Energy Star program and the Department of Energy building codes establish baseline efficiency thresholds that shape product qualification and project financing access across the United States. Canada's National Energy Code for Buildings and provincial adaptations in British Columbia and Ontario create comparable compliance ladders that drive specification upgrades. Stakeholders must monitor evolving stringency in municipal reach codes and green building ordinances as these local layers increasingly determine project feasibility ahead of national minimums.
Market Dynamics
Portfolio decarbonization mandates from Fortune 500 corporate real estate divisions are compressing payback-period thresholds for certified retrofits, forcing building owners to front-load capital into envelope upgrades and on-site generation rather than staged improvements.
Growth Catalysts
- California Title 24:The state's energy code revisions mandate solar-ready construction and demand-responsive controls, compelling developers in Los Angeles and San Francisco corridors to specify integrated building systems.
- Mass timber fabrication:Cross-laminated timber production capacity in British Columbia and the US Pacific Northwest is expanding, lowering material lead times for mid-rise commercial and institutional projects.
- Corporate net-zero commitments:Lease renewal negotiations in Manhattan, Chicago, and Toronto now routinely require LEED Gold or equivalent certification as a baseline occupancy condition.
Market Restraints
- High-performance glazing supply:Vacuum-insulated and electrochromic glass fabrication concentrates in a handful of European and Asian suppliers, exposing North American projects to shipping cost volatility and extended lead times.
- Skilled installer scarcity:Air-sealing contractors certified for Passive House-level envelope performance remain concentrated in coastal metropolitan markets, limiting project feasibility in secondary cities.
- Utility interconnection queues:On-site solar and battery storage projects face 12-24 month delays in Texas, California, and New York ISO territories, compressing projected returns.
Strategic Opportunities
- Midwestern industrial retrofits:Aging manufacturing and logistics facilities across Ohio, Michigan, and Illinois present uncaptured volume for deep energy retrofits as ESG-linked financing expands.
- Grid-interactive efficient buildings:Convergence of building automation systems with utility demand-response programs creates revenue streams from thermal mass and battery dispatch.
- Federal Inflation Reduction Act:Section 179D deductions and 48E clean electricity credits are restructuring project finance, enabling ownership models that transfer tax benefits to operating partners.
Industry Challenges
- Commissioning agent shortage:Certified commissioning professionals capable of integrated systems verification remain scarce relative to project pipeline growth in major metropolitan markets.
- Multifamily affordability tension:Green certification cost premiums collide with rent-stabilized financing constraints in New York and California, forcing trade-offs between performance targets and unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Green Buildings Market |
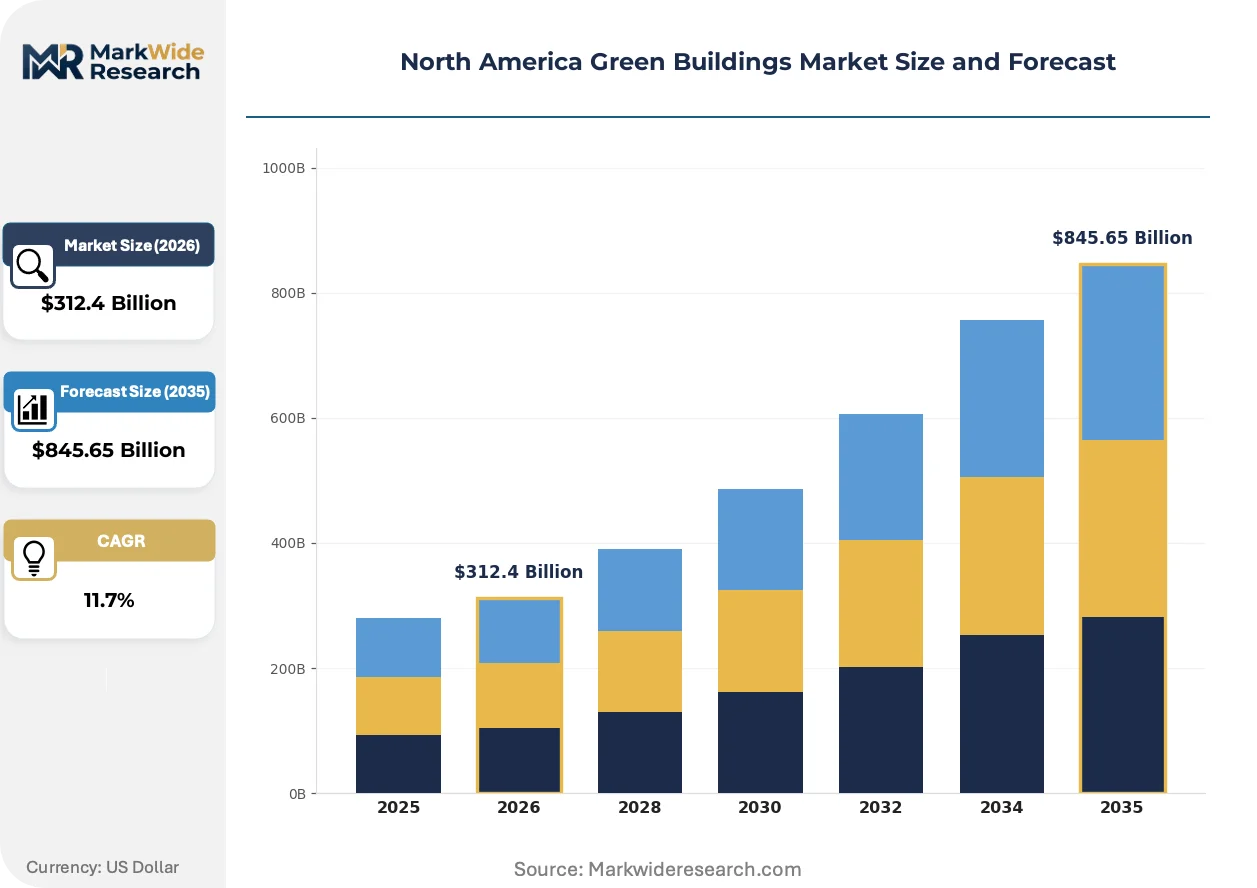
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $845.65 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Institutional, Industrial Construction Method: Traditional, Modular, Pre-fabricated, Hybrid Energy Source: Solar, Wind, Biomass, Geothermal Certification Level: LEED, BREEAM, Green Globes, Living Building Challenge |
| Companies Covered | PPG Industries, BASF SE, Owens Corning, Amvic Inc., Kingspan Group, Forbo International SA, Siemens, Interface Inc., Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Green Buildings Market Trends and Innovations
Digital twin platforms are compressing the feedback loop between design intent and operational performance, enabling real-time calibration of building systems against energy models rather than post-occupancy remediation.
Electrochromic glazing is hybridizing static and dynamic solar control. Corporate headquarters and healthcare facilities in California and New York are specifying these systems at accelerating rates. The technology is hybridizing conventional HVAC load profiles, enabling downsized mechanical plant specifications and shifting capital allocation toward envelope-first strategies.
The US Department of Energy's Better Buildings Initiative and evolving ASHRAE 90.1 standards are ratcheting baseline efficiency thresholds. Equipment manufacturers must recalibrate product lines to maintain qualification for federal and utility incentive programs. Commercial new construction in Texas and Florida is responding fastest, driven by utility rebate structures and insurer risk-pricing adjustments.
Tenant improvement allowances are increasingly tied to measured energy performance rather than installed equipment specifications. Landlords in Seattle, Vancouver, and Denver are replacing prescriptive allowance schedules with outcome-based reimbursement tied to twelve-month utility data. This restructuring concentrates risk on contractors and commissioning agents while transferring operational upside to occupants.
North America Green Buildings Market Segmentation
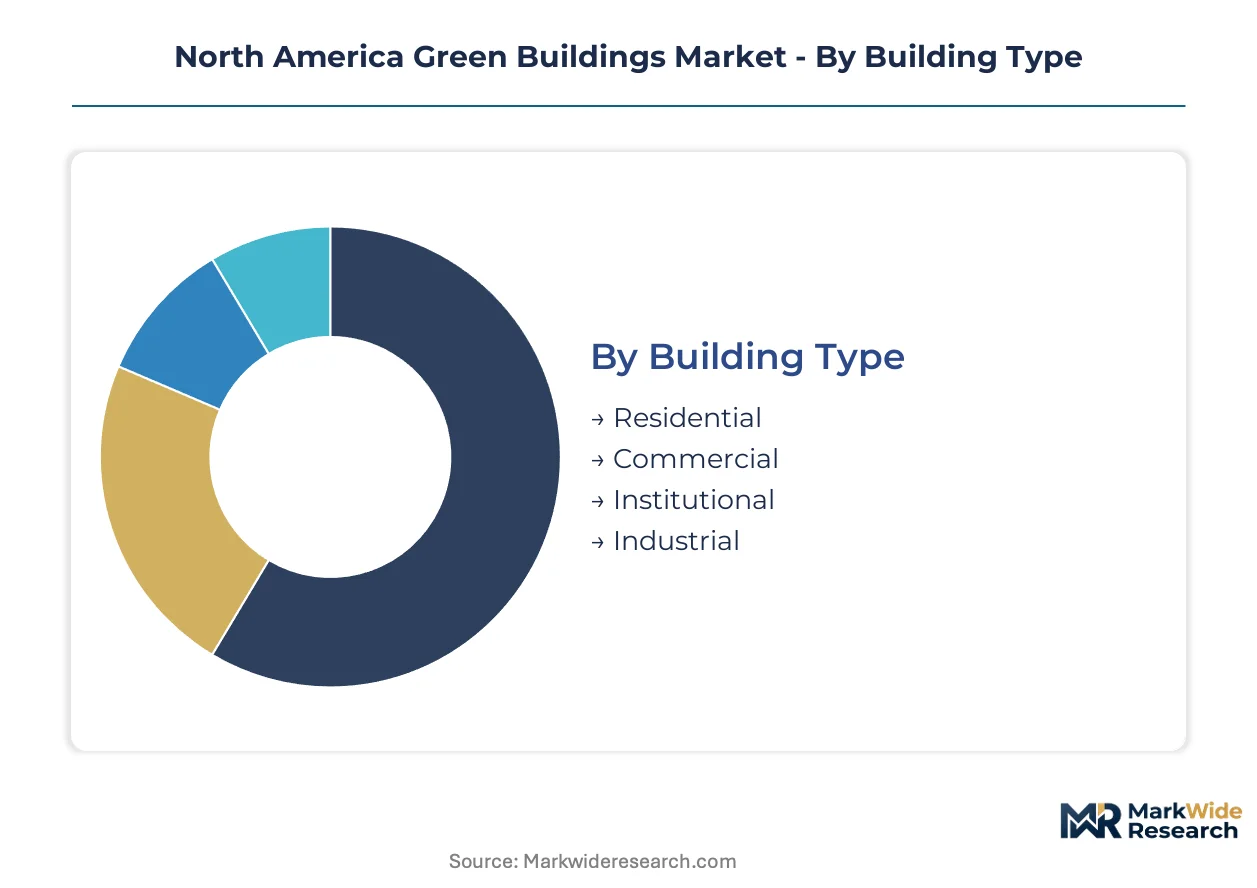
Segmentation in the North America Green Buildings Market reveals distinct capital cycles and specification patterns across building types, construction methods, energy sources, and certification tiers. Each dimension carries different payback horizons and regulatory exposure that reshape procurement priorities for developers and portfolio managers.
Building Type:
Commercial projects turn over fastest at 5-7 year capital refresh cycles, while institutional buildings stretch to 25-40 year horizons with bond-financed construction timelines.
- Residential:Multifamily developers in Vancouver, Toronto, and Seattle are specifying Passive House envelopes to meet municipal net-zero readiness codes. Rent-stabilized financing constraints in New York and California force trade-offs between performance targets and unit economics.
- Commercial:Corporate office portfolios across Manhattan, Chicago, and Los Angeles are accelerating certified retrofits as Fortune 500 decarbonization mandates tighten lease renewal standards. Speculative office construction in Texas and Florida responds fastest to utility rebate structures.
- Institutional:Universities and hospital systems anchor long-dated demand for Living Building Challenge certification in showcase projects.
- Industrial:Aging logistics facilities across Ohio, Michigan, and Illinois present uncaptured volume for deep energy retrofits as ESG-linked financing expands.
Commercial anchors the volume base while industrial retrofits gain share at the steepest rate.
Construction Method:
Cost tier stratification separates premium factory-controlled approaches from field-built alternatives, with labor scarcity driving specification shifts toward capital-intensive methods that compress site schedules.
- Traditional:Stick-built construction retains dominant share in single-family residential and custom commercial projects where design flexibility outweighs schedule pressure. Skilled trades scarcity in secondary markets limits envelope performance consistency.
- Modular:Volumetric units fabricated in controlled environments achieve tighter air-sealing and waste reduction targets. Projects in California and British Columbia specify modular for mid-rise multifamily to meet aggressive Title 24 and BC Energy Step Code timelines.
- Pre-fabricated:Panelized wall and roof systems reduce site labor hours by 30-50% in union jurisdictions.
- Hybrid:Blends structural steel or mass timber frames with pre-fabricated envelope panels.
Traditional construction retains volume leadership while modular approaches climb the fastest as labor markets tighten.
Energy Source:
Application context determines technology selection, with on-site generation favoring solar for distributed commercial rooftops while district-scale systems in institutional campuses tap geothermal and biomass.
- Solar:Photovoltaic arrays dominate new commercial construction in California, Texas, and Florida where utility interconnection queues, despite 12-24 month delays, still outperform alternative permitting pathways. Section 48E credits restructure project finance toward ownership models that transfer tax benefits to operating partners.
- Geothermal:Ground-source heat pumps concentrate in institutional and educational campuses with land availability for borefield installation. The technology avoids utility interconnection exposure entirely.
- Wind:Small-scale turbines supplement solar in rural commercial and industrial settings with adequate setback clearance.
- Biomass:Combined heat and power systems serve forest products industry facilities in the Pacific Northwest with captive feedstock access.
Solar anchors the volume base while geothermal gains share at the steepest rate among institutional developers seeking interconnection certainty.
Certification Level:
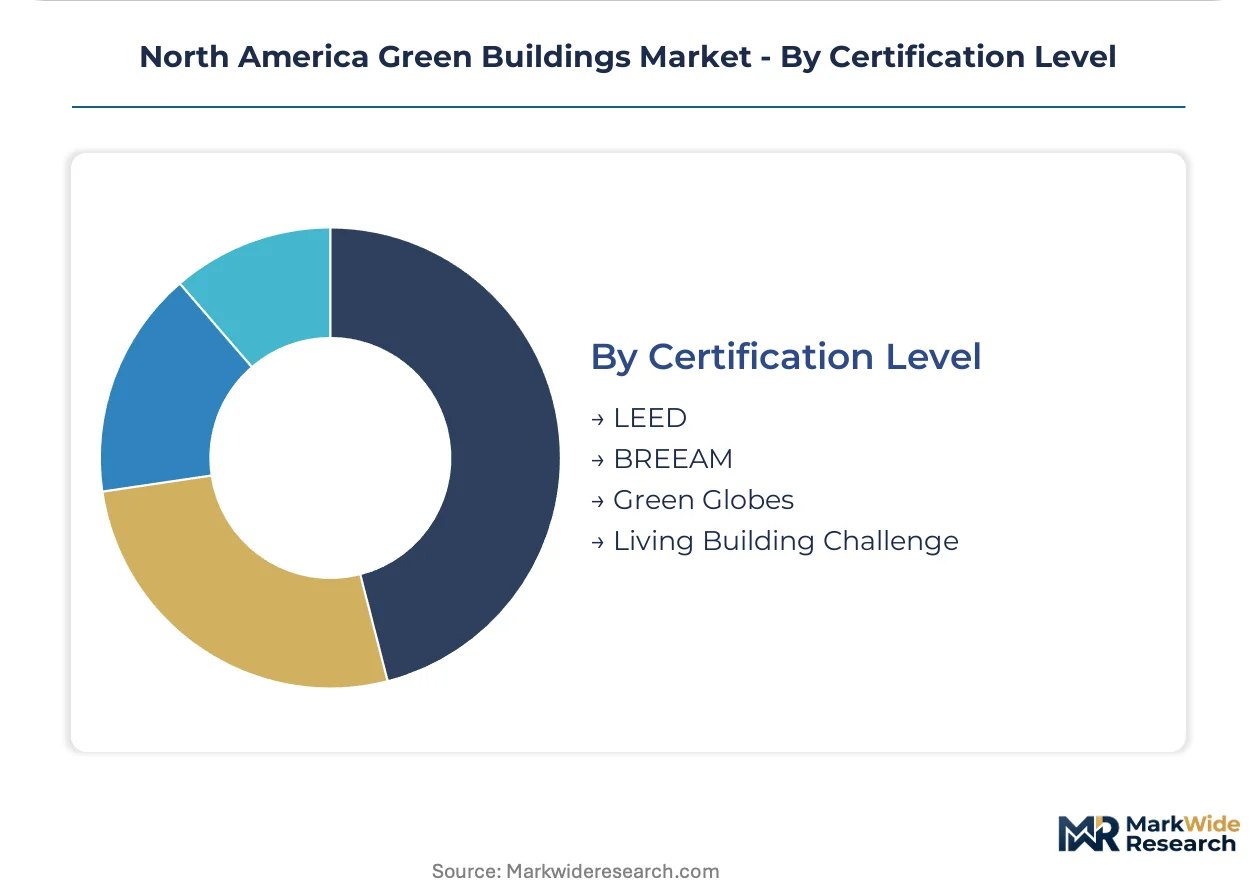
Margin tier separates baseline compliance from premium positioning, with LEED maintaining specification ubiquity while Living Building Challenge commands 15-25% construction cost premiums for showcase outcomes.
- LEED:The US Green Building Council's rating system maintains dominant share in commercial specifications across the United States, with Gold certification now a baseline occupancy condition in Manhattan, Chicago, and Toronto lease negotiations. Version 4.1 updates emphasize operational carbon and embodied carbon reporting.
- Living Building Challenge:The International Living Future Institute's standard captures premium margins in institutional and corporate headquarters projects with net-positive energy and water mandates. Certification requires 12-month performance verification post-occupancy.
- BREEAM:The UK-originated system retains niche presence in multinational corporate portfolios with European parent companies.
- Green Globes:The Green Building Initiative's alternative offers streamlined documentation for industrial and retail projects seeking cost-efficient third-party verification.
LEED anchors the volume base while Living Building Challenge gains share at the steepest rate among institutional clients with endowment-funded capital programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass timber fabrication capacity concentrates in the Pacific Northwest while corporate decarbonization mandates drive specification intensity across major metropolitan corridors. The United States dominates project volume, though Canadian urban centers and Mexican industrial zones present distinct regulatory and capital dynamics.
United States
California's Title 24 energy code revisions mandate solar-ready construction and demand-responsive controls in Los Angeles and San Francisco corridors. The EPA Energy Star program and Department of Energy building codes establish baseline efficiency thresholds that shape product qualification and project financing access nationwide. Corporate office portfolios in Manhattan, Chicago, and Seattle accelerate certified retrofits as Fortune 500 lease negotiations now require LEED Gold certification.
Canada
British Columbia and Ontario lead multifamily developers specifying Passive House envelopes to meet provincial net-zero readiness codes. The National Energy Code for Buildings and provincial adaptations create compliance ladders that drive specification upgrades across Vancouver and Toronto. Cross-laminated timber production capacity in the Pacific Northwest expands, lowering material lead times for mid-rise commercial and institutional projects.
Mexico
Industrial manufacturing and logistics facilities near the US border present uncaptured volume for energy efficiency upgrades as nearshoring accelerates. Federal energy efficiency standards and state-level building codes in Nuevo León and Baja California establish emerging compliance frameworks. Monterrey and Tijuana industrial corridors attract speculative green building investment from multinational corporate real estate divisions.
North America Green Buildings Market Competitive Landscape
Material suppliers and building systems integrators split the market along envelope-versus-automation specialization lines. The vendor base organizes around three strategic archetypes: vertically integrated insulation and cladding manufacturers, specialty coatings and sealants formulators, and digital building automation platforms. Consolidation pressure runs through fiberglass and mass timber supply chains while partnership networks dominate smart building integration.
Within the building materials tier, Owens Corning anchors North American insulation supply through captive fiberglass operations, BASF SE competes in high-performance coatings for energy-efficient envelopes, and Siemens occupies the automation-integration position with digital twin platforms. These three exemplify the segmentation between passive envelope performance and active operational optimization.
| Leading Market Players |
|---|
| PPG Industries |
| BASF SE |
| Owens Corning |
| Amvic Inc. |
| Kingspan Group |
| Forbo International SA |
| Siemens |
| Interface Inc. |
| Sika AG |
| Others |
Pricing and Supply Chain Analysis
The Vancouver-Seattle freight corridor's timber and insulation logistics costs cascade through envelope system pricing, concentrating margin capture among vertically integrated fiberglass suppliers while forcing project developers toward modular procurement to offset volatile glazing imports from European and Asian fabrication centers.
Pricing Analysis
California Title 24 dictates the pricing tier structure across commercial new construction, with three-tier pricing structure across premium, standard, and economy levels separating Living Building Challenge showcase projects from baseline LEED Silver compliance and speculative code-minimum development. Certification level and geographic delivery cost drive price differentiation, with Passive House-level envelope components commanding substantial premiums in coastal metropolitan markets. Cost compression in high-performance glazing is intensifying because vacuum-insulated and electrochromic glass fabrication concentrates overseas. Speculative developers in Texas and Florida exhibit highest price sensitivity, while institutional endowments in Manhattan and Toronto demonstrate lowest sensitivity due to long-dated capital horizons.
Supply Chain Analysis
Cross-laminated timber feedstock draws from British Columbia, the US Pacific Northwest, and emerging Great Lakes production zones, with fiberglass insulation sourcing from captive North American smelters and chemical precursors anchored in Gulf Coast petrochemical corridors. Raw material dependencies center on timber harvest cycles, glass silica purity grades, and blowing agent chemical formulations. Single-source vulnerability in electrochromic glazing fabrication exposes projects to shipping cost volatility. Distribution runs through regional building material distributors serving metropolitan construction corridors, with direct-to-project relationships gaining share for mass timber and modular envelope systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Green Buildings Market is recovering from cyclical lows in speculative construction starts, with corporate net-zero lease mandates and Inflation Reduction Act tax credit monetization creating durable demand visibility across the analysis window.
For Market Incumbents: Build certification moats around Living Building Challenge and Passive House consulting capabilities to defend against emerging automation-platform entrants. Deepen backward integration into mass timber fabrication in the Pacific Northwest and expand commissioning agent training pipelines to address verified scarcity. Channel control through exclusive distributor relationships for high-performance envelope systems protects margin position in LEED Gold-specified projects.
For New Entrants and Emerging Players: Secondary Midwestern cities present the most penetrable geography for air-sealing contractor networks and modular fabrication facilities, with aging industrial stock across Ohio, Michigan, and Illinois offering uncaptured retrofit volume. Target mid-rise multifamily developers in rent-stabilized jurisdictions seeking Passive House compliance without premium cost structures. Partner with regional banks offering ESG-linked construction financing to secure project pipeline access ahead of established competitors.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates' non-core building coatings divisions, with specialty sealants and high-performance paint formulations offering bolt-on growth to insulation and envelope platforms. Long-term viability hinges on regulatory ratchet mechanics in California, New York, and Canadian provincial codes sustaining specification upgrade cycles. Monitor municipal reach code adoption velocity across Sun Belt metropolitan areas as the inflection indicator for geographic demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Mass Timber Capacity Expansion | Pacific Northwest production growth shortens lead times for British Columbia and Seattle corridor developers. |
| Digital Twin Platform Integration | Siemens and automation vendors compress feedback loops between design intent and operational carbon performance. |
| Commissioning Agent Certification Pipeline | Training investments address scarcity constraining project feasibility in secondary metropolitan markets. |
| ESG-Linked Financing Partnerships | Regional bank alliances unlock Midwestern industrial retrofit volume as bond market access expands. |
| Electrochromic Glazing Supply Agreement | Long-term offtake contracts with European and Asian fabricators mitigate interconnection queue exposure. |
Research Methodology
The analysis maps commercial office retrofits, multifamily new construction, institutional showcase projects, and industrial logistics facilities, each validated through conversations with real estate portfolio managers, envelope system procurement leads, commissioning agents, and municipal building code officials. Primary interviews with industry stakeholders combine with secondary validation against Department of Energy building code filings, EPA Energy Star qualification databases, USGBC LEED project registries, and provincial energy code adaptations in British Columbia and Ontario. Bottom-up project pipeline aggregation and top-down construction spending forecasts undergo triangulation to resolve volume estimates.
Assumptions regarding Title 24 stringency trajectory, Inflation Reduction Act credit monetization mechanics, and corporate net-zero commitment durability remained fixed across scenarios, while timber harvest cycle volatility and utility interconnection queue lengths varied. Segmentation dimensions modeled span building type, construction method, energy source, and certification level, with regional regulatory cluster and labor market tightness as additional industry-specific dimensions. CAGRs derive from fitted growth curves against historical construction permit data and forward-looking lease negotiation standards, incorporating mass timber production capacity buildout schedules and electrochromic glazing technology cost curves as forecast inputs.
Practitioners should monitor municipal reach code adoption, utility interconnection queue clearance rates, and mass timber fabrication capacity utilization for early signals of forecast revision. Cross-checking against Dodge Construction Network permit data and CBRE lease transaction databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Building Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Green Rebar Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
Solar Frames Market
Green Building Materials
Green Silica Market
Green Building Materials
GCC Green Cement Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Green Cement Market