
 United States Green Cement Market | 2026-2036
United States Green Cement Market Size, Share, and Industry Trends Forecast 2026-2036
United States Green Cement Market Intelligence
The Inflation Reduction Act is consolidating the cost-of-entry calculus for domestic green cement producers. CarbonCure Technologies Inc. leverages its CO₂ injection platform to differentiate across precast and ready-mix channels. Heidelberg Materials anchors its position through backward integration into alternative fuel and clinker substitution supply chains. Solidia Technologies competes on a chemically distinct curing pathway that reduces process emissions without requiring wholesale kiln redesign.
United States green cement denotes hydraulic binders manufactured with reduced clinker content, supplementary cementitious materials such as fly ash or blast furnace slag, or novel chemistries like geopolymers that achieve compressive strengths comparable to Portland cement while lowering embodied carbon. These formulations serve structural and non-structural applications where lifecycle carbon accounting, LEED certification thresholds, or owner-mandated environmental product declarations govern material selection. Fly ash cement occupies the largest existing volume pool due to decades of ASTM C618 compliance and established supply relationships with coal-dependent power generators. Geopolymer cement represents the fastest-growing structural category as state DOTs in California and New York draft performance-based specifications that decouple approval from prescriptive clinker limits. Low-carbon cement concentrates margin pools in infrastructure prequalification programs where sole-source exemptions protect incumbent blenders.
The EPA oversees greenhouse gas reporting under Subpart H of the Mandatory Reporting Rule, while OSHA enforces silica exposure limits that affect slag grinding and handling operations; the Buy Clean Initiative from the General Services Administration embeds embodied carbon thresholds directly into federal construction procurement. State-level action supplements federal frameworks, with California's Department of General Services and New York's Climate Leadership and Community Protection Act imposing progressively tighter emissions benchmarks on public works concrete. Stakeholders must monitor whether emerging state low-carbon material standards fragment into incompatible compliance regimes or coalesce around a unified federal embodied carbon methodology.
Market Dynamics
Federal procurement mandates under the Buy Clean Initiative are compressing specification timelines for public infrastructure concrete, forcing blenders to requalify low-carbon formulations ahead of traditional ASTM C150 compliance cycles.
Growth Catalysts
- Buy Clean Initiative:Federal embodied carbon thresholds now govern GSA construction contracts, pulling fly ash and slag blends into highway and bridge specifications.
- California DOT performance specs:State-level decoupling of approval from clinker content limits accelerates geopolymer adoption in structural precast applications.
- Coal plant retirement wave:Utilities in Texas and the Midwest are locking in long-term fly ash supply agreements with cement blenders before ash pond closures.
Market Restraints
- Slag supply concentration:Domestic blast furnace slag output depends on integrated steel mill locations in Indiana and Ohio, creating regional availability gaps.
- Input cost volatility:Natural gas price swings directly impact the economics of calcined clay activation for LC3 formulations.
- Silica exposure limits:OSHA's revised permissible exposure levels for respirable crystalline silica add capital burden to slag grinding and handling operations.
Strategic Opportunities
- Pacific Northwest multifamily housing:Seattle and Portland embodied carbon ordinances create first-mover advantage for low-carbon mix suppliers in residential verticals.
- Carbon utilization convergence:CO₂ mineralization platforms paired with ready-mix batching systems open revenue streams from industrial emissions capture.
- Florida resiliency codes:Hurricane-resistant construction standards in coastal counties are incorporating lifecycle carbon metrics into material selection criteria.
Industry Challenges
- EPD certification timelines:Third-party verification for environmental product declarations currently spans 8-14 months, delaying prequalification for federal projects.
- Geopolymer skill gaps:Field crews and specifying engineers lack training in mix design and curing protocols for alkali-activated binders.
- Legacy batch plant retrofit costs:Existing ready-mix infrastructure requires silo segregation and quality control upgrades to handle SCM-heavy blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Green Cement Market |
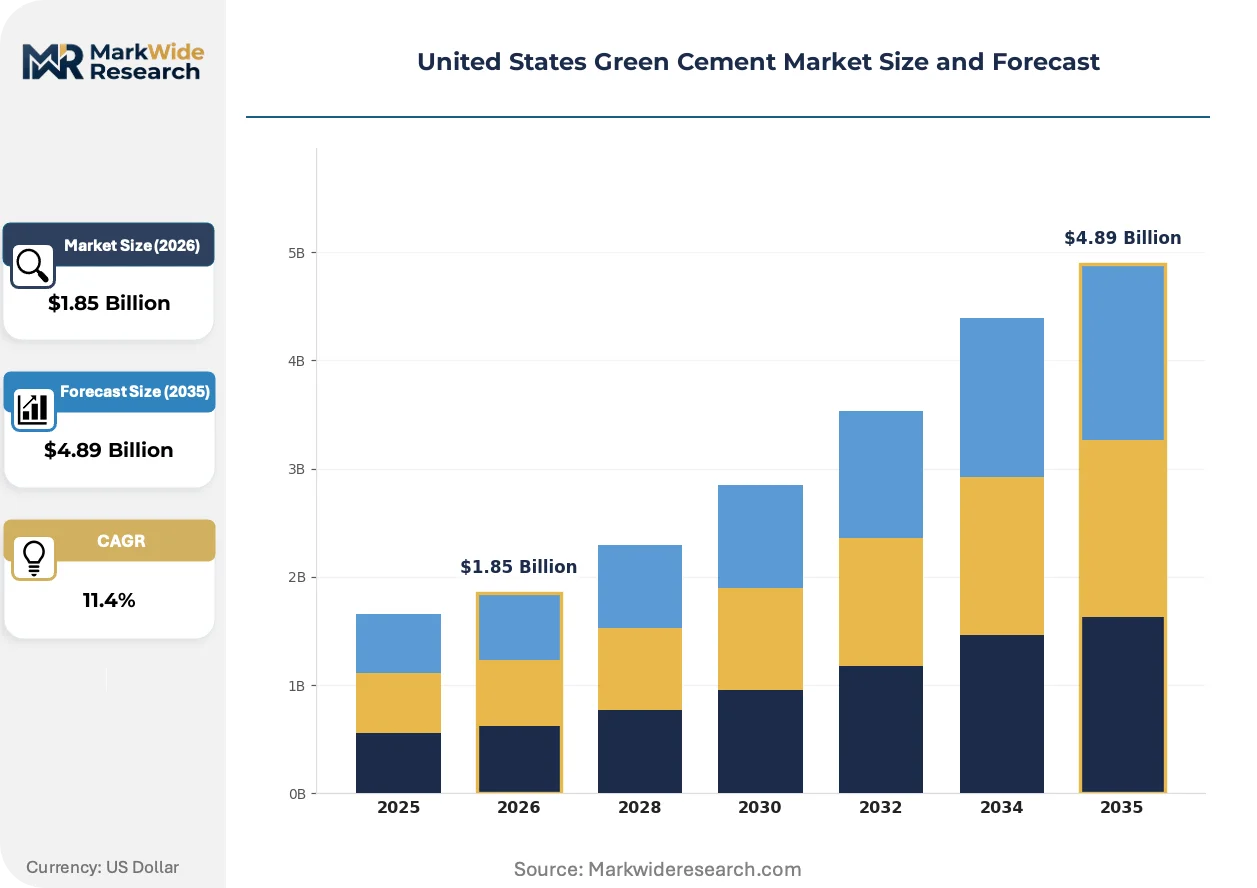
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Carbon Cement, Fly Ash Cement, Recycled Aggregates Cement, Geopolymer Cement End User: Residential Construction, Commercial Buildings, Infrastructure Projects, Industrial Applications Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale Suppliers Application: Road Construction, Bridge Construction, Precast Concrete, Sustainable Infrastructure |
| Companies Covered | LafargeHolcim, CEMEX, CRH plc, Calera Corporation, CarbonCure Technologies Inc., Heidelberg Materials, Holcim, Votorantim Cimentos, Solidia Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Green Cement Market Strategic Shifts & Innovations
Process digitization and chemistry diversification are compressing the gap between laboratory formulation and field-scale deployment of low-carbon binders.
CO₂ injection systems integrated at the ready-mix plant are automating the mineralization of fresh concrete, locking anthropogenic carbon into calcium carbonate formations during early hydration. State DOTs in New York and California are piloting these systems on highway paving contracts. The technology is automating quality control documentation for carbon accounting, reducing manual testing overhead that previously slowed specification approval.
The EPA's pending expansion of Subpart H greenhouse gas reporting to cover downstream concrete products is tightening measurement requirements across the value chain. Blenders must now install continuous emissions monitoring at kiln and grinding operations. Small regional producers in the Midwest are consolidating to share compliance infrastructure costs.
Design-build firms are bundling material procurement with carbon performance guarantees, shifting risk from project owners to concrete suppliers. This model is displacing traditional low-bid awarding on federal courthouse and VA hospital projects. Texas and Florida transportation departments are piloting similar outcome-based specifications for bridge deck replacements.
United States Green Cement Market Segmentation
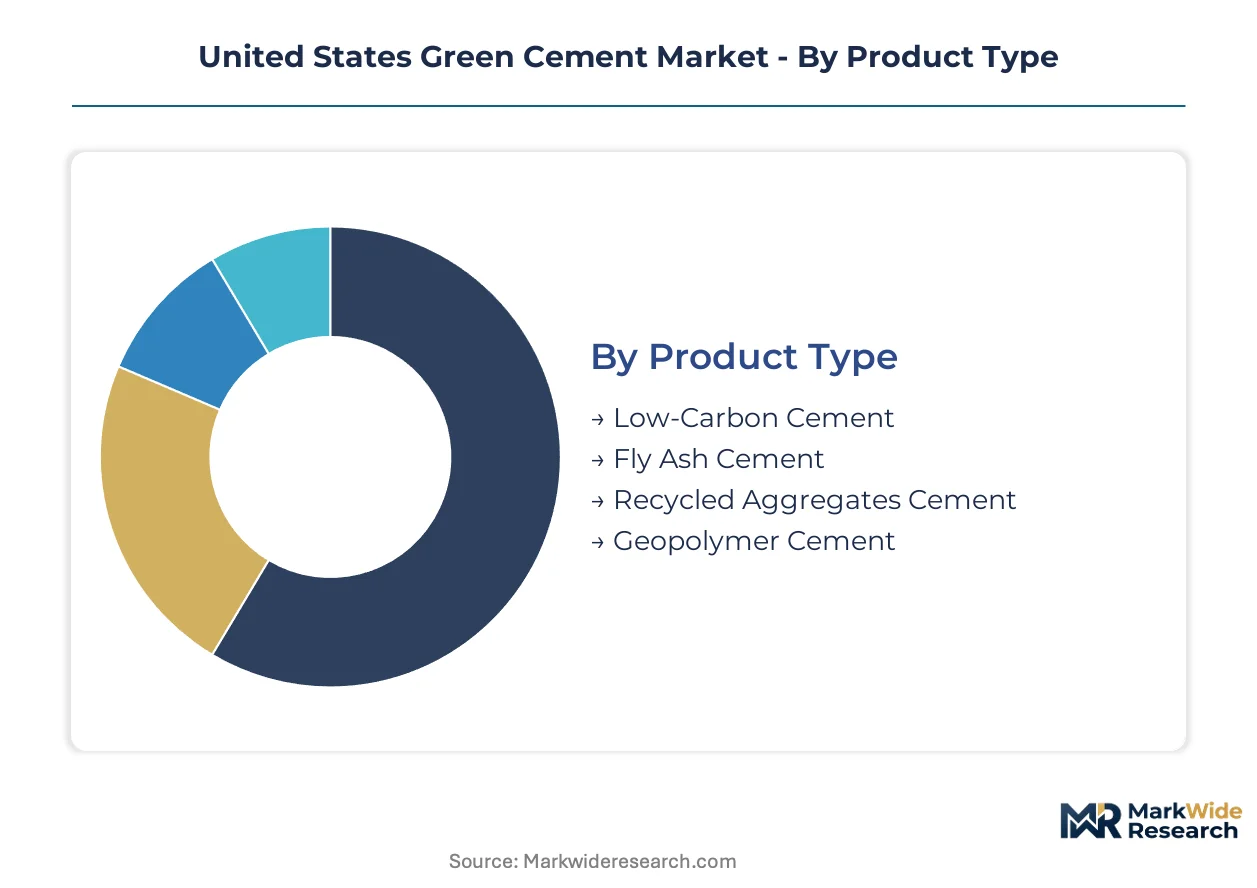
Green cement segmentation in the United States reflects divergent technical maturity and procurement pathways across federal, state, and private construction channels. Product chemistry and end-use specifications determine qualification timelines and margin structures for blenders competing under Buy Clean thresholds.
Product Type:
Volume concentration favors established SCM blends, while premium positioning attaches to novel chemistries commanding performance-based specifications.
- Low-Carbon Cement:Formulations combining Portland clinker with calcined clays or limestone achieve 30-40% emissions reductions without wholesale kiln redesign. Demand concentrates in California DOT highway contracts where performance specs decouple approval from traditional ASTM limits. The Buy Clean Initiative pulls these blends into federal courthouse and VA hospital prequalification programs.
- Fly Ash Cement:ASTM C618-compliant blends with 15-40% coal combustion residuals dominate existing volume pools across Texas, Ohio, and Midwest infrastructure corridors. Utilities in these states are locking in long-term supply agreements before ash pond closures eliminate feedstock access. Margin compression follows as supply agreements commoditize regional availability.
- Recycled Aggregates Cement:Incorporates post-consumer concrete fines and reclaimed masonry as partial clinker replacement. Demand from Florida coastal resiliency codes incorporates lifecycle carbon metrics into hurricane-resistant construction standards.
- Geopolymer Cement:Alkali-activated binders using metakaolin or blast furnace slag eliminate Portland clinker entirely. New York and California DOT pilot programs for structural precast applications are accelerating specification approval outside traditional compliance cycles.
Mature deployment sits with Fly Ash Cement. Newer deployment is concentrated in Geopolymer Cement.
End User:
Procurement risk allocation shifts with project scale, separating owner-operated federal work from speculative residential development.
- Residential Construction:Multifamily developers in Seattle and Portland specify low-carbon mixes to satisfy local embodied carbon ordinances. Design-build firms bundle material procurement with carbon performance guarantees, transferring risk from owners to suppliers.
- Commercial Buildings:LEED certification thresholds and corporate ESG mandates drive specification in corporate headquarters and data center construction. Third-party EPD verification spans 8-14 months, delaying prequalification for private projects.
- Infrastructure Projects:Federal procurement mandates compress specification timelines for highway, bridge, and transit concrete. GSA contracts now embed embodied carbon thresholds that disqualify conventional Portland blends.
- Industrial Applications:Manufacturing facility slabs and warehouse foundations prioritize cost containment over carbon accounting, limiting green cement penetration absent regulatory mandate.
Steepest expansion trajectory attaches to Infrastructure Projects. Slowest adoption persists in Industrial Applications.
Distribution Channel:
Channel selection reflects batch plant proximity and quality control requirements for SCM-heavy formulations.
- Direct Sales:Ready-mix producers with captive cement grinding capacity supply major infrastructure contractors under sole-source federal exemptions. CarbonCure injection systems integrate at these plants for automated mineralization documentation.
- Distributors:Regional material houses aggregate bagged and bulk shipments for mid-tier commercial contractors. Silo segregation investments separate SCM blends from conventional inventory.
- Wholesale Suppliers:Volume aggregators serve rural construction markets where batch plant density cannot support direct producer relationships.
- Online Retail:Limited to specialty repair mortars and small-volume geopolymer kits for restoration contractors.
Channel margin concentration aligns with Direct Sales. Wholesale Suppliers face disintermediation as producers consolidate regional coverage.
Application:
Structural load requirements and exposure classifications segment approval pathways across transportation and building systems.
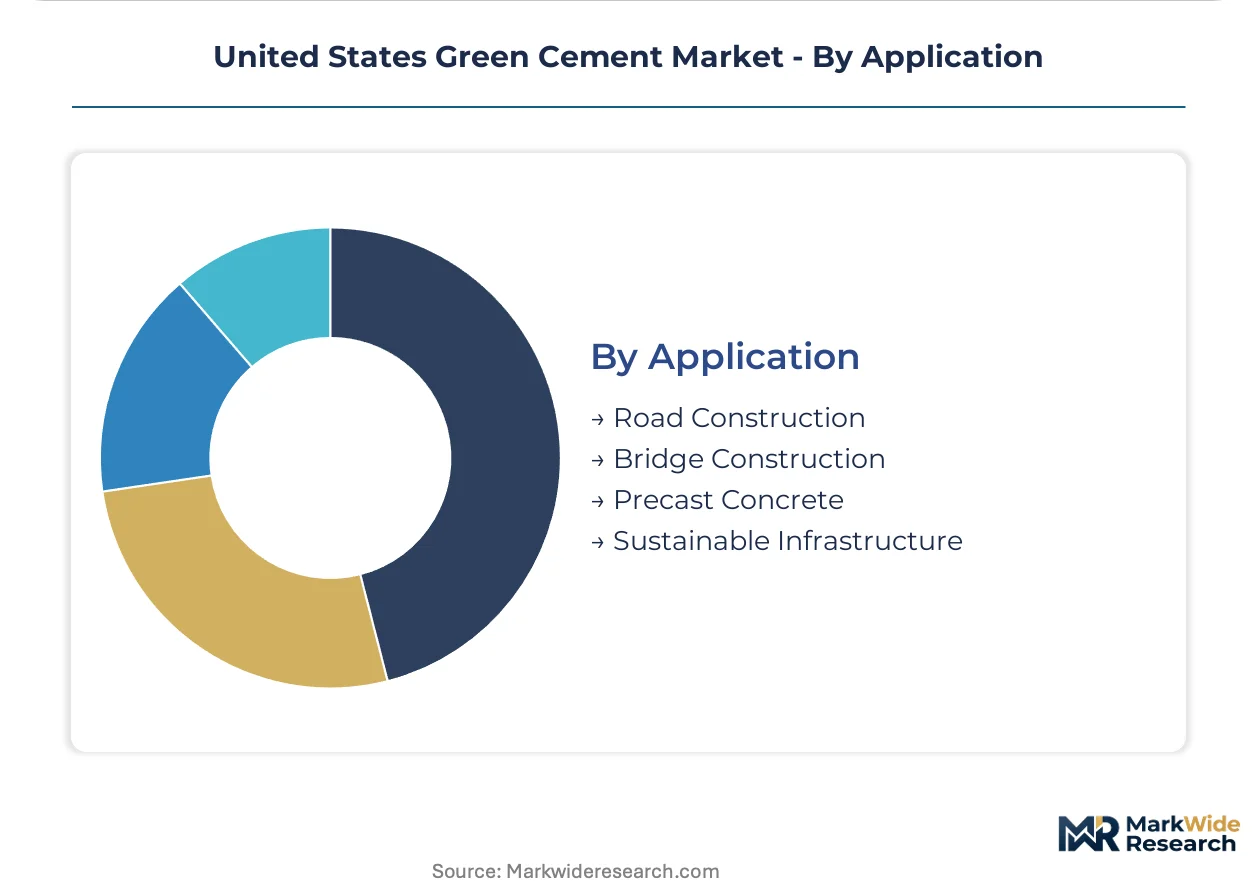
- Road Construction:Paving contractors in Texas and California DOT districts pilot CO₂ injection systems for carbon accounting automation. Highway specifications prioritize freeze-thaw durability over emissions intensity in northern climates.
- Bridge Construction:Deck replacement contracts in Florida and New York incorporate lifecycle carbon metrics alongside chloride penetration resistance. Design-build risk transfer models displace low-bid awarding on these projects.
- Precast Concrete:Controlled curing environments accommodate geopolymer and alkali-activated binders sensitive to ambient temperature fluctuations. State DOT performance specs accelerate adoption outside traditional ASTM cycles.
- Sustainable Infrastructure:Federal courthouse, VA hospital, and GSA lease construction mandates embodied carbon thresholds through the Buy Clean Initiative. EPD certification delays currently bottleneck supplier qualification.
Application revenue pools concentrate in Road Construction. Specification innovation is advancing most quickly in Precast Concrete.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public infrastructure procurement concentrates demand in the South and West, while state-level embodied carbon mandates pull specification innovation toward the coasts. Federal Buy Clean thresholds and DOT performance specifications are redrawing regional competitive boundaries.
Texas
Highway and bridge contractors consume fly ash blends under accelerated federal procurement timelines. The Texas Department of Transportation embeds lifecycle carbon metrics into design-build contracts for interstate expansion corridors. Houston and Dallas-Fort Worth batch plants are retrofitting silo systems to handle SCM-heavy formulations.
California
State DOT performance specifications decouple approval from clinker content limits, enabling geopolymer pilots in structural precast. The Department of General Services enforces progressively tighter emissions benchmarks on public works concrete. Los Angeles and Sacramento construction markets anchor specification development for low-carbon cement categories.
Florida
Coastal resiliency codes incorporate lifecycle carbon metrics into hurricane-resistant construction standards for multifamily and commercial verticals. Miami-Dade and Broward County ordinances drive specification of recycled aggregates cement in high-wind zones. Tampa and Orlando developers are bundling material procurement with carbon performance guarantees.
Pacific Northwest
Seattle and Portland embodied carbon ordinances create first-mover advantage for low-carbon mix suppliers in residential construction. Washington and Oregon DOTs pilot CO₂ injection systems on highway paving contracts for automated carbon accounting. The region's hydropower base supports calcined clay activation economics for LC3 formulations.
Midwest
Integrated steel mill locations in Indiana and Ohio concentrate blast furnace slag supply for regional blenders. Chicago and Detroit infrastructure markets depend on slag-blend availability for DOT-compliant highway work. Utilities across Ohio and Illinois are locking in long-term fly ash agreements before ash pond closures eliminate feedstock access.
United States Green Cement Market Key Industry Players
Multinational integrated producers anchor one tier; domestic technology specialists hold differentiated positions in carbon utilization and novel curing pathways. Market structure reflects consolidation among kiln operators alongside fragmentation in injection technology and geopolymer chemistry. Three archetypes dominate: vertically integrated multinationals with captive SCM supply, CO₂ mineralization platform developers, and alkali-activated binder specialists. Competitive moves center on backward integration into alternative fuel supply chains and strategic partnerships for batch plant retrofit deployment.
Among Switzerland-based multinationals, LafargeHolcim and Holcim exemplify scale-driven archetypes with grinding capacity and federal prequalification infrastructure. Heidelberg Materials anchors the German-origin tier through upstream control over clinker substitution feedstocks. CarbonCure Technologies Inc. occupies the specialist position, representing CO₂ injection platform developers competing on automated carbon accounting documentation.
| Leading Market Players |
|---|
| LafargeHolcim |
| CEMEX |
| CRH plc |
| Calera Corporation |
| CarbonCure Technologies Inc. |
| Heidelberg Materials |
| Holcim |
| Votorantim Cimentos |
| Solidia Technologies |
| Others |
Cost & Logistics Intelligence
Federal Buy Clean Initiative embodied carbon thresholds gate qualified supply access and premium-tier pricing power for domestic blenders competing on GSA prequalification status. EPD certification timelines compress the addressable contractor pool, allowing verified producers to command structural premiums on federal courthouse and VA hospital contracts.
Pricing Analysis
Short lead-time premiums attach to qualified supply for accelerated federal procurement timelines, while spot inventory discounts emerge from legacy Portland stockpiles facing Buy Clean disqualification. Three-tier pricing structure across premium, standard, and economy levels stratifies by EPD verification status and ASTM C150 compliance tier. Cost compression in fly ash blends is intensifying because utilities are locking in long-term supply agreements before ash pond closures. Infrastructure contractors demonstrate lowest price sensitivity due to sole-source exemption protections, while speculative residential developers in Florida and the Pacific Northwest exhibit highest sensitivity to per-yard premiums.
Supply Chain Analysis
Dual-sourcing requirements from state DOTs and federal agencies mandate multi-supplier qualification for highway and bridge concrete, preventing single-source dependencies. Geographic supply concentrates in Indiana, Ohio, and Texas where integrated steel mills and coal-dependent power generators anchor slag and fly ash feedstock. Raw material dependencies rest on blast furnace slag, coal combustion residuals, and calcined clay activators. Single-source vulnerability runs through concentrated slag output from Midwest steel mill locations. Distribution feeds from captive batch plant networks serving major metropolitan construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slag grinding capacity scarcity props pricing power for qualified blenders, constraining supply expansion faster than Buy Clean demand growth. Federal procurement mandates are compressing specification timelines without matching capacity buildout.
For Market Incumbents: Anticipate geopolymer skill gaps and silica exposure compliance costs as dual threats to margin structures. Prioritize backward integration into alternative fuel supply chains and calcined clay activation capacity in the Pacific Northwest. Secure long-term fly ash agreements before utility ash pond closures eliminate feedstock access. For New Entrants and Emerging Players: Capture Pacific Northwest multifamily housing and Florida coastal resiliency codes as penetrable verticals with unmet low-carbon mix demand. Design-build risk transfer models in Seattle and Portland offer the most accessible go-to-market angle for carbon performance guarantee bundling. For Investors and Strategic Acquirers: California DOT geopolymer pilot program expansion is the leading indicator that alkali-activated binder specialists will command acquisition premiums. Target CO₂ mineralization platform developers with automated carbon accounting documentation capabilities. Watch for EPA Subpart H expansion to downstream concrete products as the inflection signal for compliance infrastructure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Fuel Supply | Heidelberg Materials anchors position through upstream control over clinker substitution feedstocks. |
| CO₂ Injection Platform Deployment | CarbonCure Technologies automates mineralization documentation for federal carbon accounting compliance. |
| Geopolymer Chemistry Scale-Up | Solidia Technologies differentiates on chemically distinct curing pathways bypassing kiln redesign requirements. |
| Long-Term Fly Ash Supply Agreement | Midwest utilities lock in feedstock relationships before ash pond closures eliminate regional availability. |
| EPD Certification Infrastructure Investment | Third-party verification bottlenecks protect prequalified blenders from commodity pricing pressure. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with ready-mix plant managers, state DOT specification engineers, federal procurement officers, and cement industry R&D directors. EPA Subpart H greenhouse gas reports, GSA Buy Clean procurement databases, state DOT performance specification drafts, and ASTM committee documentation provided validation benchmarks. Bottom-up volume estimates from batch plant capacity and top-down demand projections from construction spending data were reconciled through triangulation.
Data-stream reconciliation across production surveys, import-export flows, and end-use consumption patterns shaped the analytical framework. Segmentation dimensions modeled include product chemistry tier, end-use application, distribution channel structure, and regional regulatory cluster. CAGRs were derived from slope analysis of annualized growth trajectories. Industry-specific forecast inputs incorporated coal plant retirement schedules, steel mill slag output projections, and state-level embodied carbon ordinance adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA regulatory expansion timing and state low-carbon material standard fragmentation. Deviation in federal Buy Clean threshold stringency or geopolymer ASTM approval timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Rebar Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
Solar Frames Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Non-Residential Green Building Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Green Coatings Market
Green Building Materials
Green Cement Market
Green Building Materials
Green Building Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Solar Glass Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Solar Windows Market
Green Building Materials
GCC Green Cement Market