
 Green Building Market | 2026-2036
Green Building Market Size, Share, and Industry Trends Forecast 2026-2036
Green Building Market Intelligence
The integration of Building Information Modeling (BIM) with Internet of Things (IoT) smart sensors is tilting project design and facility management towards predictive maintenance and energy optimization. This digital transformation enables real-time performance monitoring, a core tenet of modern green construction. Skanska leverages its expertise in sustainable construction methods across Northern Europe and the United States. In contrast, VINCI differentiates through its large-scale infrastructure projects incorporating recycled materials and energy-efficient systems, particularly in France.
Green building encompasses the planning, design, construction, and operation of structures with a focus on minimizing environmental impact. This involves using sustainable materials, reducing energy and water consumption, and improving indoor air quality to meet specific performance targets, such as a low Energy Use Intensity (EUI). The residential application segment is expanding, driven by homeowner incentives for energy efficiency. Within product types, high-performance insulation and advanced solar panels represent high-value categories due to their direct impact on a building's operational carbon footprint.
Voluntary certification standards like LEED in the United States and BREEAM in the United Kingdom set critical benchmarks for energy and resource efficiency. Government mandates such as China's Three-Star Rating System and the EU's Corporate Sustainability Reporting Directive (CSRD) create direct demand for certified commercial properties. Navigating the diverse landscape of regional green codes and sustainable material sourcing will be a central challenge for developers and contractors seeking to balance upfront cost with long-term asset value.
Market Dynamics
The convergence of stringent government regulations and tenant-driven demand for certified sustainable spaces is the central force shaping the market. This dual pressure compels developers and investors to prioritize measurable energy efficiency and carbon reduction in both new builds and renovations.
Growth Catalysts
- Regulatory Mandates:Frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) create direct demand for certified commercial properties, compelling landlords to upgrade portfolios to meet corporate tenant disclosure requirements.
- Technology Integration:The fusion of Building Information Modeling (BIM) with IoT sensors enables predictive maintenance and real-time energy optimization, which are core value propositions for modern green facilities management.
- Government Incentives:China's Three-Star Rating System promotes green construction through preferential policies and subsidies, accelerating the adoption of sustainable practices in large-scale urban development projects.
Market Restraints
- High Initial Costs:The significant upfront capital investment required for high-performance insulation, advanced solar panels, and complex water recycling systems remains a primary barrier compared to conventional construction methods.
- Material Sourcing Complexity:Developers face challenges in consistently sourcing certified sustainable materials, such as FSC-certified wood or low-VOC paints, across different regions, leading to potential supply chain disruptions and cost overruns.
- Fragmented Building Codes:Navigating the diverse and often conflicting landscape of regional and municipal green building codes complicates design and compliance for multinational construction firms, increasing project risk.
Strategic Opportunities
- Building Retrofitting:A substantial opportunity exists in retrofitting the vast existing building stock, particularly in North America and Europe, to comply with new energy performance standards and reduce operational carbon footprints.
- Emerging Economies:Markets in Southeast Asia and Latin America represent significant growth potential as governments begin to introduce green building incentives and awareness of long-term asset value increases among investors.
- Grid-Interactive Buildings:Integrating building energy management systems with smart grid technology allows structures to act as distributed energy resources, offering new revenue streams for building owners through demand-response programs.
Industry Challenges
- Specialized Skill Gaps:A persistent shortage of architects, engineers, and construction managers with expertise in sustainable design, BIM, and green certification processes hinders project execution and quality control.
- Certification Delays:The lengthy and rigorous documentation and review process for obtaining certifications like LEED and BREEAM can introduce significant timeline risks and administrative burdens to development projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Building Market |
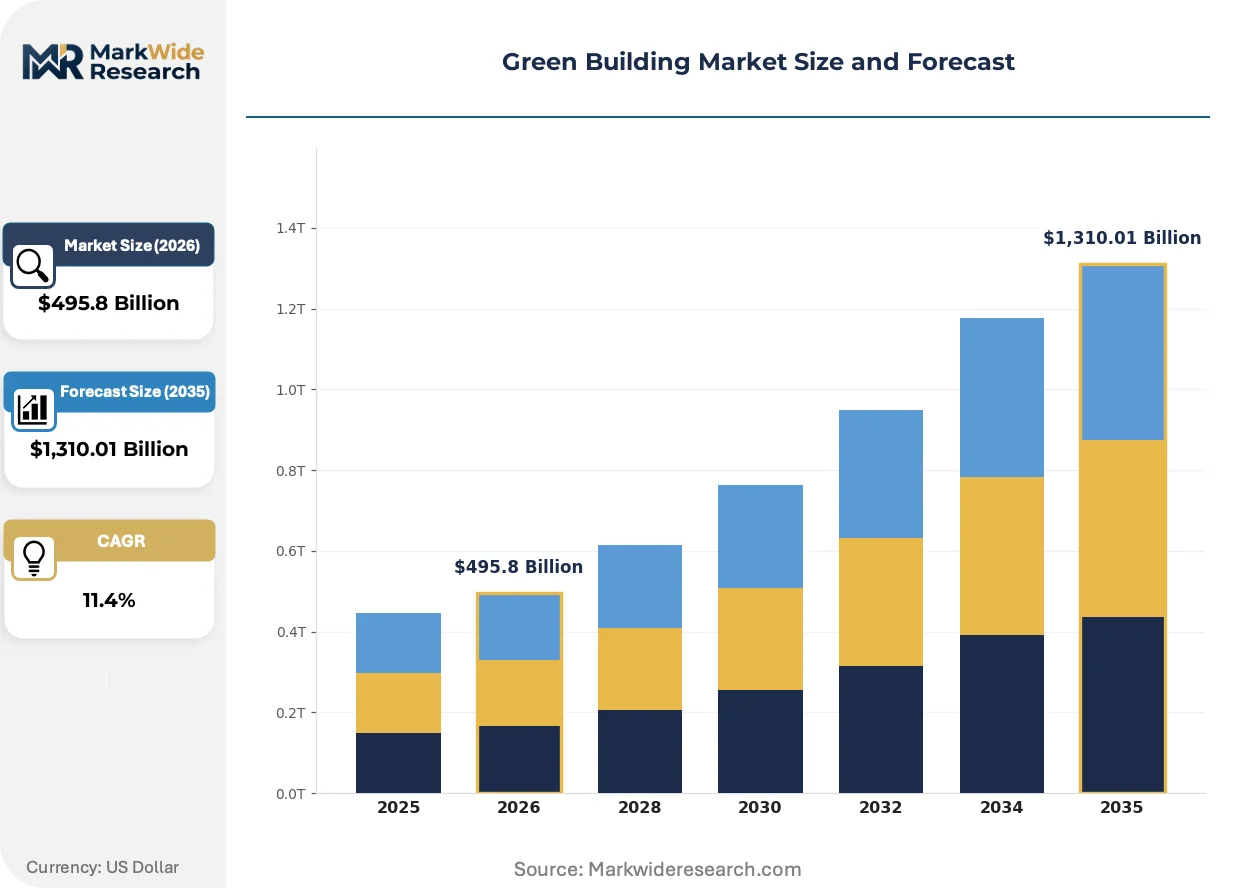
| Market Size in 2026 | $495.8 Billion |
| Market Size in 2035 | $1,310.01 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation, Windows, Flooring, Roofing Application: Residential, Commercial, Institutional, Industrial Material: Bamboo, Recycled Steel, Hempcrete, Rammed Earth Technology: Solar Panels, Geothermal Systems, Rainwater Harvesting, Smart Sensors |
| Companies Covered | Bechtel, Larsen & Toubro, VINCI, Hochtief, Acciona, ACS Group, Fluor Corporation, Skanska, Bouygues, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Building Market Strategic Shifts & Innovations
Performance data is displacing design intent as the primary currency of value in green buildings. The market is shifting from a focus on static material checklists to dynamic, operational efficiency measured in real time through integrated digital systems.
Digital twin technology, created from BIM and live IoT sensor data, provides a virtual replica of a building for performance simulation. Facility managers and commercial real-estate portfolio owners are the primary adopters. This technology is collapsing the gap between designed energy targets and actual operational consumption, enabling a proactive approach to maintenance and optimization.
China's "dual carbon goals" policy framework establishes strict energy consumption benchmarks for new buildings. This forces developers to specify high-efficiency HVAC, superior insulation, and on-site renewable systems from the earliest design stages. The mandate most heavily impacts the commercial and public building sectors, accelerating demand for products with verified low-carbon credentials.
Corporate tenants are increasingly specifying green building certifications like LEED or BREEAM as mandatory requirements in lease agreements. This changes the dynamic from a developer's cost choice to a critical element of a tenant's sustainability reporting and talent attraction strategy. This demand-side pull is most visible in the Class A commercial office markets across the United States and Europe.
Green Building Market Segmentation
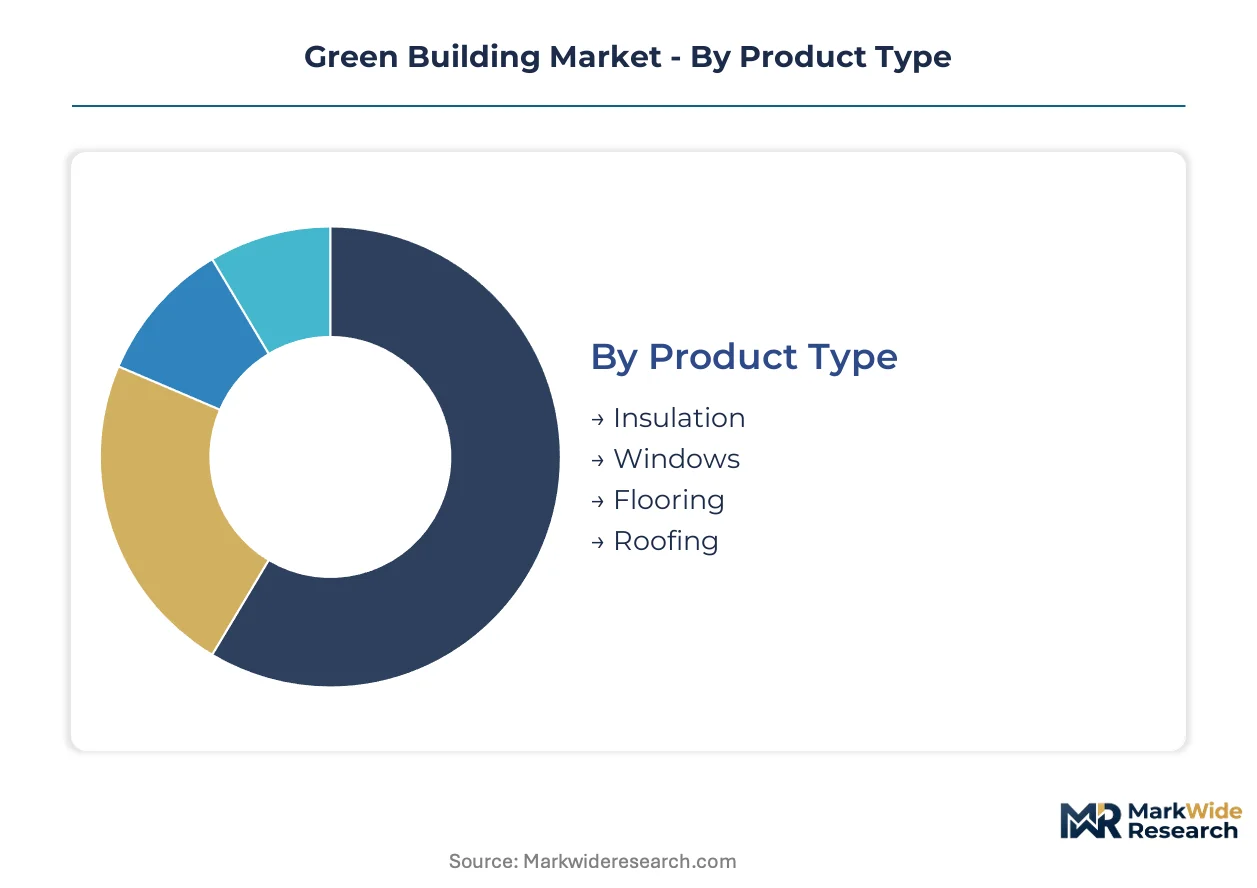
The green building market comprises diverse elements, each contributing uniquely to sustainable construction practices. Understanding these segments allows developers and investors to identify specific areas for innovation and strategic investment. This granular view reveals where regulatory pressures and technological advancements create the most significant impact.
Product Type:
The use-case spectrum for green building products ranges from foundational structural components to advanced energy-saving installations.
- Insulation:This category includes high-performance materials like mineral wool, cellulose, and rigid foam boards, designed to minimize heat transfer through building envelopes. Demand concentrates in regions like Northern Europe and the United States, driven by stringent energy efficiency codes and homeowner incentives for reduced utility costs.
- Roofing:Green roofing encompasses cool roofs, vegetated roofs, and integrated solar solutions, which reduce urban heat island effects and improve building energy performance. Commercial properties, particularly in urban centers, are adopting these systems to meet sustainability targets and manage stormwater runoff effectively.
- Windows:Energy-efficient windows feature multiple panes, low-emissivity coatings, and insulated frames to reduce thermal loss and gain.
- Flooring:Sustainable flooring options include bamboo, recycled content tiles, and reclaimed wood, selected for their low environmental impact and durability.
The dominant share belongs to Insulation, while Roofing is closing the gap fastest.
Application:
Cost tiers influence the adoption rate of green building solutions across various end-use applications, from large-scale commercial projects to individual residential upgrades.
- Commercial:This segment includes office buildings, retail spaces, and hospitality venues, where green certifications like LEED and BREEAM are critical for attracting corporate tenants. Regulatory mandates such as the EU's CSRD compel property owners to invest in energy-efficient systems and sustainable materials to meet disclosure requirements.
- Residential:Single-family homes and multi-unit dwellings form this application segment, driven by homeowner desires for lower utility bills and government incentives for energy-efficient upgrades. The United States and China show strong growth due to increasing consumer awareness and policy support.
- Institutional:Schools, hospitals, and government facilities fall into this category, often driven by public sector sustainability goals and long-term operational cost savings.
- Industrial:Manufacturing plants and warehouses represent this segment, where the focus is on optimizing energy consumption, reducing waste, and improving indoor environmental quality for workers.
Commercial applications hold the largest share, with Residential applications gaining share fastest.
Material:
Volume considerations heavily influence the selection of green building materials, balancing availability with environmental performance and structural integrity.
- Recycled Steel:This material offers high strength-to-weight ratios and significantly reduces the energy footprint compared to virgin steel production. Its widespread availability and established supply chains make it a preferred choice for structural components in large construction projects across all geographies.
- Hempcrete:A bio-composite material made from hemp hurds and lime, Hempcrete provides excellent thermal insulation and moisture regulation, offering a low-carbon alternative to traditional concrete. Its use is expanding in European markets like France, driven by a focus on natural and breathable building envelopes.
- Bamboo:Known for its rapid growth and strength, bamboo is used in flooring, paneling, and structural elements, particularly in Asian markets.
- Rammed Earth:This ancient construction technique uses compacted natural soils to create durable and thermally massive walls, seeing a resurgence in arid and semi-arid regions.
Recycled Steel maintains a substantial market presence, while Hempcrete exhibits the steepest expansion trajectory.
Technology:
The application of green building technologies spans from on-site energy generation to intelligent building management, enhancing operational efficiency and environmental performance.
- Solar Panels:Photovoltaic (PV) systems convert sunlight into electricity, significantly reducing a building's reliance on grid power and lowering operational carbon emissions. Their adoption is accelerating in the United States and China, propelled by government incentives and decreasing panel costs.
- Smart Sensors:Integrated IoT sensors monitor various environmental parameters like temperature, humidity, and occupancy, enabling real-time data collection for energy optimization and predictive maintenance. Commercial real estate portfolios are increasingly deploying these systems for facility management across Europe.
- Geothermal Systems:These systems utilize the earth's stable temperature to provide efficient heating and cooling, offering a consistent renewable energy source.
- Rainwater Harvesting:This technology collects and stores rainwater for non-potable uses like irrigation and toilet flushing, reducing municipal water demand.
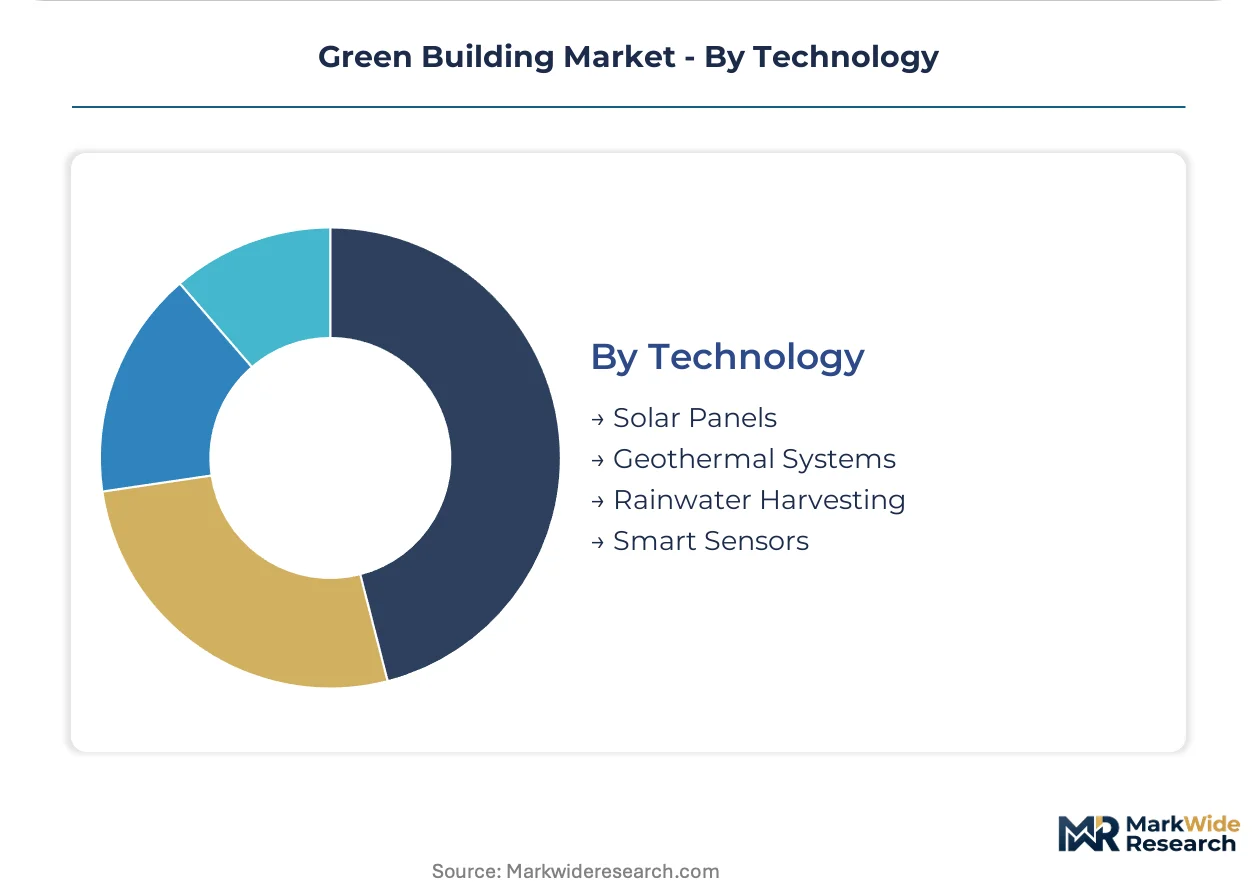
Solar Panels currently command the largest segment, with Smart Sensors demonstrating rapid advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for green building materials and technologies flows significantly from Europe to the United States, driven by a shared commitment to sustainable infrastructure. This cross-continental exchange supports innovation in energy-efficient systems and certified construction practices. Regulatory alignment fosters market expansion across these key regions.
United States
Strong demand for LEED-certified commercial spaces drives green building activity across the United States. The Inflation Reduction Act (IRA) provides significant tax credits for energy-efficient building upgrades and renewable energy installations. Major metropolitan areas like New York City are implementing stringent local energy codes for new and existing buildings, compelling developers to adopt sustainable practices.
China
China's rapid urbanization and national sustainability goals propel the adoption of green construction technologies and materials. The China Three-Star Rating System promotes energy-efficient design and material use in large-scale projects. Cities such as Shanghai are seeing extensive development of low-carbon commercial and residential complexes, driven by government mandates and corporate sustainability targets.
Germany
Germany's stringent energy performance standards for buildings create a robust market for high-performance insulation and smart building technologies. The EU Green Deal and national KfW programs incentivize energy-efficient renovations and new builds across the country. The Rhine-Ruhr region actively integrates renewable energy systems into urban development projects, focusing on reducing operational carbon footprints.
France
France's public sector commitments to carbon neutrality stimulate demand for sustainable materials like hempcrete and advanced energy management systems. VINCI leverages its expertise in large-scale infrastructure projects incorporating recycled materials and energy-efficient systems within France. Paris is a hub for innovative retrofitting initiatives designed to meet ambitious carbon reduction targets for existing building stock.
India
India's growing awareness of environmental impact and government initiatives like the Energy Conservation Building Code (ECBC) are boosting green construction. The Indian Green Building Council (IGBC) certification system is gaining traction for commercial and residential projects nationwide. Bengaluru's IT parks increasingly feature green building designs to attract multinational tenants and meet corporate sustainability mandates.
Green Building Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in the green building sector. The market exhibits a tiered structure, with large general contractors operating across multiple geographies alongside niche technology providers focusing on specific solutions. Strategic archetypes include integrated construction giants, specialized sustainable material suppliers, and smart building technology developers. Geographic expansion into high-growth regions and portfolio diversification into new green solutions are common competitive moves among the larger entities.
Among integrated construction firms, VINCI, a French-based entity, exemplifies a strategic focus on large-scale infrastructure projects incorporating recycled materials and energy-efficient systems. Skanska, a Swedish-headquartered firm, represents expertise in sustainable construction methods across Northern Europe and the United States, emphasizing operational efficiency. Bechtel, a US-based engineering and construction company, anchors the high-end project segment, often delivering complex green building solutions for institutional and commercial clients. These firms leverage their extensive project management capabilities to deliver certified sustainable spaces globally, shaping market standards.
| Leading Market Players |
|---|
| Bechtel |
| Larsen & Toubro |
| VINCI |
| Hochtief |
| Acciona |
| ACS Group |
| Fluor Corporation |
| Skanska |
| Bouygues |
| Others |
Cost & Logistics Intelligence
Under-capacity in specialized green building material production in emerging economies drives supplier behavior towards premium pricing for certified products. This scarcity impacts project cost structures, influencing developer material selection and procurement strategies.
Pricing Analysis
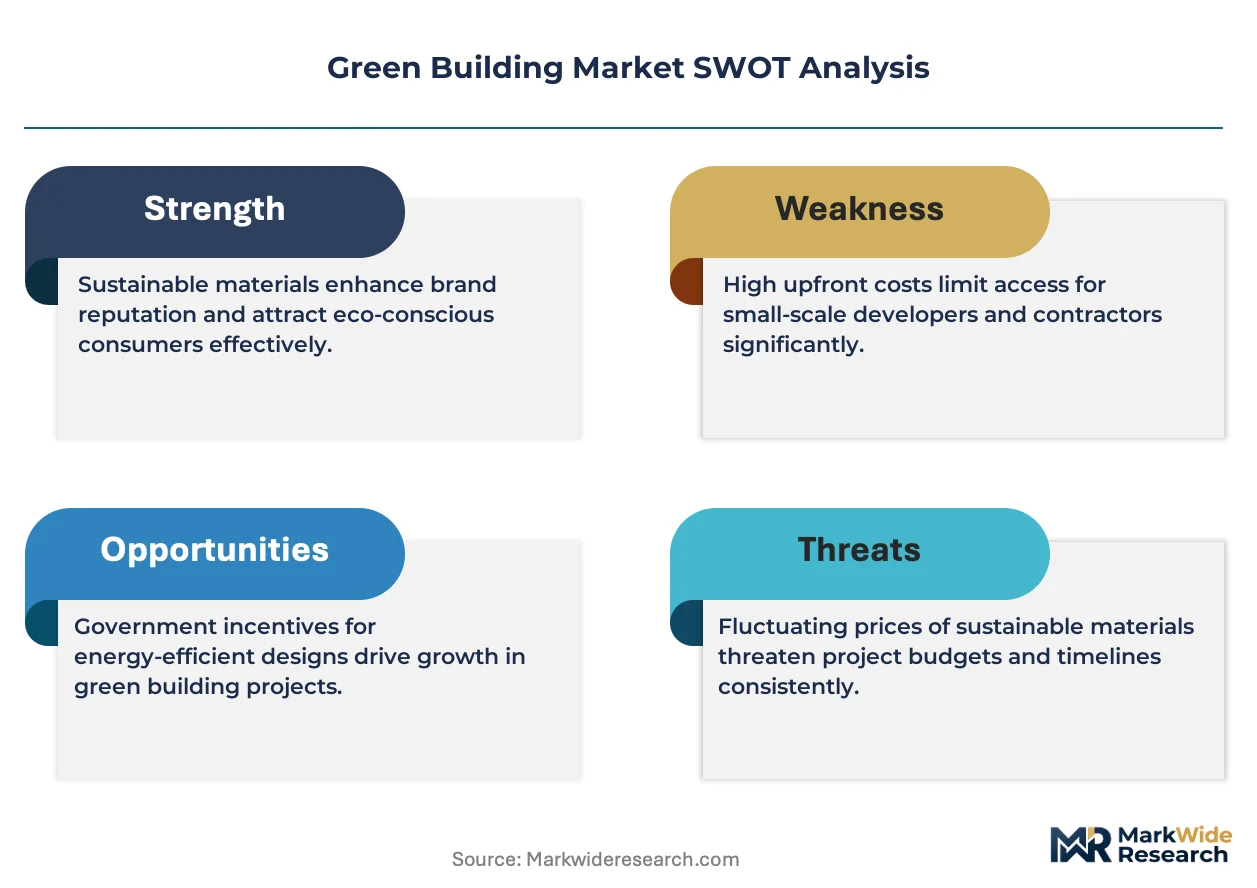
Next-generation building technologies like integrated smart sensors and advanced solar panels command higher pricing compared to prior-generation high-performance insulation. Project-based pricing dominates for large-scale green building installations, reflecting customization and integration complexity. Price differentiation stems from certification levels, such as LEED or BREEAM, and long-term performance guarantees. Pricing softness affects commodity green materials due to expanding production capacity. Residential homeowners exhibit high price sensitivity for energy-efficient upgrades, whereas institutional clients prioritize long-term asset value.
Supply Chain Analysis
Extended payment terms for high-value green building components influence supplier liquidity and investment in new technologies. Geographic supply concentration for advanced components centers on China and Germany, while India provides many basic construction materials. The supply chain draws from recycled steel, specialized insulation compounds, and rare earth elements for advanced solar panels. Commodity price volatility for these critical inputs represents a structural supply chain risk. Distribution runs through specialized distributors for materials and direct sales channels for complex technology systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green building market is experiencing a cyclical recovery, primarily driven by a post-pandemic rebound in commercial construction activity across major urban centers. This renewed momentum creates strategic imperatives for various market participants.
For Market Incumbents: Pre-empt market fragmentation by investing in digital twin technology for predictive maintenance and operational efficiency across portfolios. Consolidate market share through strategic acquisitions of specialized green material suppliers to control sourcing and quality. This defends against emerging entrants offering niche sustainable solutions. Vertical integration into sustainable material production mitigates supply chain disruptions and strengthens market position against commodity price volatility.
For New Entrants and Emerging Players: Retrofitting older commercial buildings in European secondary cities represents a highly penetrable entry point due to stringent EU Green Deal mandates. Focus on providing integrated smart sensor solutions for real-time energy optimization in these existing structures. A compelling go-to-market angle involves offering bundled energy performance contracts, guaranteeing operational savings for property owners. This strategy leverages the demand for certified sustainable spaces without requiring new construction capital.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across advanced green building technology segments as manufacturing scales. The market offers long-term viability driven by sustained regulatory pressure and corporate sustainability commitments over the next decade. Target mid-sized firms specializing in high-performance insulation or grid-interactive building technologies with strong intellectual property. Increased government incentive disbursements, like those from the US Inflation Reduction Act, serve as a critical signal to watch for accelerated investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Technology Adoption | Integrated construction giants deploy virtual models for predictive maintenance and real-time energy optimization across their portfolios. |
| Sustainable Material Sourcing Partnerships | Developers establish long-term contracts with suppliers for FSC-certified wood and low-carbon concrete to secure supply. |
| Energy Performance Contracting Expansion | Specialized firms offer guaranteed operational savings for commercial property retrofits under new regulatory mandates. |
| Grid-Interactive Building Development | Technology providers integrate advanced building energy management systems with smart grid infrastructure for demand response. |
| Green Certification Process Streamlining | Consultancy firms develop AI-powered platforms to accelerate LEED and BREEAM documentation and review for clients. |
Research Approach
Desk research of industry association reports and government energy performance databases preceded structured interviews with architects, facility managers, sustainability consultants, and government regulators. This approach combined primary insights from industry stakeholders with secondary validation from published data. Market sizing and segmentation involved both bottom-up aggregation of product sales and top-down analysis of overall construction spending.
Assumptions regarding stable global economic growth and consistent regulatory enforcement were held fixed across the analysis window, while technological adoption rates were varied. The analytical framework modeled market dynamics across product type, application, material, technology, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected impacts of government incentives. Forecast inputs included building code stringency levels and the declining cost of renewable energy solutions.
Practitioners should monitor evolving geopolitical shifts and potential supply chain disruptions for critical green building materials for early signals of market change. Forecasts reflect assumptions documented through extensive primary and secondary research. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Green Roof Market
Green Building Materials
Green Coatings Market
Green Building Materials
Non-Residential Green Building Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
North America Green Cement Market
Green Building Materials
Outdoor Flooring Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Solar Windows Market
Green Building Materials
Green Rebar Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Solar Glass Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
Solar Frames Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Global Green Walls Market