
 Carbon Verification Market | 2026-2036
Carbon Verification Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Verification Market Insights
Digital ledger technology is recalibrating carbon verification economics by replacing paper-based attestation with immutable audit trails. Verra leverages its voluntary carbon standard registry to anchor premium pricing for nature-based offset projects. SGS competes through accredited laboratory networks spanning six continents. Bureau Veritas differentiates via integrated sustainability assurance that bundles verification with supply chain risk assessment.
Carbon verification encompasses the independent assessment of greenhouse gas assertions against recognized protocols using sampling plans, measurement uncertainty budgets, and materiality thresholds to issue limited or reasonable assurance opinions. Third-party audit methodologies apply ISO 14064-3 principles for direct emissions quantification, while satellite observation systems deploy hyperspectral imaging to detect land-use change across forest carbon projects. Verification method selection tracks project scale and data availability, with blockchain-enabled measurement-reporting-verification pipelines representing the fastest-growing technology segment as corporations seek tamper-evident disclosure records. Certification standard adoption clusters around Verra and Gold Standard for voluntary markets, though local regulations are gaining share where jurisdictions impose compliance-grade obligations.
The EU Green Deal and CSRD mandate granular corporate emissions disclosure, while the EPA in the United States enforces mandatory greenhouse gas reporting for large industrial facilities. ISO 14064 provides the technical backbone for cross-border recognition of verification outcomes, reducing duplication costs for multinational filers. Stakeholders must monitor whether emerging national carbon accounting frameworks achieve mutual recognition or fragment into non-tariff trade barriers.
Market Dynamics
Corporate disclosure mandates under the EU CSRD and Science Based Targets initiative are forcing granular emissions verification across tiered supply chains, compressing audit timelines and elevating demand for automated measurement-reporting-verification pipelines.
Growth Catalysts
- EU CSRD Mandates:The Corporate Sustainability Reporting Directive requires third-party limited assurance on Scope 3 emissions, creating compulsory audit demand from industrial filers across Germany, France, and Italy.
- ISO 14064 Certification:German industrial clusters pursuing export competitiveness are driving concentrated demand for accredited verification bodies capable of cross-border protocol recognition.
- Blockchain-Enabled MRV:Immutable audit trails are displacing paper-based attestation, with hyperspectral satellite imaging expanding into forest carbon project monitoring to reduce verification cycle times.
Market Restraints
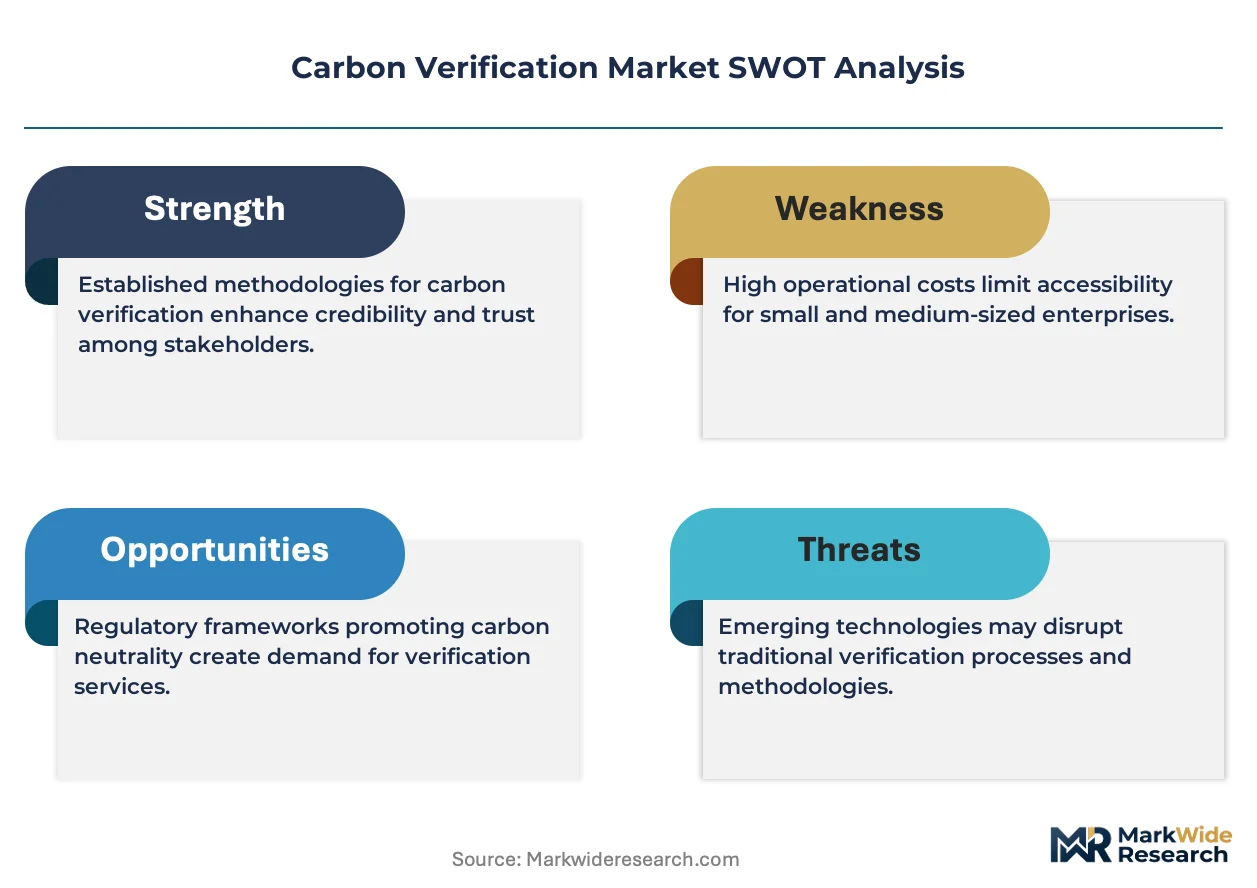
- Accredited Assessor Scarcity:The limited pool of ISO 14064-3 certified auditors creates supply bottlenecks, particularly in emerging markets where accreditation infrastructure remains underdeveloped.
- Measurement Uncertainty Costs:Complex sampling plans and materiality threshold calculations for Scope 3 value chain emissions inflate verification fees, pricing out mid-cap filers.
- Protocol Fragmentation Risk:Divergent national carbon accounting frameworks threaten mutual recognition, potentially forcing duplicate verification for multinational corporations operating across jurisdictions.
Strategic Opportunities
- India's PLI-Linked Disclosure:Production-linked incentive schemes for green hydrogen and renewable manufacturing are mandating emissions benchmarking, opening verification demand among domestic industrial conglomerates.
- Integrated Sustainability Assurance:Bundling carbon verification with supply chain risk assessment creates differentiated service offerings for private equity portfolio companies facing ESG due diligence pressure.
- Smallholder Agriculture Carbon:Nature-based offset projects in Brazil and Indonesia remain underpenetrated by accredited verification bodies, representing white space for protocol adaptation at scale.
Industry Challenges
- Remote Sensing Calibration:Hyperspectral imaging systems require ground-truthing expertise that remains scarce outside established verification markets, constraining satellite-based audit deployment.
- Legacy ERP Integration:Corporations with decades-old emissions data architectures face friction connecting distributed source systems to automated verification platforms, elongating implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Verification Market |
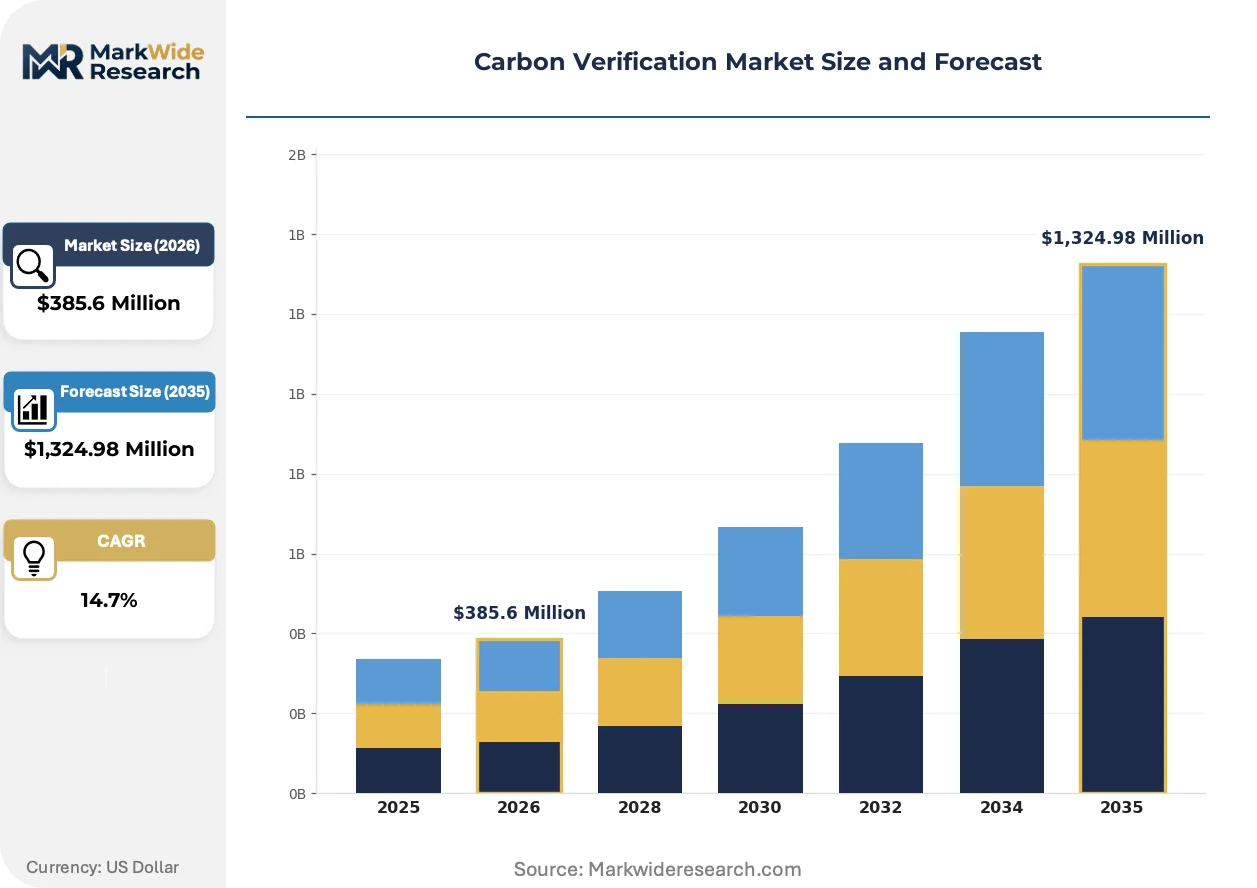
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,324.98 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Verification Method: Direct Measurement, Data Monitoring, Satellite Observation, Third-Party Audit End User: Corporations, Governments, Environment Organizations, Financial Institutions Technology: Blockchain, AI Analytics, IoT Sensors, Carbon Footprint Calculators Certification Standard: ISO 14064, Verra, Gold Standard, Local Regulations |
| Companies Covered | Verra, Gold Standard, DNV, TÜV SÜD, American Carbon Registry, Climate Action Reserve, Bureau Veritas, SGS, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Verification Market Trends and Innovations
Digital ledger infrastructure is compressing verification economics while regulatory granularity tightens audit specifications. Three developments are restructuring competitive positioning and service delivery models.
Blockchain-enabled measurement-reporting-verification pipelines are expanding into corporate sustainability disclosure, replacing notarized paper trails with tamper-evident timestamped records. Large industrial filers in Germany and the Netherlands are adopting these systems to meet CSRD assurance deadlines. The technology is expanding into premium pricing tiers for nature-based offset projects where provenance documentation commands buyer premiums.
The EPA's mandatory greenhouse gas reporting program for large industrial facilities is tightening quantification protocols, requiring enhanced sampling plans and uncertainty budgets for combustion source categories. Chemical and refining complexes in Texas and Louisiana are expanding in-house metrology capabilities to preempt enforcement actions. This regulatory compression is elevating demand for accredited third-party verification bodies with stationary source specialization.
Buyers are unbundling assurance services from bundled consulting arrangements, contracting directly with accredited verification bodies to eliminate perceived conflicts of interest. Private equity sponsors conducting ESG due diligence are driving this pattern, particularly for portfolio companies with Science Based Targets initiative commitments. The shift is most visible in the United Kingdom and Nordic markets where investor stewardship codes emphasize independent attestation.
Carbon Verification Market Segmentation
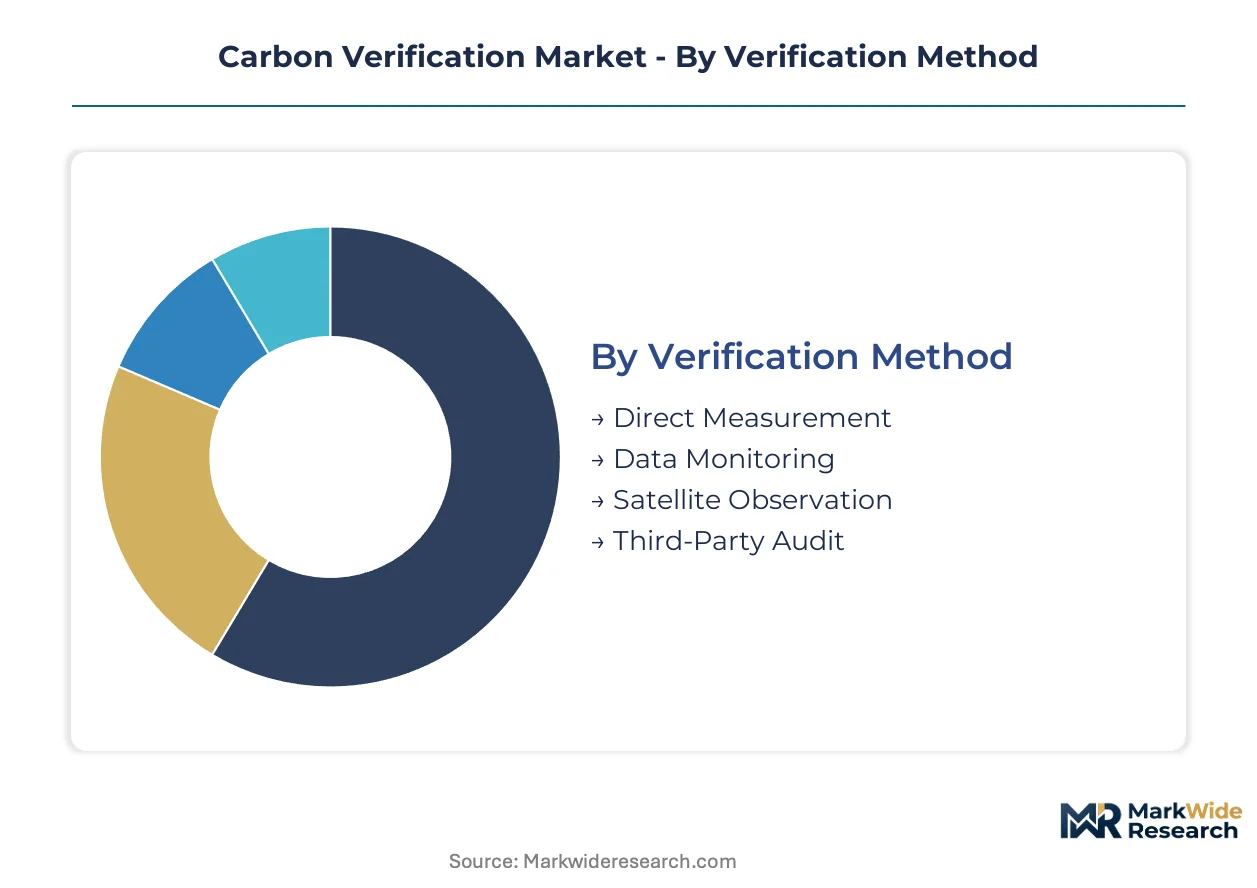
Carbon verification services fragment across methodological approaches, end-user sophistication, and technology integration depth. Each segmentation dimension carries distinct margin profiles and capability requirements that shape competitive positioning.
Verification Method:
Standalone verification protocols operate independently of corporate IT systems, while embedded methods integrate with automated data pipelines.
- Third-Party Audit:ISO 14064-3 accredited assessors conduct on-site inspections and documentation reviews to issue limited or reasonable assurance opinions. Demand concentrates in Germany's industrial clusters seeking export competitiveness certification under EU CSRD mandates.
- Satellite Observation:Hyperspectral imaging systems detect land-use change across forest carbon projects without physical site visits. Brazil and Indonesia nature-based offset developers deploy this method to compress verification cycle times where ground access remains costly.
- Direct Measurement:Continuous emissions monitoring systems at stationary sources capture real-time stack gas concentrations.
- Data Monitoring:Automated collection from utility meters and fuel consumption records supports Scope 2 calculations.
Volume placements concentrate in Third-Party Audit; the faster expansion belongs to Satellite Observation.
End User:
Customer sophistication tiers separate enterprise-grade filers with dedicated sustainability teams from smaller entities purchasing standardized verification packages.
- Corporations:Large industrial filers with Science Based Targets initiative commitments require granular Scope 3 value chain verification across tiered suppliers. German automotive and chemical conglomerates drive premium demand for integrated sustainability assurance bundles.
- Financial Institutions:Private equity sponsors and asset managers commission independent attestation for ESG due diligence on portfolio companies. United Kingdom and Nordic investor stewardship codes accelerate direct contracting with accredited verification bodies.
- Governments:National regulators and municipal authorities verify compliance-grade emissions for carbon pricing schemes.
- Environment Organizations:NGOs operating nature-based offset projects seek certification for voluntary carbon market participation.
Revenue concentration sits with Corporations; Financial Institutions are climbing the fastest as ESG disclosure tightens.
Technology:
Technology maturity curves separate proven infrastructure from emerging platforms still requiring calibration validation.
- Blockchain:Immutable timestamped records replace notarized paper trails in measurement-reporting-verification pipelines. Large Dutch industrial filers adopt these systems to meet CSRD assurance deadlines with tamper-evident disclosure documentation.
- AI Analytics:Machine learning models process heterogeneous emissions data to flag anomalies and project trajectories.
- IoT Sensors:Distributed device networks capture operational data from industrial equipment and building systems.
- Carbon Footprint Calculators:Standardized software tools enable self-assessment for preliminary emissions screening.
Deployment scale favors Blockchain; AI Analytics shows the steepest expansion trajectory as model accuracy improves.
Certification Standard:
Protocol recognition tiers separate internationally portable standards from jurisdiction-specific frameworks with limited cross-border validity.
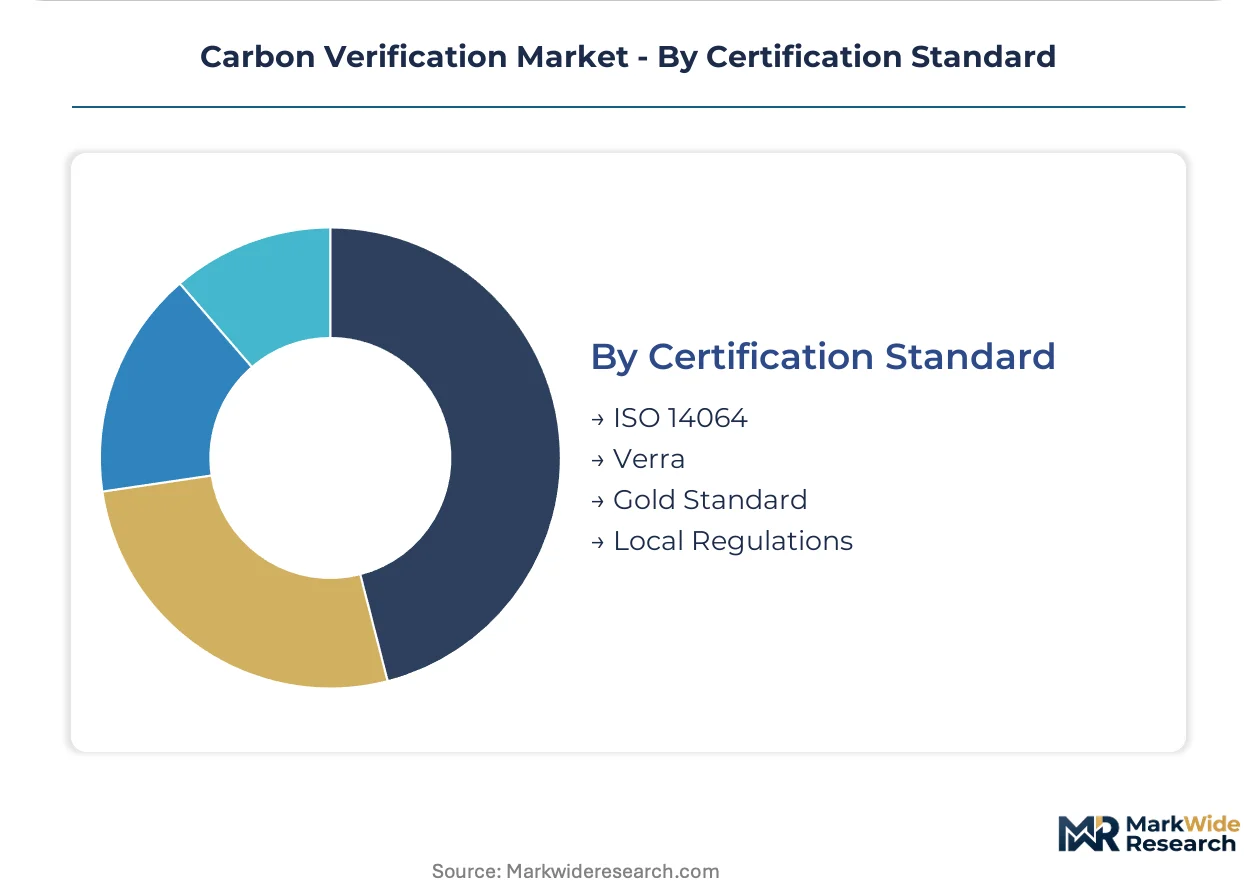
- ISO 14064:Technical backbone for cross-border recognition of verification outcomes reduces duplication costs for multinational filers. German industrial exporters prioritize this standard for supply chain passporting into EU and Asian markets.
- Verra:Voluntary Carbon Standard registry anchors premium pricing for nature-based offset projects with provenance documentation. Forest carbon developers in Brazil and Indonesia leverage Verra certification to access buyer pools demanding rigorous additionality testing.
- Gold Standard:Sustainable development co-benefit requirements attract impact-focused voluntary market participants.
- Local Regulations:National carbon accounting frameworks gain share where jurisdictions impose compliance-grade obligations distinct from voluntary protocols.
Adoption volume clusters around ISO 14064; Local Regulations are gaining share fastest as sovereign carbon pricing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free zones in the Netherlands and Germany's Rhine-Ruhr corridor concentrate carbon verification demand as export-oriented manufacturers seek ISO 14064 certification for supply chain passporting into EU and Asian markets.
United States
Texas and Louisiana petrochemical complexes drive demand for EPA-mandated greenhouse gas reporting with enhanced sampling protocols. The EPA enforces mandatory emissions quantification for large combustion sources. Houston-area refineries are expanding in-house metrology capabilities to preempt enforcement actions and secure third-party verification contracts.
Germany
Automotive and chemical conglomerates in Baden-Württemberg and North Rhine-Westphalia require granular Scope 3 verification across tiered suppliers. The EU CSRD mandates third-party limited assurance on corporate sustainability disclosures. Stuttgart's industrial cluster is adopting blockchain-enabled measurement-reporting-verification pipelines to compress audit timelines for export competitiveness.
Netherlands
Rotterdam port authorities and Dutch industrial filers deploy immutable audit trails to meet CSRD assurance deadlines with tamper-evident documentation. The EU Green Deal drives granular emissions disclosure requirements across value chains. Eindhoven's technology corridor integrates digital ledger infrastructure with automated data pipelines for real-time verification.
Brazil
Amazon basin forest carbon developers leverage hyperspectral satellite imaging to compress verification cycle times for nature-based offset projects. Local regulations gain share as sovereign carbon pricing frameworks expand. São Paulo-based project developers pursue Verra certification to access international buyer pools demanding rigorous additionality testing.
India
Gujarat and Maharashtra industrial conglomerates face emissions benchmarking mandates under production-linked incentive schemes for green hydrogen and renewable manufacturing. The country's central electricity authority and Bureau of Indian Standards shape certification requirements. Mumbai's financial institutions commission independent attestation for ESG due diligence on infrastructure portfolio companies.
Carbon Verification Market Competitive Landscape
Branded specialists and contract verification bodies split share differently across segments, with accredited assessor scarcity creating supply bottlenecks in emerging markets. The vendor base concentrates around three strategic archetypes: standards registry operators anchoring premium voluntary market pricing, multinational testing-inspection-certification conglomerates with cross-border laboratory networks, and boutique sustainability assurance firms bundling verification with supply chain risk assessment. Competitive moves center on blockchain technology licensing for immutable audit trails and strategic partnerships with satellite imagery providers to expand remote sensing capabilities.
Within the standards registry tier, Verra and Gold Standard exemplify positioning built on voluntary carbon market infrastructure and provenance documentation for nature-based projects. Among testing-inspection-certification conglomerates, Bureau Veritas and SGS occupy positions defined by integrated service bundling and accredited laboratory networks spanning multiple continents. DNV represents the technical verification archetype with specialization in protocol engineering and assurance methodology development for industrial emissions quantification.
| Leading Market Players |
|---|
| Verra |
| Gold Standard |
| DNV |
| TÜV SÜD |
| American Carbon Registry |
| Climate Action Reserve |
| Bureau Veritas |
| SGS |
| Intertek Group |
| Others |
Pricing and Supply Chain Analysis
EU CSRD-mandated third-party limited assurance on Scope 3 emissions is compressing audit timelines and forcing verification bodies to restructure capacity deployment, elevating pricing power for accredited assessors with ISO 14064-3 certification while squeezing margins for non-specialized providers.
Pricing Analysis
Short lead-time premiums of 15-25% apply to expedited CSRD compliance audits as German automotive conglomerates face hard disclosure deadlines. Three-tier pricing structure across premium, standard, and economy levels separates integrated sustainability assurance bundles from standalone verification and self-service calculator tools. Cost compression in the mid-market tier is intensifying because accredited assessor scarcity creates supply bottlenecks, yet mid-cap filers remain priced out of comprehensive Scope 3 value chain verification. Private equity sponsors conducting ESG due diligence show least price sensitivity, while Indian industrial conglomerates under PLI-linked disclosure mandates exhibit highest sensitivity to verification fees.
Supply Chain Analysis
ISO 14064-3 assessor accreditation gating restricts supply to bodies with recognized laboratory networks spanning Germany, the United Kingdom, and the Netherlands. Raw material inputs for verification services draw from satellite imagery licensing, blockchain infrastructure providers, and ground-truthing field teams. Single-source vulnerability concentrates in hyperspectral imaging calibration expertise, where ground-truthing capabilities remain scarce outside established European markets. Distribution runs through direct contracting relationships between accredited bodies and large industrial filers, with emerging volume through private equity ESG due diligence channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon verification market functions as a cost-of-compliance story where EU CSRD mandates create a barrier-to-entry moat for ISO 14064-3 accredited bodies, locking out unqualified competitors from premium assurance revenue pools.
For Market Incumbents: Extend accredited assessor training pipelines into India and Brazil to preempt emerging market supply constraints. Secure exclusive satellite imagery partnerships with hyperspectral providers to differentiate remote sensing capabilities against boutique competitors. Capacity addition in Stuttgart and Rotterdam industrial clusters captures concentrated German automotive demand for blockchain-enabled measurement-reporting-verification pipelines. For New Entrants and Emerging Players: Capture white space in smallholder agriculture carbon projects across Brazil and Indonesia where accredited verification penetration remains minimal. Target India's PLI-linked disclosure mandates among Gujarat and Maharashtra industrial conglomerates seeking emissions benchmarking for green hydrogen manufacturing. A go-to-market angle bundling carbon verification with supply chain risk assessment addresses private equity ESG due diligence requirements. For Investors and Strategic Acquirers: The window for entry favors boutique sustainability assurance firms with ISO 14064-3 accreditation and established satellite imagery partnerships. Long-term viability rests on regulatory expansion rather than voluntary market cyclicality, positioning compliant assessors for durable revenue streams. The signal to watch is mutual recognition agreements between national carbon accounting frameworks, which would consolidate verification demand around internationally portable standards.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Enabled MRV Platform Launch | Immutable audit trails meet CSRD tamper-evident documentation requirements for Dutch industrial filers. |
| Accredited Assessor Training Expansion | India and Brazil capacity addresses supply bottlenecks from ISO 14064-3 certification scarcity. |
| Satellite Imagery Partnership | Hyperspectral imaging access compresses verification cycle times for Amazon basin forest carbon developers. |
| Integrated Sustainability Assurance Bundle | Combined verification and supply chain risk assessment targets private equity ESG due diligence demand. |
| Local Regulation Certification Program | Jurisdiction-specific framework alignment captures sovereign carbon pricing expansion in emerging markets. |
Research Methodology
Multi-period observation of verification body accreditation expansion, CSRD implementation timelines, and satellite imagery technology deployment anchored the trend analysis, supplemented by interviews with sustainability officers at German automotive manufacturers, ESG due diligence leads at London-based private equity firms, certification managers at Verra and Gold Standard, and procurement directors at Indian industrial conglomerates. Secondary validation drew from EPA greenhouse gas reporting program filings, EU CSRD regulatory texts, ISO 14064-3 technical documentation, and Bureau of Indian Standards PLI scheme notifications. Bottom-up demand modeling triangulated against top-down regulatory mandate sizing.
Input-output matrices mapped verification service demand across methodological approaches, end-user sophistication tiers, and technology integration depth. Segmentation dimensions modeled included verification method, customer type, technology platform, and certification standard adoption. CAGRs were derived from regression analysis of historical accreditation growth rates and regulatory mandate expansion trajectories. Industry-specific forecast inputs incorporated EU CSRD phased implementation schedules and India's PLI-linked disclosure rollout pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to protocol fragmentation risk and mutual recognition agreement negotiations between national carbon accounting frameworks. A model refresh is warranted upon material change in EU CSRD enforcement stringency or emergence of competing blockchain verification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market