
 Green Technology and Sustainability Market | 2026-2036
Green Technology and Sustainability Market Size, Share, and Industry Trends Forecast 2026-2036
Green Technology and Sustainability Market Intelligence
Corporate procurement departments are reorganizing supplier requirements around carbon accounting and lifecycle transparency, displacing traditional cost-only sourcing. Siemens anchors its position through deep manufacturing scale in industrial energy systems. Schneider Electric differentiates via integrated software-hardware platforms for building efficiency. General Electric Company leverages its turbine heritage to dominate utility-scale wind installations across multiple continents.
Green technology and sustainability encompasses engineered systems, digital platforms, and resource-efficient processes designed to reduce environmental impact while maintaining economic output, typically incorporating photovoltaic conversion efficiencies above 20 percent or energy storage densities exceeding 150 watt-hours per kilogram. Its primary commercial purpose is enabling organizations to meet regulatory thresholds while lowering operational resource consumption. Energy Storage is recording the fastest expansion as grid operators deploy lithium-ion and emerging solid-state systems for renewable intermittency management. Solar Power occupies the largest installed base but faces margin compression as module manufacturing commoditizes. Sustainable Agriculture within the Application dimension is attracting new software entrants as precision irrigation and soil carbon monitoring gain buyer attention.
The EU Green Deal, CSRD, and REACH framework collectively mandate emissions disclosure, restrict hazardous inputs, and impose circular economy obligations on products sold in Europe. EPA regulations in the United States and China's dual carbon goals under MEE direction impose parallel compliance burdens, forcing vendors to architect multi-jurisdiction certification strategies. Stakeholders must decide whether to build proprietary compliance infrastructure or embed third-party verification platforms as regulatory fragmentation intensifies.
Market Dynamics
Corporate procurement departments are reorganizing supplier requirements around carbon accounting and lifecycle transparency, displacing traditional cost-only sourcing as the dominant selection logic. This shift compresses vendor qualification timelines while elevating embedded emissions data to a primary contract variable.
Growth Catalysts
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive forces emissions disclosure across value chains, creating immediate demand for carbon accounting software and verification services from European manufacturers.
- Lithium-ion grid storage:Utility operators deploy battery systems for renewable intermittency management, pulling demand for power conversion hardware and grid integration services.
- Industrial corridor retrofitting:Germany's manufacturing belt drives facility upgrades for scope emissions compliance, concentrating capital deployment in energy systems and process electrification.
Market Restraints
- Critical mineral supply concentration:Cobalt and lithium processing concentrates in a narrow geographic band, exposing battery manufacturers to input volatility and geopolitical friction.
- Interconnection queue delays:Grid operators face years-long backlogs for renewable project approvals, freezing capital deployment regardless of technology readiness.
- Green premium compression:Module manufacturing commoditization erodes margins across solar supply chains, limiting reinvestment capacity for next-generation efficiency gains.
Strategic Opportunities
- Precision agriculture software:Soil carbon monitoring and variable-rate irrigation create white space for digital platforms in sustainable agriculture applications.
- US IRA production incentives:Domestic content bonuses and tax credits under the Inflation Reduction Act attract manufacturing investment across battery and clean hydrogen value chains.
- Building-to-grid integration:Convergence of building automation software with vehicle-to-home charging systems enables new revenue streams for facility energy managers.
Industry Challenges
- Scope 3 data collection:Suppliers lack standardized emissions measurement protocols, forcing buyers to build proprietary verification infrastructure or accept data gaps.
- Legacy asset stranding:Industrial incumbents face write-down pressure on fossil-dependent equipment before depreciation cycles complete, complicating capital allocation.
- Multi-jurisdiction certification:REACH, EPA, and China's MEE impose overlapping but non-identical compliance burdens, fragmenting product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Technology and Sustainability Market |
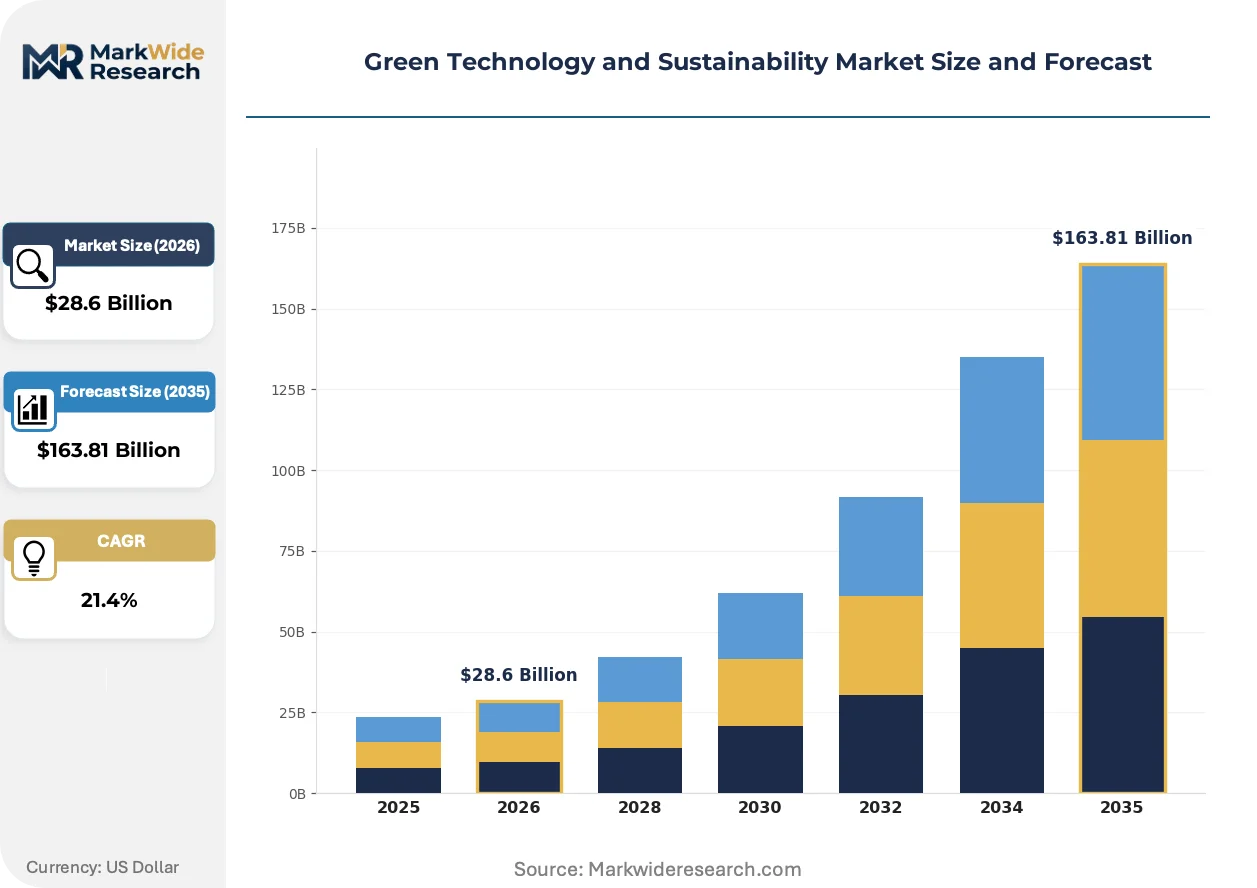
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $163.81 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Solar Power, Wind Energy, Biofuels, Energy Storage Application: Waste Management, Water Treatment, Energy Efficiency, Sustainable Agriculture End User: Residential, Commercial, Industrial, Government Service Type: Consulting, Installation, Maintenance, Product Sales |
| Companies Covered | General Electric Company, Schneider Electric, Siemens, IBM Corporation, SAP, Microsoft Corporation, Salesforce, Inc., Xylem, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Technology and Sustainability Market Strategic Shifts & Innovations
Digital platforms and engineered hardware are converging to reshape how environmental performance is measured, verified, and monetized across industrial supply chains. Three distinct vectors are compressing traditional service models and creating new competitive terrain.
Solid-state battery chemistry is fragmenting the energy storage landscape by replacing liquid electrolytes with ceramic or polymer alternatives that eliminate thermal runaway risk. Automotive OEMs and grid operators pilot these systems for electric vehicle and stationary applications, though manufacturing scale remains constrained by sintering process yields. This technology is fragmenting incumbent lithium-ion supply relationships as buyers diversify qualification portfolios beyond dominant cell suppliers.
REACH framework restrictions on hazardous substance inputs are forcing reformulation across electronics and industrial equipment supply chains. The European Chemicals Agency's substance of very high concern list expands annually, compelling vendors to redesign products for circular economy compliance or exit European markets. Battery and solar inverter manufacturers face the steepest compliance curves as they balance performance specifications against restricted material substitutions.
Corporate buyers now require tiered supplier emissions disclosure before contract execution, replacing post-award sustainability questionnaires. Industrial procurement functions embed carbon thresholds alongside price and delivery in vendor scorecards, compressing qualification cycles for uncertified suppliers. This pattern concentrates most visibly in German automotive and machinery supply chains, where OEMs cascade CSRD obligations downstream through binding supplier codes.
Green Technology and Sustainability Market Segmentation
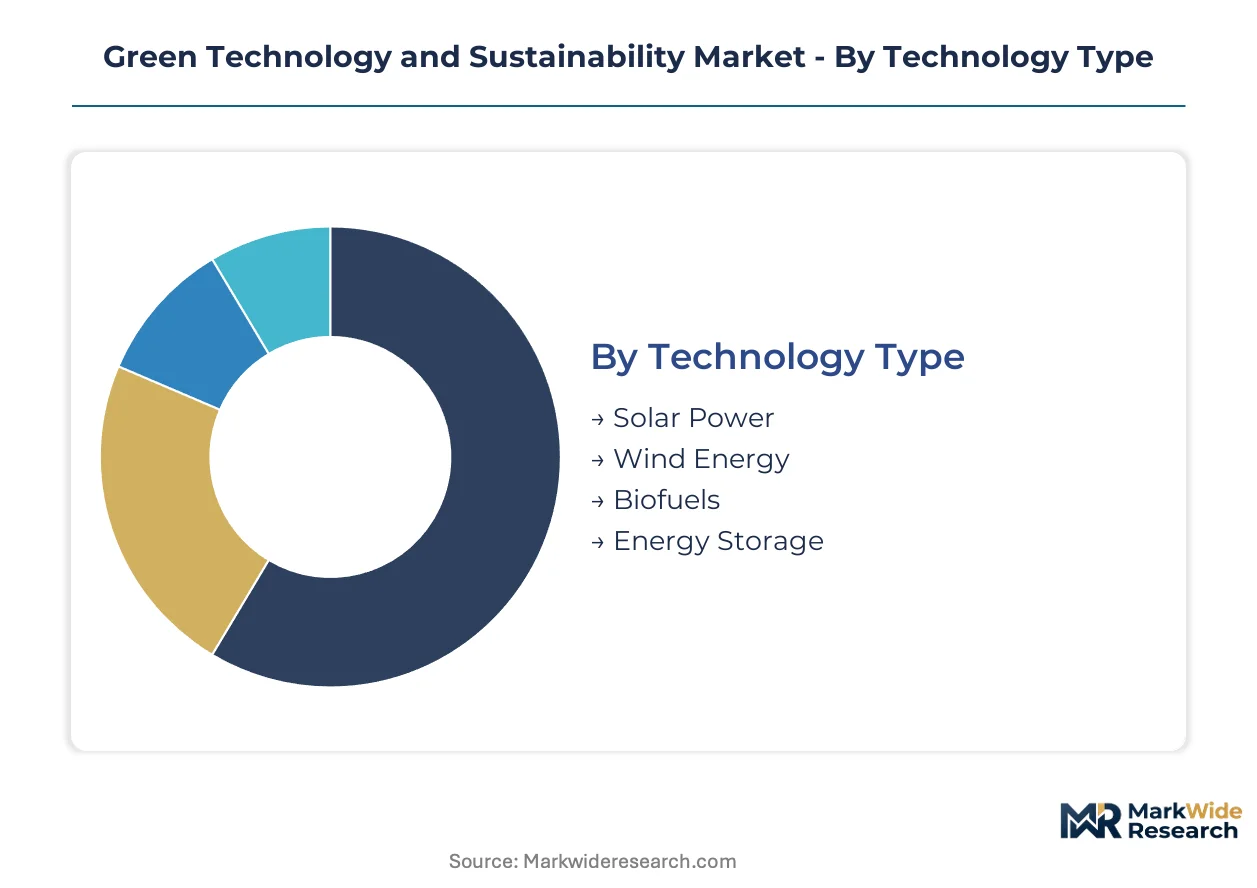
Segmentation in green technology reveals how procurement priorities diverge across technology maturity, regulatory exposure, and capital intensity. Buyers deploy distinct evaluation frameworks for hardware-intensive versus service-based offerings, creating non-overlapping competitive arenas.
Technology Type:
Margin pools concentrate in systems requiring specialized integration expertise and long-term performance guarantees rather than commoditized component supply.
- Energy Storage:Lithium-ion and emerging solid-state battery systems store electrical energy at densities exceeding 150 watt-hours per kilogram for grid and mobility applications. Demand clusters in Germany's industrial corridor as manufacturers retrofit facilities for scope emissions compliance and backup power resilience.
- Solar Power:Photovoltaic conversion systems achieve efficiencies above 20 percent through crystalline silicon or thin-film architectures. Module manufacturing commoditization erodes margins across supply chains, though utility-scale installations in India and the United States sustain volume throughput.
- Wind Energy:Utility-scale turbine installations leverage blade aerodynamics and generator scaling for capacity factors above 35 percent. Offshore project pipelines in Denmark and the United Kingdom drive nacelle and foundation demand.
- Biofuels:Liquid fuel substitutes derived from agricultural feedstocks or waste streams power aviation and heavy transport segments. Indonesia and Brazil dominate feedstock cultivation for international offtake.
The dominant share belongs to Solar Power, while Energy Storage is closing the gap fastest.
Application:
Application selection correlates with regulatory enforcement intensity and capital availability across end-use sectors.
- Energy Efficiency:Building automation, industrial process optimization, and HVAC retrofitting reduce consumption per unit output. Germany's manufacturing belt drives facility upgrades as CSRD disclosure mandates compress reporting timelines.
- Sustainable Agriculture:Precision irrigation, soil carbon monitoring, and variable-rate input application optimize resource use per hectare. Software entrants target this white space as buyer attention shifts toward agricultural emissions accounting.
- Water Treatment:Membrane filtration, biological processing, and desalination systems reclaim or purify water for industrial and municipal reuse. Australia's drought-prone regions and California's agricultural valleys sustain membrane replacement cycles.
- Waste Management:Circular economy infrastructure including sorting, anaerobic digestion, and materials recovery extracts value from waste streams. The EU Green Deal's circular economy obligations force vendor redesign for European market access.
Energy Efficiency commands the largest deployment capital, though Sustainable Agriculture is gaining share fastest among software-centric buyers.
End User:
Customer type determines contract structure, with industrial buyers demanding performance guarantees and residential segments prioritizing financing accessibility.
- Industrial:Manufacturing, extraction, and processing facilities deploy heavy energy systems and process electrification. Corporate procurement departments now embed carbon thresholds alongside price in vendor scorecards.
- Commercial:Office buildings, retail chains, and logistics centers adopt building automation and on-site generation for operational cost control. ESG-linked financing accelerates rooftop solar and battery installations.
- Government:Municipal, state, and national entities procure infrastructure through public tender frameworks with domestic content requirements. The US IRA production incentives attract manufacturing investment across battery and clean hydrogen value chains.
- Residential:Single-family and multi-family housing units adopt distributed solar, heat pumps, and smart thermostats through lease or loan structures. Interconnection queue delays freeze capital deployment regardless of technology readiness.
Industrial end users generate the highest contract values, while Commercial segments are expanding most quickly through green lease standards.
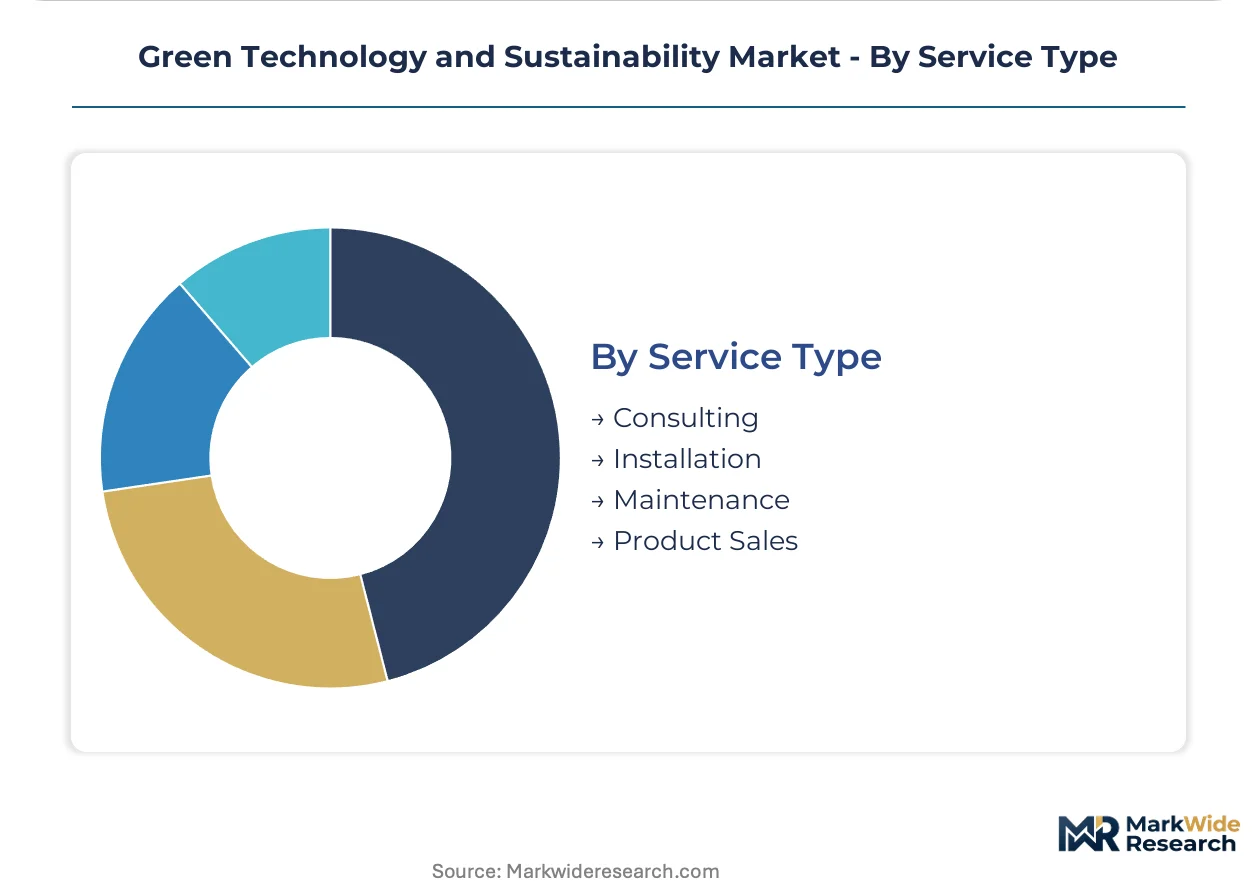
Service Type:
Service mix reflects buyer capability gaps, with sophisticated industrial clients internalizing installation while outsourcing complex system design.
- Consulting:Carbon accounting, lifecycle assessment, and compliance strategy advisory supports regulatory navigation. CSRD disclosure mandates create immediate demand for verification services from European manufacturers.
- Installation:Engineering, procurement, and construction contractors deploy hardware systems with performance guarantees. Grid operators face years-long backlogs for renewable project approvals.
- Product Sales:Component and equipment supply without attached services suits buyers with in-house integration capabilities. Green premium compression limits reinvestment capacity for next-generation efficiency gains.
- Maintenance:Long-term service agreements ensure availability and output performance for utility-scale assets. Solid-state battery chemistry fragments incumbent supply relationships as buyers diversify qualification portfolios.
Installation captures the dominant revenue share, while Consulting is climbing the fastest as disclosure mandates multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Germany, the United States, and China concentrate procurement authority for green technology systems, while policy enforcement in the European Union and subsidy deployment in North America reshape vendor qualification requirements across value chains.
United States
Utility-scale solar developers and battery integrators drive equipment procurement as grid operators manage renewable intermittency. The Inflation Reduction Act's domestic content bonuses attract manufacturing investment across battery and clean hydrogen value chains. Texas and California industrial clusters deploy energy storage systems for backup power resilience and emissions compliance.
Germany
Automotive OEMs and machinery manufacturers retrofit facilities for scope emissions compliance under compressed CSRD timelines. The EU Green Deal and REACH framework mandate circular economy obligations on products sold in Europe. The industrial corridor spanning Bavaria and Baden-Württemberg concentrates capital deployment in process electrification and building automation.
China
State-owned grid operators and provincial manufacturers deploy lithium-ion systems at scale for renewable integration. Dual carbon goals under MEE direction impose parallel compliance burdens on industrial emitters. The Yangtze River Delta manufacturing belt hosts concentrated production of photovoltaic modules and power conversion hardware.
India
Domestic solar developers and agricultural processors adopt precision irrigation and distributed generation for cost control. PLI scheme incentives attract manufacturing investment across solar cell and module value chains. Gujarat and Maharashtra industrial zones drive facility upgrades for energy efficiency and water treatment infrastructure.
United Kingdom
Offshore wind project developers and building retrofit contractors procure nacelle components and automation systems. ESG-linked financing accelerates rooftop solar and battery installations across commercial portfolios. The North Sea offshore pipeline and London commercial real estate market sustain demand for grid integration services.
Green Technology and Sustainability Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with embedded software capabilities, creating a tiered structure where scale-driven hardware manufacturers compete against cloud-native platform providers. Siemens and Schneider Electric anchor the integrated systems tier, while IBM and Microsoft occupy the data and analytics layer. Dominant competitive moves include portfolio diversification into adjacent sustainability software and strategic partnerships bridging operational technology with enterprise IT infrastructure.
Among diversified industrial conglomerates, General Electric Company and Siemens exemplify the hardware-anchored archetype with deep manufacturing heritage in energy systems. Schneider Electric occupies a position within the integrated platform tier, representing vendors that combine building automation hardware with lifecycle management software. SAP and Oracle Corporation sit within the enterprise software layer, anchoring carbon accounting and ESG disclosure functionality for procurement departments reorganizing supplier requirements.
| Leading Market Players |
|---|
| General Electric Company |
| Schneider Electric |
| Siemens |
| IBM Corporation |
| SAP |
| Microsoft Corporation |
| Salesforce, Inc. |
| Xylem |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
REACH substance restrictions gate European market access for battery and solar inverter manufacturers while simultaneously stratifying price tiers based on compliance certification levels. Buyers in Germany's automotive corridor now embed ECHA substance-of-very-high-concern screening into vendor scorecards alongside unit economics.
Pricing Analysis
Next-generation solid-state battery systems command premium positioning against incumbent lithium-ion and legacy lead-acid alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in crystalline silicon modules is intensifying because manufacturing capacity expansion in China and Southeast Asia outpaces demand absorption. Residential distributed solar buyers exhibit highest price sensitivity while industrial EPC contractors prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites cobalt and lithium concentrate flows from DRC and Indonesian processing facilities to East Asian cell manufacturing. China, South Korea, and Japan anchor cathode active material production while Australia and Chile feed lithium carbonate and spodumene concentrate. Single-source vulnerability concentrates in DRC cobalt extraction and Chinese graphite anode processing. Distribution runs through long-term offtake contracts with automotive OEMs and utility grid operators rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized carbon accounting expertise sits in short supply relative to CSRD-mandated disclosure demand, compressing vendor qualification timelines for qualified verification platforms. Procurement departments now treat emissions data infrastructure as a core competency gap.
For Market Incumbents: Consolidate software-hardware integration capabilities through targeted capability acquisition in building automation and grid-edge control systems. Siemens and Schneider Electric face emerging cloud-native platform entrants attacking the middleware layer between operational technology and enterprise carbon accounting. Priority lever rests on deepening captive supply of solid-state battery cell capacity before qualification cycles lock in supplier relationships.
For New Entrants and Emerging Players: Lead with precision agriculture software targeting variable-rate irrigation and soil carbon monitoring white space in India's Gujarat and Maharashtra agricultural processing zones. Sustainable agriculture applications remain underpenetrated by incumbent industrial conglomerates. Go-to-market angle emphasizes API-first carbon data integration with existing farm management information systems rather than rip-and-replace hardware deployment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core sustainability software assets stranded within legacy energy or automation divisions. Long-term viability frames around decade-duration regulatory enforcement intensity rather than technology performance metrics alone. Signal to watch is CSRD audit finding severity escalation forcing mid-market manufacturers toward outsourced verification platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Platform Integration | Schneider Electric and SAP converge building automation with ESG disclosure functionality for German automotive procurement departments. |
| Solid-State Battery Qualification Partnership | Automotive OEMs diversify cell supplier portfolios beyond dominant lithium-ion incumbents through ceramic electrolyte pilot programs. |
| Precision Agriculture Software Launch | Digital entrants target soil carbon monitoring white space as India's PLI scheme attracts agricultural processing investment. |
| Domestic Content Manufacturing Scale-Up | US IRA production incentives pull battery and electrolyzer assembly into Texas and California industrial clusters. |
| Building-to-Grid Integration Development | Convergence of HVAC automation with vehicle-to-home charging creates new revenue streams for facility energy managers. |
Research Approach
A spread of perspectives from utility planning officers, EPC contractors, corporate sustainability directors, and grid operators converged on the working assumptions around interconnection queue timelines and CSRD compliance cost trajectories. Primary field engagement with battery integrators and solar project developers combined with secondary validation from FERC interconnection databases, IEA technology roadmaps, ECHA substance restriction updates, and SEC climate disclosure filings. Bottom-up project pipeline aggregation triangulated against top-down regulatory mandate impact modeling.
Segmentation dimensions modeled span technology type, application sector, end-user category, and service delivery mode across the projection horizon. CAGRs derive from installed capacity buildout curves, policy incentive phase-out schedules, and technology cost reduction experience rates. Industry-specific forecast inputs include lithium carbonate price volatility bands and solid-state battery manufacturing yield improvement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity and IRA credit continuity would require recalibration. Forecasts reflect documented assumptions around mineral supply expansion and grid interconnection processing capacity. Practitioners should keep alternative scenarios live as REACH substance restriction expansion pace and China dual carbon goal implementation rigor evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Emission Management Software Market
Environment & Sustainability
Ecotoxicological Studies Market
Environment & Sustainability
Smart Water Monitoring Market
Environment & Sustainability
Residential Water Treatment Equipment Market
Environment & Sustainability
Recycled Ocean Plastics Market
Environment & Sustainability
North America Waste Recycling Services Market
Environment & Sustainability
Wheeled Bins Market
Environment & Sustainability
Global Waste Management Software Market
Environment & Sustainability
Global Waste Oil Market
Environment & Sustainability
Lithium-Ion Battery Reuse and Recycling Market
Environment & Sustainability
Smart Waste Sorting Bin Market
Environment & Sustainability
Energy Efficient Window and Door Market
Environment & Sustainability
Saudi Arabia Medical Waste Management Market
Environment & Sustainability
Carbon Credit Trading Platform Market
Environment & Sustainability
GCC Green Cement Market
Environment & Sustainability
India Bio-Medical Waste Management Market