
 Europe Green Cement Market | 2026-2036
Europe Green Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Cement Market Intelligence
A capital-intensity divergence between integrated kiln operators and import-dependent blenders is unwinding competitive stability across the European supply base. CRH plc leverages its vertical control over limestone quarries and grinding assets to sustain margin capture under carbon border adjustments. Heidelberg Cement anchors its position through energy-efficient precalciner technology deployed across Central European plants. Vicat Group differentiates via geopolymer research partnerships with French infrastructure agencies.
Europe green cement denotes hydraulic binders manufactured with reduced clinker content, supplementary cementitious materials such as fly ash or slag, and processes limiting carbon dioxide emissions to below conventional Portland thresholds. These formulations achieve compressive strengths of 30–50 MPa while serving structural applications in buildings, roads, and bridges where embodied carbon reporting is mandatory. Blended cement occupies the largest volume share as contractors substitute Portland in standard-grade pours, while geopolymer technology leads growth in precast segments where curing time flexibility offsets premium pricing. Carbon capture installations at kiln stacks concentrate investment pools among operators with captive limestone reserves and grid access for CO2 offtake.
The EU Emissions Trading System and REACH chemical registration frameworks compel producers to document lifecycle carbon and material safety across supply chains. The EU Green Deal's 55% emissions reduction target for 2030 is forcing clinker ratio cuts and biomass fuel transitions. ECHA's evolving substance restrictions further constrain traditional additives, redirecting R&D toward alkali-activated binders. Stakeholders must monitor carbon border adjustment implementation schedules and pre-certify products under upcoming Construction Products Regulation revisions to secure public tender eligibility.
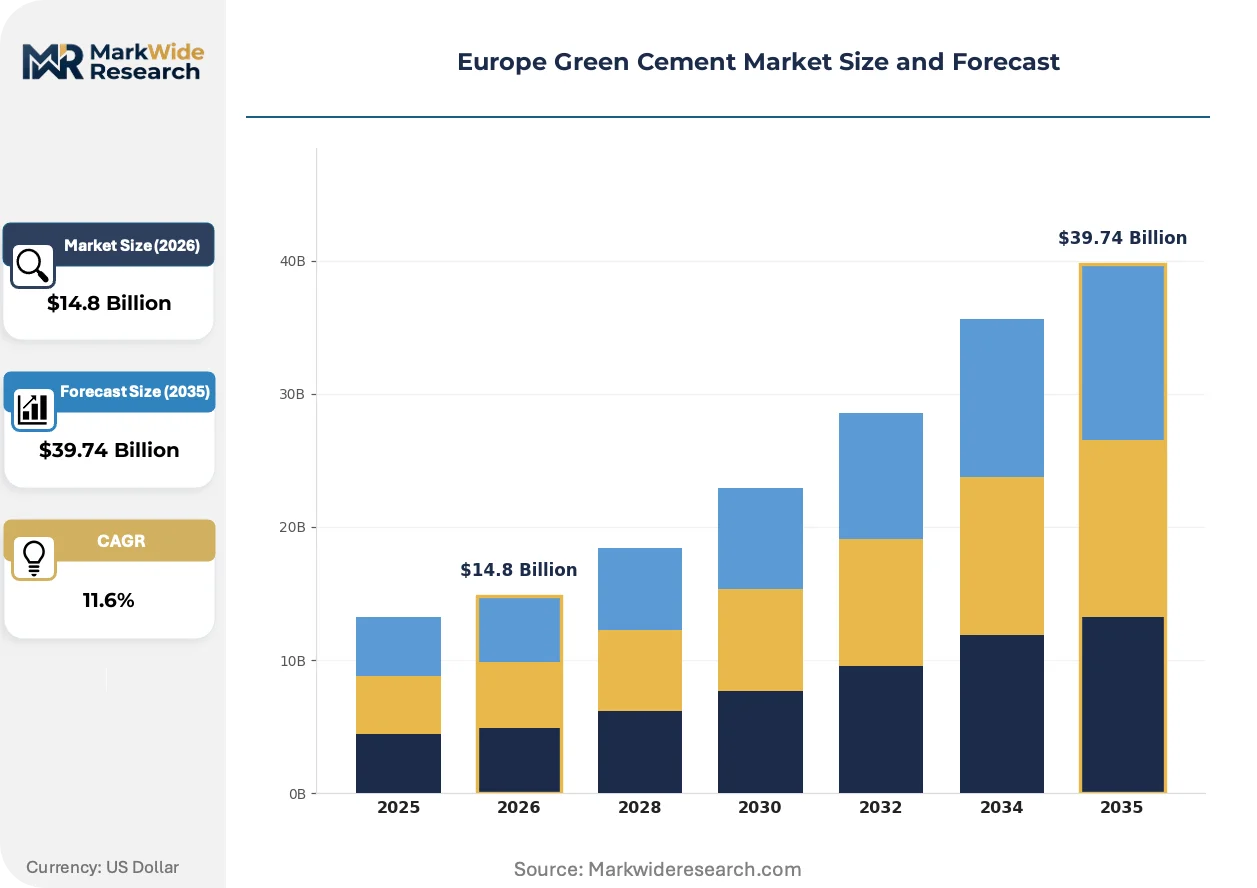
Market Dynamics
The EU ETS carbon pricing mechanism is compressing margins for high-clinker producers while rewarding operators with biomass co-firing capabilities and carbon capture retrofits. This regulatory pressure is redistributing competitive advantage toward integrated kiln owners with captive limestone reserves.
Growth Catalysts
- EU Green Deal 55% target:The 2030 emissions reduction mandate is accelerating kiln technology retrofits and biomass fuel transitions across German and French production facilities.
- Municipal procurement mandates:Rhine-Ruhr corridor cities now require low-clinker formulations in public infrastructure tenders, creating guaranteed offtake for blended cement producers.
- Carbon capture installations:Stack capture technology at Central European plants is qualifying operators for EU Innovation Fund grants and securing CO2 offtake agreements with industrial gas handlers.
Market Restraints
- Limestone reserve concentration:Captive quarry access concentrates among three major integrated groups, limiting blender access to cost-competitive clinker substitutes.
- Biomass fuel volatility:Agricultural waste and processed refuse-derived fuel prices fluctuate with seasonal crop yields and waste stream competition from power generators.
- REACH additive restrictions:ECHA's evolving substance limitations are constraining traditional chromium reducers and grinding aids, forcing reformulation cycles.
Strategic Opportunities
- Italian residential retrofit wave:Superbonus 110% tax incentives are channeling renovation spending toward low-carbon building materials in Lombardy and Veneto.
- Geopolymer precast expansion:French infrastructure agencies are piloting alkali-activated binders for bridge decks and tunnel segments where curing time flexibility offsets premium pricing.
- Carbon border adjustment timing:Early certification under the Construction Products Regulation revision will secure eligibility for public tenders before full CBAM implementation.
Industry Challenges
- Process engineer scarcity:Kiln operators struggle to recruit specialists capable of managing precalciner retrofits and alternative fuel co-combustion systems.
- Certification timeline compression:EPD validation and CE marking updates for novel SCM blends require 18-24 month approval windows that lag behind product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Cement Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland, Blended, Geopolymer, Others End User: Residential Construction, Commercial Buildings, Infrastructure, Industrial Facilities Application: Roads, Bridges, Residential, Industrial Technology: Carbon Capture, Biomass Fuel, Waste Material Incorporation, Energy-efficient Production |
| Companies Covered | CRH plc, Vicat Group, Lafarge Holcim, Titan Cement Group, Cementir Holding, Heidelberg Cement, Buzzi Unicem, Euro Cement Group, Cemex, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Cement Market Strategic Shifts & Innovations
Electrification of clinker production and alternative binder chemistry are converging to redefine manufacturing economics. These shifts are compressing the cost gap between conventional Portland and low-carbon formulations.
Calcined clay activation is supplanting fly ash as the dominant supplementary cementitious material in blended formulations. Precast concrete manufacturers in the Benelux region are adopting metakaolin-enriched binders at accelerating rates. This substitution is supplanting import-dependent supply chains for coal combustion residuals while enabling 40% clinker reduction without strength penalty.
REACH chemical registration frameworks are tightening disclosure requirements for chromium VI content and heavy metal traces in cement additives. Manufacturers must now document full material safety data across supply chains to maintain CE marking validity. Blended cement categories with novel SCM combinations face the steepest compliance burden as ECHA evaluates substance hazard classifications.
Embodied carbon reporting is becoming a mandatory tender qualification criterion for public construction contracts. General contractors in Germany and France now require EPD-certified products with verified GWP figures below 400 kg CO2 equivalent per ton. This specification shift is compressing supplier lists to pre-qualified low-carbon producers and excluding import-dependent blenders without certified production data.
Europe Green Cement Market Segmentation
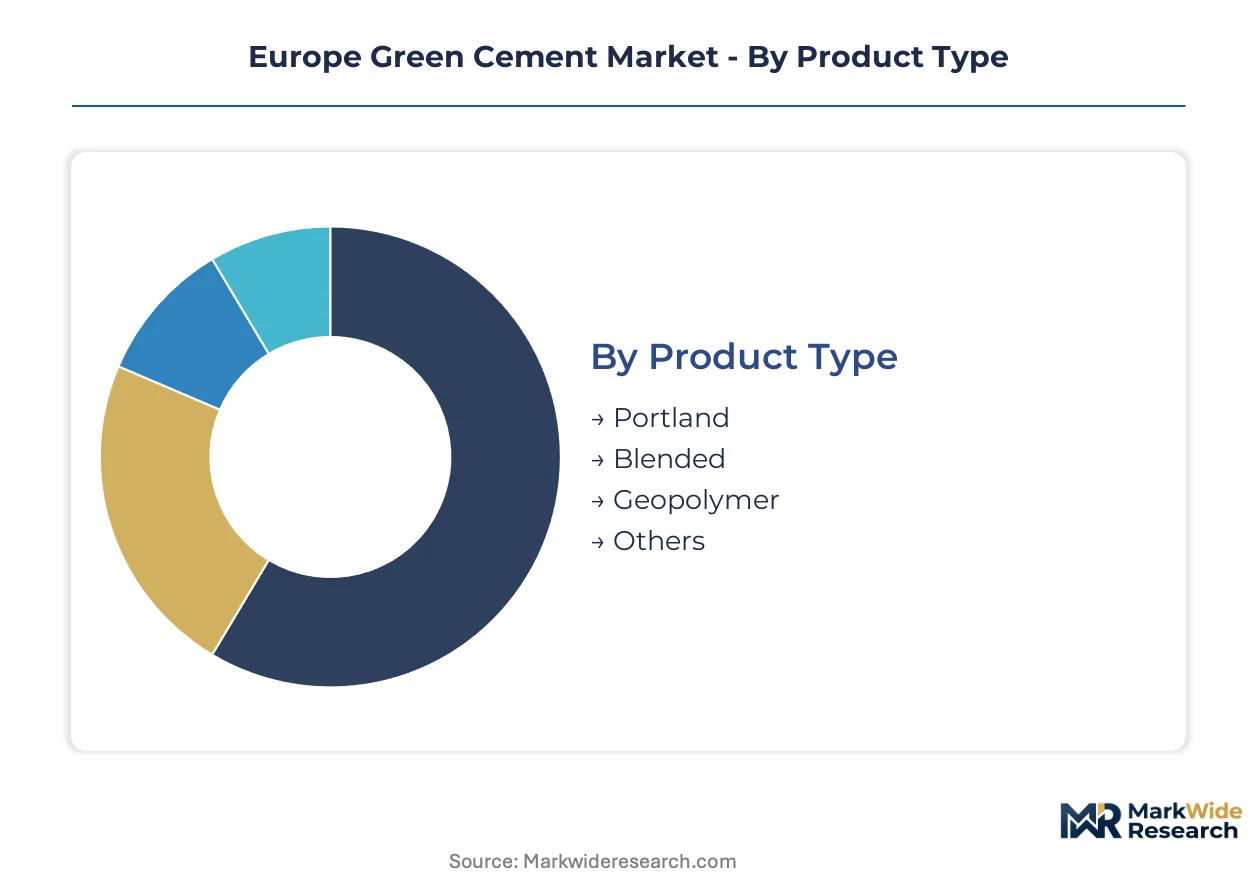
Segmentation in the Europe green cement market reveals how regulatory pressure and procurement mandates are concentrating volume across distinct formulation and technology categories. Producers must align product portfolios with EU ETS compliance tiers and municipal tender specifications to secure offtake.
Product Type:
Margin pools concentrate in formulations achieving the steepest clinker reduction without triggering REACH reformulation costs or EPD recertification delays.
- Blended:These formulations combine Portland clinker with calcined clay, slag, or fly ash to achieve 30–50% carbon reduction. Demand concentrates in Germany's Rhine-Ruhr corridor where municipal procurement mandates require low-clinker content for public infrastructure tenders.
- Geopolymer:Alkali-activated binders using metakaolin or industrial waste streams eliminate clinker entirely. French infrastructure agencies are piloting these formulations for bridge decks and tunnel segments where extended curing windows offset premium pricing.
- Portland:Conventional formulations with carbon capture retrofits retain share in segments where contractors require familiar handling characteristics and rapid strength development.
- Others:Emerging categories include magnesium-based cements and bio-cements using bacterial mineralization, currently limited to research partnerships and demonstration projects.
Blended cement holds installed capacity across Central European kiln networks. Geopolymer is rotating up the share rankings as ECHA restrictions on traditional additives accelerate alkali-activated binder development.
End User:
Volume distribution follows public construction budgets and retrofit incentive programs rather than private development cycles.
- Residential Construction:Italy's Superbonus 110% tax incentives are channeling renovation spending toward low-carbon materials in Lombardy and Veneto, creating guaranteed demand for EPD-certified products.
- Infrastructure:Roads, bridges, and tunnels absorb the largest tonnage as EU Green Deal funding requires embodied carbon reporting below 400 kg CO2 equivalent per ton for tender eligibility.
- Commercial Buildings:Office and retail developments in France and Germany specify blended formulations to meet CSRD disclosure requirements and green building certification thresholds.
- Industrial Facilities:Manufacturing plants and logistics centers prioritize rapid-strength Portland variants with carbon capture, balancing emissions targets with construction schedule constraints.
Infrastructure commands the dominant share of annual tonnage. Residential construction is climbing fastest as retrofit incentives redirect renovation material specifications.
Application:
Performance requirements and curing time flexibility determine formulation selection across structural use cases.
- Bridges:Geopolymer and high-slag blended cements dominate where design life exceeds 100 years and chloride resistance is critical. French agencies specify these for marine-exposed superstructures.
- Roads:Standard-grade blended formulations with calcined clay achieve the cost-performance balance for pavement and highway base layers across German federal transport contracts.
- Residential:Foundations and structural walls employ fly ash or slag blends where contractors prioritize pumpability and finish quality over extreme durability.
- Industrial:Heavy-duty floors and containment structures use rapid-hardening variants with limited clinker reduction to withstand chemical exposure and abrasion.
Road applications hold the largest installed formulation capacity. Bridge specifications are advancing fastest as asset owners adopt whole-life carbon accounting.
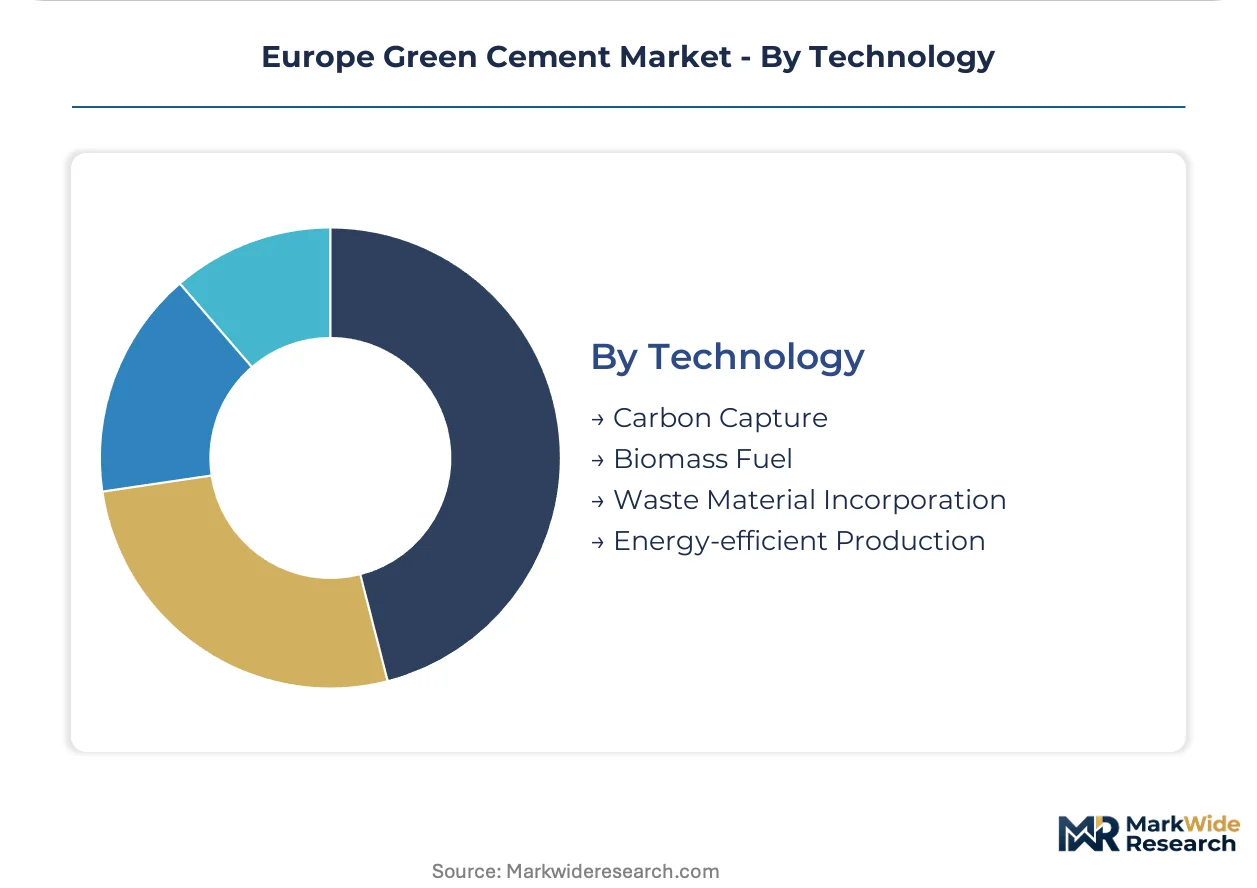
Technology:
Capital deployment concentrates where EU Innovation Fund grants and carbon border adjustment pre-certification create first-mover advantages.
- Carbon Capture:Post-combustion amine and calcium looping systems at kiln stacks qualify operators for grant funding and secure CO2 offtake agreements with industrial gas handlers in the Benelux region.
- Energy-efficient Production:Precalciner retrofits and waste heat recovery systems anchor margin defense for integrated producers with captive limestone reserves across Central Europe.
- Biomass Fuel:Agricultural waste and processed refuse-derived fuel co-firing reduces scope 1 emissions but faces price volatility from seasonal crop yields and competition from power generators.
- Waste Material Incorporation:Steel slag, fly ash, and construction demolition waste substitution in blended formulations depends on import logistics and ECHA substance classification stability.
Energy-efficient production holds the broadest installed base. Carbon capture is gaining share fastest as EU ETS price levels justify capital intensity for stack retrofit projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing power through integrated kiln networks and captive limestone reserves, while Italian blenders face margin compression from import-dependent clinker substitution and volatile biomass fuel costs.
Germany
Rhine-Ruhr municipal procurement mandates and federal transport infrastructure budgets absorb the largest blended cement volumes. The EU ETS carbon pricing mechanism forces clinker ratio reductions while rewarding precalciner retrofits. Düsseldorf and Essen anchor production clusters where CRH plc and Heidelberg Cement defend margin capture through vertical quarry control.
France
Geopolymer pilot programs for bridge decks and tunnel segments drive alkali-activated binder demand from French infrastructure agencies. REACH compliance protocols and ECHA substance restrictions redirect R&D away from traditional chromium reducers. Lyon and Marseille concentrate precast manufacturing where Vicat Group partnerships with public works departments validate extended curing formulations.
Italy
Superbonus 110% tax incentives channel residential retrofit spending toward EPD-certified low-carbon materials in Lombardy and Veneto. The EU Green Deal emissions benchmarks accelerate biomass fuel transitions at Central Italian plants. Milan and Turin construction markets prioritize embodied carbon reporting for tender eligibility.
Netherlands
Benelux precast manufacturers adopt metakaolin-enriched binders at accelerating rates as calcined clay supplants import-dependent fly ash. Carbon capture installations at Rotterdam-area kiln stacks qualify operators for EU Innovation Fund grants. The Port of Rotterdam industrial cluster secures CO2 offtake agreements with industrial gas handlers.
Poland
Eastern European infrastructure contracts specify blended formulations as EU ETS compliance costs penetrate contractor procurement decisions. CE marking updates for novel SCM combinations face 18-24 month validation windows. Warsaw and Kraków construction markets absorb rising volumes of low-clinker cement for road and residential foundation applications.
Europe Green Cement Market Key Industry Players
Concentration sits with integrated kiln operators possessing captive limestone reserves and carbon capture retrofit capabilities. Three major groups control quarry access across Central Europe, compressing blender margins and redistributing competitive advantage toward backward-integrated producers. Strategic archetypes include vertically integrated quarry-to-kiln operators, import-dependent grinding specialists, and geopolymer research partnerships. Dominant competitive moves encompass precalciner technology deployment and EU Innovation Fund grant capture for stack capture installations.
Among Ireland-based integrated groups, CRH plc exemplifies the quarry-control archetype through limestone reserve ownership. French specialists Vicat Group occupy a position within the alkali-activated binder research tier. German operators Heidelberg Cement anchor the energy-efficient production category through Central European plant networks.
| Leading Market Players |
|---|
| CRH plc |
| Vicat Group |
| Lafarge Holcim |
| Titan Cement Group |
| Cementir Holding |
| Heidelberg Cement |
| Buzzi Unicem |
| Euro Cement Group |
| Cemex |
| Others |
Cost & Logistics Intelligence
Calcined clay activation displacing fly ash in blended formulations simultaneously redraws raw material sourcing maps and compresses the cost premium for low-clinker cement. This substitution shifts procurement gravity from import-dependent coal combustion residuals toward domestic kaolin deposits, altering freight economics and supplier power across Central European production networks.
Pricing Analysis
The customization-premium spread widens between standard-grade blended cement and project-specific geopolymer formulations with extended curing protocols. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and embodied carbon intensity, with EPD-validated products commanding measurable premiums over uncertified alternatives. Pricing pressure stems from EU ETS carbon cost pass-through to high-clinker producers, compressing margins for operators without biomass co-firing capabilities. Import-dependent blenders exhibit highest price sensitivity due to volatile clinker substitute logistics, while integrated kiln owners with captive limestone reserves maintain pricing power.
Supply Chain Analysis
Germany, France, and Italy anchor clinker and blended cement production across the European supply base. Raw material flows draw from captive limestone quarries, steel slag from Ruhr industrial clusters, and calcined clay from Benelux kaolin deposits. Single-source vulnerability concentrates in biomass fuel supply chains where agricultural waste competition from power generators creates seasonal price spikes. Distribution runs through bulk terminal networks serving Rhine-Ruhr municipal procurement hubs and Mediterranean port clusters for Italian export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting services and EPD certification consulting are expanding faster than physical cement production, creating recurring-revenue layers that outpace hardware margins. This service-attach dynamic rewards operators bundling embodied carbon verification with material supply contracts.
For Market Incumbents: Compound quarry reserve control with carbon capture retrofit deployment to defend margin capture under EU ETS price escalation. Prioritize precalciner technology upgrades across Central European plants to anchor energy-efficient production capacity. Lock in long-term CO2 offtake agreements with industrial gas handlers before carbon border adjustment full implementation.
For New Entrants and Emerging Players: Differentiate on alkali-activated binder chemistry for French infrastructure precast segments where curing time flexibility offsets premium positioning. Target Italian residential retrofit markets channeling Superbonus incentives toward EPD-certified low-carbon materials. Pursue research partnerships with municipal procurement agencies to validate novel supplementary cementitious material blends ahead of CE marking approval.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated operators with captive limestone reserves and carbon capture grant eligibility. Long-term viability hinges on EU Innovation Fund access and pre-certification under Construction Products Regulation revisions. Monitor carbon border adjustment implementation schedules as the critical inflection signal for import-dependent blender distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Precalciner Retrofit Deployment | Heidelberg Cement anchors margin defense through energy-efficient kiln technology across German production facilities. |
| Carbon Capture Installation | EU Innovation Fund grants qualify Rotterdam-area stack capture projects securing industrial gas handler offtake agreements. |
| Geopolymer Research Partnership | Vicat Group validates alkali-activated binders with French infrastructure agencies for bridge deck applications. |
| Biomass Fuel Transition | Central Italian plants reduce scope 1 emissions through agricultural waste co-firing despite seasonal price volatility. |
| EPD Certification Investment | Pre-qualification under Construction Products Regulation revisions secures eligibility for Rhine-Ruhr municipal tenders. |
Research Approach
A spread of perspectives from kiln operations managers, municipal procurement officers, EPD certification specialists, and construction materials distributors converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through EU ETS emissions registries, REACH substance restriction updates, and national construction statistics from Eurostat and national statistical institutes. Bottom-up plant capacity assessments triangulated against top-down public infrastructure budget allocations across Germany, France, and Italy.
Segmentation dimensions modeled include product formulation type, end-use construction sector, structural application, and decarbonization technology deployment across the projection horizon. CAGRs derive from regression analysis against EU Green Deal emissions benchmarks and municipal procurement mandate implementation timelines. Forecast inputs incorporate kiln retrofit investment cycles, biomass fuel price volatility indices, and ECHA substance classification revision schedules.
Decision-makers should treat outputs as directional under sustained EU ETS price levels and REACH compliance stability; material deviation in carbon border adjustment timing or EPD certification delays would warrant model refresh. Recalibration cycles align with material shifts in EU Green Deal funding disbursement and Construction Products Regulation revision adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Solar Windows Market
Green Building Materials
Solar Frames Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Rebar Market
Green Building Materials
Green Cement Market
Green Building Materials
China Green Building Materials Market
Green Building Materials
Solar Glass Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Green Concrete Market
Green Building Materials
North America Green Buildings Market
Green Building Materials
Green Roof Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
North America Green Cement Market
Green Building Materials
Eco Flooring Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
United States Green Cement Market