
 Green Waterproofing Products Market | 2026-2036
Green Waterproofing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Green Waterproofing Products Market Foresight
Plant-derived polyurethane dispersions is broadening the addressable cost envelope for high-performance roofing membranes. Sika leverages its European formulation network to supply low-VOC liquid membranes meeting German DIBt standards. BASF anchors its position through backward integration into bio-based polyol feedstocks for construction-grade coatings.
Green waterproofing products encompass membrane systems and coating formulations engineered with renewable feedstocks, recycled content, or reduced hazardous air pollutants, typically achieving elastomeric elongation above 300% and VOC content below 50 g/L to seal building envelopes against liquid and vapor intrusion. Liquid membranes command the deepest specification penetration among product types due to seamless application over complex geometries, while cementitious coatings retain cost leadership in emerging markets with less stringent emissions enforcement. Polyurethane dominates material selection for below-grade applications demanding hydrostatic pressure resistance, whereas silicone formulations lead in UV-exposed roofing where thermal cycling endurance determines lifecycle value.
EPA VOC regulations for architectural coatings, REACH Annex XVII restrictions on isocyanate labeling, and LEED v4.1 material ingredient transparency credits collectively elevate compliance costs for conventional formulations while accelerating specification shifts toward certified green alternatives. China's MEE standards on construction material emissions and India's BIS waterproofing durability codes add parallel compliance layers for multinational suppliers. Stakeholders must track divergence between regional chemical hazard classifications and green certification point systems when allocating R&D and registration budgets across formulation platforms.
Market Dynamics
Commercial building energy retrofit mandates across Germany, the United States, and China are compressing specification cycles for low-VOC liquid membrane systems, forcing suppliers to accelerate certification timelines while reformulating around bio-based polyol feedstocks.
Growth Catalysts
- LEED v4.1 Material Ingredient Reporting:Transparency credits for hazardous substance disclosure redirect procurement toward certified green alternatives in commercial roofing and foundation applications.
- REACH Annex XVII Isocyanate Restrictions:Labeling requirements on solvent-borne polyurethane formulations elevate compliance costs for conventional products while opening specification pathways for waterborne dispersions.
- Building Energy Retrofit Mandates:Tightening thermal performance thresholds in Germany, the United States, and China concentrate demand for high-elongation membrane systems that seal aging envelopes.
Market Restraints
- Bio-Based Polyol Feedstock Volatility:Agricultural commodity price swings for castor oil and soybean derivatives compress margin stability for polyurethane dispersion manufacturers.
- Specialty Additive Supply Concentration:European and Chinese producers dominate silane-terminated polymer supply for moisture-cure systems, creating single-source vulnerability.
- Cementitious Coating Cost Floor:Inorganic waterproofing retains 40-60% price advantage in markets without VOC enforcement, limiting green premium capture in India and Southeast Asia.
Strategic Opportunities
- India BIS Waterproofing Durability Codes:Emerging enforcement of construction material performance standards creates first-mover advantage for certified membrane suppliers.
- Below-Grade Application Expansion:Hydrostatic pressure-rated bio-polyurethane systems penetrate data center and battery storage facility foundations.
- Direct-to-Contractor Digital Platforms:Specification tools that automate LEED credit calculation and regional code compliance bypass traditional distributor markup layers.
Industry Challenges
- Cross-Functional Formulation Expertise Gap:Polymer chemists with simultaneous competence in bio-feedstock processing and construction-grade durability testing command scarcity premiums.
- Multi-Jurisdiction Registration Timelines:Parallel EPA VOC, REACH Annex XVII, and China MEE construction material emission approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Waterproofing Products Market |
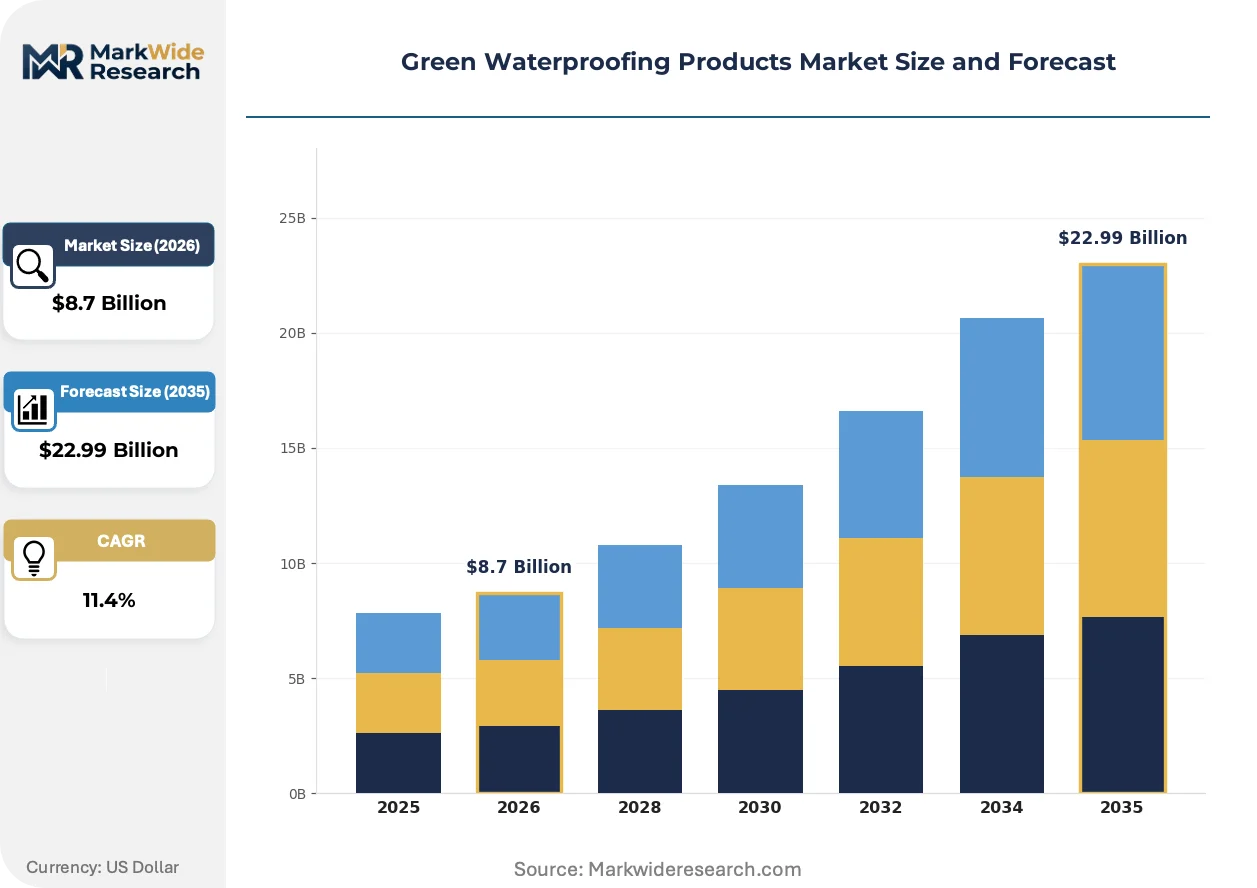
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Membranes, Sheet Membranes, Cementitious Coatings, Bituminous Coatings Application: Roofing, Foundation, Underground Structures, Bridges Material: Polyurethane, Silicone, Latex, Natural Rubber End User: Contractors, Homeowners, Commercial Developers, Government Agencies |
| Companies Covered | Sika, BASF, Dow, Fosroc, GAF Materials, Soprema Group, Carlisle Companies, Saint-Gobain, RPM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Waterproofing Products Market Shifts & Advancements
Formulation science and procurement infrastructure are converging to compress the cost-performance gap between bio-based and petroleum-derived waterproofing systems, with regulatory transparency requirements accelerating specification automation.
Plant-derived polyurethane dispersions is modularizing application workflows for complex roof geometries. Roofing contractors in Germany and the Netherlands are adopting spray-applied systems at triple the pace of conventional sheet membranes. This modularity is compressing labor cost differentials that previously favored cementitious coatings in commercial projects.
EPA VOC regulations for architectural coatings now mandate sub-50 g/L thresholds in 17 US states representing 60% of commercial construction value. The industrial consequence is forced reformulation of solvent-borne systems by Q4 2025. Below-grade polyurethane applications face the steepest technical adaptation burden as hydrostatic pressure resistance must be maintained without aromatic isocyanate content.
Specification decisions increasingly flow through automated compliance platforms that pre-filter products by regional code alignment. Distributor sales teams in California and New York are losing gatekeeper status to software tools that rank alternatives by LEED point contribution. This disintermediation is most visible in commercial office and multifamily residential verticals where institutional owners mandate portfolio-wide green certification.
Green Waterproofing Products Market Segmentation
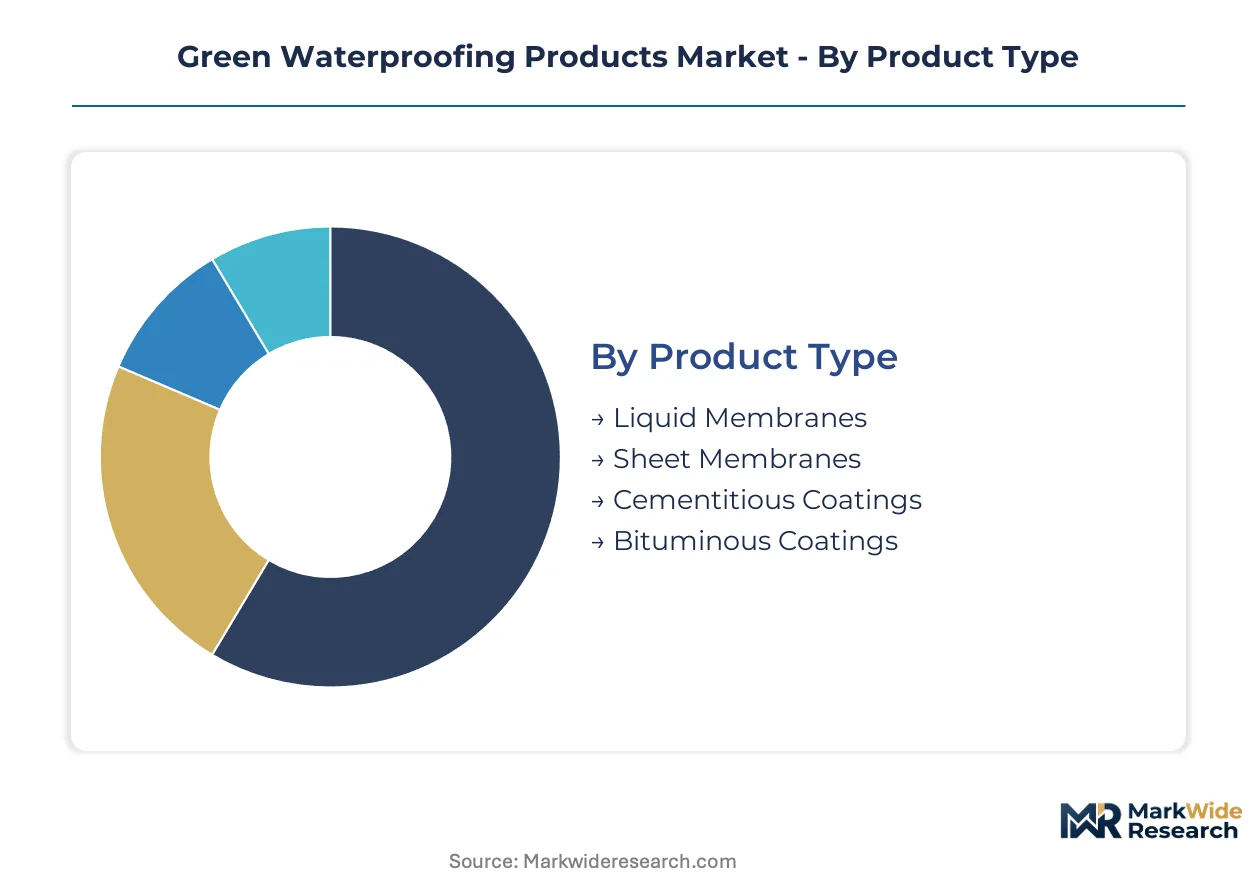
Segmentation in green waterproofing reveals how regulatory pressure and application complexity fragment purchasing behavior. Specification cycles differ sharply between commercial retrofit mandates and new residential construction. Material selection tracks directly to hydrostatic pressure requirements and UV exposure intensity.
Product Type:
Liquid membranes capture premium pricing through seamless application, while cementitious coatings dominate volume in price-sensitive emerging markets.
- Liquid Membranes:Waterborne polyurethane and silicone dispersions cure into elastomeric films exceeding 300% elongation. German contractors specify these for complex roof geometries where sheet membranes fail at seams. REACH Annex XVII restrictions on solvent-borne alternatives accelerate procurement shifts in European commercial retrofit projects.
- Sheet Membranes:Pre-formed thermoplastic polyolefin and modified bitumen rolls deliver consistent thickness but require heat-welded seams. Demand concentrates in US multifamily residential foundations where speed of installation outweighs labor cost. Limited penetration in retrofit applications due to substrate preparation requirements.
- Cementitious Coatings:Crystalline and flexible Portland-based formulations seal concrete capillaries through chemical reaction. Cost leadership in Indian and Southeast Asian markets without VOC enforcement limits green premium capture.
- Bituminous Coatings:Solvent-refined asphalt emulsions retain below-grade specification in legacy infrastructure projects. Regulatory pressure from EPA VOC thresholds in 17 US states forces reformulation toward waterborne alternatives.
Today's leader: Liquid Membranes. Tomorrow's challenger: Reformulated bituminous coatings meeting sub-50 g/L thresholds.
Application:
Below-grade specifications command material premiums due to hydrostatic pressure ratings, while roofing applications drive volume through energy retrofit mandates.
- Roofing:UV-exposed membrane systems face thermal cycling stress requiring silicone or aliphatic polyurethane chemistry. German and Dutch contractors adopt spray-applied liquid systems at triple the pace of conventional sheets. LEED v4.1 transparency credits redirect commercial office procurement toward certified low-VOC alternatives.
- Foundation:Hydrostatic pressure resistance demands thick-film polyurethane or modified bitumen systems. Data center and battery storage facility construction in the United States and China concentrates demand for bio-based polyol formulations with elastomeric recovery above 400%.
- Underground Structures:Tunnel and subway waterproofing requires spray-applied membranes with rapid cure chemistry to minimize operational disruption. European urban transit expansions in Germany and France specify silane-terminated polyurea systems.
- Bridges:Expansion joint sealing and deck waterproofing combine traffic-bearing membrane systems with corrosion-resistant primers. US state DOT procurement increasingly mandates recycled content thresholds.
Foundation applications claim the steepest price premiums. Roofing volumes are expanding most quickly across German and US commercial retrofit mandates.
Material:
Polyurethane chemistry anchors performance specifications, while natural rubber derivatives capture sustainability-driven niche positioning.
- Polyurethane:Bio-based polyol feedstocks from castor oil and soybean derivatives now supply construction-grade dispersions. BASF's backward integration into renewable feedstock production secures margin stability against agricultural commodity swings. Below-grade hydrostatic applications demand aromatic isocyanate alternatives to meet REACH labeling restrictions.
- Silicone:Moisture-cure alkoxy-terminated polymers deliver UV stability and thermal cycling endurance exceeding 20 years. Premium roofing specifications in California and Florida specify silicone where reflective cool roof requirements compound with waterproofing performance.
- Latex:Styrene-butadiene and acrylic emulsions serve cost-sensitive above-grade applications with moderate elongation requirements. Limited penetration in commercial specifications due to hydrostatic pressure performance gaps.
- Natural Rubber:Hevea brasiliensis-derived latex and guayule extracts serve sustainability-certified niche projects. Marginal commercial presence due to supply concentration in Southeast Asian plantation networks and price volatility.
Polyurethane formulations dominate specification today. Silicone systems are gaining share fastest in UV-exposed commercial roofing segments.
End User:
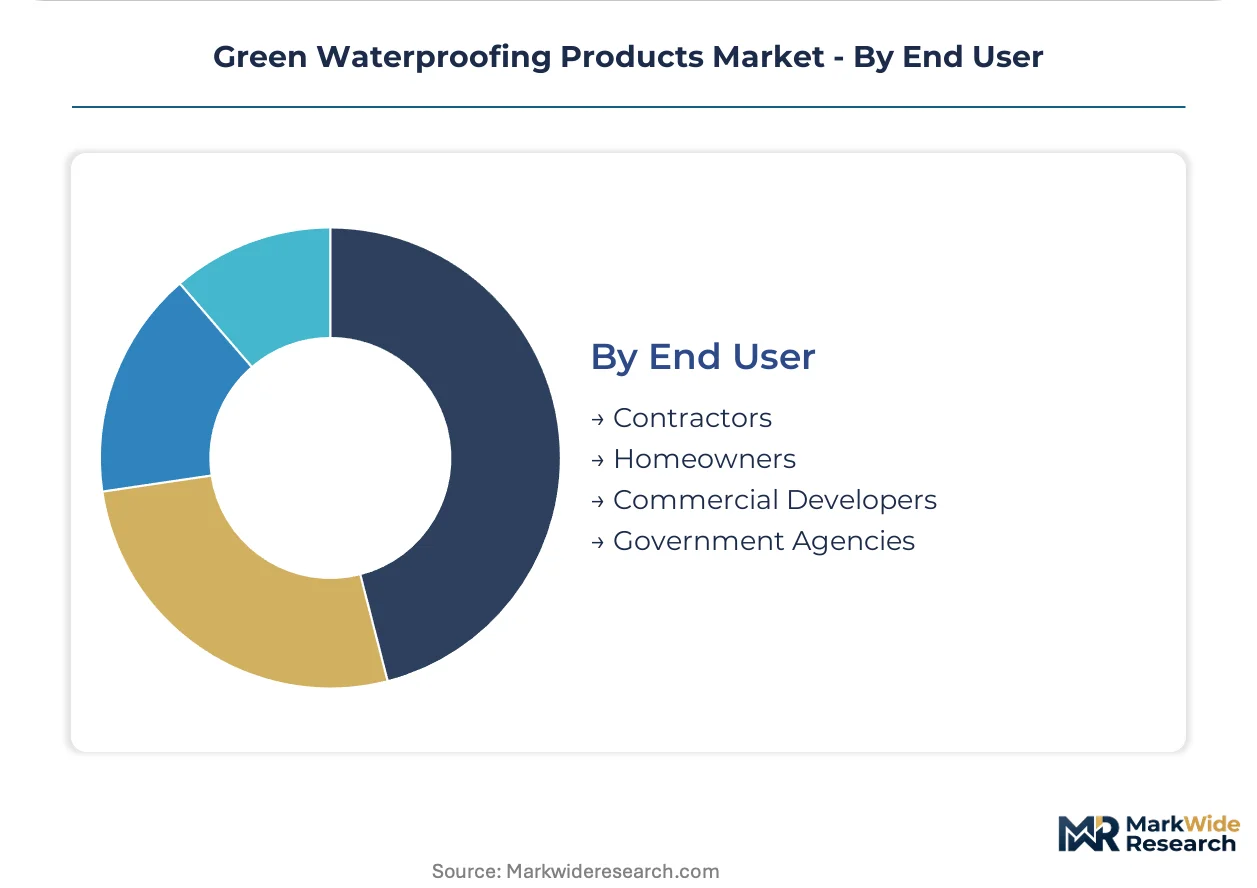
Commercial developers consolidate purchasing power through portfolio-wide green certification mandates, while contractors retain material selection influence in fragmented residential markets.
- Commercial Developers:Institutional owners in Germany, the United States, and China mandate LEED or BREEAM certification across office and multifamily portfolios. Automated specification platforms pre-filter products by regional code alignment and credit contribution, disintermediating traditional distributor relationships.
- Contractors:Roofing and waterproofing specialists in California and New York adopt digital compliance tools that rank alternatives by VOC threshold and durability rating. Labor cost differentials between liquid spray application and sheet membrane installation drive material selection in competitive bidding.
- Government Agencies:Federal and state procurement in the United States increasingly requires recycled content and bio-based feedstock disclosure. DOT and GSA specification templates cascade into municipal and educational construction standards.
- Homeowners:Residential repair and renovation demand concentrates in DIY cementitious coatings through retail hardware channels. Limited price tolerance for green premium products without regulatory enforcement or utility rebate programs.
Commercial developers set specification standards today. Government agency procurement is emerging as the fastest-growing demand channel through infrastructure stimulus programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr industrial corridor concentrates Europe's most stringent waterproofing specification requirements. Commercial retrofit mandates and REACH enforcement compress procurement cycles across the continent. Asia-Pacific markets diverge sharply between China's coastal megacities and India's price-sensitive construction zones.
Germany
Commercial building energy retrofit mandates in the Rhine-Ruhr corridor compress specification cycles for low-VOC liquid membranes. ECHA REACH Annex XVII restrictions on isocyanate labeling force reformulation of solvent-borne polyurethane systems. Stuttgart and Munich engineering clusters accelerate DIBt-certified bio-based polyol adoption for below-grade data center foundations.
United States
EPA VOC regulations covering 17 states representing 60% of commercial construction value mandate sub-50 g/L thresholds by late 2025. LEED v4.1 material ingredient transparency credits redirect institutional procurement toward certified alternatives. California and New York specification platforms automate compliance filtering, disintermediating traditional distributor relationships in commercial office verticals.
China
MEE construction material emission standards tighten enforcement across Yangtze River Delta megacities. Dual carbon goals accelerate specification of bio-based polyurethane systems in battery storage facility foundations. Shanghai and Shenzhen commercial developers consolidate purchasing power through portfolio-wide green certification mandates.
India
BIS waterproofing durability codes create first-mover advantage opportunities for certified membrane suppliers in emerging enforcement zones. Cementitious coatings retain 40-60% price advantage where VOC enforcement remains absent. Maharashtra and Gujarat industrial corridors concentrate demand from data center construction despite green premium resistance.
Netherlands
Dutch roofing contractors adopt spray-applied liquid systems at triple the pace of conventional sheet membranes. EU Green Deal building renovation targets compress labor cost differentials that previously favored cementitious coatings. Rotterdam and Amsterdam commercial retrofit projects specify silane-terminated polyurea for rapid-cure urban transit applications.
Green Waterproofing Products Market Competitive Landscape
Backward integration into bio-based polyol feedstocks dominates the current landscape among construction chemical specialists. The vendor base separates into three tiers: multinational integrated chemical producers with captive renewable feedstock supply, regional formulation specialists leveraging distributor networks, and emerging technology licensors commercializing novel curing chemistries. Competitive intensity concentrates on M&A activity targeting silane-terminated polymer capabilities and capacity expansion in waterborne polyurethane dispersion plants.
Within the integrated chemical tier, Sika and BASF occupy positions anchored by European formulation networks and backward integration into renewable feedstock production. Fosroc exemplifies the regional specialist archetype with specification strength in below-grade applications. These three companies represent contrasting strategic postures: Sika leverages distributor relationships for specification penetration, BASF secures margin stability through upstream control over bio-based polyol supply, and Fosroc concentrates on hydrostatic pressure-rated system certification for infrastructure verticals.
| Leading Market Players |
|---|
| Sika |
| BASF |
| Dow |
| Fosroc |
| GAF Materials |
| Soprema Group |
| Carlisle Companies |
| Saint-Gobain |
| RPM International |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between DIBt-compliant liquid membranes and uncertified cementitious alternatives manifests in parallel pricing power and supply chain configurations across Germany, the United States, and China. REACH Annex XVII enforcement and LEED v4.1 transparency credits compress procurement toward verified low-VOC formulations, while agricultural commodity swings in castor oil and soybean derivatives tether margin stability to bio-based polyol sourcing strategies.
Pricing Analysis
Input-cost pass-through from bio-based polyol feedstocks anchors pricing dynamics for waterborne polyurethane dispersions. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels separates DIBt-certified German formulations from REACH-compliant alternatives and uncertified Asian imports. Pricing pressure stems from cementitious coating cost floors in Indian and Southeast Asian markets without VOC enforcement. Commercial developers in Germany and the United States show lowest price sensitivity due to portfolio-wide green certification mandates, while residential contractors in emerging markets resist green premiums without regulatory compulsion.
Supply Chain Analysis
Dual-sourcing requirements from multinational chemical buyers mandate qualified supply from both European and Chinese silane-terminated polymer producers. Bio-based polyol production concentrates in Germany, the United States, and Brazil, while specialty additive manufacturing anchors in China and the Netherlands. Raw material dependencies rest on castor oil derivatives, soybean-based polyols, and moisture-cure silane polymers. Single-source vulnerability in European silane-terminated polymer supply creates structural risk for moisture-cure system manufacturers. Distribution runs through formulation specialists and direct-to-contractor digital platforms that automate LEED credit calculation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The green waterproofing products market functions as a stable compounder where regulatory ratchet effects in building energy codes generate predictable specification migration toward certified alternatives.
For Market Incumbents: Extend backward integration into bio-based polyol feedstocks to secure margin stability against agricultural commodity volatility. Accelerate DIBt and REACH Annex XVII certification timelines to preempt emerging entrant formulation specialists in below-grade data center applications. Channel control through direct-to-contractor digital platforms defends specification gatekeeper status against automated compliance tool disintermediation. For New Entrants and Emerging Players: Rapid-cure silane-terminated polyurea chemistry offers a technology-first wedge into European urban transit expansion projects where operational disruption constraints favor spray-applied systems. Target Indian BIS waterproofing durability code enforcement zones before incumbent certification investments solidify. White-space capture in battery storage facility foundations across China's Yangtze River Delta leverages dual carbon goal procurement mandates. Go-to-market through specification platform partnerships automates regional code compliance demonstration. For Investors and Strategic Acquirers: Consolidation pressure builds where silane-terminated polymer capabilities concentrate among single-source European and Chinese producers. Five-to-ten year viability frames this market around regulatory irreversibility in commercial building energy retrofit mandates. Acquisition target archetypes include regional formulation specialists with DIBt-certified below-grade systems and captive bio-based polyol supply agreements. Watch for divergence between EPA VOC state adoption timelines and LEED v4.1 transparency credit enforcement as inflection indicator for North American specification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyols | BASF's captive castor oil supply secures margin stability against agricultural commodity swings. |
| Direct-to-Contractor Digital Platform Launch | Automated LEED credit calculation bypasses traditional distributor markup layers in California and New York. |
| Silane-Terminated Polymer Capacity Expansion | European producers dominate moisture-cure chemistry for rapid-cure urban transit applications. |
| DIBt Certification Acceleration | German commercial retrofit mandates compress specification cycles for verified low-VOC membranes. |
| India BIS Durability Code Pre-Positioning | First-mover certification investment captures data center construction in Maharashtra and Gujarat corridors. |
Research Methodology
Bottom-up commercial retrofit and new construction modeling reconciled against top-down formulation plant capacity tracking forms the analytical core of this study. Primary interviews with waterproofing contractors, commercial developer procurement directors, chemical plant managers, and regulatory affairs specialists at multinational suppliers combined with secondary validation from EPA VOC regulatory filings, ECHA REACH Annex XVII substance restriction databases, DIBt certification registries, and China MEE construction material emission standards. Triangulation across stakeholder input and documentary sources anchors segment-level demand estimates.
Input-output matrix framing connects bio-based polyol feedstock availability to regional formulation capacity and end-use specification intensity. Segmentation dimensions span product type, application, material chemistry, and end-user archetype across the projection horizon. CAGRs derive from regression-based specification penetration curves calibrated to regulatory enforcement timelines. Forecast inputs include building energy retrofit mandate adoption rates and green certification credit system evolution.
The model holds under steady regulatory enforcement trajectories; deviation in EPA VOC state adoption pace, REACH Annex XVII amendment scope, or China dual carbon goal implementation intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Coatings Market
Green Building Materials
Green Silica Market
Green Building Materials
Sustainable and Green Building Materials Market
Green Building Materials
Eco-Friendly Tiles Market
Green Building Materials
Green Building Materials Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
Solar Windows Market
Green Building Materials
Green Building Market
Green Building Materials
Artificial Green Wall Market
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Solar Frames Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Green Rebar Market
Green Building Materials
APAC Green Buildings Market
Green Building Materials
Non-Residential Green Building Market