
 Eco-Friendly Tiles Market | 2026-2036
Eco-Friendly Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Tiles Market Analysis
Buyer concentration among large-scale commercial developers is recalibrating procurement standards across the Eco-Friendly Tiles landscape. Enviroglas leverages post-consumer glass feedstock to dominate recycled material tile production. Johnson Tiles anchors UK specification through its BREEAM-aligned product ranges. Dal-Tile Corporation extends its manufacturing scale across North American distribution channels.
Eco-friendly tiles are surfacing materials manufactured with recycled, rapidly renewable, or low-embodied-carbon constituents, typically pressed at 900–1200°C and certified to ISO 14021 environmental claims; they serve to reduce lifecycle emissions in built environments while meeting slip-resistance and durability specifications. Porcelain commands the structural center due to its density and frost resistance in exterior commercial applications. Recycled materials represent the fastest-expanding product type as architects prioritize circular material specifications. Residential application generates the deepest volume pool, though commercial projects yield wider margin spreads through custom color matching and large-format capabilities.
The EU Green Deal and REACH frameworks in Europe, India's BIS eco-mark standards, and the US EPA's recycled content guidelines collectively elevate compliance thresholds for market entry. ECHA's restricted substance lists are forcing reformulation of traditional glaze chemistries toward water-based alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border projects.
Market Dynamics
Embodied carbon accounting in construction procurement is compressing specification timelines for low-coefficient materials, forcing tile manufacturers to validate supply chain emissions through third-party EPDs before project bid deadlines.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Commercial developers in Germany and France now mandate EPD-verified tiles for public tenders, accelerating specification of recycled-content porcelain in urban renewal corridors.
- India's urban corridor densification:State-level smart city authorities in Maharashtra and Karnataka are embedding LEED-equivalent material standards into infrastructure RFPs, creating pull-through for certified eco-tiles in transit-oriented developments.
- Post-consumer glass feedstock availability:Municipal recycling stream upgrades in the UK and Netherlands are stabilizing cullet supply chains, enabling consistent production of high-recycled-content surfacing materials at scale.
Market Restraints
- Natural gas price volatility in kiln operations:Firing temperatures of 900–1200°C create exposure to European energy market fluctuations, compressing margins for manufacturers without long-term utility contracts.
- Glaze chemistry reformulation costs:ECHA's restricted substance lists are forcing migration from solvent-based to water-based glaze systems, extending R&D cycles and raising batch consistency failure rates.
- Substitute material penetration:Polished concrete and engineered stone are capturing specification share in commercial lobbies and retail environments where seamless surfaces reduce installation labor.
Strategic Opportunities
- Underpenetrated residential retrofit segment:Germany's building energy renovation subsidies (BAFA programs) are unlocking replacement demand in multi-family housing stock for low-embodied-carbon flooring upgrades.
- Digital specification platforms:Architect procurement workflows are migrating to BIM-integrated material libraries, creating first-mover advantage for manufacturers with parametrically modeled EPD data.
- Water-based glaze technology convergence:Advanced ceramic inkjet deposition is converging with low-VOC glaze formulations, enabling custom color matching at production speeds previously restricted to conventional chemistries.
Industry Challenges
- EPD verification talent scarcity:Lifecycle assessment expertise remains concentrated among third-party consultancies, creating bottlenecks for mid-tier manufacturers seeking ISO 14021 certification.
- Cross-border regulatory divergence:India's BIS eco-mark standards, EU REACH frameworks, and US EPA recycled content guidelines employ incompatible testing protocols, forcing SKU proliferation for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Tiles Market |
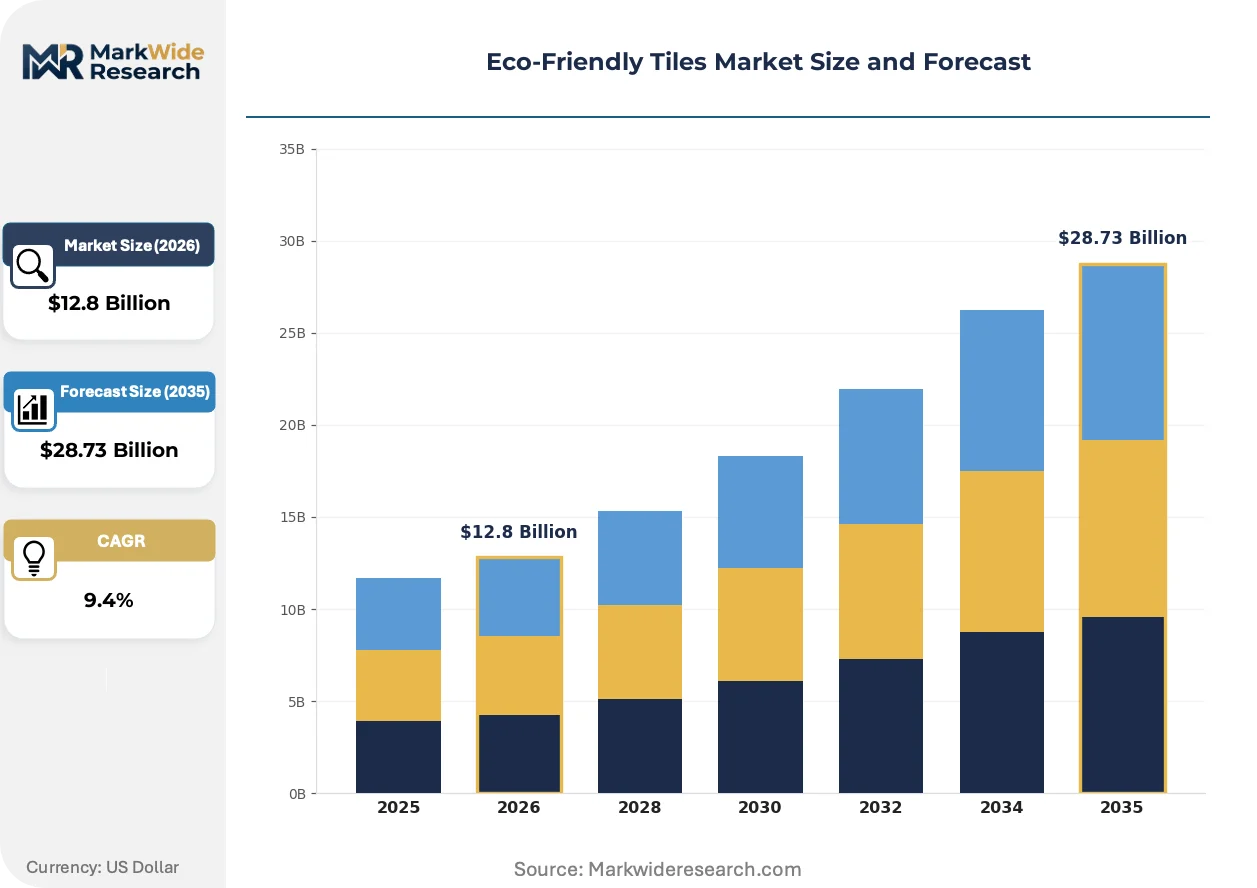
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Porcelain, Glass, Recycled Materials Color: Earth Tones, Bright Shades, Pastels, Neutral Colors Application: Residential, Commercial, Outdoor, Interior Installation Type: Adhesive, Grout, Interlocking, Loose Lay |
| Companies Covered | Enviroglas, Johnson Tiles, Ceramiche Refin S.p.A, Vitromex, MILEstone, Crossville Inc., Dal-Tile Corporation, Emil Ceramica Srl, Centura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Tiles Market Emerging Trajectories
Digital manufacturing controls and regulatory disclosure mandates are compressing the gap between material specification and verified environmental performance, rewarding investments in supply chain traceability infrastructure.
Dry-pressed porcelain manufacturing with digital inkjet decoration is converging with real-time emissions monitoring systems, allowing batch-level carbon footprint tagging. Large-scale commercial developers in the Netherlands and Denmark are piloting blockchain-linked material passports, compressing due diligence cycles from weeks to hours. This convergence is displacing traditional certificate-based verification with continuous data-stream accountability.
REACH Annex XVII restrictions on heavy metals in ceramic glazes are forcing reformulation of cobalt and chrome-based colorants across European production facilities. Manufacturers are responding with mineral-derived pigment alternatives, though color stability in high-traffic applications remains under validation. The commercial hospitality segment—hotels and airport terminals—faces the tightest compliance deadlines and is accelerating supplier audits.
Buyer concentration among design-build contractors is consolidating specification authority away from individual architects, compressing vendor qualification lists to pre-approved manufacturer pools. Tier-one contractors in India's National Capital Region and Germany's Rhine-Ruhr corridor are deploying centralized procurement platforms that filter materials by automated EPD threshold checks, marginalizing smaller producers without digitized certification libraries.
Eco-Friendly Tiles Market Segmentation
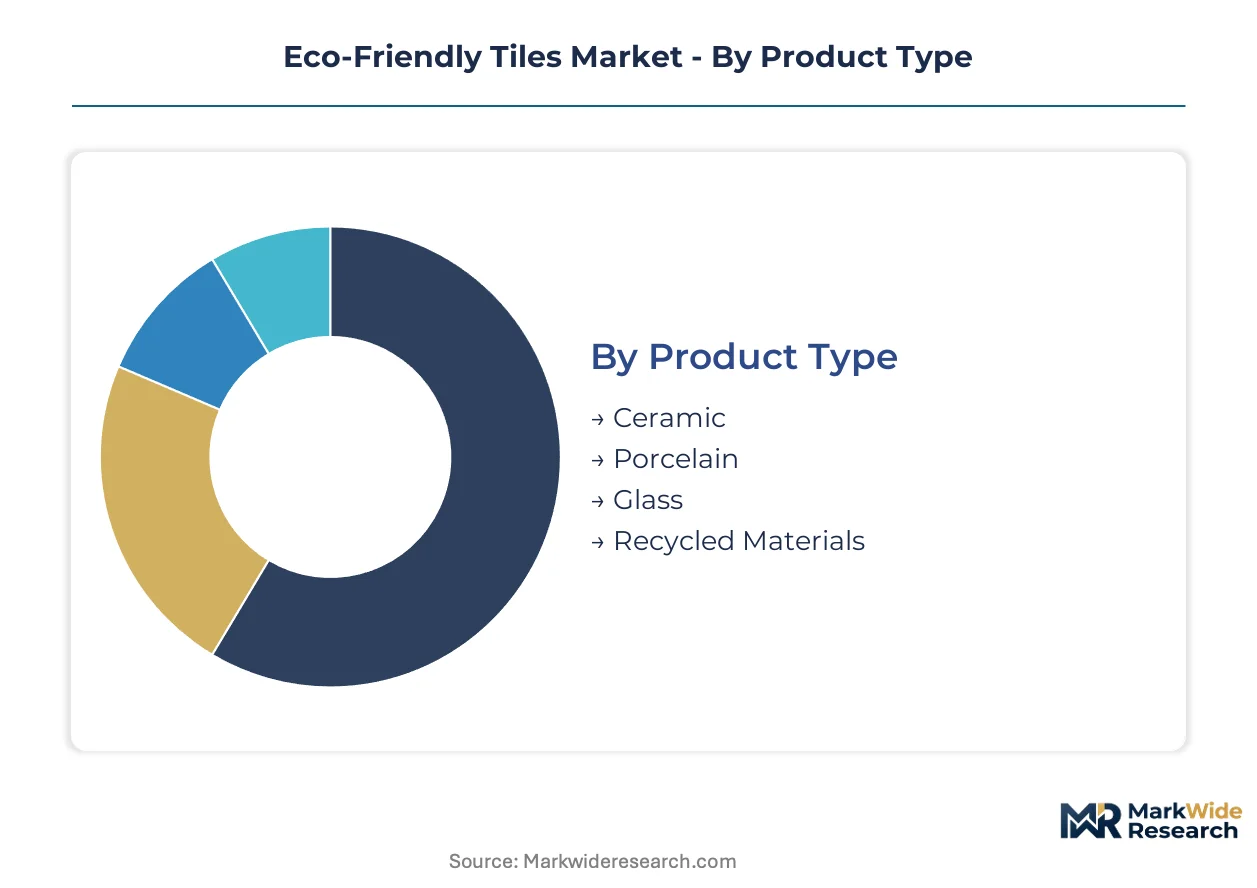
Segmentation in eco-friendly tiles tracks how material composition, aesthetic preference, and installation context reshape procurement patterns across construction verticals. Specification authority concentrates differently by project type, with commercial developers prioritizing EPD-verified porcelain while residential retrofits favor accessible recycled-content ceramic.
Product Type:
Replacement cycles in commercial flooring run 15-25 years, driving specification toward materials that balance durability with embodied carbon reduction.
- Porcelain:Dense, low-porosity ceramic fired above 1200°C delivers frost resistance and load-bearing capacity for exterior commercial applications. German transit authorities specify porcelain for station platforms under EU Green Deal procurement rules.
- Recycled Materials:Post-consumer glass and ceramic waste streams reduce virgin raw material extraction by 40-60% in verified production batches. Netherlands municipal recycling upgrades stabilize cullet supply for consistent manufacturing scale.
- Ceramic:Traditional clay-based tiles fired at 900-1100°C serve cost-sensitive residential replacement demand with established supply chains.
- Glass:Translucent surfacing from recycled silica streams enables light-diffusing interior applications with distinctive aesthetic properties.
Porcelain sits at the top of the volume ranking, with recycled materials climbing the fastest.
Color:
Cost tiers in tile procurement separate premium custom-matched specifications from standard catalog offerings.
- Neutral Colors:Grayscale and beige palettes dominate commercial specification for lease-flexible interiors. Large-format neutral porcelain commands widest margin spreads through volume-contract pricing.
- Earth Tones:Terracotta, ochre, and clay-inspired hues align with biophilic design mandates in wellness-focused commercial spaces. Indian smart city projects specify earth tones for transit-oriented residential clusters.
- Bright Shades:Saturated colorways serve branded retail environments and wayfinding applications with shorter replacement horizons.
- Pastels:Soft-toned specifications concentrate in hospitality and healthcare segments seeking reduced visual stimulation.
Neutral colors dominate commercial volume, with earth tones gaining share fastest in residential new-build specifications.
Application:
Customer type determines whether procurement flows through centralized contractor platforms or fragmented retail channels.
- Commercial:Office, retail, and institutional projects require EPD documentation and slip-resistance certification for liability coverage. Design-build contractors in India's National Capital Region filter specifications through automated compliance platforms.
- Residential:Single-family and multi-family housing generates deepest volume pools through replacement demand and new construction. Germany's BAFA renovation subsidies accelerate low-embodied-carbon flooring upgrades in existing housing stock.
- Interior:Climate-controlled environments permit broader material latitude including moisture-sensitive recycled-content options.
- Outdoor:Freeze-thaw cycling and UV exposure restrict specification to frost-resistant porcelain and specialized ceramic formulations.
Residential generates the deepest volume pool, with commercial applications expanding most quickly through tightened public procurement standards.
Installation Type:
Supply concentration in adhesive chemistry favors established construction chemical suppliers over tile manufacturers.
- Adhesive:Cementitious and polymer-modified bonding systems dominate permanent installations with highest load-bearing requirements.
- Grout:Joint-filling compounds complete watertight assemblies in wet-area applications with antimicrobial additive options.
- Interlocking:Mechanical connection systems enable floating floors without subfloor preparation, accelerating renovation timelines.
- Loose Lay:Friction-based placement suits temporary installations and rapid commercial refresh cycles with minimal substrate disruption.
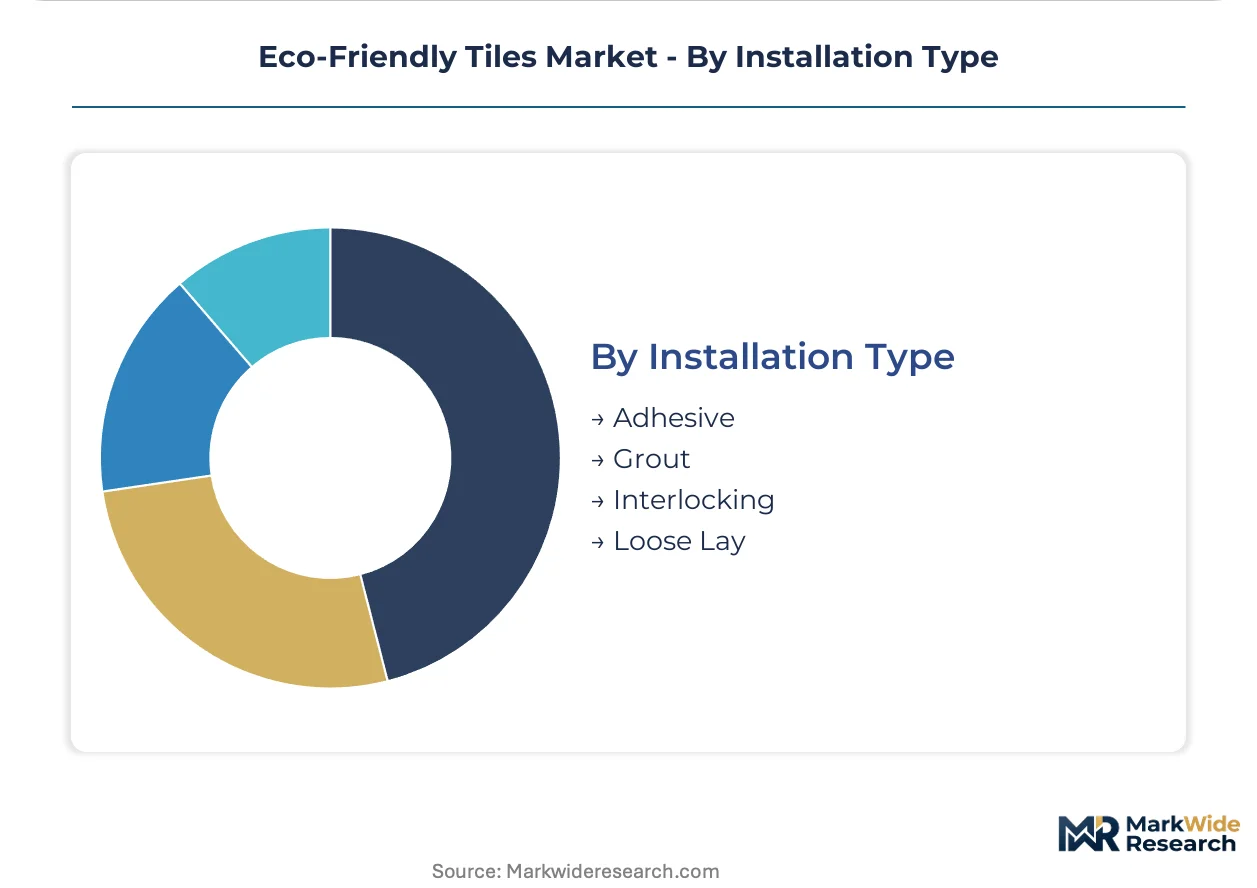
Adhesive installation commands the highest volume share, with interlocking systems climbing fastest in residential retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's building energy renovation subsidies outpace France's public procurement mandates in absolute tile specification volume, while India's urban corridor densification generates faster percentage growth in certified material demand.
Germany
Multi-family housing retrofits and transit platform renewals drive specification of frost-resistant porcelain. BAFA renovation subsidies accelerate low-embodied-carbon flooring upgrades in existing building stock. The Rhine-Ruhr corridor concentrates design-build contractor procurement platforms that filter materials through automated EPD threshold checks.
India
Smart city infrastructure and transit-oriented residential clusters create pull-through for LEED-equivalent certified tiles. BIS eco-mark standards elevate compliance thresholds for building materials in Maharashtra and Karnataka state projects. The National Capital Region deploys centralized procurement systems that marginalize producers without digitized certification libraries.
United States
Commercial office renovations and institutional building retrofits prioritize recycled-content surfacing materials. EPA recycled content guidelines shape federal procurement standards for construction materials. Crossville, Tennessee anchors North American manufacturing scale for post-consumer glass feedstock tile production.
Netherlands
Municipal recycling stream upgrades stabilize cullet supply chains for consistent high-recycled-content manufacturing. EU Green Deal embodied carbon thresholds mandate EPD-verified materials in public tenders. Amsterdam and Rotterdam urban renewal corridors pilot blockchain-linked material passports for compressed due diligence cycles.
United Kingdom
Post-consumer glass feedstock availability from upgraded municipal recycling enables scaled production of recycled-content tiles. BREEAM-aligned product standards dominate commercial specification authority. Greater London design-build contractors consolidate vendor qualification lists to pre-approved manufacturer pools with digitized EPD libraries.
Eco-Friendly Tiles Market Vendor Landscape
European producers anchor the premium tier with EPD-verified porcelain and BREEAM-aligned product ranges; North American specialists hold scale advantages in post-consumer glass feedstock processing and distribution channel density. The vendor base fragments across regional compliance jurisdictions, with mid-tier manufacturers facing SKU proliferation pressures from incompatible testing protocols. Three archetypes dominate: recycled-content specialists leveraging cullet supply chains, full-range manufacturers with digital specification platform integration, and regional scale players optimizing kiln efficiency through long-term utility contracts. Competitive moves concentrate on strategic partnerships with municipal recycling operators and backward integration into cullet processing facilities.
Among UK-based fabricators, Johnson Tiles exemplifies the BREEAM-aligned full-range archetype, while Enviroglas occupies a position within the recycled-content specialist tier. Dal-Tile Corporation represents North American scale-driven manufacturing, anchoring distribution density across regional construction markets. These three companies illustrate the geographic and strategic segmentation compressing procurement authority toward pre-qualified vendor pools.
| Leading Market Players |
|---|
| Enviroglas |
| Johnson Tiles |
| Ceramiche Refin S.p.A |
| Vitromex |
| MILEstone |
| Crossville Inc. |
| Dal-Tile Corporation |
| Emil Ceramica Srl |
| Centura |
| Others |
Supply Flow & Price Mechanics
Dry-pressed porcelain manufacturing with digital inkjet decoration is compressing production economics while concentrating supply authority among kiln operators with long-term natural gas contracts in Germany and the Netherlands. This technology transition simultaneously reduces per-unit firing costs and raises barriers for mid-tier producers lacking utility price hedging, reshaping competitive margins across the eco-friendly tiles landscape.
Pricing Analysis
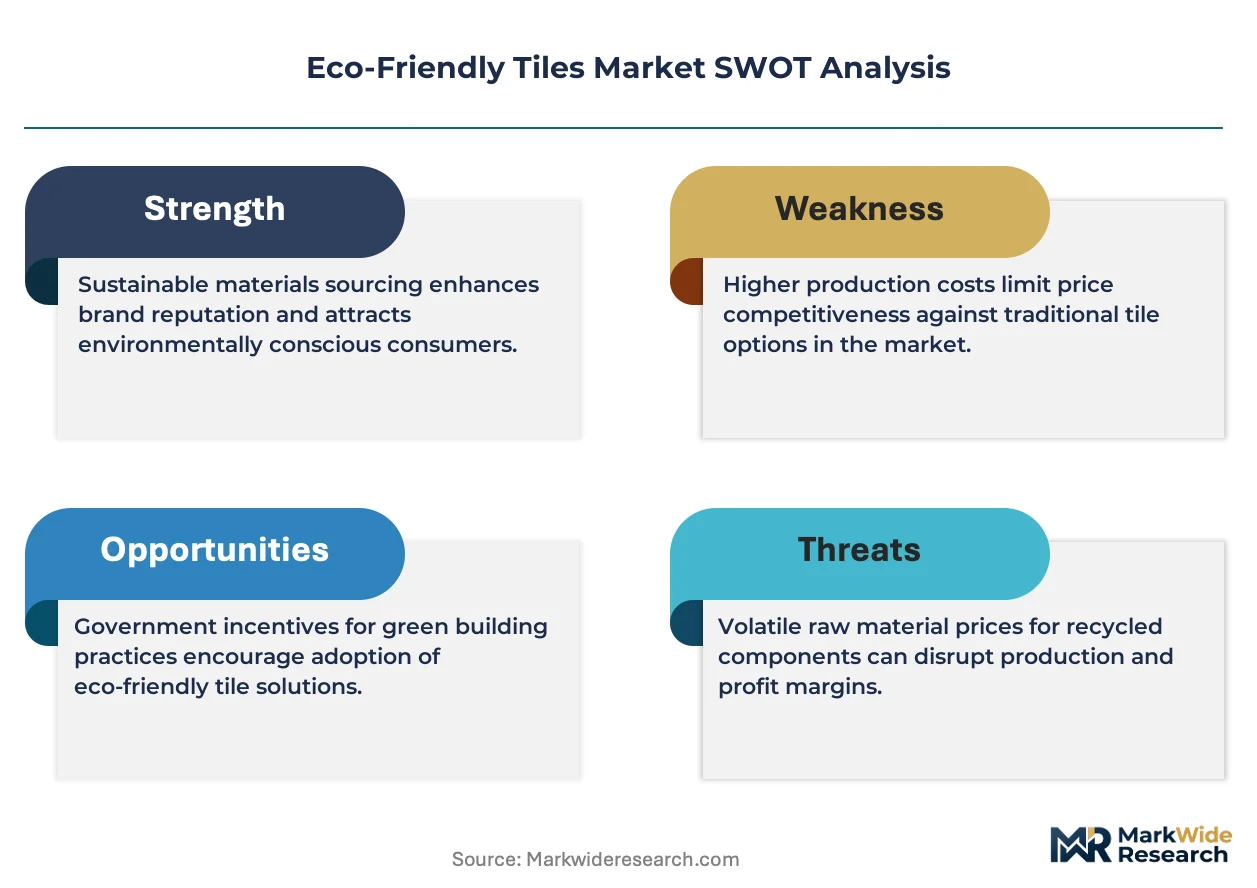
Capacity additions in India are reshaping price floors for standard-grade ceramic tiles, forcing European manufacturers toward premium EPD-verified porcelain tiers. Three-tier pricing structure across premium, standard, and economy levels separates BREEAM-aligned specification grades from mass-market residential offerings, with certification tier and volume scale driving differentiation. Cost compression in the standard tier is intensifying because of Indian kiln capacity expansion and freight cost advantages. Residential retrofit buyers exhibit highest price sensitivity, while commercial developers under EU Green Deal mandates show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Regional distribution centers in the Netherlands and United Kingdom anchor hub-and-spoke patterns for post-consumer glass feedstock collection and cullet processing. Manufacturing concentration centers on Italy, Spain, and India for ceramic body production, with Germany and the United States hosting specialized recycled-content fabrication. Raw material dependencies include kaolin clay deposits, post-consumer glass cullet, and mineral-derived pigments for REACH-compliant glaze reformulation. Supply chain risk stems from single-source vulnerability in cobalt and chrome-based colorant alternatives under ECHA restricted substance lists. Distribution runs through design-build contractor procurement platforms and BIM-integrated material libraries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eco-friendly tiles market functions as a geographic-arbitrage play between European embodied carbon compliance premiums and Indian manufacturing cost advantages, with BAFA subsidy flows in Germany creating demand pull that outpaces domestic kiln capacity.
For Market Incumbents: Anchor specification authority through captive cullet processing facilities and EPD digitization investments. Defensive consolidation should prioritize backward integration into municipal recycling partnerships to lock post-consumer glass feedstock against emerging competitors. Threat substitution from polished concrete and engineered stone demands accelerated water-based glaze R&D to maintain architectural specification share. For New Entrants and Emerging Players: Begin with Germany's underpenetrated residential retrofit segment, where BAFA renovation subsidies create pull-through for low-embodied-carbon flooring upgrades without requiring commercial-scale EPD infrastructure. The most penetrable geography is India's National Capital Region, where centralized procurement platforms still lack digitized certification libraries from smaller producers. A go-to-market angle through BIM-integrated material libraries enables first-mover positioning before incumbent EPD data migration completes. For Investors and Strategic Acquirers: Valuations sit cheapest among recycled-content specialists with cullet supply contracts but without digital specification platform integration, as buyer concentration favors full-range manufacturers with parametric EPD modeling. Long-term viability over the next decade hinges on regulatory divergence management capabilities across EU REACH, India BIS eco-mark, and US EPA recycled content frameworks. The signal to watch is blockchain-linked material passport adoption rates in Dutch and Danish urban renewal corridors, indicating whether continuous data-stream accountability displaces certificate-based verification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Processing | Captive post-consumer glass supply stabilizes feedstock costs against municipal recycling stream volatility. |
| EPD Digitization and BIM Integration | Parametric environmental data enables automated compliance filtering on design-build contractor procurement platforms. |
| Water-Based Glaze Technology Scale-Up | REACH Annex XVII alignment opens specification access to EU public tenders with heavy metal restrictions. |
| Regional Distribution Center Expansion | Hub-and-spoke logistics compress delivery timelines for just-in-time commercial project schedules. |
| Joint Venture with Municipal Recycling Operators | Long-term cullet offtake agreements secure manufacturing scale for high-recycled-content product lines. |
Methodological Framework
Direct dialogue with ceramic plant managers, commercial developer procurement leads, architectural specification consultants, and municipal recycling operators grounded qualitative findings, cross-checked against customs trade data, EU EPD registry filings, SEC 10-K disclosures from listed building materials firms, and BIS eco-mark certification databases. Bottom-up volume estimates from kiln capacity utilization and top-down demand calibration from construction permit flows were triangulated to reconcile production and consumption figures.
Segment-level outputs across product type, application, color palette, and installation method were generated through the projection horizon, with CAGRs derived from regression analysis of historical construction spending and regulatory adoption curves. Forecast inputs incorporated EU Green Deal embodied carbon threshold implementation timelines, India smart city infrastructure award schedules, and natural gas price volatility scenarios for kiln operation economics.
Several conditions sit outside the modeled scope, including unforeseen ceramic glaze chemistry breakthroughs, abrupt shifts in municipal recycling stream composition, and trade policy interventions affecting cross-border tile shipments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Green Building Materials
Energy Efficient Window and Door Market
Green Building Materials
Green Roof Market
Green Building Materials
Green Silica Market
Green Building Materials
Green Cement and Concrete Market
Green Building Materials
Asia Pacific Green Cement Market
Green Building Materials
Green Coatings Market
Green Building Materials
United States Green Cement Market
Green Building Materials
Global Eco-Friendly Green Roofs Market
Green Building Materials
Global Green Walls Market
Green Building Materials
Solar Frames Market
Green Building Materials
Solar Glass Market
Green Building Materials
Green Building Market
Green Building Materials
Green Waterproofing Products Market
Green Building Materials
Sustainable Construction Market
Green Building Materials
Europe Green Cement Market
Green Building Materials
Eco Flooring Market