
 GCC Automotive Connectors Market | 2026-2036
GCC Automotive Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Automotive Connectors Market Intelligence
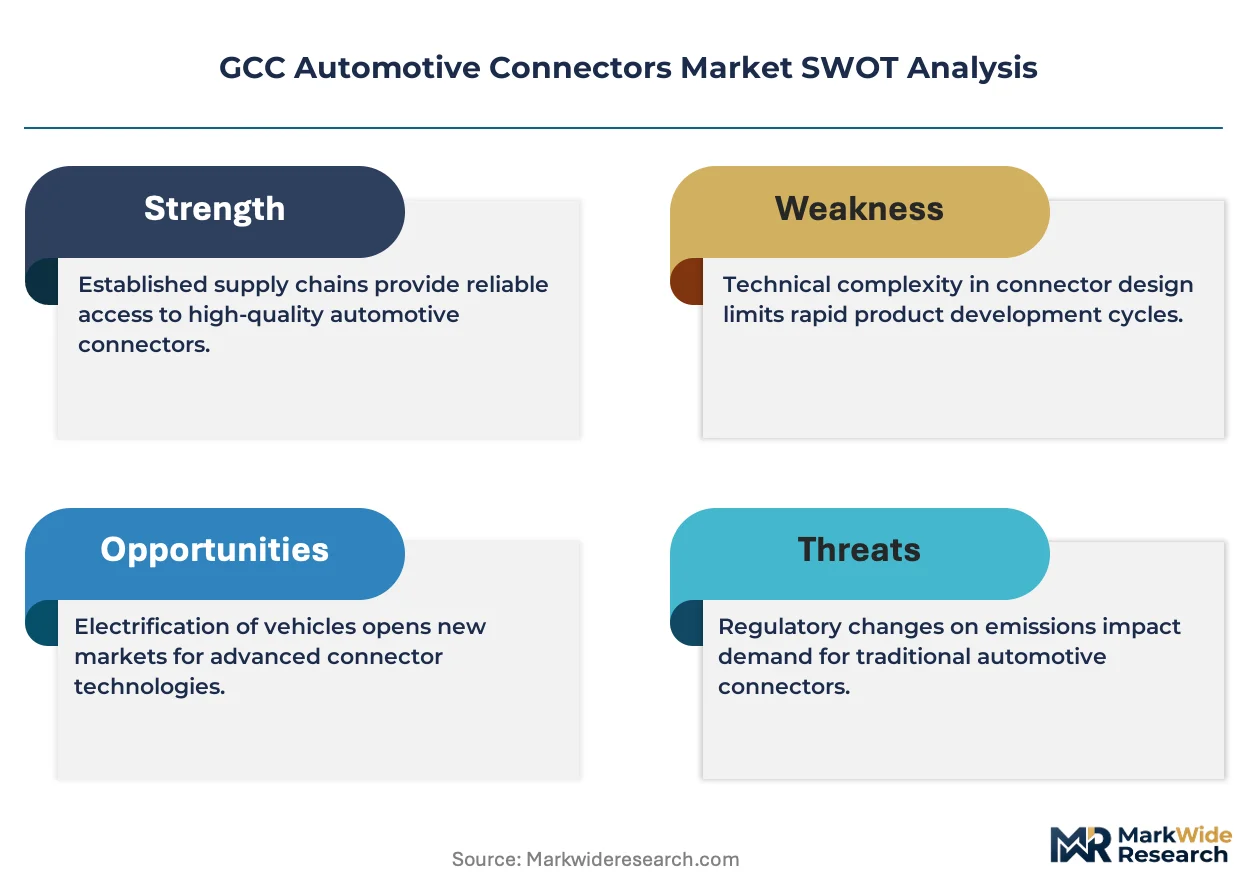
Copper alloy terminals are rebalancing connector economics as manufacturers reduce silver plating thickness to cut raw material exposure. TE Connectivity leverages vertical integration across its Dubai logistics hub to secure Gulf-wide distribution. Aptiv PLC anchors its regional competitiveness through high-voltage connector specialization for hybrid platforms. Amphenol Corporation dominates marine-grade sealed connector variants serving Saudi Arabia's desert-operating commercial fleets.
Automotive connectors are electromechanical joining devices engineered to transmit electrical signals and power between vehicle subsystems, typically rated for temperatures spanning minus 40 to 150 degrees Celsius and vibration resistance exceeding 10G acceleration. Their primary function is ensuring reliable circuit continuity across powertrain, chassis, and cabin electronics in environments of extreme thermal cycling and mechanical stress. Wire-to-Wire configurations lead volume shipments across GCC assembly lines, while Sealed Connectors command premium positioning due to dust-ingress specifications mandatory for regional operating conditions. Safety Systems applications are expanding fastest as Gulf regulators mandate advanced driver-assistance hardware in new vehicle platforms.
Gulf Standards Organization harmonization with EU REACH substance restrictions and UAE-specific ESMA product conformity schemes are elevating material disclosure requirements for connector imports. Saudi Standards, Metrology and Quality Organization technical regulations for automotive electrical components are reshaping supplier qualification protocols across the six member states. Stakeholders must monitor evolving type-approval timelines as local content incentives redraw sourcing boundaries between regional manufacturing and Asian import channels.
Market Dynamics
Electric vehicle manufacturing localization across Saudi Arabia and the UAE is compressing connector procurement cycles as OEMs demand just-in-time delivery from regional suppliers rather than Asian import channels.
Growth Catalysts
- SFDA-aligned material compliance rules:Abu Dhabi's dual carbon goals are tightening product specifications and accelerating connector material upgrades across the emirate's automotive assembly plants.
- Wire-to-Wire configurations:Volume shipments dominate GCC assembly lines as domestic vehicle production scales and tier-1 suppliers expand regional distribution hubs.
- Safety Systems mandates:Gulf regulators now require advanced driver-assistance hardware in new vehicle platforms, expanding connector demand for sensor arrays and electronic control units.
Market Restraints
- Copper alloy terminal volatility:Raw material exposure from silver plating thickness requirements creates margin pressure as metal prices fluctuate without long-term hedging mechanisms.
- Asian import channel concentration:Connector sourcing remains concentrated in East Asian manufacturing clusters, exposing GCC buyers to shipping delays and currency translation risks.
- ESMA conformity timeline friction:UAE-specific product certification schemes extend type-approval durations and raise qualification costs for new market entrants.
Strategic Opportunities
- Dubai-Jebel Ali automotive cluster:Tier-1 suppliers expanding regional distribution hubs create captive demand for localized connector warehousing and technical support services.
- Sealed Connectors premium positioning:Dust-ingress specifications mandatory for Saudi Arabia's desert-operating commercial fleets command price premiums over standard variants.
- SASO technical regulation alignment:Saudi Standards, Metrology and Quality Organization rules for automotive electrical components are reshaping supplier qualification protocols across all six GCC member states.
Industry Challenges
- High-voltage connector engineering scarcity:Hybrid platform specialization requires electromechanical engineers with EV powertrain experience, a skill set concentrated in European and Asian talent markets.
- Gulf Standards Organization harmonization complexity:REACH substance restriction alignment demands material disclosure systems that most regional distributors lack, forcing capex into compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Automotive Connectors Market |
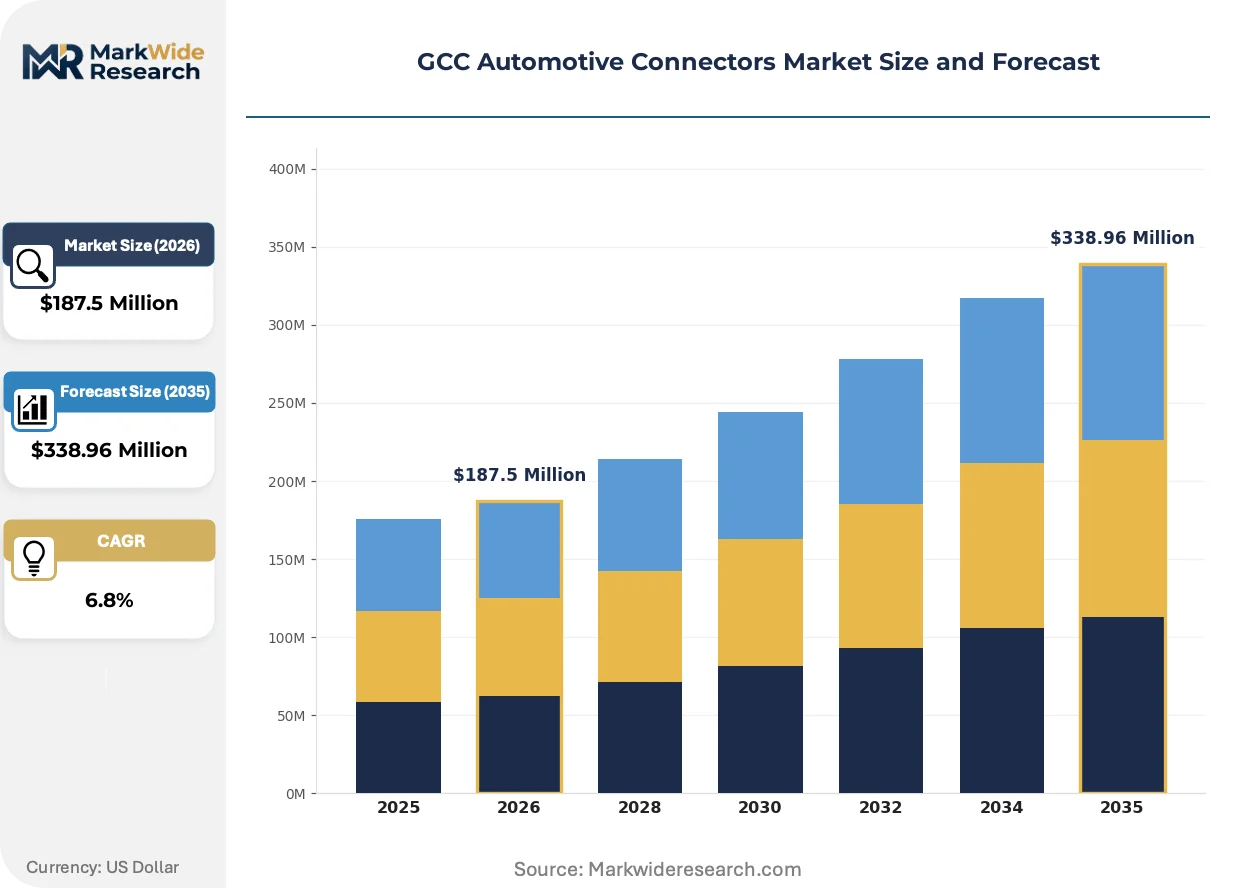
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $338.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire-to-Wire, Wire-to-Board, Board-to-Board, Sealed Connectors Application: Powertrain, Body Electronics, Infotainment, Safety Systems Customer Type: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Automated Assembly, Hand Assembly, Test Procedures, Retrofitting |
| Companies Covered | TE Connectivity, Aptiv PLC, Amphenol Corporation, Yazaki Corporation, Molex Incorporated, Sumitomo Electric Industries, Ltd., Hirose Electric Co., Ltd., JST Manufacturing Co., Ltd., Kyocera Corporation, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Automotive Connectors Market Strategic Shifts & Innovations
Connector manufacturers are rebalancing terminal metallurgy and sealing architectures to satisfy simultaneous pressures from desert operating conditions and electrified powertrain voltage loads.
Automated crimping inspection systems are automating quality assurance across GCC assembly lines. Tier-1 suppliers in the Dubai-Jebel Ali corridor are deploying machine vision at wire termination stations to eliminate manual inspection bottlenecks. This technology is automating defect detection rates previously requiring dedicated quality engineering headcount.
SASO technical regulations for automotive electrical components are mandating traceability documentation from raw material source through finished goods shipment. Saudi Arabia's national standards body requires batch-level serialization for all safety-critical connector assemblies. High-voltage variants for hybrid platforms face the most stringent documentation burdens and longest approval cycles.
Fleet operators in Saudi Arabia's commercial vehicle sector are consolidating connector procurement under single-source agreements with integrated logistics providers. Traditional distributor networks serving independent repair channels are losing volume to direct OEM-affiliated service operations. This concentration is most visible in Riyadh-based heavy-duty truck maintenance facilities where dealer-captive parts programs now dominate connector replacement demand.
GCC Automotive Connectors Market Segmentation
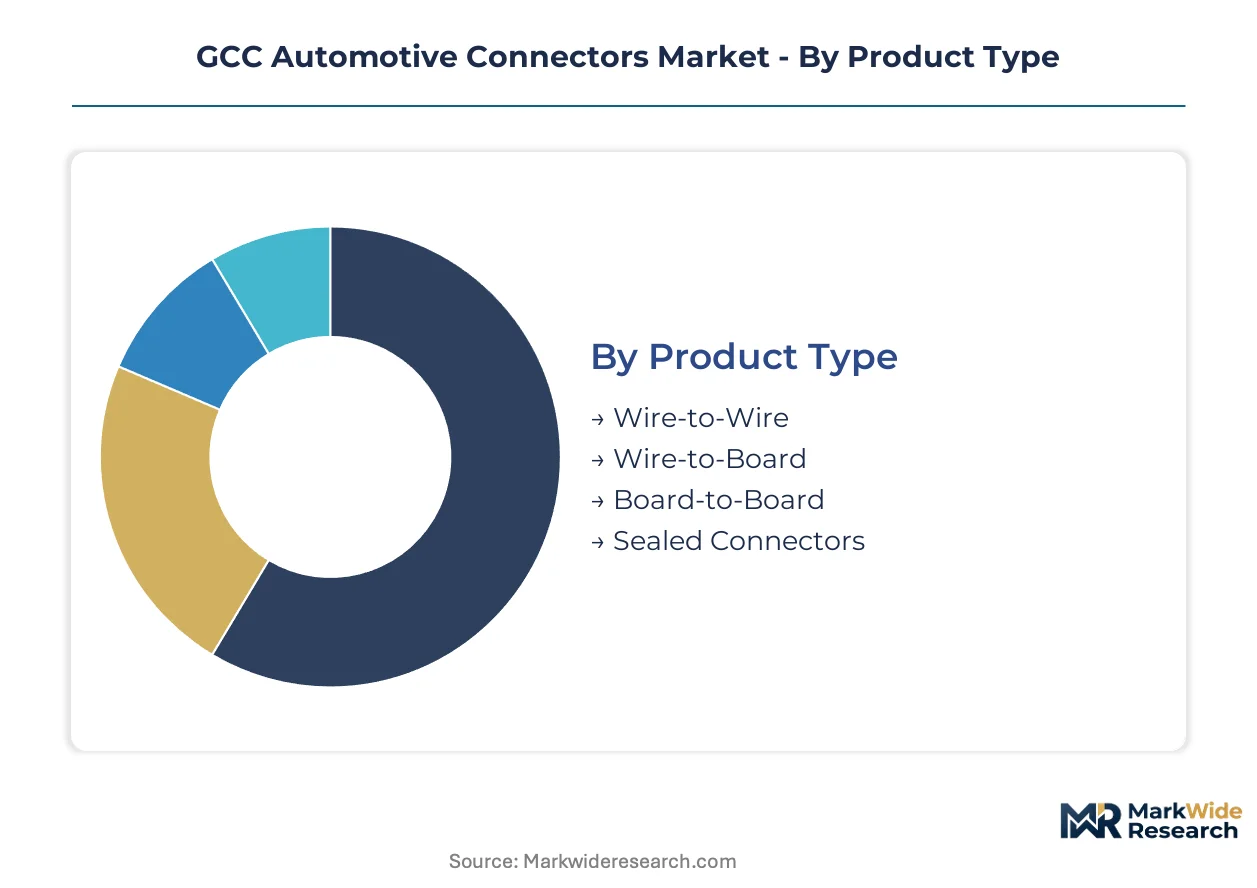
Connector procurement patterns across the GCC diverge sharply by product architecture and end-use criticality. Sealed variants command material premiums in Saudi Arabia's desert fleet operations, while Wire-to-Wire configurations anchor volume economics in UAE-based assembly plants.
Product Type:
Supply concentration for terminal metallurgy and sealing architectures determines competitive positioning across connector families.
- Wire-to-Wire:These configurations join discrete cable harnesses without intermediate PCB substrates, typically employing crimped copper terminals with tin or silver plating. Demand concentrates in Dubai-Jebel Ali automotive cluster assembly lines where tier-1 suppliers are expanding regional distribution hubs for just-in-time delivery to OEM localization programs.
- Sealed Connectors:Environmental sealing rated to IP67 and above blocks dust ingress through multi-lip elastomer gaskets and potting compounds. Saudi Arabia's desert-operating commercial fleets mandate these specifications, creating price premiums over standard variants and qualifying specialized suppliers with SFDA-aligned material compliance documentation.
- Wire-to-Board:Direct harness-to-PCB interfaces serving cabin electronics modules in UAE vehicle platforms.
- Board-to-Board:Stacked PCB interconnects for compact infotainment and ADAS controller assemblies.
Today's leader: Wire-to-Wire. Tomorrow's challenger: Sealed Connectors.
Application:
Cost tier differentiation separates safety-critical applications from convenience electronics across Gulf assembly specifications.
- Safety Systems:Airbag deployment circuits, ABS sensor arrays, and ADAS camera modules demand fault-tolerant connector designs with redundant contact springs and gold-plated interfaces. Gulf regulators now mandate advanced driver-assistance hardware in new vehicle platforms, expanding connector procurement for electronic control units across Saudi and Emirati OEM programs.
- Powertrain:Engine management and transmission control connectors face extreme thermal cycling from minus 40 to 150 degrees Celsius plus vibration resistance exceeding 10G acceleration. High-voltage variants for hybrid platforms require electromechanical engineers with EV powertrain experience, a skill set concentrated in European and Asian talent markets.
- Body Electronics:Door modules, lighting controls, and HVAC interfaces with moderate environmental sealing requirements.
- Infotainment:Display and audio interconnects prioritizing signal integrity over mechanical ruggedness.
Safety Systems is climbing the fastest as regulatory mandates harden across GCC type-approval frameworks.
Customer Type:
Volume concentration tracks OEM localization timelines, with procurement patterns shifting from Asian import channels to regional supplier qualification.
- OEMs:Original equipment manufacturers operating Saudi Arabia and UAE vehicle assembly plants are compressing connector procurement cycles through direct supplier agreements rather than distributor intermediaries.
- Tier-1 Suppliers:Integrated wiring harness and electronics module providers expanding Dubai-Jebel Ali distribution hubs.
- Vehicle Assemblers:Contract manufacturers serving regional badge-engineering programs with standardized connector specifications.
- Aftermarket Providers:Independent distributors losing volume to dealer-captive parts programs in Riyadh-based heavy-duty truck maintenance facilities.
Procurement authority is concentrating with OEMs and tier-1 suppliers as fleet operators consolidate under single-source logistics agreements.
Installation:
Margin profiles diverge between capital-intensive automated lines and labor-dependent manual assembly operations.
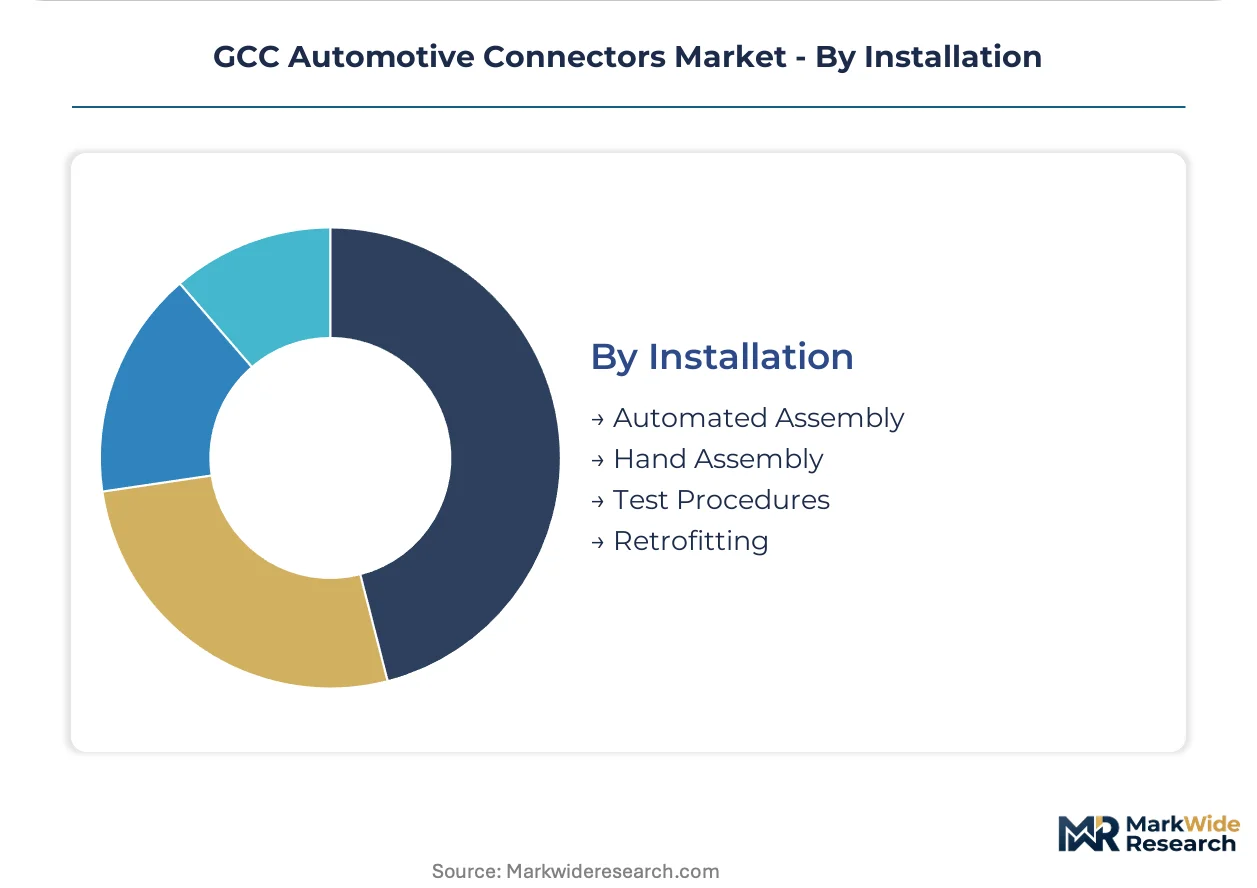
- Automated Assembly:Machine vision-guided crimping and insertion equipment eliminates manual inspection bottlenecks across GCC assembly lines. Tier-1 suppliers in the Dubai-Jebel Ali corridor deploy automated quality assurance at wire termination stations to achieve defect detection rates previously requiring dedicated engineering headcount.
- Hand Assembly:Low-volume prototyping and repair operations in aftermarket channels with higher per-unit labor costs.
- Test Procedures:SASO-mandated traceability documentation requires batch-level serialization for safety-critical connector assemblies.
- Retrofitting:Legacy fleet upgrades in Saudi commercial vehicle sector with compatibility constraints against existing harness architectures.
Automated Assembly commands investment priority as ESMA conformity timelines pressure qualification speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai-Jebel Ali automotive cluster anchors connector procurement intensity across the Gulf Cooperation Council, with tier-1 suppliers expanding regional distribution hubs to serve accelerating OEM localization programs in Saudi Arabia and the UAE.
Saudi Arabia
Electric vehicle manufacturing localization in Riyadh and Jeddah is compressing connector procurement cycles as Lucid Motors and Ceer Motors demand just-in-time delivery from regional suppliers. SASO technical regulations for automotive electrical components mandate batch-level serialization for safety-critical assemblies. Eastern Province heavy-duty truck fleets are consolidating connector procurement under single-source agreements with dealer-captive parts programs.
United Arab Emirates
Abu Dhabi's dual carbon goals and SFDA-aligned material compliance rules are tightening product specifications for connector imports across emirate assembly plants. ESMA conformity schemes extend type-approval durations and raise qualification costs for new market entrants. Dubai's Jebel Ali free zone hosts expanding regional distribution hubs for TE Connectivity and tier-1 wiring harness providers serving Gulf-wide OEM networks.
Qatar
Commercial vehicle fleet modernization ahead of FIFA legacy infrastructure maintenance is sustaining connector replacement demand in Doha-based logistics operations. The country's national standards body maintains alignment with Gulf Standards Organization REACH substance restriction frameworks. Ras Laffan industrial zone vehicle pools require sealed connector specifications for desert-operating conditions.
Kuwait
Ministry of Commerce and Industry import licensing for automotive electrical components is channeling connector procurement through established distributor relationships. Shuwaikh industrial area maintenance facilities are losing volume to OEM-affiliated service operations as fleet operators consolidate procurement. Mina Abdullah port logistics clusters are developing limited warehousing capacity for regional connector distribution.
Oman
Sohar free zone automotive assembly incentives are attracting tier-1 supplier warehousing investments to serve lower Gulf markets. The country's national standardization authority is harmonizing with SASO technical regulations to facilitate cross-border component trade. Duqm special economic zone vehicle project delays have deferred connector demand concentration anticipated for industrial fleet applications.
GCC Automotive Connectors Market Key Industry Players
High-voltage connector specialization dominates the current landscape as hybrid platform proliferation across Saudi and Emirati OEM programs rewards engineering depth over scale economies. The vendor base concentrates among multinational electromechanical specialists with Gulf logistics infrastructure, tier-1 integrated harness providers, and Japanese precision component manufacturers with regional distributor networks. Three archetypes define competitive positioning: vertically integrated global specialists, regional distribution-anchored tier-1 suppliers, and niche sealed connector providers for desert fleet applications. M&A activity targets high-voltage engineering talent pools, while capacity expansion focuses on Dubai-Jebel Ali warehousing to compress delivery cycles.
Within the multinational specialist tier, TE Connectivity leverages its Dubai logistics hub to secure Gulf-wide distribution reach, while Aptiv PLC occupies a position exemplifying high-voltage connector specialization for hybrid platforms. Amphenol Corporation represents the niche archetype through marine-grade sealed connector variants. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| TE Connectivity |
| Aptiv PLC |
| Amphenol Corporation |
| Yazaki Corporation |
| Molex Incorporated |
| Sumitomo Electric Industries, Ltd. |
| Hirose Electric Co., Ltd. |
| JST Manufacturing Co., Ltd. |
| Kyocera Corporation |
| Others |
Cost & Logistics Intelligence
Sovereign-backed industrial development funds across Saudi Arabia and the UAE are consolidating connector procurement under long-term offtake agreements, compressing spot-market liquidity while elevating price discipline for qualified suppliers with SASO and ESMA certifications.
Pricing Analysis
Silver and copper alloy terminal costs pass through directly to OEM procurement teams, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and volume scale. TE Connectivity and Aptiv PLC command brand premiums for high-voltage hybrid platform connectors, while unbranded Asian imports compete on per-unit economics for aftermarket replacement demand. Pricing pressure stems from raw material volatility as Gulf buyers lack long-term hedging mechanisms against London Metal Exchange fluctuations. Fleet operators in Saudi Arabia's Eastern Province commercial vehicle sector exhibit highest price sensitivity, whereas Abu Dhabi OEM assembly plants prioritize SFDA-aligned material compliance over unit cost minimization.
Supply Chain Analysis
Reverse-logistics flows for connector refurbishment remain underdeveloped across GCC markets, with end-of-life harness assemblies typically scrapped rather than remanufactured due to SASO batch-level serialization requirements that complicate component traceability. Manufacturing concentration rests on Japan, China, and South Korea for precision terminal stamping and elastomer sealing compounds, with Germany supplying high-voltage engineering expertise for hybrid platform variants. Raw material dependencies draw from Chilean copper concentrate, Indonesian nickel for alloy formulations, and Malaysian rubber for desert-grade sealing gaskets. Single-source vulnerability concentrates in East Asian connector housing injection molding, where shipping delays through the Strait of Hormuz expose GCC buyers to inventory disruption. Distribution runs through Dubai-Jebel Ali free zone warehousing for Gulf-wide OEM and tier-1 supplier fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC automotive connector procurement functions as a geographic-arbitrage play, with Dubai-Jebel Ali logistics infrastructure offering 15-20 day delivery advantages over direct Asian import channels for Saudi Arabia's accelerating EV localization programs.
For Market Incumbents: Cement regional distribution dominance by expanding Dubai-Jebel Ali warehousing capacity to capture just-in-time delivery contracts from Lucid Motors and Ceer Motors assembly plants. Invest in backward integration into copper alloy terminal production to offset silver plating cost volatility. Prioritize high-voltage connector engineering talent acquisition from European EV powertrain specialists before Asian competitors establish regional R&D footprints.
For New Entrants and Emerging Players: E-commerce procurement platforms targeting independent aftermarket distributors in Riyadh-based heavy-duty truck maintenance facilities offer lowest competitive density, as dealer-captive parts programs have displaced traditional distributor networks. White-space concentration sits with sealed connector variants for Saudi desert-operating commercial fleets, where Amphenol Corporation's marine-grade positioning leaves room for specialized entrants with SFDA-aligned material compliance documentation. Pursue direct technical service partnerships with Eastern Province fleet operators rather than distributor intermediaries.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Japanese precision component manufacturers with regional distributor networks but limited high-voltage engineering capabilities. Long-term viability across the analysis window hinges on hybrid platform proliferation across Saudi and Emirati OEM programs, rewarding engineering depth over scale economies. Target acquisition archetype: European electromechanical specialists with EV powertrain connector IP and limited Gulf logistics presence. Monitor ESMA conformity timeline compression as early signal for qualification cost barrier reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Engineering Talent Acquisition | Secures scarce electromechanical expertise for Saudi hybrid platform localization ahead of Asian competitors. |
| Dubai-Jebel Ali Warehousing Expansion | Compresses delivery cycles to Ceer Motors and Lucid Motors just-in-time procurement requirements. |
| SFDA-Aligned Material Compliance Investment | Unlocks premium positioning in Abu Dhabi assembly plants with dual carbon goal specifications. |
| Backward Integration into Terminal Metallurgy | Reduces silver plating cost exposure through captive copper alloy production capacity. |
| Direct Fleet Operator Partnership Programs | Circumvents distributor displacement in Riyadh heavy-duty truck maintenance consolidation. |
Research Approach
Coverage spans Saudi Arabia, UAE, Qatar, Kuwait, and Oman, with primary inputs from each national standards body and automotive cluster. The analysis combines structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and SFDA regulatory affairs specialists with secondary validation from SASO technical regulation filings, ESMA product conformity databases, Gulf Standards Organization harmonization protocols, and vehicle production registration data. Bottom-up connector shipment estimates triangulate against top-down OEM localization program announcements.
Granularity-level modeling operates at product type, application, customer tier, and installation method dimensions, with additional segmentation by propulsion architecture distinguishing internal combustion from hybrid and battery-electric platforms. Value projections across the analysis window derive from unit economics calibrated to raw material cost indices and regional certification burden estimates. CAGRs emerge from logistic growth curve fitting against OEM capacity expansion timelines and fleet replacement cycles. Forecast inputs incorporate copper price volatility scenarios and ESMA type-approval duration assumptions.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter high-voltage connector engineering requirements and qualification timelines. Forecasts reflect documented assumptions regarding Saudi EV localization pace and UAE dual carbon goal enforcement stringency. Practitioners should monitor Gulf Standards Organization REACH alignment acceleration and Dubai-Jebel Ali free zone warehousing capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Idler Arm Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Steering Gear Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Trailer Landing Gear Market