
 Steering Gear Market | 2026-2036
Steering Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Gear Market Analytics
Electric vehicle OEM procurement is consolidating as automakers abandon hydraulic architectures for electromechanical rack-and-pinion systems with integrated torque sensors. ZF Friedrichshafen AG leverages its chassis systems portfolio to anchor European premium EV supply chains. JTEKT Corporation dominates precision gear machining for Japanese and Southeast Asian OEM programs. Nexteer Automotive Corporation specializes in software-defined steering with over-the-air calibration capabilities.
Steering gear converts rotational input from the steering wheel into lateral wheel motion through a gear reduction mechanism, typically achieving ratios between 12:1 and 20:1 depending on vehicle class and maneuverability requirements. Rack-and-pinion architectures occupy the highest volume tier across passenger car platforms due to packaging efficiency and direct road feedback. Electronic steering segments sustain the fastest structural expansion as torque-vectoring and autonomous lane-keeping functions require programmable rack force. Recirculating ball systems retain residual demand in heavy commercial vehicles where load-bearing capacity exceeds rack-and-pinion mechanical limits.
NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity and fail-safe performance for US-market vehicles. EPA fuel economy regulations indirectly accelerate electromechanical adoption by eliminating parasitic losses from engine-driven hydraulic pumps. EU F-Gas Regulation and REACH chemical restrictions constrain hydraulic fluid formulations, tilting procurement toward sealed electronic units. Stakeholders must monitor how ISO 26262 functional safety grades and UN ECE automated driving regulations redefine supplier qualification thresholds for steer-by-wire architectures.
Market Dynamics
Electrification of vehicle architectures is compressing steering gear procurement cycles, as OEMs abandon hydraulic pumps for integrated electromechanical racks that eliminate parasitic losses and enable torque-vectoring software layers.
Growth Catalysts
- EPA fuel economy mandates:US tailpipe regulations penalize engine-driven hydraulic pumps, accelerating factory fitment of electromechanical rack-and-pinion units that recover 3-4% fuel efficiency.
- Autonomous lane-keeping requirements:SAE Level 2+ systems demand programmable rack force for micro-corrections, embedding torque sensors and redundant ECUs directly into steering gear housings.
- China EV production concentration:Domestic intelligent chassis programs from BYD, NIO, and Xpeng specify steer-by-wire platforms that consolidate steering motors with brake and suspension controllers.
Market Restraints
- Rare earth magnet supply concentration:Neodymium-dysprosium permanent magnets for steering motors face processing bottlenecks in China's Inner Mongolia refining corridor, creating input cost volatility.
- EU F-Gas Regulation friction:Hydraulic fluid formulations containing HFC-134a face phasedown schedules, forcing dual inventory management for suppliers serving both European and non-European assembly plants.
- Rack-and-pinion load limits:Heavy commercial vehicles above 7.5 tonnes gross vehicle weight retain recirculating ball architectures, fragmenting platform standardization and diluting scale economies.
Strategic Opportunities
- India PLI scheme for automotive components:Production-linked incentives for advanced driver assistance systems create localized manufacturing pull for torque-sensor-integrated steering gears serving Maruti Suzuki and Tata Motors.
- Software-defined steering calibration:Over-the-air update capabilities enable subscription-based handling profiles, converting hardware sales into recurring service revenue streams.
- Japan METI carbon-neutral vehicle roadmap:Battery electric and fuel cell commercial vehicle subsidies extend to chassis electrification, opening replacement demand for electromechanical recirculating ball variants.
Industry Challenges
- ISO 26262 ASIL-D certification timelines:Functional safety validation for steer-by-wire fault tolerance requires 18-24 month qualification cycles, compressing program launch windows.
- Legacy hydraulic service infrastructure:Independent repair networks face stranded asset risk as sealed electronic units reduce fluid change frequency and parts replacement rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Gear Market |
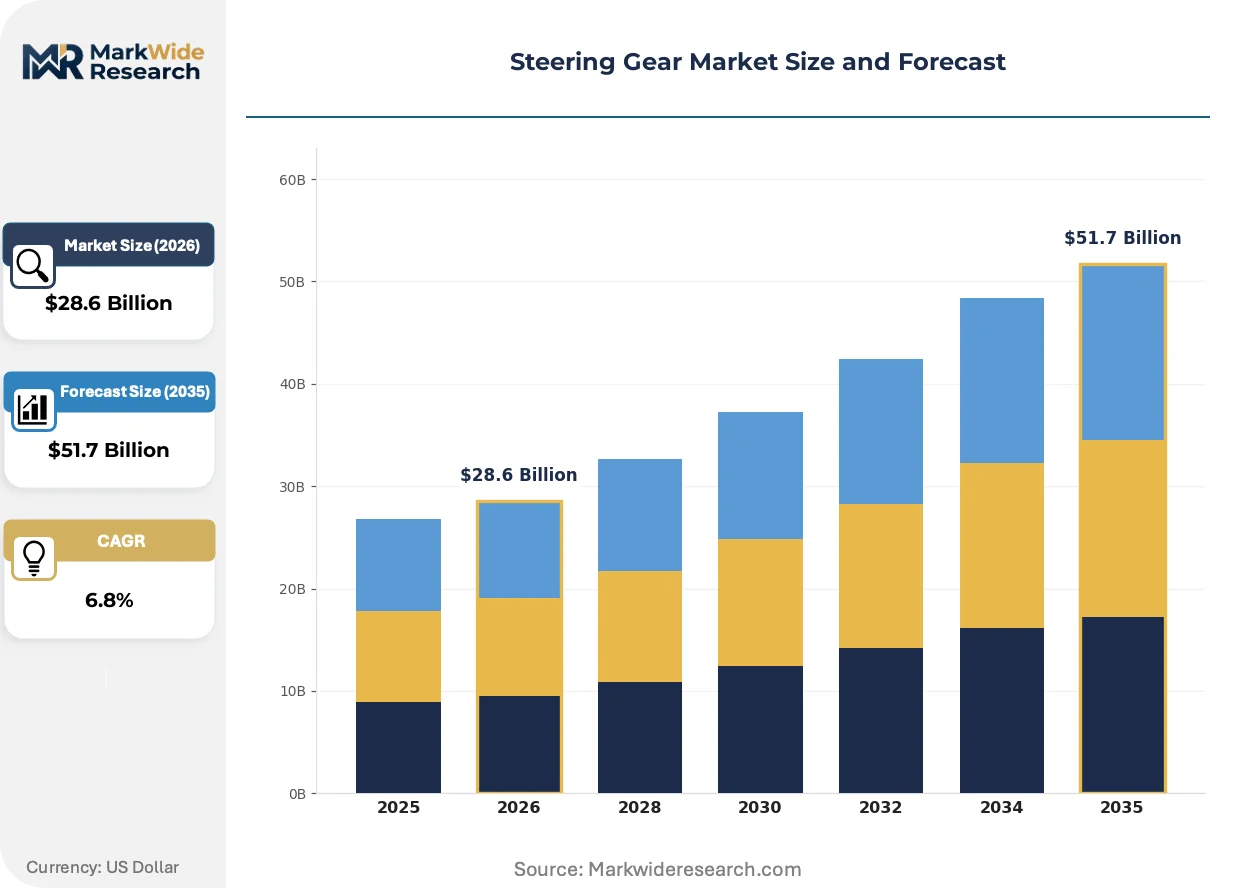
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack-and-Pinion, Recirculating Ball, Worm Gear, Electronic Vehicle Type: Passenger Car, Commercial Vehicle, Electric Vehicle, Hybrid Vehicle Application: Urban Driving, Racing, Off-Road, Highway End User: OEMs, Aftermarket, Fleet Operators, Car Rental Services |
| Companies Covered | JTEKT Corporation, ZF Friedrichshafen AG, Robert Bosch GmbH, Nexteer Automotive Corporation, NSK Ltd, Mando Corporation, Thyssenkrupp AG, Hyundai Mobis, Showa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Gear Market Evolving Landscape
Steer-by-wire architectures are collapsing the mechanical linkage between steering wheel and road wheels, enabling cockpit design freedom and crash safety improvements while demanding new validation protocols for haptic feedback fidelity.
Integrated steer-by-wire platforms are expanding into premium and mass-market electric vehicle segments simultaneously. ZF Friedrichshafen and Nexteer are shipping production units without steering columns for multiple 2024-2025 vehicle programs. This technology is expanding into chassis domain controller architectures that consolidate steering, braking, and suspension under single software stacks.
EU F-Gas Regulation is forcing hydraulic steering suppliers to reformulate working fluids away from high-global-warming-potential compounds. ECHA REACH restrictions on PFAS and chlorinated solvents compound formulation challenges. European commercial vehicle manufacturers are responding fastest, accelerating electromechanical platform adoption ahead of 2030 phase-down deadlines.
Fleet procurement managers are consolidating supplier relationships around vertically integrated chassis system providers capable of warrantying steering, braking, and suspension as unified subsystems. Tier 1 suppliers with software competencies are displacing pure hardware manufacturers in OEM request-for-quotation processes. This concentration is most visible in Germany and South Korea, where Hyundai-Kia and Volkswagen Group have issued consolidated intelligent chassis tenders.
Steering Gear Market Segmentation
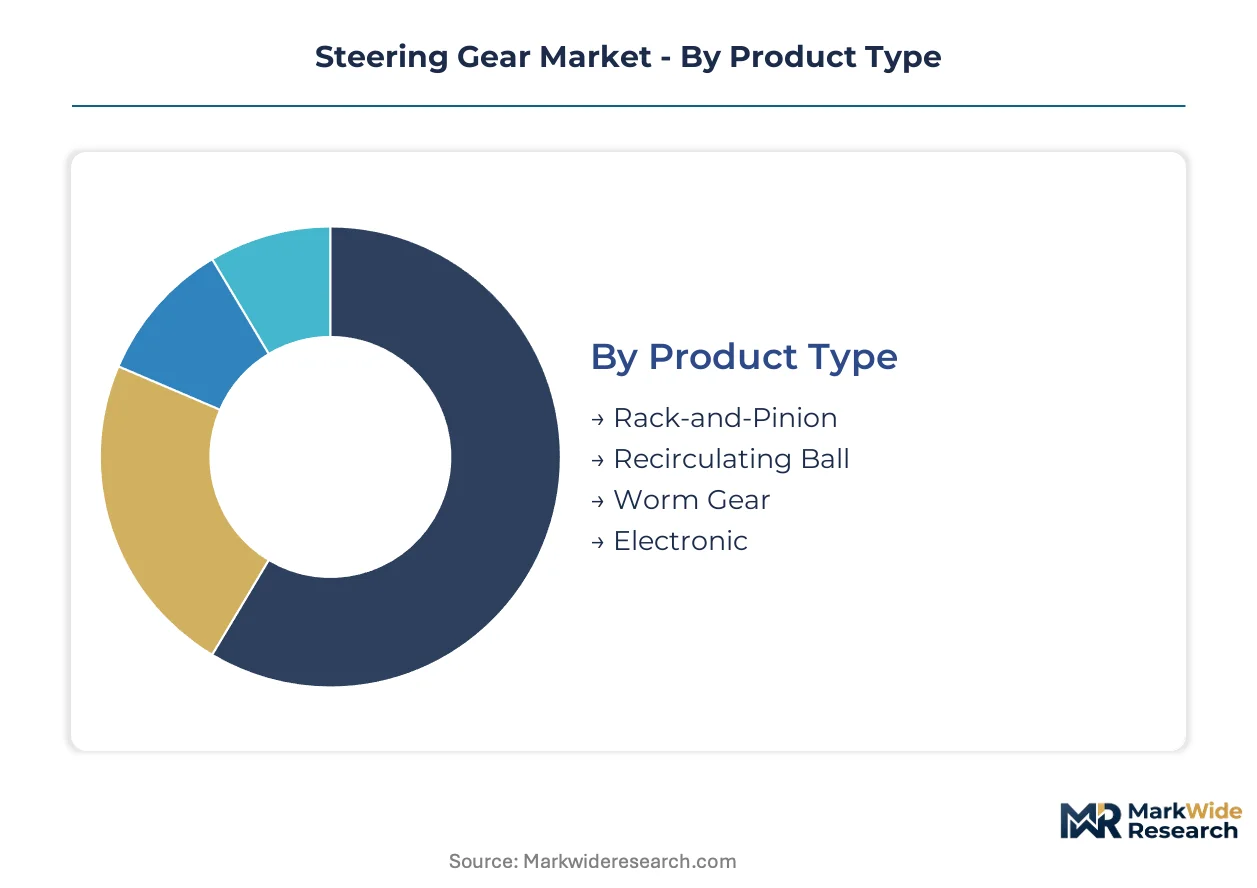
Steering gear procurement decisions hinge on load-bearing requirements, electrification architecture, and software integration depth. OEMs specify fundamentally different gear mechanisms for hydraulic legacy platforms versus steer-by-wire electric vehicle programs.
Product Type:
Cost tier drives supplier selection, with electronic units commanding premium positioning against mechanical alternatives.
- Rack-and-Pinion:Direct meshing of pinion gear with linear rack achieves 12:1 to 20:1 reduction ratios for precise road feedback. Passenger car OEMs in Germany and Japan specify this architecture for 90% of A-segment through E-segment platforms due to packaging efficiency and manufacturing scale.
- Electronic:Brushless DC motors with torque sensors eliminate mechanical linkages entirely, enabling programmable rack force for autonomous lane-keeping. BYD, NIO, and Xpeng procurement teams in China specify these units for intelligent chassis consolidation with brake-by-wire and active suspension controllers.
- Recirculating Ball:Circulating ball bearings reduce friction in high-load steering columns for commercial vehicles above 7.5 tonnes gross vehicle weight.
- Worm Gear:Self-locking characteristics suit heavy industrial and specialty off-highway applications with intermittent steering duty cycles.
Volume sits with Rack-and-Pinion; growth tilts toward Electronic.
Vehicle Type:
Application context determines durability specifications and software integration requirements across passenger, commercial, and electrified platforms.
- Passenger Car:Rack-and-pinion architectures dominate with electromechanical power assistance, achieving 3-4% fuel economy recovery versus hydraulic pumps under EPA testing protocols. European premium OEMs specify integrated torque sensors for SAE Level 2+ highway assistance functions.
- Electric Vehicle:Steer-by-wire platforms eliminate steering columns entirely, collapsing mechanical inventory and enabling cockpit design freedom. Chinese domestic brands specify these systems as standard equipment for intelligent chassis domain controllers.
- Commercial Vehicle:Recirculating ball systems retain mandatory status for load-bearing capacity above rack-and-pinion mechanical limits in heavy trucking applications.
- Hybrid Vehicle:Dual-powertrain architectures create transitional procurement specifying electromechanical racks compatible with both engine-on and electric-only operating modes.
Passenger Car holds installed base dominance; Electric Vehicle climbs the fastest.
Application:
Operating environment dictates gear ratio selection, sealing specifications, and thermal management requirements.
- Highway:Sustained high-speed operation demands precise on-center feel and minimal hysteresis for lane-keeping assistance. German autobahn-rated specifications from KBA certification protocols require redundant torque sensors and fail-safe mechanical backup paths.
- Urban Driving:Low-speed maneuverability with high steering angles prioritizes quick ratio racks and parking assistance integration. Japanese kei-car regulations specify ultra-compact rack housings for 3.4-meter vehicle length constraints.
- Off-Road:Contamination-resistant sealing and elevated torque capacity address unpaved surface impacts and water fording requirements.
- Racing:Minimal compliance, adjustable ratio mapping, and rapid response characteristics serve closed-circuit competition applications.
Highway commands specification premiums; Urban Driving gains share fastest.
End User:
Procurement scale and software control requirements separate fleet-level contracting from fragmented aftermarket demand.
- OEMs:Factory-fitment contracts specify ISO 26262 ASIL-D functional safety validation and 10-year corrosion warranties. Volkswagen Group and Hyundai-Kia consolidated intelligent chassis tenders now require unified subsystem warranties covering steering, braking, and suspension.
- Fleet Operators:Total cost of ownership calculations prioritize sealed electronic units with reduced fluid change intervals and predictive maintenance telemetry. Large European logistics fleets specify steer-by-wire for driver monitoring integration and insurance premium reductions.
- Aftermarket:Independent repair networks face stranded asset risk as sealed electronic units reduce serviceable parts and fluid replacement frequency.
- Car Rental Services:Turnover velocity and damage liability drive procurement toward standardized, rapidly replaceable rack-and-pinion units with broad vehicle coverage.
OEMs concentrate manufacturing volume; Fleet Operators expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate electromechanical steering production capacity serving BYD and NIO intelligent chassis programs. German automotive clusters anchor European premium EV supply chains with integrated steer-by-wire development. Japanese precision machining corridors sustain rack-and-pinion manufacturing for Southeast Asian export markets.
China
Domestic EV brands BYD, NIO, and Xpeng consolidate procurement around steer-by-wire platforms with brake and suspension domain controllers. MIIT dual carbon goals accelerate factory electrification mandates for chassis component suppliers. Shanghai and Shenzhen industrial corridors host concentrated electromechanical steering motor production for intelligent chassis architectures.
Germany
Volkswagen Group and BMW specify ISO 26262 ASIL-D certified electromechanical racks for SAE Level 2+ highway assistance functions. KBA certification protocols mandate redundant torque sensors and fail-safe mechanical backup paths for autobahn-rated specifications. Stuttgart and Munich engineering clusters drive steer-by-wire validation for premium EV platforms.
United States
EPA fuel economy mandates penalize engine-driven hydraulic pumps, accelerating electromechanical rack fitment for 3-4% efficiency recovery. NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity and fail-safe performance for domestic-market vehicles. Detroit and Tennessee assembly corridors concentrate procurement from vertically integrated chassis system providers.
Japan
Toyota and Honda procurement teams specify precision-machined rack-and-pinion units for hybrid powertrain compatibility across engine-on and electric-only modes. METI carbon-neutral vehicle roadmap extends subsidies to battery electric and fuel cell commercial vehicle chassis electrification. Nagoya and Osaka manufacturing belts sustain gear machining excellence for Southeast Asian OEM export programs.
South Korea
Hyundai-Kia consolidated intelligent chassis tenders require unified subsystem warranties covering steering, braking, and suspension. MFDS automotive safety regulations align with UN ECE automated driving standards for supplier qualification thresholds. Seoul Capital Area and Busan-Ulsan industrial zones anchor electromechanical steering production for domestic and export EV programs.
Steering Gear Market Competitive Landscape
Top-tier vendors anchor consolidated OEM supply relationships, while mid-tier specialists compete on regional cost positioning and application-specific certifications. The vendor base stratifies across three functional tiers: full-system chassis integrators, electromechanical component specialists, and precision gear machining houses. Strategic archetypes include software-defined steering developers, rare earth magnet supply chain controllers, and legacy hydraulic service network operators. Dominant competitive moves encompass backward integration into torque sensor manufacturing and strategic partnerships with intelligent chassis domain controller developers.
Within the full-system chassis integrator tier, ZF Friedrichshafen AG and Nexteer Automotive Corporation exemplify vertically integrated suppliers capable of warranting steering, braking, and suspension as unified subsystems. JTEKT Corporation occupies a position among precision gear machining specialists serving Japanese and Southeast Asian OEM programs with established quality protocols.
| Leading Market Players |
|---|
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Nexteer Automotive Corporation |
| NSK Ltd |
| Mando Corporation |
| Thyssenkrupp AG |
| Hyundai Mobis |
| Showa Corporation |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down schedules gate qualified supply access for hydraulic steering gear manufacturers while simultaneously erecting premium-tier pricing barriers for electromechanical alternatives that eliminate fluid-dependent architectures entirely. OEM procurement teams now face bifurcated qualification pathways where sustainability compliance determines supplier eligibility and tier positioning.
Pricing Analysis
Lead-time premiums compress margins for urgent electromechanical rack orders while spot inventory of legacy hydraulic units trades at distressed levels. Three-tier pricing structure across premium steer-by-wire, standard electromechanical, and economy hydraulic levels reflects ISO 26262 ASIL-D certification investment and rare earth magnet input costs. Pricing pressure stems from neodymium-dysprosium supply bottlenecks in China's Inner Mongolia refining corridor. Fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while premium EV OEMs absorb certification premiums for software-defined steering capabilities.
Supply Chain Analysis
Regional distribution centers in Shanghai, Stuttgart, and Detroit anchor hub-and-spoke patterns for electromechanical steering motor and torque sensor components. Manufacturing concentrates in China, Germany, and Japan for precision gear machining and motor assembly. Supply chains draw from rare earth magnet processors, semiconductor foundries, and specialty steel mills. Single-source vulnerability around neodymium-dysprosium refining creates structural exposure to export restriction shocks. Distribution runs through vertically integrated chassis system providers capable of unified subsystem warranties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steering gear sector sits in a technology-transition phase where steer-by-wire architectures displace mechanical linkages and hydraulic pumps across passenger and commercial vehicle platforms. Electromechanical rack-and-pinion systems with integrated torque sensors are replacing legacy architectures.
For Market Incumbents: Cement consolidated intelligent chassis supply relationships by warranting steering, braking, and suspension as unified subsystems. Invest in backward integration into torque sensor manufacturing to offset rare earth magnet cost volatility. Threat substitution from Chinese domestic EV brands with captive chassis development compresses European and Japanese supplier margins. For New Entrants and Emerging Players: Digital aftermarket calibration platforms offer white-space entry points for subscription-based handling profile services. Target India's PLI scheme for automotive components serving Maruti Suzuki and Tata Motors intelligent chassis programs. Fleet operator telematics integration provides the most penetrable go-to-market angle for predictive maintenance revenue streams. For Investors and Strategic Acquirers: Consolidated intelligent chassis tenders from Hyundai-Kia and Volkswagen Group are the leading indicator that software-defined steering capabilities command acquisition premiums. Five-to-ten-year viability favors electromechanical specialists with ISO 26262 ASIL-D validation infrastructure. Acquisition target archetypes include torque sensor manufacturers and steer-by-wire software stacks. Watch for tiered supplier qualification thresholds under UN ECE automated driving regulations as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Torque Sensors | Captive supply of critical electromechanical components reduces rare earth magnet cost exposure. |
| Software-Defined Steering Calibration | Over-the-air handling profiles convert hardware sales into recurring service revenue streams. |
| ISO 26262 ASIL-D Certification Investment | Functional safety validation qualifies suppliers for SAE Level 2+ highway assistance programs. |
| Intelligent Chassis Domain Controller Partnership | Unified subsystem warranties with brake and suspension developers displace pure hardware manufacturers. |
| India PLI Scheme Localization | Production-linked incentives create manufacturing pull for torque-sensor-integrated steering gears. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and intelligent chassis domain controller developers provided qualitative validation. Secondary sources encompassed NHTSA safety standard databases, EPA fuel economy compliance filings, EU F-Gas Regulation implementation reports, and vehicle production registration data from national automotive associations. Bottom-up segment sizing triangulated against top-down market value estimates.
Data-stream reconciliation across production volume databases, component bill-of-materials analysis, and OEM procurement contract disclosures informed the analytical framework. Segmentation dimensions modeled vehicle class, propulsion architecture, gear mechanism type, and regional production cluster. CAGRs derived from fitted growth curves applied to electromechanical adoption rates and steer-by-wire penetration assumptions. Forecast inputs incorporated EPA tailpipe standard stringency trajectories and MIIT dual carbon goal implementation timelines.
The model holds under sustained electrification mandates and rare earth supply continuity; deviation in export restriction severity or autonomous driving regulatory delays would shift trajectory. Forecasts reflect documented assumptions around technology substitution elasticities and supplier consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Thrust Bearings Market
Vehicle Components
EGR Valve Market
Vehicle Components
Transmission Components Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Trailer Landing Gear Market