
 Global Automotive Wheel Bearings Market | 2026-2036
Global Automotive Wheel Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Wheel Bearings Market Analysis
East Asian bearing producers is pivoting toward integrated hub assembly capacity to capture electric vehicle platform contracts. SKF leverages its European R&D footprint to sustain technology leadership in low-friction seal designs. Timken Company anchors North American heavy-duty commercial vehicle supply through vertically controlled heat-treatment operations. Schaeffler Group differentiates via mechatronic bearing modules that merge sensor integration with mechanical performance.
Automotive wheel bearings are precision-engineered rolling-element components, typically manufactured from through-hardened chromium steel with raceway surface finishes below 0.2 micrometers Ra, designed to support radial and axial loads while enabling controlled wheel rotation. Ball bearings dominate passenger vehicle steering and drivetrain positions where moderate loads and high-speed operation predominate. Roller bearings occupy the fastest-expanding niche in commercial vehicle hubs and electric vehicle platforms where higher load capacity and extended service intervals command premium positioning. Tapered bearings retain structural importance in brake system integration and suspension knuckle assemblies across legacy internal combustion architectures.
The US NHTSA and EPA jointly shape product demand through fuel economy standards that incentivize bearing weight reduction and friction loss minimization. China's MIIT enforces GB standards for automotive component durability that directly specify bearing life test protocols. Europe's REACH regulation and CE marking requirements constrain lubricant chemistry and material composition choices for suppliers accessing EU vehicle assembly chains. Stakeholders must monitor regulatory divergence between Chinese efficiency mandates and European material restriction frameworks when configuring regional product portfolios.
Market Dynamics
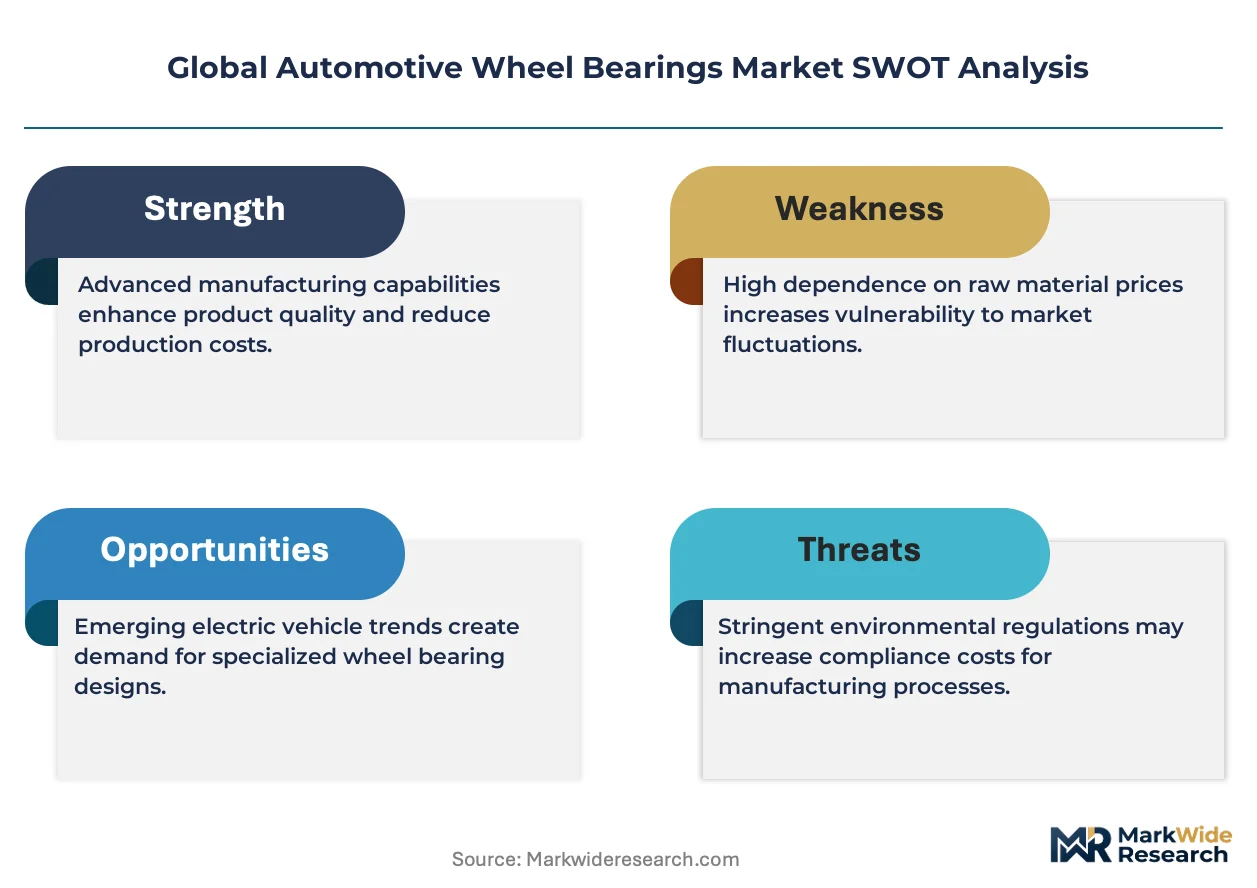
Electric vehicle platform architecture is compressing bearing supplier margins while demanding integrated hub assemblies that combine mechanical rotation with sensor telemetry and thermal management functions.
Growth Catalysts
- China MIIT lightweighting mandates:GB standards for component mass reduction force OEMs toward hollow-section bearing designs and ceramic rolling elements, accelerating material substitution in passenger vehicle steering knuckles.
- Commercial vehicle electrification:Heavy-duty truck and bus platforms in North America and Europe require bearings rated for 500,000+ kilometer service intervals, pulling tapered roller configurations into extended-life specifications.
- Sensor-integrated hub assemblies:ABS, wheel speed, and temperature monitoring functions are merging into single bearing cartridges, creating value capture opportunities for mechatronics-capable suppliers.
Market Restraints
- Alloy steel price volatility:Chromium and molybdenum input costs fluctuate with mining output from South Africa and Kazakhstan, compressing gross margins for heat-treatment-dependent producers.
- REACH lubricant chemistry constraints:ECHA restrictions on perfluorinated compounds limit seal material options for EU-bound products, forcing reformulation investments without price recovery mechanisms.
- Ceramic bearing substitution ceiling:Silicon nitride rolling elements face cost barriers above 40 millimeter bore diameters, capping penetration in commercial vehicle hub positions.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced manufacturing equipment create first-mover advantages for integrated hub assembly capacity serving domestic EV and export markets.
- Remanufactured bearing channels:Circular economy frameworks in Germany and France are legitimizing refurbished commercial vehicle bearings, opening aftermarket revenue streams outside OEM warranty structures.
- Dual carbon goals in China:Provincial MEE enforcement of carbon intensity targets for automotive suppliers favors low-energy heat-treatment processes and localized forging operations.
Industry Challenges
- Tribology and sensor fusion talent scarcity:Bearing engineers with simultaneous expertise in contact mechanics and signal processing command premium compensation, constraining R&D team scaling.
- ISO 26262 functional safety certification:Automotive safety integrity level validation for sensor-integrated bearings extends development timelines by 14-18 months, delaying platform contract awards.
- Legacy fleet service interval compression:Internal combustion vehicle owners deferring maintenance during economic uncertainty create warranty exposure for premature bearing failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Wheel Bearings Market |
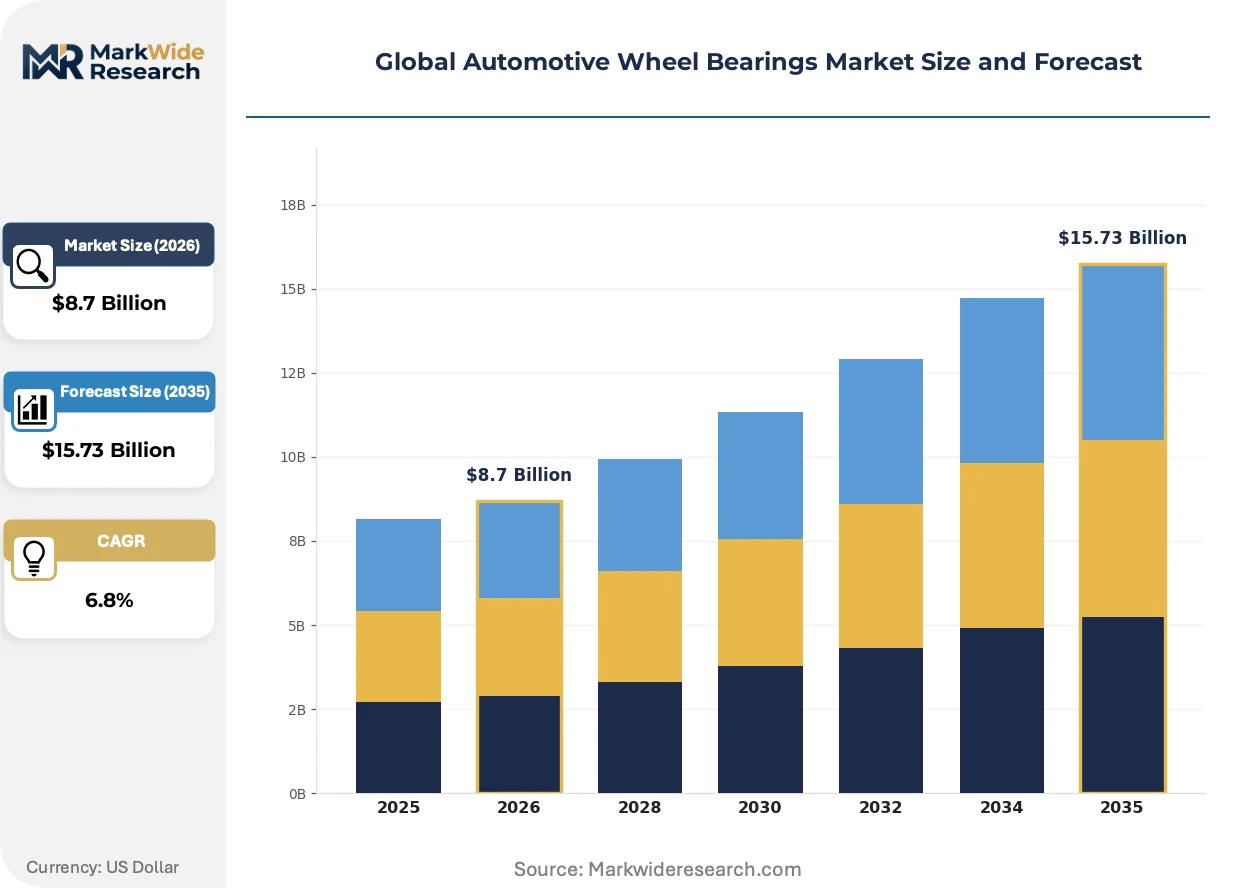
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Roller Bearings, Tapered Bearings, Spherical Bearings Vehicle Type: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles Sales Channel: OEMs, Aftermarket, Distributors, Online Retail Application: Steering Systems, Suspension Systems, Drivetrain Systems, Brake Systems |
| Companies Covered | NTN Corporation, Timken Company, SKF, C&U Group, Nachi-Fujikoshi Corp., Schaeffler Group, JTEKT Corporation, ILJIN Group, NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Wheel Bearings Market Emerging Trajectories
Digital twin simulation and predictive maintenance algorithms are redefining how bearing performance is guaranteed, shifting supplier value propositions from component sales to uptime assurance.
Integrated hub-bearing assemblies with built-in torque sensors and thermal monitoring are consolidating multiple vehicle functions into single sealed units. Tier-1 suppliers serving premium German OEMs are adopting these configurations fastest, with platform awards now requiring 10-year corrosion resistance validation. This consolidation is compressing the addressable market for standalone bearing manufacturers while elevating capital barriers for new entrants.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of seal elastomers and grease thickeners used in EU-bound automotive bearings. Suppliers must now qualify hydrogenated nitrile and polyurea alternatives through 2,000-hour durability testing. The regulation most impacts small-series specialty producers lacking in-house lubricant chemistry capabilities, driving consolidation toward integrated material science operations.
Fleet operators and leasing companies are unbundling bearing maintenance from full-service contracts, creating direct procurement relationships with component suppliers. This disintermediation bypasses traditional aftermarket distributors in North American heavy-duty trucking corridors. The shift is most visible in long-haul logistics networks where telematics-enabled condition monitoring allows predictive replacement scheduling rather than interval-based maintenance.
Global Automotive Wheel Bearings Market Segmentation
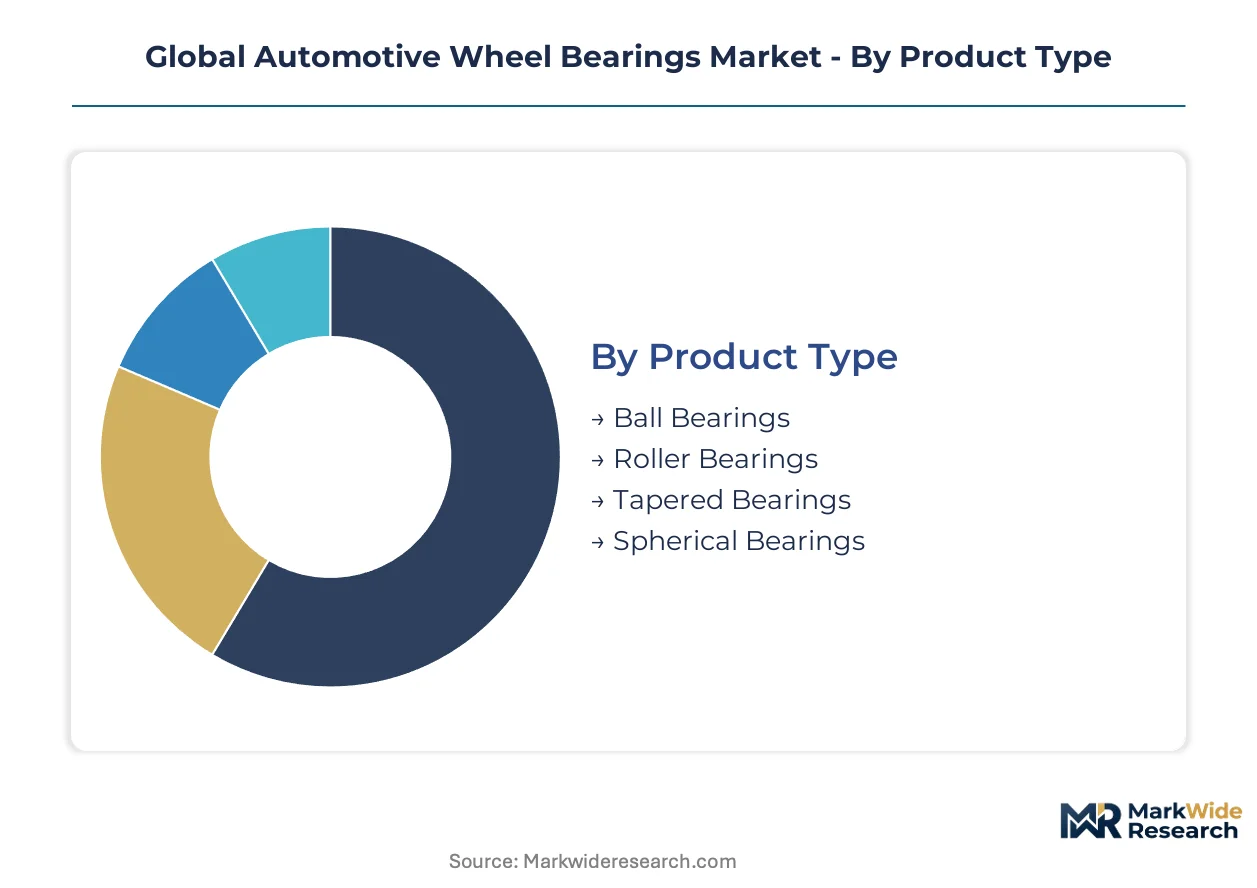
Automotive wheel bearing segmentation reveals how engineering specifications, vehicle architectures, and procurement channels fragment demand. Suppliers configure production lines around these divisions to capture platform-specific contracts and aftermarket service intervals.
Product Type:
Standardization dominates ball bearing production while roller and tapered configurations require extensive customization for load ratings and seal integration.
- Ball Bearings:Precision-ground chromium steel raceways with surface finishes below 0.2 micrometers Ra support moderate radial loads in high-speed steering positions. Passenger vehicle steering knuckle assemblies in Germany's premium manufacturing corridor specify these for friction minimization under NHTSA fuel economy guidelines.
- Roller Bearings:Cylindrical and needle configurations handle higher load densities across extended service intervals. Commercial vehicle hub positions in North America and electric vehicle platforms in China pull these into 500,000-kilometer durability specifications under MIIT efficiency mandates.
- Tapered Bearings:Conical raceway geometry manages combined radial and thrust loads in brake system integration.
- Spherical Bearings:Self-aligning designs accommodate misalignment in suspension articulation points.
Most installed capacity flows through Ball Bearings. Expansion is steepest in Roller Bearings.
Vehicle Type:
Volume concentration sits with legacy internal combustion platforms while electrification redefines bearing integration requirements.
- Passenger Vehicles:High-volume production lines supply steering and drivetrain positions across mass-market and premium segments. China's MIIT lightweighting mandates accelerate hollow-section bearing adoption in domestic OEM supply chains.
- Electric Vehicles:Integrated hub assemblies merge mechanical rotation with torque sensors and thermal management. SKF and Schaeffler Group capture platform awards requiring 10-year corrosion resistance validation for European EV architectures.
- Commercial Vehicles:Heavy-duty trucks and buses specify extended-life tapered configurations for 500,000+ kilometer intervals.
- Two-Wheelers:Compact sealed units prioritize cost efficiency over serviceability in high-volume Asian markets.
Passenger Vehicles absorb the largest production share. Electric Vehicles are climbing the fastest as platform awards consolidate around integrated hub suppliers.
Sales Channel:
Direct OEM relationships command premium positioning while aftermarket channels fragment across distributor networks and emerging digital procurement.
- OEMs:Tier-1 suppliers negotiate multi-year platform contracts with embedded sensor integration and predictive maintenance telemetry. German premium OEMs now require ISO 26262 functional safety certification, extending development timelines.
- Aftermarket:Fleet operators in North American long-haul corridors bypass traditional distributors through telematics-enabled direct procurement relationships.
- Distributors:Regional warehousing networks service independent repair channels with interval-based replacement inventory.
- Online Retail:Digital platforms capture DIY replacement demand with specification-matching algorithms for legacy vehicle populations.
OEMs concentrate the highest value contracts. Online Retail is gaining share fastest as fleet procurement digitizes.
Application:
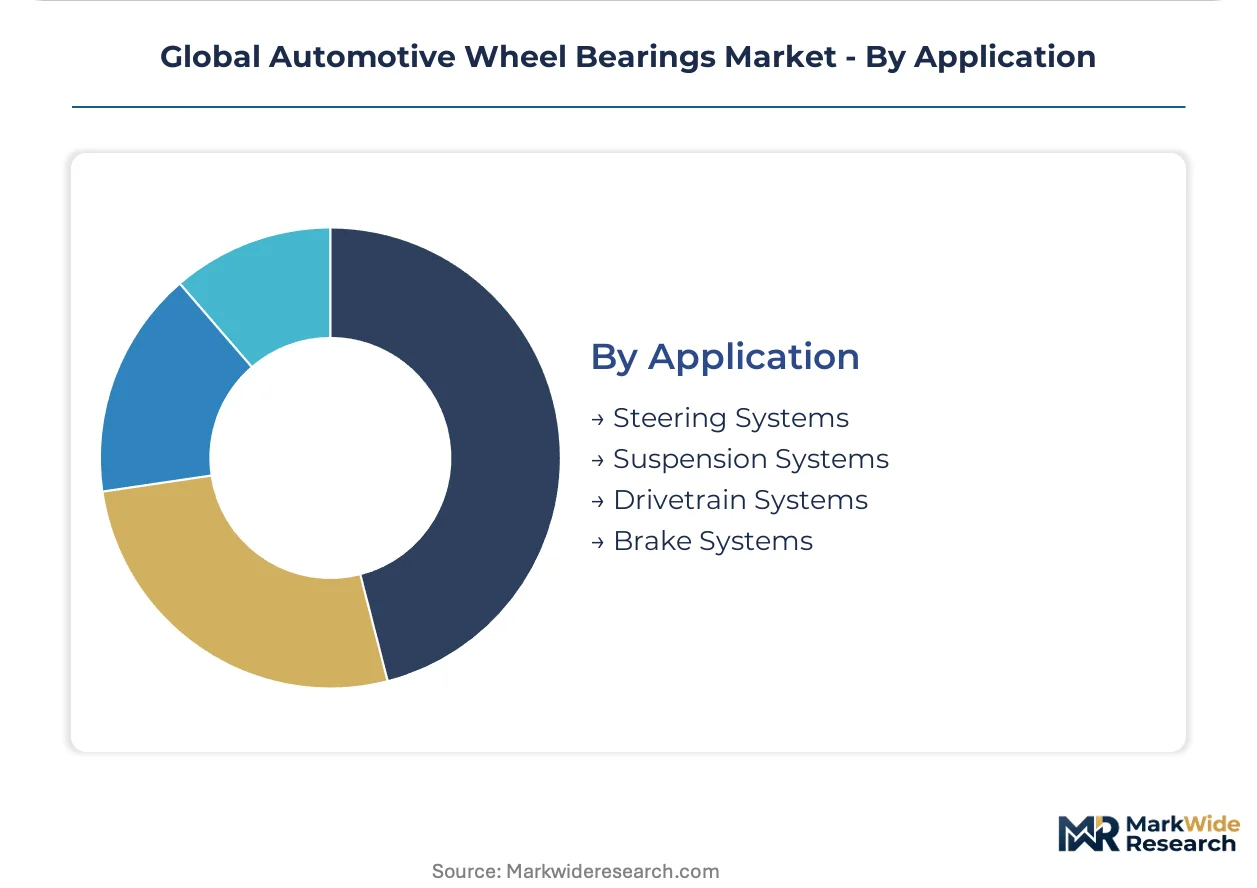
Functional location within vehicle architecture determines load characteristics, seal requirements, and sensor integration complexity.
- Steering Systems:Low-friction ball bearings enable precise feedback in rack-and-pinion and steering column assemblies. China's GB standards for component durability specify accelerated life test protocols for these positions.
- Suspension Systems:Spherical and tapered configurations manage multi-axis loads through knuckle and control arm pivot points. REACH Annex XVII restrictions on seal elastomers force hydrogenated nitrile qualification through 2,000-hour testing for EU-bound products.
- Drivetrain Systems:Axle and differential bearings handle torque transmission with minimal power loss.
- Brake Systems:Tapered bearings maintain rotor alignment under thermal cycling and hydraulic pressure.
Steering Systems anchor the largest installed base. Suspension Systems show the steepest specification escalation as electrified platforms demand integrated sensor hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as suppliers migrate capacity toward jurisdictions with lower compliance costs for heat-treatment emissions and material chemistry standards. China's MIIT efficiency mandates and Europe's REACH restrictions create divergent cost structures that influence where forging and finishing operations locate.
China
Domestic EV platform expansion drives integrated hub assembly demand across multiple provincial manufacturing clusters. MIIT-enforced GB standards for component durability and lightweighting accelerate hollow-section bearing adoption and ceramic rolling element trials. Yangtze River Delta concentration around Shanghai and Jiangsu hosts the densest supplier ecosystem serving BYD, NIO, and export-oriented joint ventures.
Germany
Premium OEM sourcing requirements for 10-year corrosion resistance validation sustain high-specification bearing demand across powertrain and chassis positions. REACH Annex XVII restrictions on seal elastomers and lubricant chemistry force hydrogenated nitrile qualification investments. Baden-Württemberg's Stuttgart-centric supplier corridor anchors development of mechatronic hub modules merging torque sensing with mechanical rotation.
United States
Heavy-duty commercial vehicle electrification pulls extended-life tapered configurations into 500,000-mile service interval specifications. NHTSA fuel economy standards incentivize friction reduction through low-drag seal designs. Michigan-Ohio manufacturing belt concentration serves Detroit Three platforms while Texas-based forging operations supply oil-field service vehicle aftermarket channels.
Japan
Precision manufacturing heritage sustains dominance in ball bearing segments for steering and high-speed drivetrain positions. METI industrial policy supports advanced material R&D for silicon nitride rolling element cost reduction. Kansai region Osaka-Kobe industrial corridor maintains specialized heat-treatment capacity for through-hardened chromium steel raceway finishing below 0.2 micrometers Ra.
India
PLI scheme production-linked incentives for advanced manufacturing equipment attract integrated hub assembly investments serving domestic EV and two-wheeler export markets. BIS standards adoption for automotive component durability creates certification barriers for unorganized sector suppliers. Tamil Nadu's Chennai-Sriperumbudur automotive belt concentrates forging and machining capacity for Maruti Suzuki and Hyundai Motor India platforms.
Global Automotive Wheel Bearings Market Vendor Landscape
East Asian producers anchor one tier of supply; European specialists hold premium positioning through functional safety certification and mechatronics integration. Market structure concentrates around heat-treatment-dependent integrated manufacturers and material-science-focused precision specialists. Three archetypes dominate: vertically controlled forging-to-finish operators, sensor-integrated hub assemblers, and ceramic rolling element technology developers. Competitive moves center on ISO 26262 validation acceleration and regional forging capacity expansion to capture EV platform awards.
Within the integrated hub assembly tier, Schaeffler Group and SKF occupy positions defined by mechatronics capability and European R&D proximity to premium OEM validation requirements. Timken Company represents the North American heavy-duty commercial vehicle anchor with heat-treatment operations supporting extended service interval specifications. NTN Corporation, JTEKT Corporation, and NSK Ltd. exemplify the East Asian precision manufacturing cluster serving high-volume steering and drivetrain positions through forged chromium steel raceway expertise.
| Leading Market Players |
|---|
| NTN Corporation |
| Timken Company |
| SKF |
| C&U Group |
| Nachi-Fujikoshi Corp. |
| Schaeffler Group |
| JTEKT Corporation |
| ILJIN Group |
| NSK Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive heat-treatment operations among integrated manufacturers anchor both supply security and pricing power in automotive wheel bearings, insulating Tier-1 suppliers from chromium and molybdenum volatility while compressing margins for outsourced forging specialists serving aftermarket channels.
Pricing Analysis
Distributor margin layers in the aftermarket segment absorb 25-35 point markups above OEM direct-contract pricing, with fleet operators in North American long-haul corridors increasingly bypassing these intermediaries through telematics-enabled procurement relationships. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified mechatronic hub assemblies from commodity ball bearings and unbranded replacement units. Pricing pressure stems from alloy steel input cost volatility originating in South African and Kazakh mining output, compressing gross margins for heat-treatment-dependent producers without backward integration into forging operations. Aftermarket distributors and independent repair channels exhibit highest price sensitivity, while German premium OEMs prioritize corrosion resistance validation and functional safety certification over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German and US OEMs mandate multi-supplier qualification for critical hub assembly positions, forcing bearing manufacturers to maintain redundant forging and finishing capacity across Germany, China, and Japan. Raw material dependencies center on through-hardened chromium steel from Japanese specialty mills, ceramic rolling element precursors from Japanese and European suppliers, and hydrogenated nitrile seal compounds qualified under REACH Annex XVII. Supply chain risk concentrates in single-source vulnerability for sub-0.2 micrometer Ra raceway finishing equipment, where Kansai region specialists control specialized heat-treatment capacity. Distribution runs through Tier-1 supplier direct fulfillment to OEM assembly plants, with emerging digital procurement platforms disintermediating traditional aftermarket warehousing networks in North American heavy-duty trucking corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive wheel bearings offer margin expansion through integrated hub assembly premiumization, as sensor-telemetry bundling and predictive maintenance algorithms shift supplier value propositions from component sales toward uptime assurance contracts.
For Market Incumbents: Hedge against ceramic rolling element substitution ceilings by accelerating silicon nitride cost reduction programs and securing long-term supply agreements with Japanese precursor suppliers. Defensive consolidation moves should prioritize captive heat-treatment capacity expansion in India's Tamil Nadu corridor to capture PLI scheme benefits, while ISO 26262 certification investments protect platform awards from mechatronics-capable challengers. Threat of REACH lubricant chemistry constraints without price recovery mechanisms demands proactive seal elastomer reformulation partnerships. For New Entrants and Emerging Players: Launch via telematics-enabled direct procurement relationships targeting North American fleet operators unbundling bearing maintenance from full-service contracts. White-space targets include remanufactured commercial vehicle bearings in Germany and France under circular economy frameworks, and hollow-section bearing designs for China's MIIT-mandated lightweighting requirements. Most penetrable segment sits with aftermarket digital platforms specification-matching legacy vehicle populations, bypassing traditional distributor markups through algorithm-driven inventory positioning. For Investors and Strategic Acquirers: Roll-up economics work for vertically controlled forging-to-finish specialists because OEM platform consolidation around integrated hub suppliers is compressing the addressable market for standalone bearing manufacturers. Long-term viability over the 5-10 year window hinges on mechatronics integration capability and regional forging proximity to EV production clusters. Acquisition target archetype: mid-cap heat-treatment operators with latent sensor integration engineering capacity. Signal to watch: provincial MEE enforcement intensity for carbon intensity targets in China's Yangtze River Delta manufacturing belt.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Hub Assembly Capacity Expansion | Captures EV platform awards requiring 10-year corrosion resistance validation from German OEMs. |
| ISO 26262 Functional Safety Certification | Accelerates development timelines for sensor-integrated bearings in premium vehicle architectures. |
| Regional Forging Footprint Optimization | Positions suppliers for India's PLI scheme incentives and China's dual carbon enforcement. |
| Ceramic Rolling Element Cost Reduction | Extends silicon nitride penetration beyond 40 millimeter bore diameter commercial vehicle limits. |
| Predictive Maintenance Algorithm Development | Shifts value capture from component sales to uptime assurance contracts with fleet operators. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and heat-treatment operations specialists with secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from listed bearing manufacturers, and MIIT GB standards documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches distributed value and volume projections across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from regression analysis of historical platform award volumes, technology substitution curves for ceramic versus steel rolling elements, and regulatory mandate implementation timelines. Industry-specific forecast inputs included MIIT lightweighting mandate compliance trajectories and REACH Annex XVII reformulation investment cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt alloy steel price spikes or accelerated commercial vehicle electrification timelines. Deviation in NHTSA fuel economy standard stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Rear Axle Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Transmission Components Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Electric Forklifts Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Car Radiator Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
Global Tyre Inflators Market