
 Sea-Based Vehicle Carrier Market | 2026-2036
Sea-Based Vehicle Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Sea-Based Vehicle Carrier Market Analytics
Project finance through sale-and-leaseback structures is rewriting capital access for mid-tier fleet operators. Höegh Autoliners leverages long-term charter-backed financing to sustain one of the youngest LNG-capable fleets in the segment. Wallenius Wilhelmsen anchors its competitive stance through integrated logistics control spanning factory gate to dealer delivery. NYK Line competes via dedicated pure car and truck carrier divisions with concentrated exposure to Japanese OEM export schedules.
Sea-based vehicle carriers are specialized roll-on/roll-off vessels with multiple weather decks, ramp systems, and internal deck heights adjustable to accommodate sedans through heavy construction equipment, typically achieving capacities between 4,000 and 8,000 vehicle equivalents. These vessels serve the primary commercial purpose of transporting finished automobiles, trucks, and rolling stock across oceanic trade lanes where land bridges prove uneconomical or impossible. Roll-on/roll-off carrier types dominate structural deployment due to their loading efficiency and compatibility with automaker just-in-sequence logistics requirements. Charter services command premium margin pools where automakers seek vessel dedication for new model launches or seasonal volume spikes, while scheduled liner services represent the mature volume backbone connecting major production and consumption markets.
The International Maritime Organization's Energy Efficiency Existing Ship Index and the EU Emissions Trading System are tightening operational parameters for vessels calling at European ports, forcing accelerated fleet renewal or costly retrofit investments. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces domestic safety standards that exceed baseline SOLAS requirements, shaping vessel design specifications for operators serving Japanese trade lanes. Stakeholders must monitor how differentiated regulatory stringency across flag states and port states reshapes fleet deployment economics and competitive positioning in the years ahead.
Market Dynamics
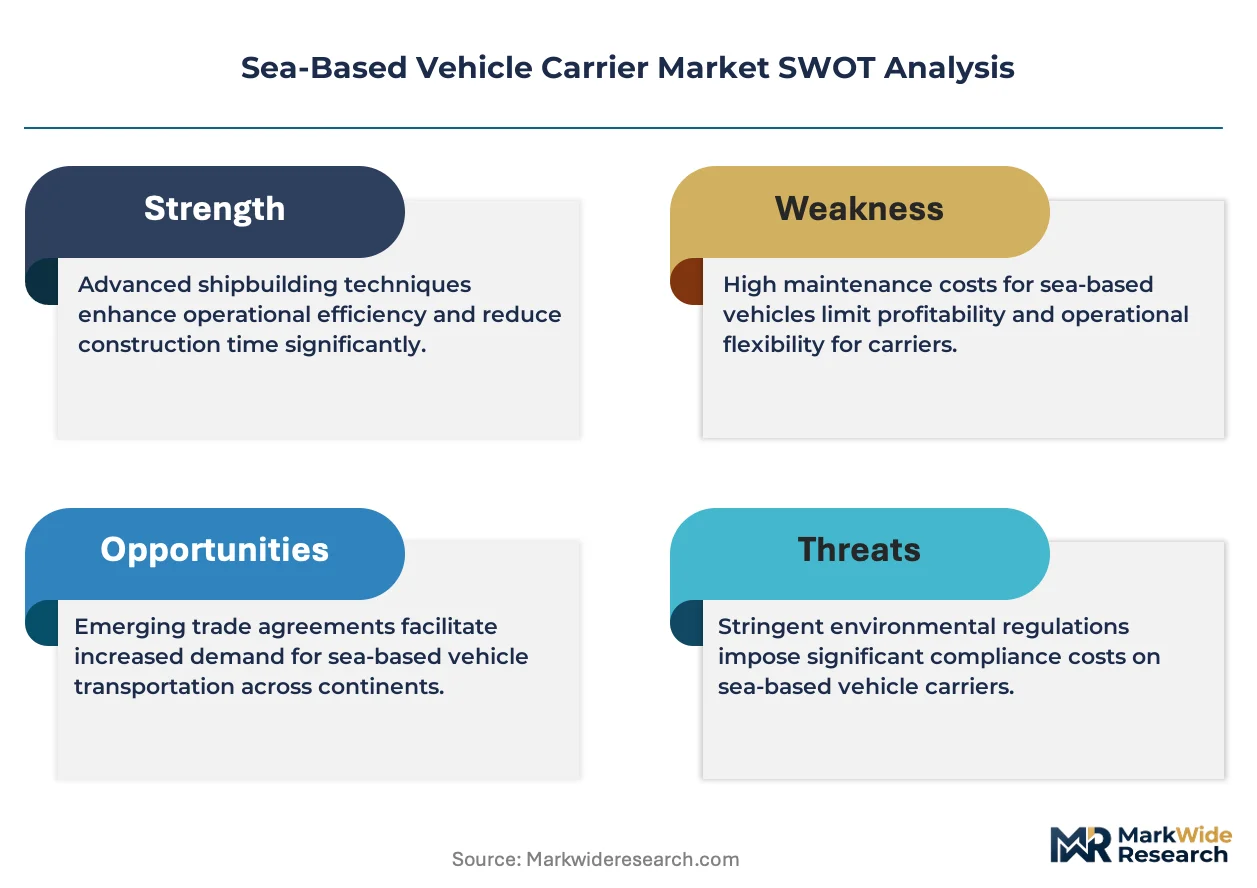
Dual-fuel propulsion retrofits are compressing operating margins for aging fleets while the International Maritime Organization's carbon intensity indicators force accelerated capital deployment into LNG-capable newbuilds.
Growth Catalysts
- EU Emissions Trading System:Carbon pricing mechanisms at European ports are pulling investment into scrubber-equipped and dual-fuel vessels serving trans-Atlantic trade lanes.
- East Asian export manufacturing:Automakers in Japan, South Korea, and China are consolidating production into coastal megaplants that depend on deep-sea roll-on/roll-off capacity.
- Hull air lubrication systems:Mitsubishi's bubble-based friction reduction technology is cutting fuel consumption on long-haul routes by reducing hydrodynamic drag.
Market Restraints
- Steel plate and marine engine cost volatility:Korean and Japanese shipyards face squeezed newbuild margins when nickel and high-tensile steel prices spike.
- Flag state regulatory fragmentation:Japan's Ministry of Land, Infrastructure, Transport and Tourism maintains safety standards exceeding baseline SOLAS, forcing design bifurcation for operators serving Japanese trade lanes.
- Air freight substitution:Premium electric vehicle launches with compressed delivery windows increasingly divert high-value cargo to dedicated cargo aircraft.
Strategic Opportunities
- Southeast Asian port infrastructure gaps:Vietnam and Indonesia lack dedicated roll-on/roll-off terminals, creating first-mover advantage for carriers investing in specialized ramp systems.
- EU Green Deal shipping mandates:The bloc's 2030 sustainable fuel targets are accelerating demand for methanol-ready vessel designs.
- Digital freight matching platforms:Algorithmic spot charter marketplaces are disintermediating traditional broker networks for backhaul optimization.
Industry Challenges
- Marine engineering talent scarcity:Dual-fuel propulsion expertise concentrates in Korean and Norwegian maritime academies, constraining fleet expansion timelines.
- Classification society certification bottlenecks:Lloyd's Register and DNV are extending review periods for novel alternative fuel system approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea-Based Vehicle Carrier Market |
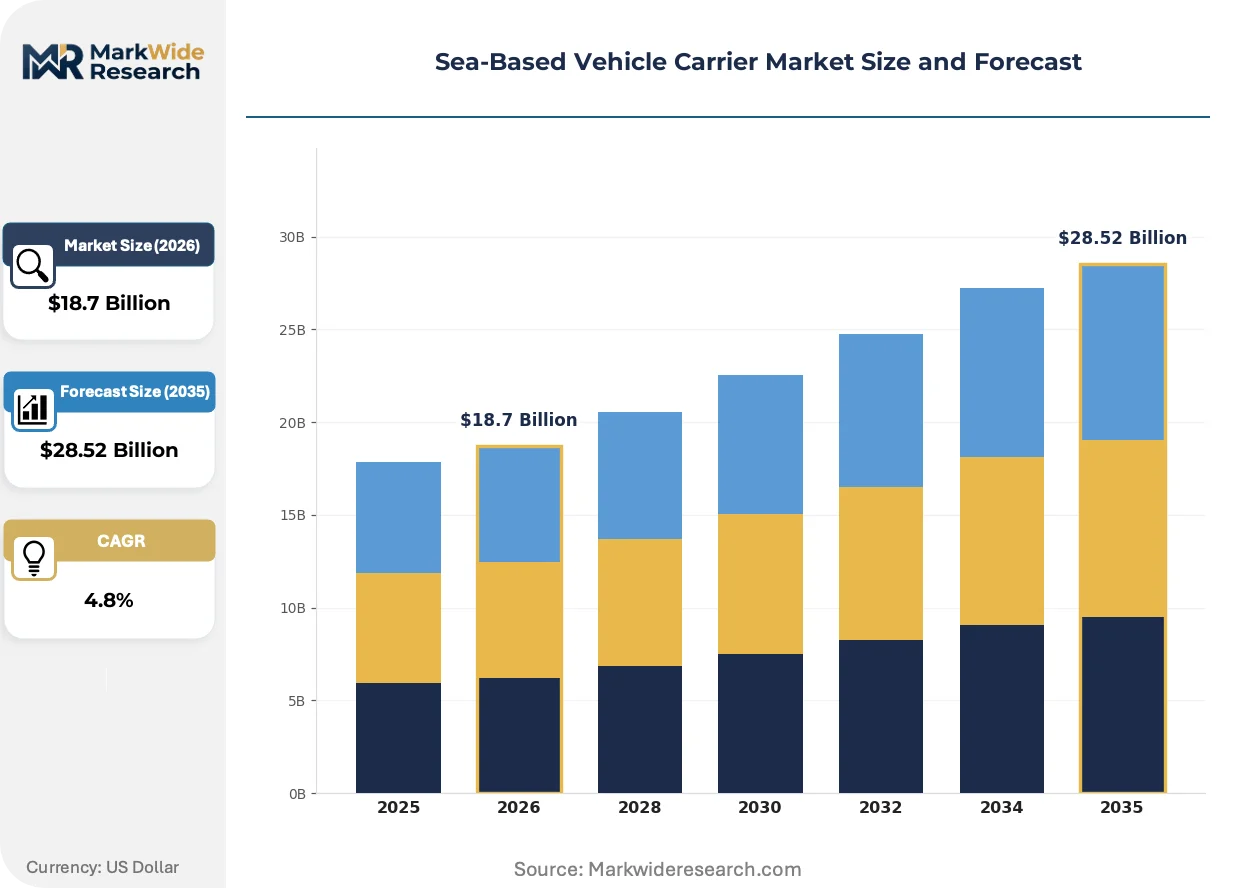
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Vehicles, Commercial Vehicles, Heavy Equipment, Military Vehicles Carrier Type: Roll-on/Roll-off, Lift-on/Lift-off, Semi-Submersible, Container Carrier Service Type: Charter Services, Scheduled Services, Freight Services, On-Demand Services End User: Automakers, Shipping Companies, Government Agencies, Logistics Providers |
| Companies Covered | K Line, Grimaldi Group, A.P. Møller – Mærsk, Hyundai Glovis, CMA CGM, Wallenius Wilhelmsen, Höegh Autoliners, Mitsui O.S.K. Lines, NYK Line, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea-Based Vehicle Carrier Market Evolving Landscape
Propulsion technology trajectories and regulatory compliance architectures are forcing simultaneous fleet renewal and operational model reinvention across the segment.
Wind-assisted propulsion is migrating from experimental retrofits to mainstream newbuild specifications. Wallenius Wilhelmsen and Maersk are installing rotor sails and kite systems on existing tonnage to satisfy carbon intensity reduction mandates. This hardware shift is compressing the payback period for auxiliary wind power from decade-long horizons toward five-year returns on trans-Pacific routes.
The International Maritime Organization's Energy Efficiency Existing Ship Index is tightening operational parameters for vessels calling at European ports. Fleet operators must choose between costly hull retrofits, engine derating, or premature scrapping of vessels under fifteen years of age. Pure car and truck carriers serving Northern European automaker terminals face the steepest compliance cliffs.
Automaker procurement departments are consolidating charter contracts around multi-year vessel dedication agreements. Toyota and Hyundai are replacing fragmented spot market exposure with integrated logistics control spanning factory gate to dealer delivery. This concentration is most visible in the Japan-South Korea-China triangle where assembly plant proximity to deepwater ports enables just-in-sequence loading protocols.
Sea-Based Vehicle Carrier Market Segmentation
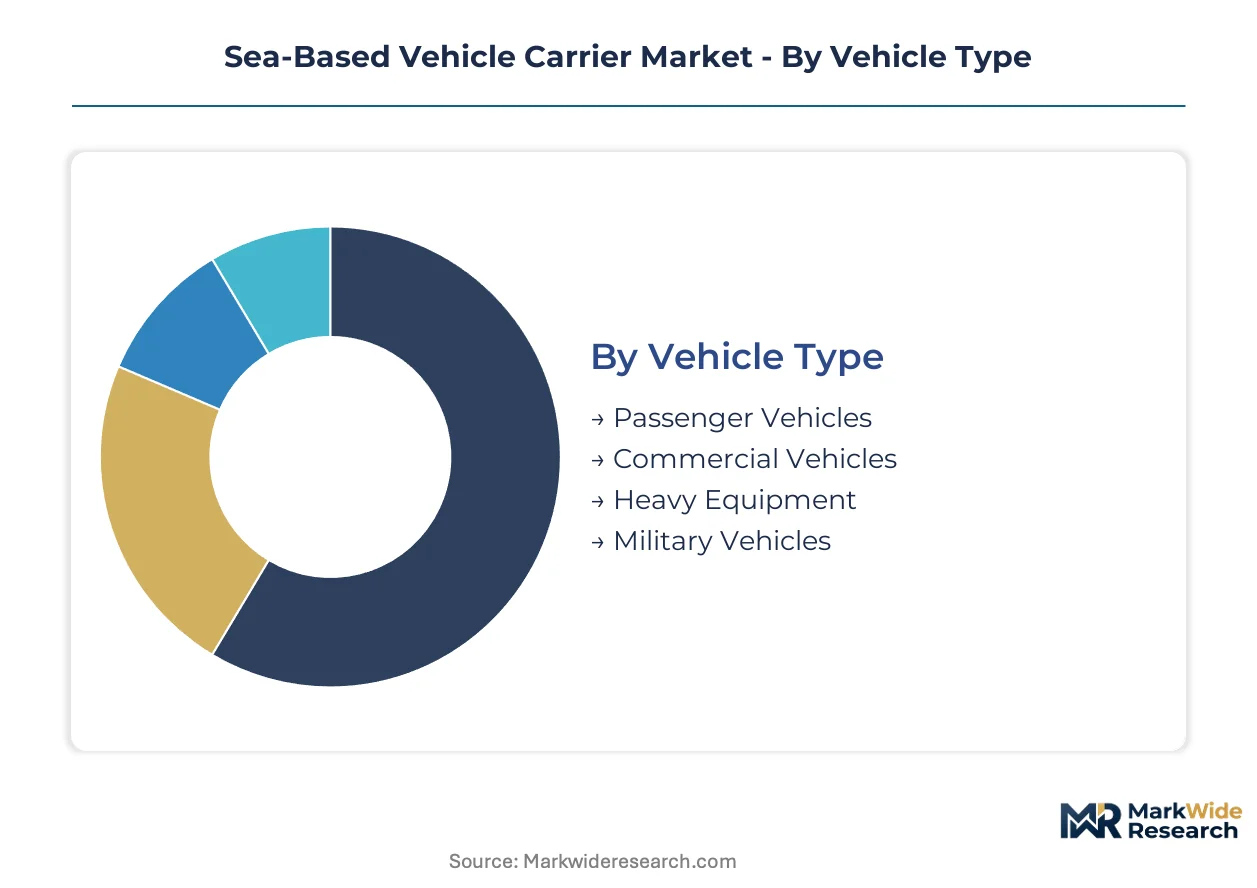
Sea-based vehicle carriers serve heterogeneous cargo profiles requiring deck height adjustability, ramp configurations, and securing systems matched to specific rolling stock dimensions. Segmentation reveals how fleet operators allocate tonnage across vehicle categories, propulsion architectures, contract structures, and customer relationships to optimize vessel utilization and charter yields.
Vehicle Type:
Cost tier differentiation across vehicle cargo classes determines deck configuration investments and port rotation economics for carriers.
- Passenger Vehicles:Sedans, SUVs, and light trucks constitute the volume backbone, requiring minimal deck reinforcement and enabling maximum stowage density through adjustable ramp systems. Demand concentrates in East Asian export corridors serving Japanese, South Korean, and Chinese OEM schedules, where just-in-sequence loading protocols compress turnaround times at Yokohama and Busan terminals.
- Commercial Vehicles:Medium-duty trucks, vans, and buses demand reinforced deck plating and elevated internal clearance heights, reducing nominal vehicle equivalent capacity per voyage. European automaker export programs from Bremerhaven and Zeebrugge drive dedicated charter demand for this segment, particularly during model changeover windows.
- Heavy Equipment:Construction machinery, mining trucks, and agricultural equipment require specialized securing arrangements and often occupy external deck positions. Project cargo forwarding networks coordinate these movements.
- Military Vehicles:Armored personnel carriers and tactical trucks move under government contract with enhanced security protocols and restricted port access.
Passenger vehicles hold installed capacity. Commercial vehicles are rotating up the share rankings.
Carrier Type:
Application-specific hull architectures separate vessels optimized for rolling cargo from those handling static or project loads.
- Roll-on/Roll-off:Multi-deck vessels with internal ramps and hoistable car decks dominate finished vehicle logistics, achieving loading efficiencies that compress port stays to under 24 hours. The Japan-South Korea-China triangle deploys this architecture almost exclusively, where dense automaker terminal networks reward rapid turnaround.
- Lift-on/Lift-off:Crane-dependent vessels serve non-rolling cargo including damaged vehicles and static machinery, occupying niche positions where port infrastructure lacks RoRo ramps. African and South American developing markets generate intermittent demand.
- Semi-Submersible:Heavy-load platforms transport yachts, floating equipment, and project cargo requiring water-level loading. Norwegian and UAE offshore service clusters utilize this capability.
- Container Carrier:Modified boxships with vehicle securing kits handle overflow volume during peak export seasons, though this remains economically inferior to purpose-built tonnage.
Roll-on/Roll-off commands fleet investment. Semi-submersible is climbing the fastest as offshore wind component logistics expand.
Service Type:
Contract duration and volume predictability separate margin pools across the service spectrum.
- Charter Services:Vessel dedication agreements spanning 3-10 years provide revenue visibility for fleet operators while giving automakers scheduling control for new model launches. Toyota and Hyundai procurement departments are consolidating around these structures.
- Scheduled Services:Fixed-route liner operations connecting major production and consumption markets form the volume foundation, with Wallenius Wilhelmsen and NYK Line maintaining dense rotations.
- Freight Services:Slot charter arrangements on scheduled sailings accommodate smaller shippers lacking volume for full vessel commitment.
- On-Demand Services:Spot market access through digital freight platforms is disintermediating traditional broker networks for backhaul optimization.
Scheduled services hold installed capacity. Charter services are rotating up the share rankings.
End User:
Customer type concentration shapes sales force deployment and contract negotiation leverage.
- Automakers:OEM logistics departments directly contract vessel capacity for factory-to-dealer distribution, representing the highest-value customer relationships with multi-year commitment horizons. East Asian manufacturers are expanding their captive fleet involvement.
- Shipping Companies:Vessel-owning operators charter tonnage to logistics integrators, concentrating financial risk with asset-heavy balance sheets while capturing charter rate upside.
- Government Agencies:Defense and development authorities contract for military equipment and infrastructure project cargo, often with sovereign guarantee terms.
- Logistics Providers:Third-party integrators aggregate shipper demand and procure vessel slots, intermediating between fragmented cargo interests and fleet operators.
Automakers hold installed capacity. Logistics providers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across major automotive production basins dictate vessel deployment patterns, with surplus manufacturing regions demanding outbound capacity and consumption markets driving inbound terminal investments. Fleet operators calibrate route density against port infrastructure readiness and regulatory compliance costs.
China
Coastal megaplants in Shanghai and Ningbo ship finished vehicles to European and Southeast Asian markets, straining existing roll-on/roll-off terminal capacity. The Ministry of Transport enforces domestic emission control area standards that exceed International Maritime Organization baselines for vessels calling at Yangtze River Delta ports. Tianjin and Guangzhou are expanding dedicated vehicle handling facilities to reduce vessel turnaround times below eighteen hours.
Japan
Yokohama and Nagoya terminals serve as primary export gateways for Toyota, Honda, and Nissan production schedules, with vessel utilization rates tracking OEM output cycles. The Ministry of Land, Infrastructure, Transport and Tourism mandates safety protocols that exceed SOLAS requirements for weather deck securing systems. Kyushu-based assembly plants are increasing direct vessel loading to bypass Tokyo Bay congestion.
South Korea
Hyundai and Kia export programs from Busan and Pyeongtaek drive dedicated charter demand for new model launch windows. The Korea Maritime and Fisheries Ministry enforces ballast water management standards that accelerate fleet renewal timelines. Ulsan port authorities are constructing additional roll-on/roll-off berths to accommodate projected electric vehicle export growth through 2030.
Germany
Bremerhaven and Zeebrugge serve as European distribution hubs for BMW, Mercedes-Benz, and Volkswagen export programs, with vessel calls peaking during model year transitions. The EU Emissions Trading System imposes carbon costs on vessels at European ports, favoring LNG-capable tonnage in fleet deployment decisions. Hamburg terminal operators are retrofitting shore power connections to comply with at-berth emission regulations.
United States
Port of Baltimore and Port Hueneme handle inbound volume from East Asian manufacturing centers, while Gulf Coast terminals support Mexican assembly plant supply chains. The Environmental Protection Agency enforces vessel emission standards under the Clean Air Act that affect fleet composition decisions. Charleston and Brunswick are expanding vehicle processing facilities to capture Southeast automotive manufacturing growth.
Sea-Based Vehicle Carrier Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in propulsion and cargo handling subsystems. The market structure concentrates around vessel-owning operators with captive automotive relationships and integrated logistics capabilities. Three archetypes dominate: asset-heavy fleet operators with multi-decade OEM contracts, logistics integrators controlling factory-to-dealer distribution, and specialized charter providers serving project cargo niches. Competitive moves center on dual-fuel newbuild programs and terminal infrastructure partnerships that lock in berth priority.
Among Nordic and East Asian fleet operators, Höegh Autoliners, Wallenius Wilhelmsen, and NYK Line occupy positions that exemplify the integrated logistics archetype, combining vessel ownership with terminal operations and inland distribution control. These operators represent the capital-intensive tier where long-term charter backing enables sustained fleet renewal programs. Hyundai Glovis anchors the captive logistics segment, while Grimaldi Group sits within the European project cargo specialist tier. K Line and Mitsui O.S.K. Lines exemplify Japanese trading house-affiliated operators with concentrated exposure to domestic OEM export schedules.
| Leading Market Players |
|---|
| K Line |
| Grimaldi Group |
| A.P. Møller – Mærsk |
| Hyundai Glovis |
| CMA CGM |
| Wallenius Wilhelmsen |
| Höegh Autoliners |
| Mitsui O.S.K. Lines |
| NYK Line |
| Others |
Value Network & Pricing Analysis
Overcapacity in the Korean newbuild orderbook is compressing charter rates across the Asia-Europe trade corridor, forcing vessel operators to accept thinner margins while Korean and Japanese shipyards compete for limited LNG-capable engine slots. This utilization squeeze propagates backward into steel plate procurement negotiations and forward into automaker contract structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures spanning three-to-ten year charter dedications. Price differentiation rests on vessel age tier and dual-fuel certification status, with LNG-ready tonnage commanding premium positioning over conventional bunkering fleets. Cost compression in the aging fleet segment is intensifying because IMO carbon intensity regulations accelerate scrapping timelines for vessels under fifteen years. Spot charter buyers exhibit highest price sensitivity, while Japanese and South Korean OEM procurement departments with captive volume commitments demonstrate lowest sensitivity due to just-in-sequence loading requirements.
Supply Chain Analysis
Extended payment terms from Korean shipyards now stretch to twenty-four months for dual-fuel propulsion packages, straining operator cash conversion cycles. Geographic supply concentrates in South Korea, Japan, and China, where Hyundai Heavy Industries, Mitsubishi Heavy Industries, and China State Shipbuilding Corporation control LNG engine fabrication. Raw material dependencies center on high-tensile steel plate, nickel-alloy fuel containment systems, and specialized marine engine crankshafts. Single-source vulnerability in Korean engine supply creates structural risk for fleet renewal timelines. Distribution runs through terminal operators at Yokohama, Busan, and Bremerhaven who coordinate berth scheduling with automaker export windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-fuel propulsion mandates are disrupting fleet economics faster than replacement cycles can absorb, compressing returns for conventional tonnage while rewarding early LNG-capable adopters with charter rate premiums and regulatory compliance runway.
For Market Incumbents: Harden terminal infrastructure control at Yokohama and Bremerhaven to lock in berth priority against emerging logistics integrators. Accelerate backward integration into LNG bunkering infrastructure to capture fuel margin pools and defend against fuel supplier concentration. Prioritize sale-and-leaseback structures to preserve balance sheet capacity for dual-fuel newbuild programs while automakers consolidate charter contracts.
For New Entrants and Emerging Players: Southeast Asian port infrastructure gaps in Vietnam and Indonesia represent the most penetrable entry point for specialized ramp system investments ahead of automaker production relocation. Digital freight matching platforms for backhaul optimization offer lower capital intensity entry compared to vessel ownership. Partner with Chinese electric vehicle exporters seeking dedicated capacity outside incumbent East Asian carrier networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operators with multi-decade Japanese and South Korean OEM charter backing, providing cash flow visibility across vessel replacement cycles. Target acquisition archetypes include mid-tier operators with undervalued LNG retrofit pipelines and terminal assets in constrained port markets. Monitor EU Emissions Trading System carbon price trajectories as the signal indicating acceleration or delay in fleet renewal demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Newbuild Program | LNG-capable vessels secure compliance runway under IMO carbon intensity regulations and EU ETS. |
| Terminal Infrastructure Partnership | Berth priority agreements at Yokohama and Bremerhaven lock in automaker loading windows. |
| Integrated Logistics Control | Factory-gate-to-dealer-delivery coverage captures margin pools beyond pure vessel charter. |
| Sale-and-Leaseback Financing | Long-term charter backing enables fleet renewal without balance sheet strain. |
| Wind-Assisted Propulsion Retrofit | Rotor sail installations on existing tonnage compress carbon intensity payback periods. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, automaker logistics procurement managers, shipyard commercial officers, and maritime classification society surveyors; and secondary validation through Lloyd's Register vessel databases, IMO greenhouse gas studies, port authority throughput statistics, and customs vehicle export records. Bottom-up vessel deployment modeling triangulated against top-down trade flow estimates.
Forecast inputs incorporated vessel orderbook analysis, automaker production schedule disclosures, and regulatory compliance timeline assumptions across the projection horizon. Segmentation dimensions modeled include vehicle cargo class, propulsion architecture, contract structure duration, and regional trade corridor density. CAGRs derived from capacity deployment trajectories weighted against charter rate elasticity and newbuild delivery schedules.
Macroeconomic conditions sit as an overlay; deviation in steel plate pricing, marine engine availability, or East Asian export manufacturing volumes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and OEM production consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Global Catamaran Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Marine Propulsion Engine Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Marine Fuel Injection System Market