
 Argentina Automotive Carbon Fiber Composites Market | 2026-2036
Argentina Automotive Carbon Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Automotive Carbon Fiber Composites Market Outlook
Argentina is reconfiguring its position within South American automotive supply chains through targeted composite material investments. Hexcel Corporation leverages its prepreg technology leadership to serve regional OEM programs requiring weight reduction. Toray Industries Inc anchors carbon fiber precursor supply through established distribution partnerships. SGL Carbon SE specializes in automotive-grade chopped fiber and thermoplastic solutions for interior applications.
Automotive carbon fiber composites consist of polyacrylonitrile-derived or pitch-based carbon fibers embedded in thermoset or thermoplastic matrices, achieving tensile strengths exceeding 3,500 MPa while reducing component mass by 50-70% versus steel equivalents. These materials primarily enable fuel efficiency gains and crashworthiness improvements in passenger and commercial vehicles. Prepreg formats dominate current value capture due to their processing consistency in autoclave and out-of-autoclave manufacturing, while reinforced plastics represent the fastest-growing category as thermoplastic compression molding shortens cycle times for high-volume platforms. Structural Parts applications concentrate the deepest margin pools, as load-bearing components require the most stringent qualification protocols and command premium pricing over decorative Body Panels.
Argentina's national automotive regulator enforces Mercosur harmonized safety standards that increasingly reference material-specific crash performance, while the Secretariat of Industry and Productive Development administers local content requirements affecting composite sourcing decisions. The INTI national standards body participates in ISO/TC61 plastics standardization, shaping test method acceptance for regional suppliers. Stakeholders must monitor evolving Mercosur-EU trade agreement provisions, as European automotive carbon fiber technical regulations could cascade into Argentine certification requirements through mutual recognition mechanisms.
Market Dynamics
Argentina's alignment with Mercosur-EU trade negotiations is forcing domestic OEMs to pre-certify carbon fiber components against European crashworthiness standards before formal mutual recognition takes effect, compressing supplier qualification timelines.
Growth Catalysts
- Fuel efficiency mandates:Mercosur's progressively tightening CO2 emission thresholds for passenger vehicles push manufacturers toward mass reduction technologies. Carbon fiber structural members deliver the highest strength-to-weight ratios available.
- Buenos Aires supplier clustering:Concentrated tier-1 engineering capabilities in the province enable just-in-time preform delivery to assembly plants, reducing logistics costs for composite-intensive vehicle programs.
- Thermoplastic processing advances:Out-of-autoclave compression molding cycles below 90 seconds now support medium-volume production economics, expanding addressable platform volumes beyond supercar niche applications.
Market Restraints
- Acrylonitrile import dependency:Argentina possesses no domestic polyacrylonitrile precursor production, exposing converters to petrochemical feedstock price volatility and currency fluctuation risk.
- Autoclave capacity scarcity:Thermoset curing infrastructure concentrates among three Buenos Aires-based processors, creating bottleneck risk for qualification-intensive structural programs.
- Steel-hybrid competition:Advanced high-strength steel grades achieve 30% mass reduction at 15-20% of carbon fiber cost, capturing mid-market platform engineering decisions.
Strategic Opportunities
- Córdoba industrial corridor:Underdeveloped composite conversion capacity in Argentina's second-largest automotive manufacturing zone offers greenfield site advantages for thermoplastic stamping operations.
- End-of-life recycling mandates:Anticipated EU-derived extended producer responsibility frameworks will reward suppliers with established carbon fiber reclamation processes, creating first-mover certification benefits.
- Battery enclosure applications:Electric vehicle platform proliferation creates demand for crash-protective, thermally insulating composite housings that steel and aluminum cannot match.
Industry Challenges
- Autoclave technician scarcity:Argentine technical institutes graduate fewer than 40 composite process engineers annually, forcing manufacturers to poach talent from aerospace or import Brazilian specialists.
- Homologation timeline compression:Mercosur's accelerated revision cycle for material-specific crash test protocols forces suppliers to maintain parallel certification tracks for multiple standard versions.
- Recycling infrastructure gaps:No commercial pyrolysis or solvolysis facilities operate within Argentina, obliging manufacturers to export manufacturing scrap to European processors at elevated cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Automotive Carbon Fiber Composites Market |
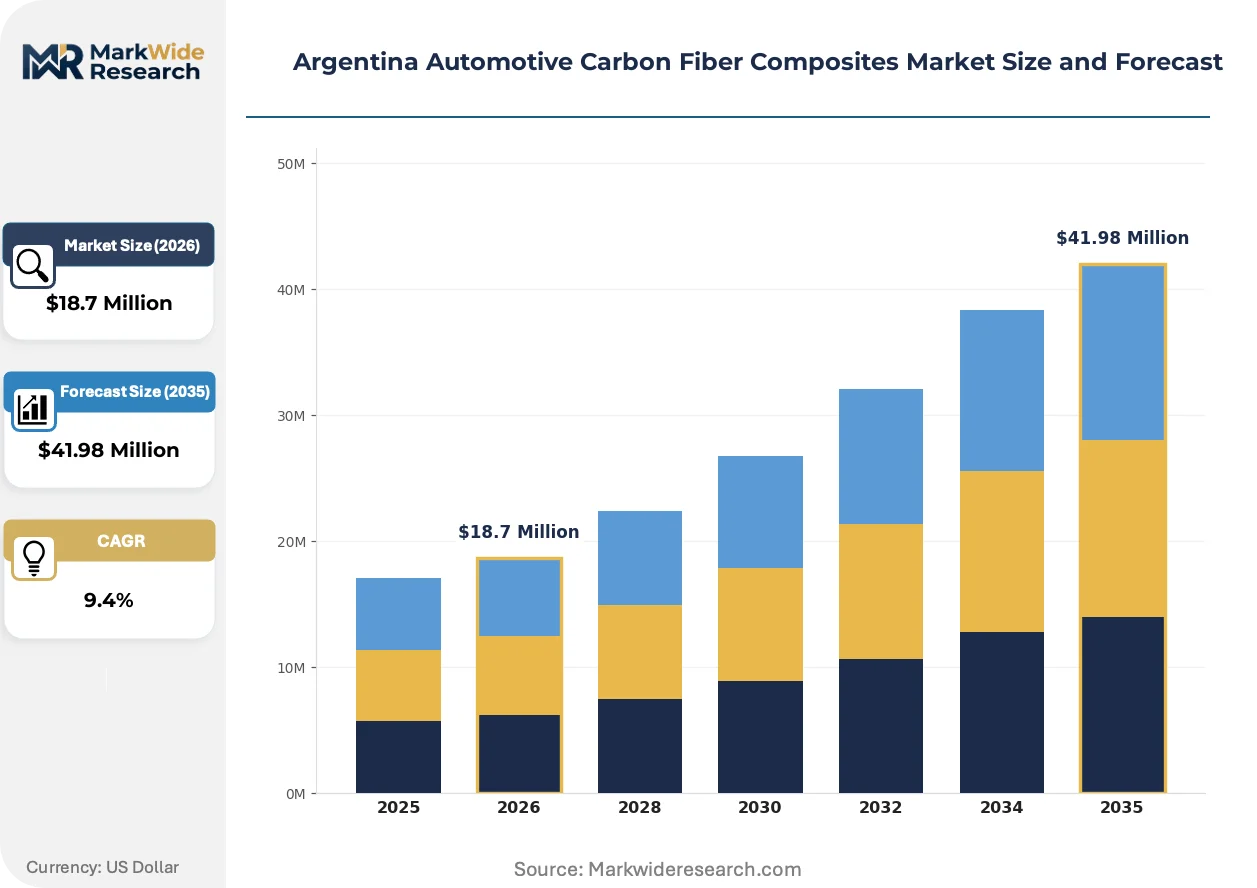
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepreg, Foam, Laminates, Reinforced Plastics Application: Interior Components, Structural Parts, Body Panels, Safety Features End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Raw Material Production, Composite Fabrication, Assembly, Quality Control |
| Companies Covered | Hexcel Corporation, Mitsubishi Chemical Carbon Fiber and Composites Inc, SGL Carbon SE, Teijin Ltd, Toray Industries Inc, A&P Technology Inc, Solvay S.A., DowAksa USA LLC, Toho Tenex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Automotive Carbon Fiber Composites Market Strategic Shifts
Thermoplastic matrix systems are displacing thermosets across structural applications, while regulatory pre-alignment with European standards reshapes certification investments. Procurement behaviors increasingly favor suppliers with integrated recycling capabilities.
Hybrid thermoplastic-thermoset prepregs is hybridizing automotive manufacturing by combining the drapability of epoxy systems with the weldability of PEEK matrices. Tier-1 suppliers serving premium SUV platforms in Buenos Aires province are trialing these materials for A-pillar reinforcements. This convergence is compressing the traditional process-material tradeoff that previously forced engineers to choose between crash performance and cycle time.
Mercosur's adoption of UN ECE R94 and R95 frontal and side-impact protocols is mandating specific energy absorption curves that carbon fiber composite designs satisfy more readily than metal alternatives. The Secretariat of Industry and Productive Development references these standards in local content credit calculations. Structural parts suppliers are responding by front-loading simulation investments to pre-validate designs against both Mercosur and EU homologation requirements.
Automakers are consolidating composite procurement under single-source framework agreements that bundle material supply, part fabrication, and end-of-life takeback obligations. This displaces the historical model of discrete transactions between resin distributors, preform converters, and Tier-1 stampers. The integrated sourcing model is most visible in premium electric vehicle programs, where battery protection requirements demand material-traceable crash performance guarantees.
Argentina Automotive Carbon Fiber Composites Market Segmentation
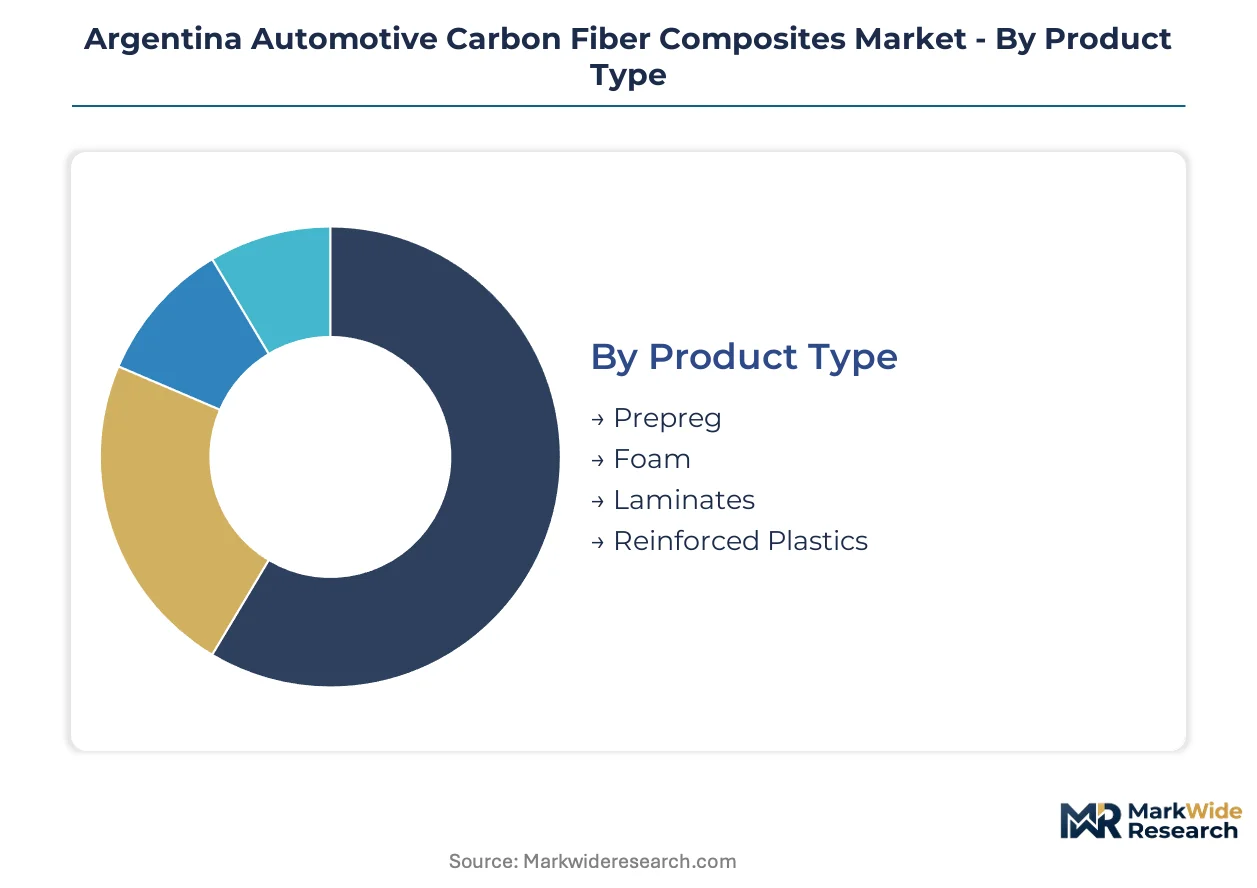
Carbon fiber composite procurement in Argentina stratifies sharply across material formats and manufacturing stages, with each segment demanding distinct qualification protocols and capital intensity. Understanding these divides clarifies where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
Cost tier determines accessibility to high-performance applications, with prepreg formats commanding premium positioning while reinforced plastics open mid-market penetration.
- Prepreg:Pre-impregnated carbon fiber sheets with thermoset resin matrices deliver consistent fiber volume fractions above 60%. Buenos Aires-based autoclave processors dominate demand for structural members in premium passenger vehicles, constrained by curing cycle durations exceeding three hours.
- Reinforced Plastics:Thermoplastic compounds with chopped or continuous fiber reinforcement enable sub-90-second compression molding cycles. Córdoba industrial corridor developers target these materials for battery enclosure volumes where throughput economics override maximum mechanical performance.
- Foam:Core materials for sandwich panel construction reduce component mass while maintaining bending stiffness. Applications concentrate in hood and decklid inner structures where local buckling resistance matters.
- Laminates:Multi-layer cured sheets supplied for secondary bonding operations or decorative trim applications. Tier-1 interior specialists in Buenos Aires province source these for dashboard carrier substrates.
Prepreg commands the established base. The steepest expansion runs through reinforced plastics.
Application:
Functional criticality separates segments, with crash-protective structures requiring exhaustive homologation against decorative surface elements.
- Structural Parts:Load-bearing components including A-pillars, roof bows, and floor pans achieve tensile strengths exceeding 3,500 MPa. Mercosur-EU pre-alignment forces simultaneous certification against UN ECE R94 and R95 protocols, compressing supplier development timelines.
- Interior Components:Trim panels, seat shells, and center console structures prioritize surface finish and acoustic damping over ultimate strength. Thermoplastic solutions from SGL Carbon SE anchor supply for these lower-stress applications.
- Body Panels:Exterior closures including hoods, fenders, and roofs balance aesthetics with dent resistance. Paint shop compatibility requirements limit matrix chemistry options for this segment.
- Safety Features:Crash absorbers, bumper beams, and side-impact reinforcements must demonstrate controlled energy dissipation curves. INTI national standards body participation in ISO/TC61 shapes test method acceptance for these critical elements.
Structural parts concentrate the deepest margin pools. Interior components gain share fastest as thermoplastic processing matures.
End User:
Supply chain position dictates technical capability requirements, with direct OEM relationships demanding integrated design services absent from aftermarket channels.
- OEMs:Vehicle manufacturers specifying material-traceable crash performance guarantees for electric vehicle battery protection programs. Integrated sourcing frameworks now bundle material supply with end-of-life takeback obligations.
- Tier-1 Suppliers:Engineering firms managing composite conversion and assembly for just-in-time delivery to Buenos Aires assembly plants. These stakeholders absorb autoclave capacity scarcity risks.
- Vehicle Assemblers:Final integration facilities focusing on bonding and fastening operations rather than primary composite fabrication.
- Aftermarket Providers:Specialty shops serving performance vehicle customization with lower qualification burdens than original equipment channels.
OEMs anchor premium program development. Tier-1 suppliers capture the broadest volume exposure.
Manufacturing Stage:
Value capture depth varies with process complexity, with fabrication stages retaining margin lost to commoditized raw material distribution.
- Composite Fabrication:Preform layup, molding, and curing operations where process engineering expertise differentiates outcomes. Buenos Aires processor clustering reflects this stage's capital intensity.
- Raw Material Production:Polyacrylonitrile precursor and carbon fiber spinning operations entirely absent from Argentina, exposing converters to import dependency.
- Assembly:Adhesive bonding, mechanical fastening, and subsystem integration requiring precision fixturing for dimensional control.
- Quality Control:Non-destructive testing and dimensional verification protocols mandated by Mercosur harmonized safety standards.
Composite fabrication commands the established base. Quality control investments are climbing the fastest as regulatory pre-certification requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Secretariat of Industry and Productive Development shapes Argentina's automotive carbon fiber trajectory through Mercosur alignment mandates that cascade into provincial industrial policy.
Buenos Aires Province
Autoclave processing clusters concentrate in Greater Buenos Aires, where tier-1 suppliers serve premium vehicle assembly plants with just-in-time preform delivery. The province absorbs 70% of national composite fabrication capacity. Industrial parks in Pilar and Campana host curing infrastructure for structural automotive programs.
Córdoba
Argentina's second automotive manufacturing zone remains underdeveloped in composite conversion, creating greenfield opportunities for thermoplastic stamping operations. The Córdoba Industrial Corridor hosts powertrain and stamping facilities that could anchor downstream composite integration. Provincial investment promotion agencies target battery enclosure manufacturing for electric vehicle platforms.
Santa Fe
Rosario's port infrastructure positions the province for acrylonitrile precursor import logistics, though no carbon fiber spinning operates domestically. The regional automotive supplier base focuses on metal stamping and powertrain components rather than advanced composites. Freight rail connections to Buenos Aires assembly plants reduce inbound material transport costs.
Mendoza
Andean logistics corridors through Mendoza connect Argentine converters to Chilean Pacific port alternatives for European carbon fiber precursor supply. The province's industrial parks lack automotive tier-1 presence but offer tax stabilization regimes for capital-intensive manufacturing. Mendoza's renewable energy profile appeals to suppliers with carbon-neutral production commitments.
Argentina Automotive Carbon Fiber Composites Market Competitive Environment
Prepreg technology leaders and thermoplastic specialists split the market along processing-method lines, with concentration highest in autoclave-dependent structural applications. Three strategic archetypes dominate: multinational material suppliers with precursor-to-prepreg integration, regional distribution partners with technical service capabilities, and tier-1 fabricators with OEM direct relationships. Competitive moves center on qualification timeline compression and recycling capability pre-positioning ahead of extended producer responsibility frameworks.
Among multinational material suppliers, Hexcel Corporation, Toray Industries Inc, and SGL Carbon SE occupy positions reflecting distinct technology anchoring. Hexcel exemplifies prepreg technology leadership serving regional OEM weight reduction programs. Toray represents carbon fiber precursor supply security through established distribution partnerships. SGL Carbon SE sits within the thermoplastic solutions tier, specializing in automotive-grade chopped fiber for interior applications. These three archetypes illustrate how global material science capabilities map onto Argentina's Mercosur-aligned certification requirements.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Mitsubishi Chemical Carbon Fiber and Composites Inc |
| SGL Carbon SE |
| Teijin Ltd |
| Toray Industries Inc |
| A&P Technology Inc |
| Solvay S.A. |
| DowAksa USA LLC |
| Toho Tenex |
| Others |
Value Chain & Pricing Dynamics
Rosario port freight corridors govern acrylonitrile import economics for Argentine converters, concentrating supply-side leverage among Buenos Aires-based autoclave processors while forcing downstream three-tier pricing stratification across premium structural programs, standard interior applications, and economy-grade reinforced plastics.
Pricing Analysis
Buenos Aires province commands 15-20% premiums over Córdoba for identical prepreg specifications due to just-in-time logistics integration. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in reinforced plastics is intensifying because thermoplastic cycle time advantages attract mid-market platform engineering. Aftermarket providers exhibit highest price sensitivity; OEM direct programs tolerate premium positioning for material-traceable crash guarantees.
Supply Chain Analysis
Polyacrylonitrile precursor production centers on Japan, the United States, and China, leaving Argentine converters exposed to petrochemical feedstock volatility. Carbon fiber tow, thermoset epoxy resins, and thermoplastic PEEK matrices constitute critical input dependencies. Single-source vulnerability runs through the three Buenos Aires autoclave processors controlling structural program capacity. Distribution runs through tier-1 engineering partners with OEM direct relationships rather than commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's automotive carbon fiber composites sector represents early-cycle expansion, with thermoplastic processing advances opening mid-market penetration beyond historical supercar niches.
For Market Incumbents: Entrench autoclave capacity advantages in Buenos Aires through technician apprenticeship pipelines that counter Brazilian specialist poaching. Secure backward integration into acrylonitrile precursor supply via long-term offtake agreements with Japanese or US suppliers. Pre-position recycling capabilities ahead of EU-derived extended producer responsibility frameworks to capture first-mover certification benefits. For New Entrants and Emerging Players: Build out thermoplastic stamping operations in the Córdoba industrial corridor, targeting battery enclosure volumes where throughput economics override maximum mechanical performance. The penetrable white space sits in medium-volume electric vehicle platforms requiring sub-90-second cycle times. A go-to-market angle through provincial investment promotion agencies offers tax stabilization regimes unavailable in saturated Buenos Aires. For Investors and Strategic Acquirers: Tier-1 fabricators with OEM direct relationships and established Mercosur-EU dual certification tracks represent the priority acquisition archetype. Long-term viability hinges on recycling infrastructure control as end-of-life mandates cascade through Mercosur-EU trade alignment. The signal to watch is accelerated homologation timeline compression forcing parallel certification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Processing Scale-Up | Sub-90-second compression molding cycles unlock medium-volume platform economics beyond supercar applications. |
| Dual Certification Investment | Pre-alignment with UN ECE R94 and R95 protocols secures Mercosur-EU mutual recognition advantages. |
| Recycling Capability Integration | Pyrolysis or solvolysis partnerships with European processors anticipate extended producer responsibility frameworks. |
| Technician Pipeline Development | Argentine technical institute partnerships counter autoclave engineer scarcity threatening capacity expansion. |
| Córdoba Greenfield Expansion | Provincial tax stabilization regimes reduce capital intensity for thermoplastic stamping operations. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; and secondary validation through customs trade records, SEC filings of multinational material suppliers, vehicle production databases, and INTI national standards documentation. Bottom-up segment modeling triangulated against top-down Mercosur automotive production forecasts.
Forecast inputs considered vehicle class stratification, propulsion architecture differentiation, and content-per-vehicle trajectories across the analysis window. CAGRs derived from regression analysis of historical adoption curves in comparable emerging markets, adjusted for Argentina-specific currency volatility and import dependency factors. Thermoplastic processing maturity curves and Mercosur-EU regulatory pre-alignment timelines shaped scenario weightings.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by multinational material suppliers or accelerated EU mutual recognition implementation would shift outcomes. Cross-checking against IHS Markit vehicle registration data and Brazilian carbon fiber import trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Suction Road Sweeper Market