
 Industrial Brake Caliper Market | 2026-2036
Industrial Brake Caliper Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Brake Caliper Market Foresight
The gap between premium forged-aluminum calipers and commodity cast-iron units is restructuring supplier economics across the industrial brake caliper landscape. Brembo SpA leverages its motorsport heritage to dominate high-performance electromechanical segments for automated material handling. Knorr Bremse AG anchors European rail and heavy-equipment contracts through captive foundry capacity and in-house friction-material production. Robert Bosch GmbH competes on sensor-integrated hydraulic systems that feed real-time wear data into plant maintenance software.
An industrial brake caliper is a clamping mechanism that applies friction force to a rotor or drum surface through hydraulic, pneumatic, or electromechanical actuation, typically generating clamping loads from 50 kN to over 500 kN in heavy-duty configurations. Its primary purpose is to decelerate or hold rotating machinery in manufacturing lines, cranes, mining trucks, and automated storage systems where failure modes must meet ISO 12100 machinery-safety thresholds. Disc calipers command the largest revenue pool due to thermal dissipation advantages in continuous-cycle operations, yet electromechanical technology is displacing legacy pneumatic systems in clean-room and food-processing warehouses where oil-free braking is mandatory. Carbon composite materials remain confined to aerospace-tier price points, leaving cast iron and aluminum to split the volume base across construction equipment and general manufacturing end users.
The EPA enforces particulate and friction-material content rules that shape North American supplier qualification, while REACH and RoHS constrain heavy-metal formulations in European-sourced brake pads and caliper coatings. China's GB standards and SAMR enforcement on machinery-safety certification create divergent testing burdens for exporters targeting domestic OEMs. Buyers must weigh regional compliance roadmaps against platform-standardization goals when selecting caliper architectures for multinational deployments.
Market Dynamics
Electromechanical actuation is absorbing share from legacy pneumatic systems as manufacturing plants automate material handling and warehouse operations. The EU F-Gas Regulation and EPA particulate standards are compressing design cycles and forcing material substitutions across supplier portfolios.
Growth Catalysts
- EU Green Deal decarbonization mandates:OEMs in Germany and France must retrofit existing machinery with energy-efficient braking systems, creating replacement demand for electromechanical calipers in automotive component plants.
- Automated storage and retrieval systems:E-commerce fulfillment centers in the United States are specifying oil-free electromechanical brakes to eliminate contamination risks in food-grade and pharmaceutical warehouses.
- GB standards machinery-safety certification:Domestic Chinese OEMs are upgrading brake systems to meet SAMR enforcement thresholds, driving procurement of ISO 12100-compliant calipers for construction equipment.
Market Restraints
- Aluminum ingot price volatility:Forged-aluminum caliper production faces margin compression when LME aluminum spikes, disadvantaging premium suppliers against cast-iron commodity producers.
- Foundry capacity concentration in Germany and China:Captive foundry operations at tier-one suppliers limit second-tier access to high-integrity casting capacity for heavy-duty configurations.
- REACH heavy-metal restrictions:Copper and antimony content limits in friction materials force reformulation of brake pads, extending qualification timelines for European market entry.
Strategic Opportunities
- India manufacturing automation:PLI scheme incentives for semiconductor and electronics manufacturing are creating first-mover openings for electromechanical brake suppliers in clean-room material handling.
- Sensor-integrated predictive maintenance:Convergence of IoT connectivity with electromechanical actuation enables real-time wear monitoring, unlocking aftermarket service revenue streams.
- Carbon-neutral steel procurement:Buyers in Sweden and Denmark are specifying calipers with certified low-carbon steel housings, creating premium positioning for suppliers with Scope 3 traceability.
Industry Challenges
- Electromechanical systems integration:Plant engineers lack expertise in servo-drive compatibility, extending commissioning timelines and inflating total cost of ownership calculations.
- Dual certification burdens:Exporters must simultaneously satisfy EPA friction-material content rules and REACH substance restrictions, duplicating testing expenditure for North American-European product lines.
- Foundry emissions compliance:Captive casting operations face MEE enforcement in China and state-level air-quality regulations in California, requiring capital deployment toward electric melting and fume capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Brake Caliper Market |
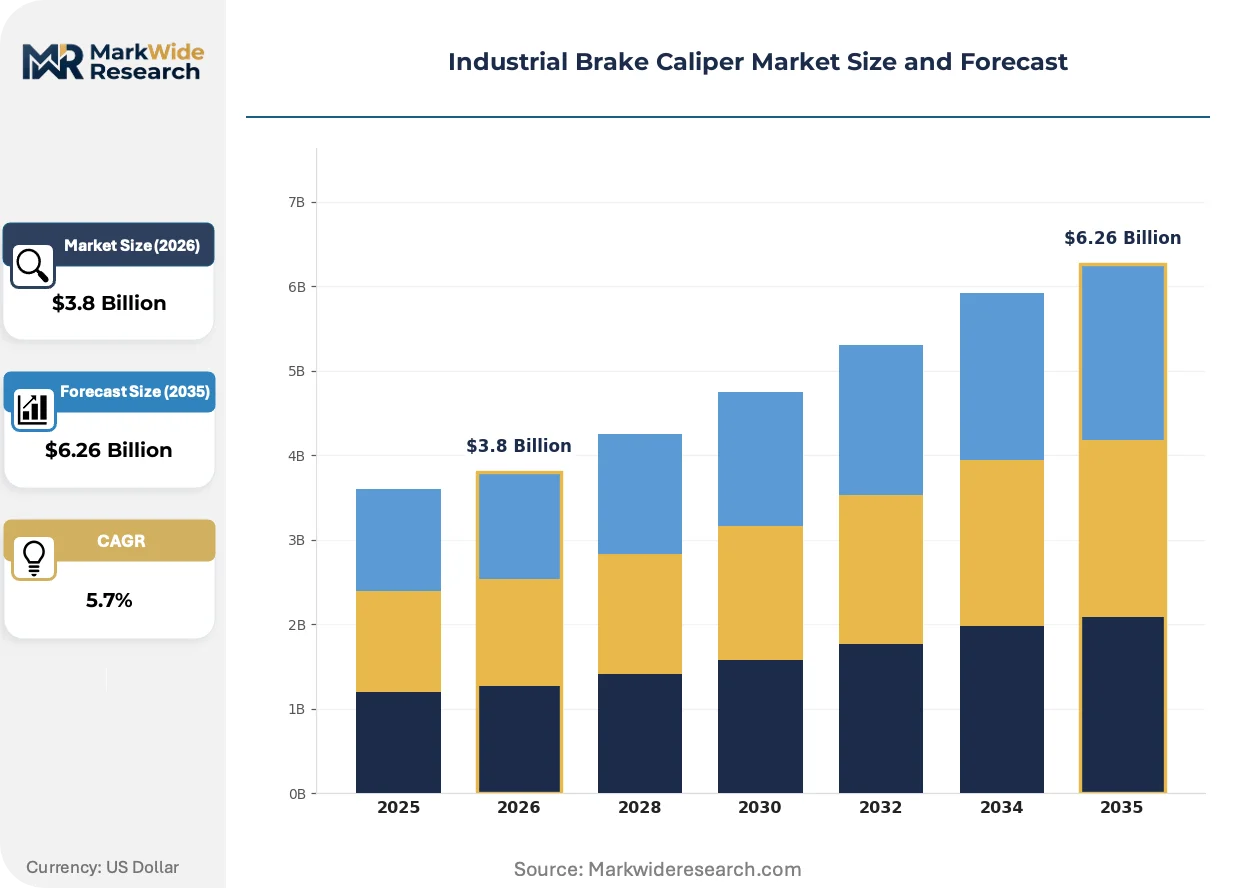
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Calipers, Drum Calipers, Hydraulic Calipers, Pneumatic Calipers End User: Manufacturing Plants, Warehouses, Construction Equipment, Automotive Material: Aluminum, Cast Iron, Carbon Composite, Stainless Steel Technology: Electromechanical, Hydraulic, Pneumatic, Hybrid |
| Companies Covered | Brembo SpA, Knorr Bremse AG, Robert Bosch GmbH, HL Mando Corporation, Aisin Seiki Co., Ltd., Continental AG, Akebono Brake Industry Co., Ltd., Haldex AB, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Brake Caliper Market Shifts & Advancements
Brake caliper architecture is bifurcating between commodity hydraulic units for construction equipment and intelligent electromechanical systems for automated manufacturing. Material selection, sensor integration, and regulatory compliance are converging to reshape supplier technical roadmaps.
Electromechanical calipers with integrated position feedback are absorbing specification share in clean-room logistics and food-processing automation. Pharmaceutical distributors in Switzerland and the Netherlands are mandating oil-free braking to eliminate contamination pathways. This technology is absorbing the service-interval advantages previously held by pneumatic systems, compressing maintenance budgets and extending replacement cycles.
REACH Annex XVII restrictions on heavy metals are forcing friction-material suppliers to eliminate copper and antimony from brake pad formulations. The industrial consequence is extended dynamometer testing to validate wear performance under thermal cycling. Rail and heavy-equipment segments in Germany face the steepest reformulation burden, with KBA type-approval timelines extending by four to six months for modified material stacks.
Buyers are consolidating supplier relationships around platform-standardized caliper families to simplify multinational spare-parts logistics. Automotive tier-one suppliers in Mexico and Thailand are pushing this consolidation, replacing site-specific brake specifications with global product codes. This pattern is most visible in conveyor and automated guided vehicle applications, where maintenance teams prioritize interchangeability over localized customization.
Industrial Brake Caliper Market Segmentation
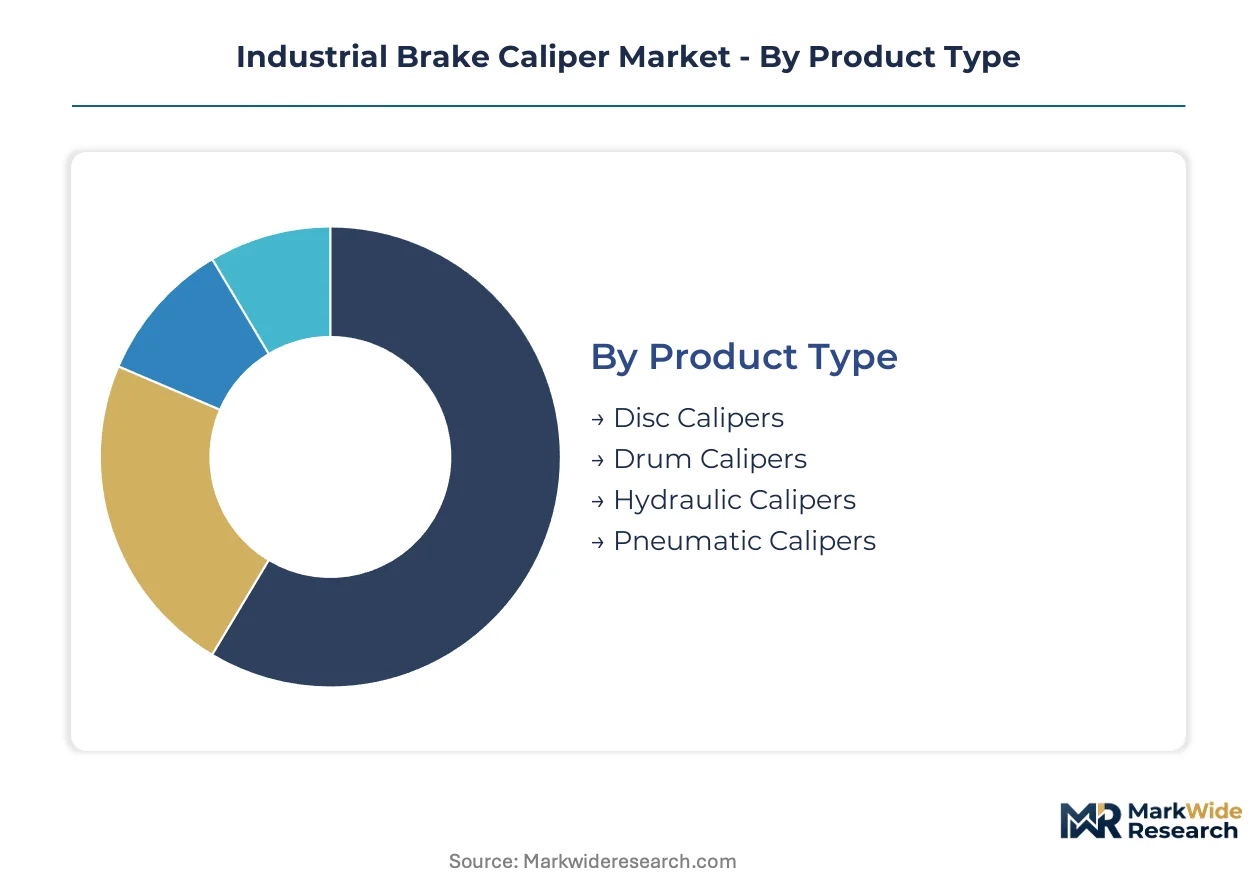
Industrial brake caliper procurement splits sharply between price-sensitive construction equipment buyers and precision-driven automation engineers. Segmentation reveals where margin pools concentrate and which technology transitions are absorbing capital allocation across manufacturing end uses.
Product Type:
Volume concentration favors thermal-dissipation designs in continuous-cycle operations, while premium positioning attaches to actuation-method differentiation.
- Disc Calipers:These units employ opposed piston configurations clamping ventilated rotors, achieving superior heat rejection in steel-mill conveyors and port cranes. German automotive component plants specify disc architectures for automated press lines where ISO 12100 safety thresholds mandate predictable fade resistance.
- Hydraulic Calipers:Oil-pressurized clamping generates 50-500 kN holding force through master-cylinder actuation, dominating heavy-equipment specifications. Chinese construction OEMs source hydraulic units for excavator swing brakes under GB standards machinery-safety certification requirements.
- Drum Calipers:External contracting shoes against cylindrical drums serve cost-optimized mining trucks and legacy agricultural equipment.
- Pneumatic Calipers:Compressed-air actuation persists in explosive-atmosphere applications where spark elimination overrides efficiency concerns.
Mature deployment sits with Disc Calipers. Newer deployment is concentrated in Pneumatic Calipers as electromechanical displacement accelerates.
End User:
Application-driven specification divergence separates contamination-sensitive food-grade operations from particulate-tolerant outdoor equipment.
- Manufacturing Plants:Automated assembly lines demand calipers with integrated position feedback and real-time wear telemetry. Swiss pharmaceutical packaging facilities specify oil-free electromechanical brakes to eliminate lubricant contamination under EU GMP Annex 1 clean-room protocols.
- Warehouses:Automated storage and retrieval systems prioritize maintenance-interval extension and energy recovery. Dutch e-commerce fulfillment centers are retrofitting crane systems with electromechanical calipers to meet F-Gas Regulation phase-down timelines for pneumatic infrastructure.
- Construction Equipment:Hydraulic disc configurations dominate excavator and loader specifications where mud ingress tolerance outweighs precision requirements.
- Automotive:Tier-one suppliers specify standardized caliper families for conveyor and automated guided vehicle integration across multinational assembly footprints.
Procurement scale clusters in Manufacturing Plants. Technology refresh is accelerating fastest in Warehouses.
Material:
Weight-versus-cost tradeoffs define supplier selection, with carbon pricing and Scope 3 traceability emerging as procurement filters.
- Cast Iron:Grey iron housings with lamellar graphite microstructure deliver vibration damping at commodity price points. Indian construction equipment OEMs source cast-iron calipers for domestic mining truck production under PLI scheme localization incentives.
- Aluminum:Forged 6061-T6 alloy bodies reduce unsprung mass by 40-60% versus iron equivalents, enabling faster cycle times in high-speed automation. Swedish automotive plants are specifying aluminum calipers with certified low-carbon primary metal to meet Science Based Targets initiative commitments.
- Carbon Composite:Carbon-ceramic matrices serve aerospace-tier thermal loads at price multiples excluding industrial volume adoption.
- Stainless Steel:Corrosion-resistant housings address chemical-processing and marine applications where salt or caustic exposure degrades ferrous materials.
Foundry capacity locks in Cast Iron dominance. Aluminum is climbing the fastest as lightweighting mandates spread from automotive into industrial machinery.
Technology:
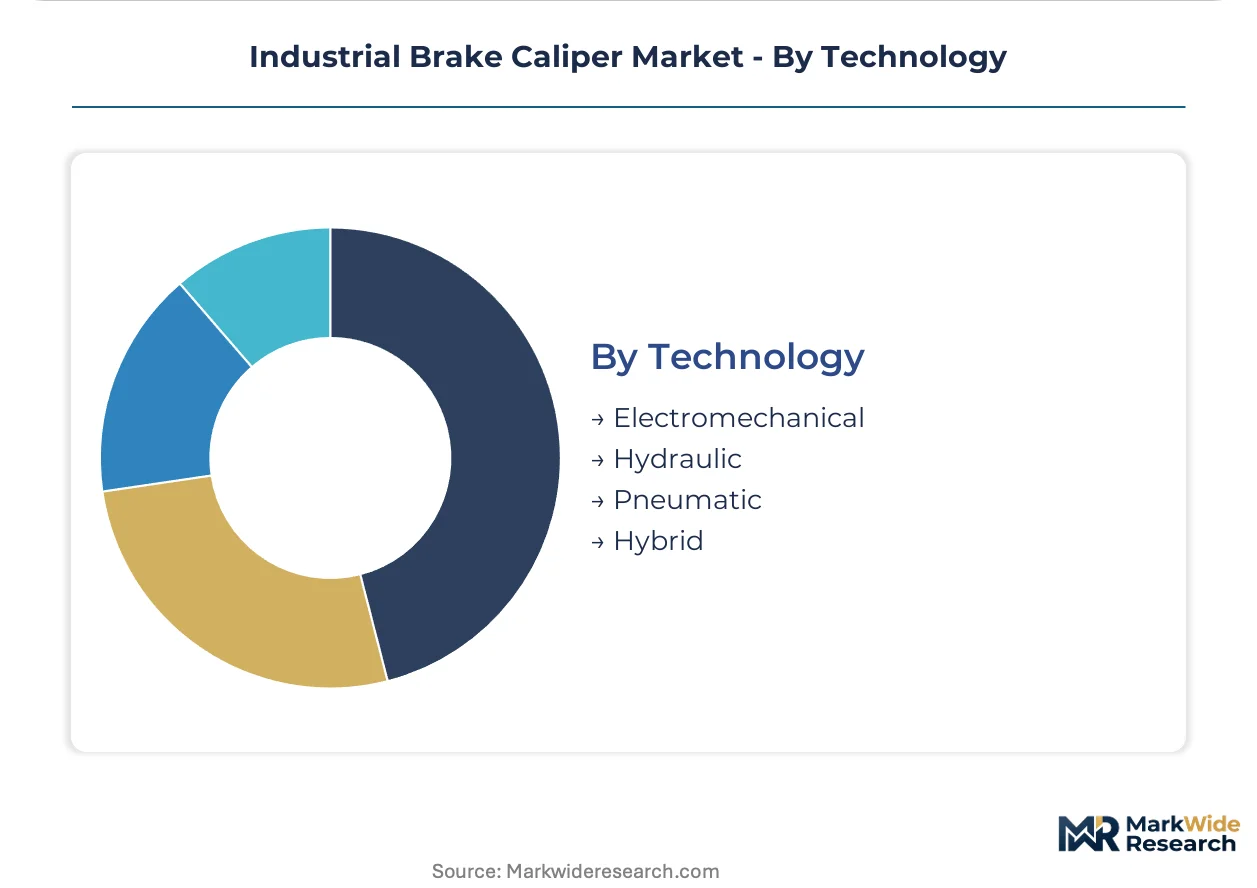
Actuation-method selection determines maintenance economics, energy consumption, and regulatory compliance pathways across end-use environments.
- Electromechanical:Servo-driven ball-screw mechanisms convert rotary motor input to linear clamping force with position-controlled precision. United States food-processing warehouses specify electromechanical brakes to eliminate hydraulic oil contamination risks under FDA Food Safety Modernization Act preventive controls.
- Hydraulic:Pressurized fluid systems maintain clamping force without continuous power input, suing safety-critical holding applications. German rail maintenance depots specify hydraulic calipers for wheel lathe workholding where power-loss protection is mandatory.
- Pneumatic:Compressed-air systems face displacement as EU F-Gas Regulation and factory decarbonization targets raise operating costs.
- Hybrid:Dual-mode actuation combining pneumatic emergency release with electromechanical precision positioning serves specialized press brake applications.
Installed base concentrates in Hydraulic systems. Steepest expansion trajectory belongs to Electromechanical as servo-drive costs decline and IoT integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates European demand for heavy-duty brake calipers serving steel-mill conveyors and port crane systems.
Germany
Automotive component plants in Stuttgart and Wolfsburg specify ISO 12100-compliant electromechanical calipers for automated press lines. The EU F-Gas Regulation accelerates pneumatic system displacement in Bavarian automotive facilities. KBA type-approval timelines extend qualification periods for reformulated friction materials.
China
Construction equipment OEMs in Xuzhou and Changzhou source hydraulic disc calipers for excavator swing brakes under GB standards machinery-safety certification. SAMR enforcement tightens testing protocols for domestic brake system upgrades. Yangtze River Delta foundries supply grey iron housings for mining truck production.
United States
E-commerce fulfillment centers in Chicago and Dallas retrofit automated storage systems with oil-free electromechanical brakes. EPA particulate standards constrain friction-material formulations for North American suppliers. FDA Food Safety Modernization Act preventive controls mandate contamination-free braking in food-processing warehouses.
India
PLI scheme incentives draw semiconductor and electronics manufacturing to Gujarat and Karnataka, creating electromechanical brake demand in clean-room material handling. BIS certification requirements shape domestic procurement specifications. Tamil Nadu construction equipment OEMs source cast-iron calipers for mining truck localization.
Japan
Automotive tier-one suppliers in Toyota City and Yokohama specify standardized caliper families for conveyor integration across multinational assembly footprints. METI industrial decarbonization targets press manufacturers toward energy-efficient actuation systems. Kansai region pharmaceutical packaging facilities mandate oil-free braking under EU GMP-aligned protocols.
Industrial Brake Caliper Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier base. Foundry ownership separates integrated manufacturers from assembly-focused competitors. Three archetypes dominate: captive-foundry European specialists, sensor-integrated technology providers, and Asian volume-scale fabricators. Strategic moves concentrate on backward integration into friction-material production and geographic expansion through regional distribution partnerships.
Within the captive-foundry tier, Brembo SpA and Knorr Bremse AG exemplify European integrated manufacturing. Robert Bosch GmbH anchors the sensor-integrated systems archetype. These three represent divergent competitive positions: Italian motorsport heritage, German rail and heavy-equipment specialization, and Stuttgart-based electromechanical technology development.
| Leading Market Players |
|---|
| Brembo SpA |
| Knorr Bremse AG |
| Robert Bosch GmbH |
| HL Mando Corporation |
| Aisin Seiki Co., Ltd. |
| Continental AG |
| Akebono Brake Industry Co., Ltd. |
| Haldex AB |
| ZF Friedrichshafen AG |
| Others |
Supply & Pricing Matrix
EU Green Deal decarbonization mandates gate qualified supply for premium-tier electromechanical calipers, concentrating pricing power among foundry-integrated suppliers with certified low-carbon steel procurement. Buyers seeking Scope 3 traceability face elongated supplier qualification timelines that compress commodity-tier margins while amplifying premium positioning for backward-integrated manufacturers.
Pricing Analysis
Value-based pricing anchors on guaranteed uptime and maintenance-interval extension in automated manufacturing environments. Three-tier pricing structure across premium, standard, and economy levels separates ISO 12100-certified electromechanical units from commodity hydraulic configurations and legacy pneumatic systems. Pricing pressure stems from aluminum ingot volatility on the London Metal Exchange, compressing forged-alloy margins against cast-iron alternatives. Construction equipment buyers exhibit highest price sensitivity, while pharmaceutical clean-room operators prioritize contamination elimination over unit cost.
Supply Chain Analysis
Skilled foundry workforce availability constrains capacity expansion in Germany's Ruhr corridor and China's Yangtze River Delta, tethering high-integrity casting output to established metallurgical labor pools. Grey iron feedstock draws from domestic blast furnace networks, while servo-drive components and position sensors source from Japanese and German precision manufacturers. Single-source vulnerability concentrates in captive foundry operations at tier-one suppliers, limiting second-tier access to heavy-duty configurations. Distribution runs through OEM direct procurement for multinational automotive tier-ones and regional distributor networks for construction equipment aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into friction-material production and captive foundry capacity defines the vertical-integration race, with sensor-integrated electromechanical development as the decisive downstream lever.
For Market Incumbents: Anticipate electromechanical displacement by accelerating servo-drive compatibility certification and securing aluminum supply agreements ahead of LME volatility. Foundry emissions compliance under China's MEE enforcement and California air-quality regulations threatens captive casting economics, demanding capital redeployment toward electric melting. In-house friction-material reformulation offsets REACH Annex XVII testing timeline extensions. For New Entrants and Emerging Players: Regional distributor partnerships in India's PLI scheme corridors offer lowest entry friction for clean-room material handling specifications. Semiconductor and electronics manufacturing automation in Gujarat and Karnataka presents the most penetrable white-space, with electromechanical brake demand outpacing established supplier presence. Lead with sensor-integrated predictive maintenance propositions to differentiate against commodity hydraulic incumbents. For Investors and Strategic Acquirers: KBA type-approval timeline extensions for reformulated friction materials are the leading indicator that regulatory qualification capacity will consolidate toward integrated manufacturers. Long-term viability favors suppliers with captive foundry operations and in-house friction-material production spanning the 5-10 year regulatory compliance horizon. Target acquisition archetype: mid-cap electromechanical specialists with established servo-drive integration expertise and regional certification in multiple jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Friction Materials | Eliminates REACH testing dependency and compresses KBA approval cycles for German rail contracts. |
| Electromechanical Platform Standardization | Enables multinational spare-parts logistics consolidation for automotive tier-one suppliers in Mexico and Thailand. |
| Captive Foundry Electrification | Secures MEE compliance in China and California air-quality permit continuity for grey iron capacity. |
| Sensor-Integrated Predictive Maintenance | Unlocks aftermarket service revenue streams through IoT-enabled wear monitoring in automated warehouses. |
| Low-Carbon Steel Certification | Meets Science Based Targets initiative procurement filters from Swedish and Danish automotive plants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this industrial brake caliper analysis. Primary interviews with plant engineers, maintenance directors at steel mills and port facilities, OEM procurement teams in automotive and construction equipment, and aftermarket service heads validated demand patterns. Secondary sources included KBA type-approval databases, EPA friction-material content registrations, SAMR machinery-safety certification records, and EU ECHA REACH restriction updates. Bottom-up caliper shipment estimates by technology and material triangulated against top-down manufacturing value-added projections.
Data-stream reconciliation across electromechanical, hydraulic, pneumatic, and hybrid actuation technologies produced volume and value outputs over the projection horizon. Segmentation dimensions encompassed product architecture, end-use environment, housing material, and actuation method, with regional regulatory cluster as an additional modeling layer. CAGRs derived from technology displacement curves, aluminum price scenario modeling, and automation adoption rates in warehouse and manufacturing verticals. Forecast inputs included servo-drive cost decline trajectories and EU F-Gas Regulation phase-down timelines.
Caveats apply where aluminum price spikes, REACH friction-material reformulation delays, or MEE foundry enforcement intensification could materially shift the outlook. Forecasts embed assumptions regarding electromechanical adoption rates and regulatory compliance timeline stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Child Seats Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Car Radiator Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
China Forklift Battery Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
US Automotive Sensors Market
Vehicle Components
Sideloaders Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Garbage Collection Vehicle Market