
 Crank Case Ventilation Valve Market | 2026-2036
Crank Case Ventilation Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Crank Case Ventilation Valve Market Outlook
Polymer composites are restructuring cost structures across crank case ventilation valve manufacturing as metal-to-plastic substitution reduces component weight and corrosion susceptibility. MAHLE GmbH leverages extensive in-house polymer compounding capabilities to control material specifications across its valve portfolio. Robert Bosch GmbH anchors European supply through integrated electromechanical actuator production for electronic control variants. Continental AG differentiates via software-calibrated solenoid valve platforms that integrate with broader engine management systems.
A crank case ventilation valve regulates pressure within an internal combustion engine's crankcase by routing blow-by gases back into the intake manifold, typically operating within vacuum differentials of -50 to -350 mbar and incorporating fluorocarbon elastomer seals for chemical resistance against oil vapor degradation. Positive crankcase ventilation valves dominate installed volume across light duty vehicle applications where regulatory mandates for evaporative emissions control remain most stringent. Electronic control valves represent the fastest-expanding technology segment as powertrain electrification and hybrid architectures demand real-time pressure modulation unavailable from mechanical predecessors. OEM channels capture the majority of value given calibration-intensive integration requirements with engine control units, though aftermarket providers sustain margin pools in regions with aging vehicle parc and extended service intervals.
EPA tailpipe and evaporative emissions standards, Euro 7 requirements under ECHA and European Commission frameworks, and China's GB 18352.6-2016 national standards collectively mandate escalating crankcase pressure control precision and material compatibility testing. These regulations force redesign cycles that favor suppliers with certified testing infrastructure and multi-region homologation experience. Stakeholders must monitor divergence between regional certification timelines and emerging powertrain electrification roadmaps to align valve platform investments with durable demand.
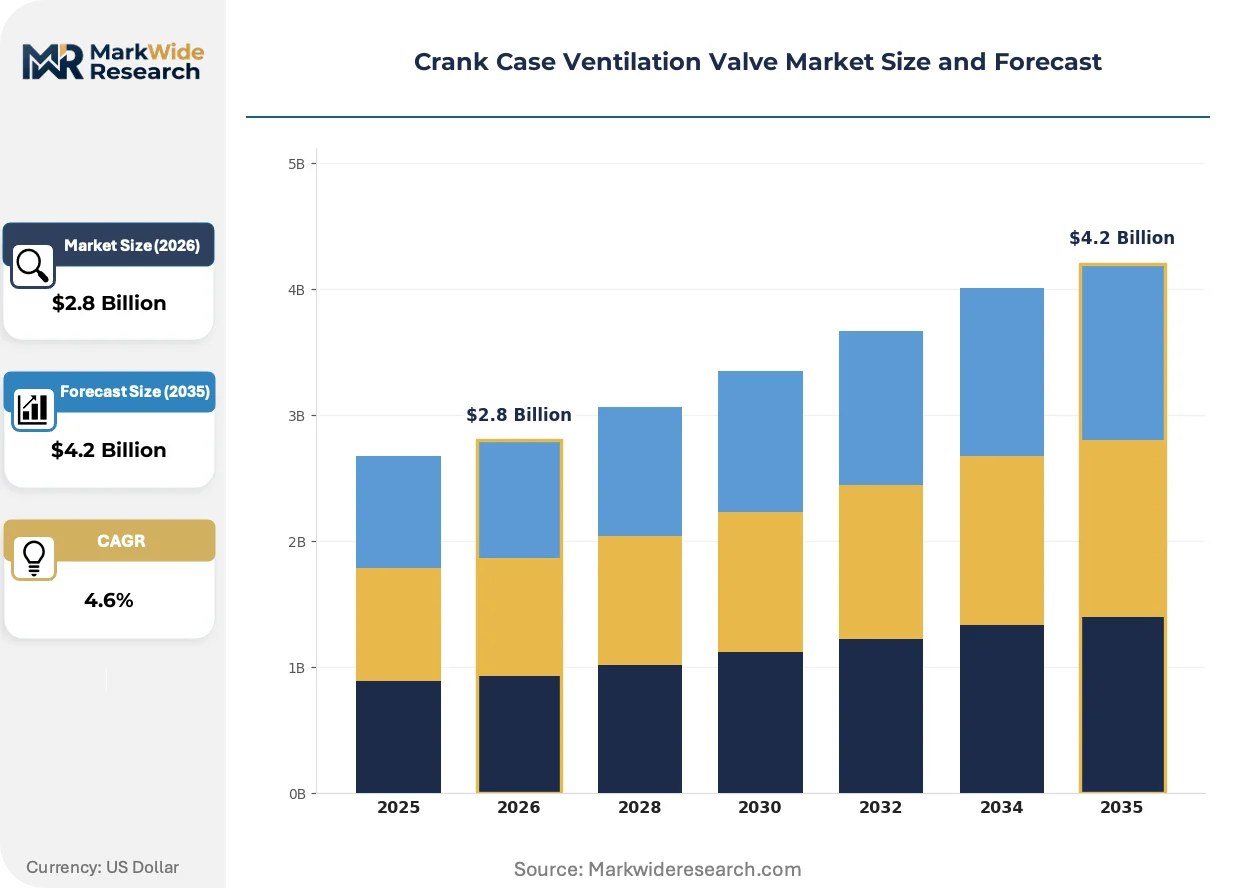
Market Dynamics
Powertrain electrification is fragmenting demand across mechanical and electronic crank case ventilation valve architectures, forcing suppliers to maintain dual development tracks while hybrid vehicle volumes expand.
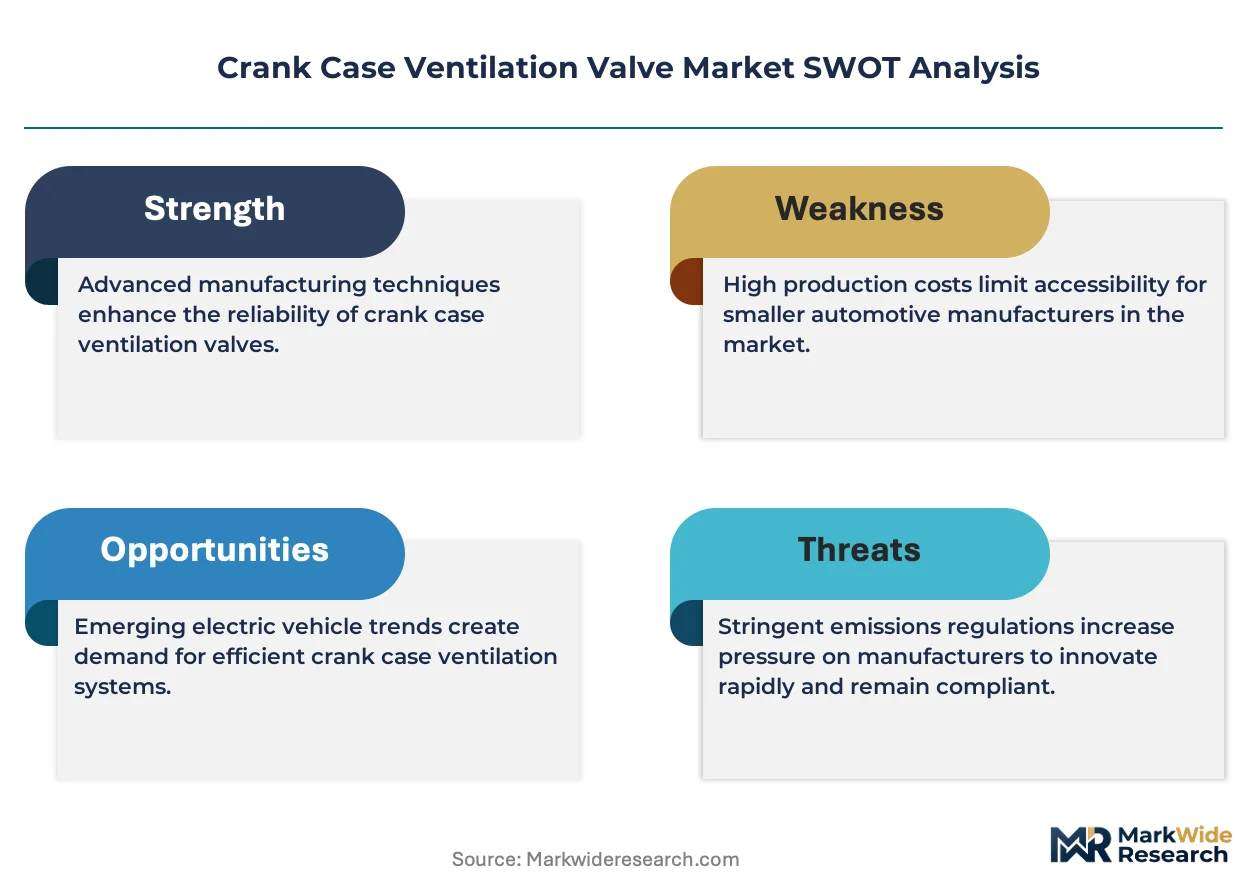
Growth Catalysts
- EPA Tier 3 evaporative emissions standards:Mandates for enhanced blow-by gas capture are compelling valve redesigns with tighter pressure tolerances and fluorocarbon seal specifications across light duty vehicle platforms.
- Polymer composite substitution:Metal-to-plastic conversion in valve housings reduces unit weight and corrosion susceptibility while enabling complex geometries for improved flow dynamics.
- Germany engineering concentration:Clustered R&D capabilities around Stuttgart and Munich accelerate prototype-to-production cycles for Euro 7-compliant electronic control variants.
Market Restraints
- Fluorocarbon elastomer supply concentration:Specialty seal material production concentrates among limited chemical suppliers, exposing valve manufacturers to input cost volatility and allocation constraints.
- Mechanical valve demand erosion:Powertrain electrification is compressing addressable volume for conventional vacuum-actuated designs as hybrid architectures prioritize electronic modulation.
- REACH substance restrictions:ECHA scrutiny of per- and polyfluoroalkyl substances threatens established seal compound formulations and forces qualification of alternative chemistries.
Strategic Opportunities
- China GB 18352.6-2016 Phase 6b implementation:Stricter crankcase emissions testing protocols create specification upgrade cycles for domestic and export-oriented vehicle manufacturers.
- Electronic-mechanical convergence:Integration of solenoid actuators with pressure sensors and engine control unit calibration is enabling predictive maintenance and real-time diagnostic capabilities.
- Aftermarket service interval extension:Aging vehicle parc in North American and European markets sustains replacement demand as OEM recommended service periods lengthen.
Industry Challenges
- Multi-region homologation complexity:Divergent EPA, ECHA, and MIIT certification timelines force parallel testing programs and strain validation engineering capacity.
- Electromechanical integration expertise:Shortage of engineers proficient in both pneumatic valve design and embedded software calibration slows electronic control platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crank Case Ventilation Valve Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Crankcase Ventilation Valve, Electronic Control Valve, Manual Control Valve, Vacuum Control Valve End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Service Centers Application: Light Duty Vehicles, Heavy Duty Vehicles, Commercial Vehicles, Motorcycles Technology: Mechanical Valve, Solenoid Valve, Pneumatic Valve, Hybrid Valve |
| Companies Covered | MAHLE GmbH, MANN+HUMMEL, Tenneco Inc., Aisan Industry Co. Ltd., Continental AG, SMP Deutschland GmbH, Robert Bosch GmbH, Alfdex AB, Parker Hannifin Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crank Case Ventilation Valve Market Strategic Shifts
Software-defined functionality is displacing mechanical determinism across crank case ventilation systems, with valve operation increasingly governed by engine control unit algorithms rather than fixed vacuum thresholds.
Smart valve architectures incorporating pressure transducers and solenoid actuators are unifying sensing and modulation within single housing units. Hybrid powertrain manufacturers in Germany and Japan are adopting these integrated designs at accelerated rates. This convergence is compressing the supplier base by disqualifying pure-play mechanical component producers from electronic platform sourcing.
Euro 7 regulations under ECHA and European Commission frameworks are mandating real-time crankcase pressure monitoring and diagnostic capability. The industrial consequence is a forced transition from passive mechanical valves to actively controlled electronic systems with onboard sensing. Light duty diesel and gasoline applications face the steepest compliance burden, with OEMs consolidating supplier qualifications around platforms with pre-certified software stacks.
Fleet operators and commercial vehicle buyers are consolidating procurement around engine management system suppliers offering integrated crank case ventilation modules rather than discrete valve components. This bundling displaces standalone valve sourcing through tier-one powertrain integrators. North American heavy-duty truck manufacturing exhibits the most pronounced concentration, with vertical integration favoring suppliers with captive electromechanical actuator production.
Crank Case Ventilation Valve Market Segmentation
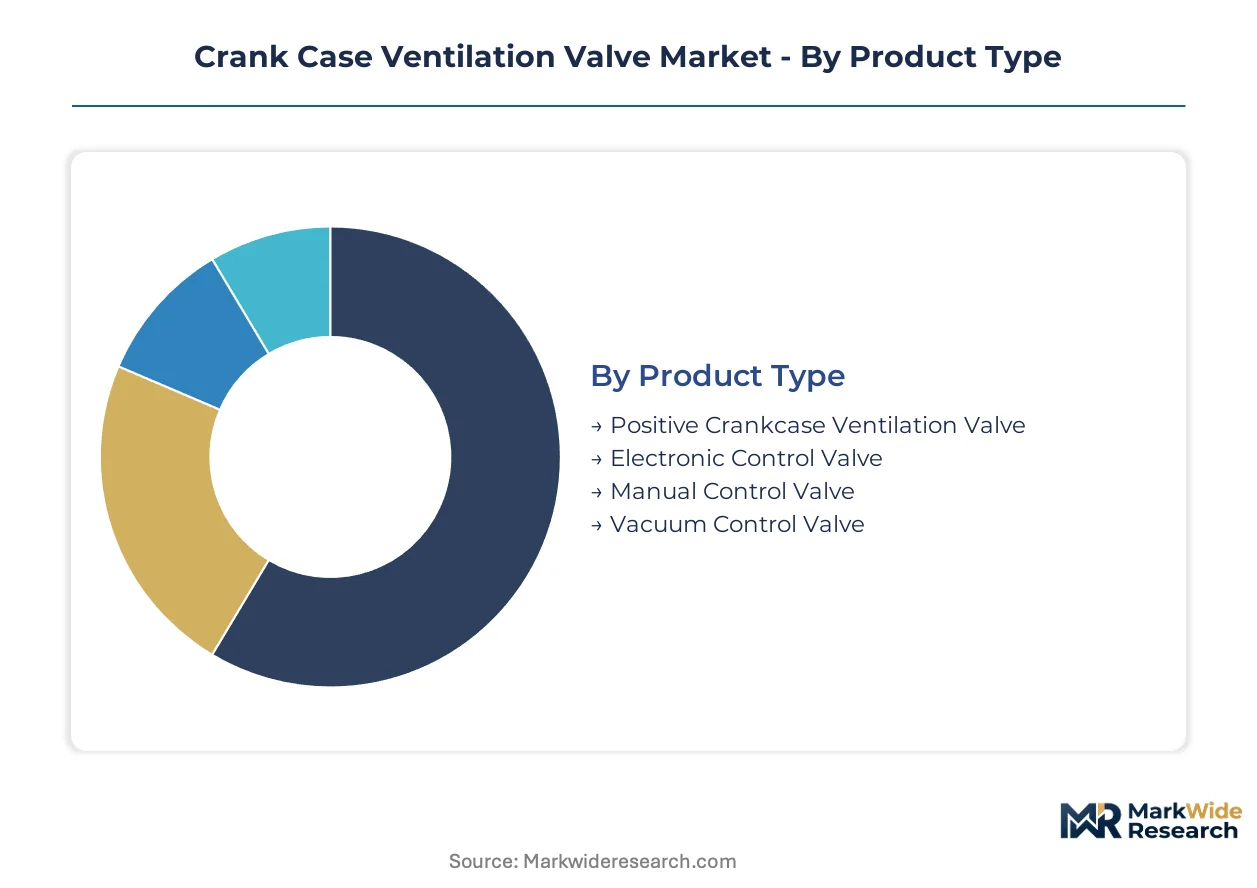
Segmentation in the crank case ventilation valve market reveals how capital deployment, regulatory exposure, and integration complexity concentrate value across distinct technology and customer configurations. Suppliers must align platform investments with segments that reward calibration-intensive engineering versus commodity replacement volume.
Product Type:
Electronic control valves demand the steepest upfront capital commitment, requiring cleanroom assembly environments, embedded software validation infrastructure, and multi-region homologation testing. Mechanical variants require far less specialized equipment but face compressing margins.
- Positive Crankcase Ventilation Valve:Vacuum-actuated devices with fluorocarbon elastomer seals rated for -50 to -350 mbar operating differentials. Light duty vehicle manufacturers in Germany specify these for Euro 7 pre-compliance builds, though electronic successors are displacing mechanical architectures in new platform designs.
- Electronic Control Valve:Solenoid-actuated systems with integrated pressure transducers and engine control unit calibration protocols. Hybrid powertrain manufacturers in Japan and Germany are adopting these at accelerated rates as real-time crankcase pressure modulation becomes mandatory for evaporative emissions compliance.
- Manual Control Valve:Basic mechanical adjustment mechanisms for legacy vehicle parc and aftermarket replacement cycles.
- Vacuum Control Valve:Pneumatic modulation devices dependent on intake manifold vacuum differentials, concentrated in aging vehicle populations and cost-sensitive commercial applications.
Positive crankcase ventilation valves absorb the bulk of installed capacity; electronic control valves are expanding most quickly.
End User:
Customer type determines margin structure through calibration ownership, with OEMs capturing specification control while aftermarket providers compete on availability and price.
- OEMs:Original equipment manufacturers specify valve architectures during engine development cycles and retain calibration intellectual property. EPA Tier 3 and Euro 7 mandates are forcing closer integration between valve suppliers and OEM engine control unit teams.
- Aftermarket Providers:Distributors and retailers serving replacement demand from aging vehicle parc in North America and Europe. Extended OEM service intervals are compressing traditional replacement frequency, forcing aftermarket players toward commercial vehicle and motorcycle segments.
- Vehicle Manufacturers:Light duty and heavy duty vehicle assemblers procuring integrated engine management modules rather than discrete valves.
- Service Centers:Independent repair facilities and dealer networks performing warranty and post-warranty maintenance.
OEMs command the specification architecture; aftermarket providers are gaining volume in regions with extended vehicle lifecycles.
Application:
Vehicle class dictates pressure tolerance requirements, duty cycle severity, and regulatory scrutiny intensity.
- Light Duty Vehicles:Passenger cars and light trucks subject to the most stringent evaporative emissions testing under EPA and Euro 7 frameworks. Electronic control valve adoption is concentrating here as hybrid architectures proliferate.
- Heavy Duty Vehicles:Long-haul trucks and vocational equipment with extended operating hours and severe crankcase pressure cycling. North American heavy-duty manufacturers are consolidating procurement around integrated engine management suppliers with captive electromechanical production.
- Commercial Vehicles:Delivery vans, buses, and fleet equipment where total cost of ownership drives specification decisions.
- Motorcycles:Two-wheel and three-wheel vehicles with compact packaging constraints and cost-sensitive production economics.
Light duty vehicles dominate specification development; heavy duty vehicles are climbing fastest in average content per engine.
Technology:
Technology choice determines supplier qualification barriers, with electromechanical convergence favoring integrated system houses over component specialists.
- Mechanical Valve:Passive vacuum-responsive devices with fixed orifice geometries and spring-loaded diaphragm actuation. Demand is eroding as powertrain electrification compresses addressable volume for conventional designs.
- Solenoid Valve:Electromagnetically actuated systems enabling pulse-width modulated flow control. German and Japanese hybrid manufacturers specify these for platforms requiring real-time diagnostic capability and predictive maintenance integration.
- Pneumatic Valve:Compressed-air actuated designs for heavy duty applications with auxiliary air systems.
- Hybrid Valve:Architectures combining mechanical fallback with electronic modulation for transitional powertrain configurations.
Mechanical valves retain the largest installed base; solenoid valves are gaining share fastest in new platform awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates engineering and production capabilities for crank case ventilation valves, with Stuttgart and Munich anchoring R&D clusters serving Euro 7 pre-compliance builds. Light duty vehicle manufacturers in Japan and the United States are accelerating electronic control valve adoption as hybrid architectures proliferate.
Germany
Stuttgart-based MAHLE GmbH and Continental AG drive specification development for Euro 7-compliant electronic control variants. ECHA scrutiny under REACH frameworks forces qualification of alternative seal chemistries beyond established fluorocarbon compounds. Munich engineering clusters accelerate prototype-to-production cycles for solenoid-actuated systems with integrated pressure transducers.
United States
EPA Tier 3 evaporative emissions standards mandate enhanced blow-by gas capture across light duty vehicle platforms. Detroit-area powertrain integrators consolidate procurement around suppliers with captive electromechanical actuator production. Heavy-duty truck manufacturers in the Midwest favor integrated engine management modules over discrete valve sourcing.
Japan
Hybrid powertrain manufacturers specify electronic control valves requiring real-time crankcase pressure modulation. METI frameworks align with Euro 7-equivalent emissions testing protocols for domestic and export markets. Nagoya engineering centers develop solenoid valve platforms with predictive maintenance integration for fleet operators.
China
GB 18352.6-2016 Phase 6b implementation creates specification upgrade cycles for domestic vehicle manufacturers. MIIT certification timelines force parallel testing programs for crankcase emissions control components. Yangtze River Delta production clusters serve export-oriented joint ventures adapting to stricter testing protocols.
Crank Case Ventilation Valve Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with OEM channels favoring integrated system houses and aftermarket providers competing on availability. The supplier base concentrates around electromechanical convergence capabilities, disqualifying pure-play mechanical component producers from electronic platform sourcing. Three archetypes dominate: German engineering-centric conglomerates with in-house polymer compounding, Japanese precision manufacturers serving hybrid powertrain specialists, and North American integrated powertrain module suppliers. Competitive moves center on backward integration into electromechanical actuator production and strategic partnerships for multi-region homologation testing.
Among German engineering-centric players, MAHLE GmbH, Continental AG, and Robert Bosch GmbH exemplify the integrated system house archetype. MAHLE GmbH represents suppliers with extensive in-house material specification control. Continental AG occupies a position emphasizing software-calibrated platform integration. Robert Bosch GmbH anchors European supply capabilities through embedded production infrastructure. These entities collectively illustrate how Euro 7 compliance demands are compressing qualification around pre-certified software stacks and captive electromechanical manufacturing.
| Leading Market Players |
|---|
| MAHLE GmbH |
| MANN+HUMMEL |
| Tenneco Inc. |
| Aisan Industry Co. Ltd. |
| Continental AG |
| SMP Deutschland GmbH |
| Robert Bosch GmbH |
| Alfdex AB |
| Parker Hannifin Corp |
| Others |
Value Chain & Pricing Dynamics
Fluorocarbon elastomer price indices cascade through crank case ventilation valve manufacturing, compressing margins for mechanical variants while electronic control tiers capture value through software calibration and sensor integration. OEM procurement consolidation around integrated engine management modules concentrates pricing power among suppliers with captive electromechanical actuator production.
Pricing Analysis
High-volume mechanical valve contracts trade at thin margins while electronic control variants command premium positioning through embedded software validation and multi-region homologation bundling. Price differentiation separates Euro 7 pre-certified platforms with integrated pressure transducers from commodity mechanical replacements lacking diagnostic capability. Pricing pressure stems from REACH substance restrictions forcing alternative seal chemistry qualification costs onto manufacturers. Aftermarket distributors exhibit highest price sensitivity, while OEM engine control unit teams prioritize calibration reliability over unit cost.
Supply Chain Analysis
Specialty fluorocarbon elastomer supply rests on concentrated Japanese and German chemical producers, exposing valve manufacturers to allocation constraints and input cost volatility. Component sourcing draws from China for stamped metal housings, Germany for precision solenoid actuators, and Japan for pressure sensor modules. Single-source vulnerability concentrates in fluorocarbon seal compounds subject to ECHA scrutiny. Distribution runs through Tier 1 powertrain integrators rather than discrete valve channels, with fleet operators consolidating procurement around bundled engine management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crank case ventilation valve manufacturing occupies a technology-transition phase as solenoid-actuated electronic architectures displace vacuum-responsive mechanical predecessors across hybrid powertrain platforms.
For Market Incumbents: To counter mechanical valve demand erosion from powertrain electrification, MAHLE GmbH and Continental AG should accelerate backward integration into electromechanical actuator production and pre-certify software stacks for Euro 7 real-time diagnostic mandates. Captive polymer compounding capabilities defend material specification control against fluorocarbon supply concentration. For New Entrants and Emerging Players: Direct-to-fleet digital channels offer white-space entry points in North American heavy-duty truck aftermarket segments where aging vehicle parc sustains replacement demand. Target commercial vehicle service centers with standalone electronic control valve retrofit kits bypassing OEM calibration lock-in. Pursue qualification partnerships with Yangtze River Delta joint ventures adapting to GB 18352.6-2016 Phase 6b protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier German engineering houses with stranded mechanical valve capacity but intact ECHA certification infrastructure. Long-term viability hinges on electronic platform transition completion within the next decade. Monitor MIIT homologation timeline acceleration as inflection signal for China specification upgrade cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electromechanical Actuator Production | Captive solenoid manufacturing secures supply continuity for Euro 7 electronic control valve platforms. |
| Pre-Certified Software Stack Development | Engine control unit calibration protocols accelerate OEM qualification cycles under ECHA diagnostic mandates. |
| Alternative Seal Chemistry Qualification | REACH-compliant fluorocarbon substitutes reduce regulatory exposure across European light duty vehicle supply. |
| Fleet-Focused Aftermarket Digital Channel | Direct procurement relationships with commercial vehicle operators bypass Tier 1 powertrain integrator concentration. |
| Multi-Region Homologation Partnership | Parallel EPA, ECHA, and MIIT testing programs compress time-to-market for hybrid powertrain platform awards. |
Study Parameters
Document review covered EPA regulatory filings, ECHA REACH substance registrations, MIIT certification databases, and OEM powertrain procurement disclosures, complemented by interviews with Tier 1 supplier engineering directors, fleet maintenance managers, and aftermarket distribution channel heads. Secondary validation drew from vehicle production databases, customs trade records for fluorocarbon elastomer imports, and SEC filings from listed automotive component suppliers. Bottom-up segment sizing triangulated against top-down powertrain production forecasts.
Market projections integrated vehicle class segmentation, propulsion architecture migration curves, and content-per-vehicle assumptions for mechanical versus electronic valve configurations across the analysis window. CAGR derivation incorporated regulatory compliance timeline phasing, OEM platform lifecycle schedules, and aftermarket replacement frequency modeling. Industry-specific inputs included Euro 7 diagnostic mandate implementation schedules and GB 18352.6-2016 Phase 6b testing protocol adoption rates.
The model holds under stable regulatory enforcement and gradual hybrid powertrain penetration; deviation in ECHA substance restriction acceleration or abrupt ICE phase-out announcements would shift platform investment returns. Forecasts reflect documented assumptions regarding OEM supplier consolidation patterns and fluorocarbon elastomer supply allocation stability. A small set of regulatory timeline triggers and raw material supply shocks warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Rail Components Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Railway Air Filter Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Automotive Sensors Market