
 Saudi Arabia E-Bike Market | 2026-2036
Saudi Arabia E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia E-Bike Market Analytics
Fleet procurement managers are bifurcating from individual consumers as the dominant volume buyers in the Saudi Arabia e-bike landscape. Giant Manufacturing Co. Ltd leverages its established distributor network across Gulf Cooperation Council markets to secure bulk supply agreements with logistics aggregators. Trek Bicycle Corporation anchors its position through premium after-sales service infrastructure in Riyadh and Jeddah showrooms. Eveons Mobility Systems LLC specializes in desert-climate battery thermal management, a critical differentiator where summer ambient temperatures exceed 50°C.
An e-bike integrates an electric motor, rechargeable battery pack, and pedal-assist or throttle-control system into a bicycle frame, typically delivering 250–750 watts of continuous power output for urban mobility and light cargo transport. Pedal-assist configurations dominate unit sales among Saudi commuters seeking exercise-compatible transport, while throttle-control variants capture delivery-fleet operators prioritizing route speed over rider exertion. Lithium-ion battery chemistry leads the installed base due to superior energy density and cycle life, though lithium-polymer packs gain traction in folding e-bikes where form-factor flexibility outweighs cost premiums.
SASO electrical-safety standards and the Saudi Traffic Department's evolving vehicle-classification rules jointly determine which e-bike configurations qualify for road registration versus restricted trail use. The Saudi Energy Efficiency Center's building-code integration of e-bike charging infrastructure into new commercial developments shapes real-estate developer procurement timelines. Stakeholders must monitor whether the Public Investment Fund's giga-project developments mandate micromobility access corridors as binding planning conditions.
Market Dynamics
Fleet procurement managers now dominate Saudi Arabia e-bike volume, redirecting procurement budgets from consumer retail toward electrified logistics contracts as fuel-cost volatility and urban congestion charges bite into delivery margins.
Growth Catalysts
- Last-mile electrification mandates:Municipal logistics regulations in Riyadh and Jeddah now prioritize zero-emission vehicle quotas for commercial delivery permits, accelerating fleet operator adoption.
- Battery thermal management advances:Desert-climate lithium-ion pack designs with active cooling circuits now sustain 50°C ambient operation without cycle-life degradation.
- Red Sea tourism corridor development:Giga-project master plans integrate micromobility access corridors as binding planning conditions, creating captive demand clusters.
Market Restraints
- SASO certification friction:Electrical-safety recertification requirements for redesigned battery-management systems delay customs clearance by 8-12 weeks for non-compliant imports.
- Lithium supply concentration:Cathode precursor processing capacity concentrates in East Asian chemical hubs, exposing Saudi importers to input cost volatility and currency mismatch risks.
- Throttle-control regulatory ambiguity:Saudi Traffic Department vehicle-classification rules create registration uncertainty for delivery-fleet operators prioritizing route speed over pedal-assist compliance.
Strategic Opportunities
- Neom and Qiddiya giga-project integration:Public Investment Fund developments mandate micromobility infrastructure in commercial zoning, opening captive procurement channels for certified suppliers.
- Solar-integrated charging infrastructure:Saudi Energy Efficiency Center building codes for new commercial developments create bundled real-estate developer procurement timelines for charging hardware.
- Desert-tourism rental fleets:Red Sea coastal tourism operators seek ruggedized e-bike configurations for guided excursion services, an application segment currently underserved by urban-optimized imports.
Industry Challenges
- Battery-management system redesign cycles:SASO electrical-safety recertification demands engineering resources that strain importer technical teams and compress product launch windows.
- After-sales thermal specialist scarcity:Desert-climate battery diagnostics and cooling system maintenance require technicians with hybrid electrical-mechanical skills currently scarce in Saudi vocational pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia E-Bike Market |
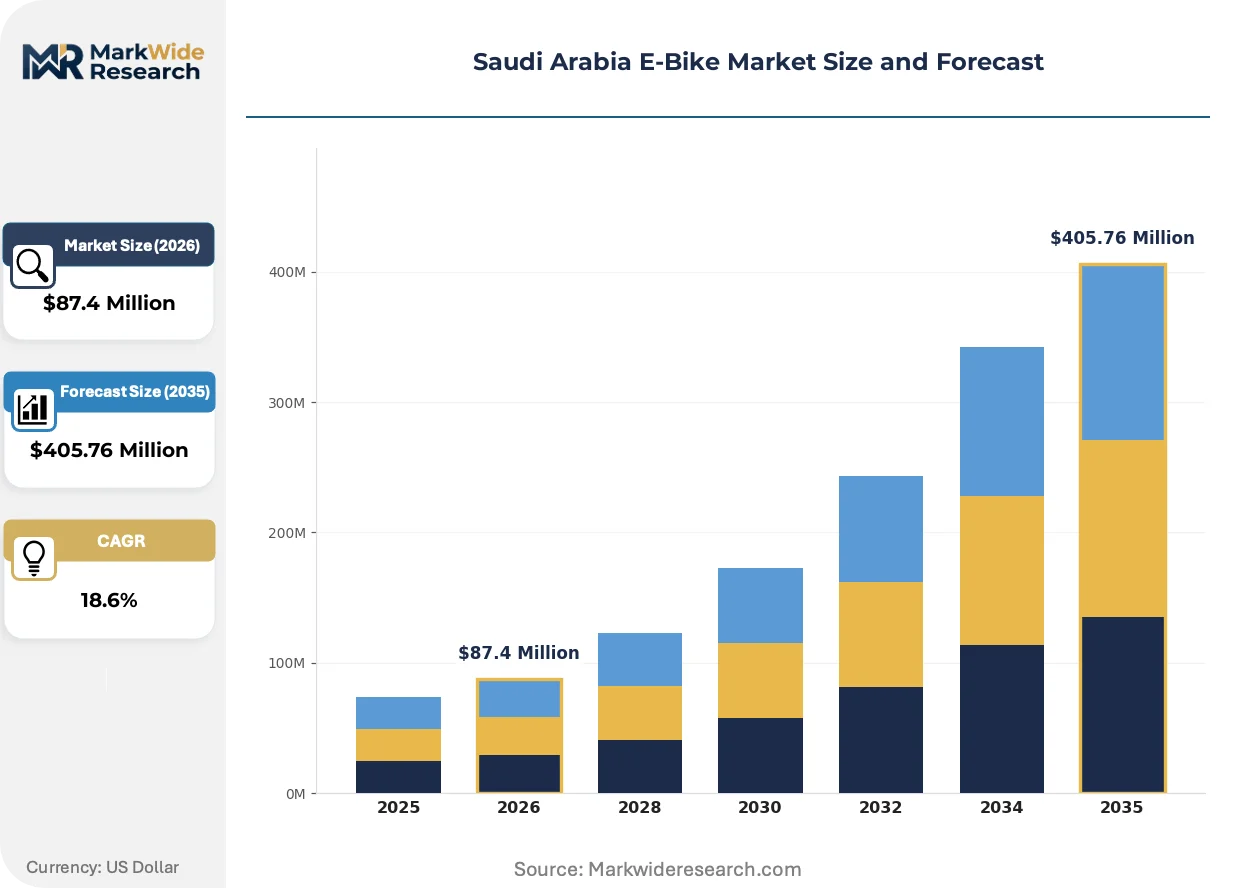
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $405.76 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedal Assist, Throttle Control, Folding E-Bikes, Mountain E-Bikes Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Lithium Polymer Application: Commuting, Recreational Riding, Delivery Services, Off-Roading Price Segment: Affordable, Mid-Range, Premium, Luxury |
| Companies Covered | Accell Group, ONE Moto, Giant Manufacturing Co. Ltd, myStromer AG, Eveons Mobility Systems LLC, Trek Bicycle Corporation, Specialized Bicycle Components, Inc, Vego Group, TRINX Bikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia E-Bike Market Evolving Landscape
Technology convergence and regulatory tightening are compressing product lifecycles while opening new procurement channels for climate-hardened configurations. Three developments merit particular attention.
Modular battery-pack architecture is decomposing traditional integrated frame designs, enabling Saudi fleet operators to swap standardized cells across multiple vehicle platforms rather than maintaining model-specific spare inventories. Logistics aggregators in Riyadh now specify hot-swappable pack compatibility in bulk supply tenders, compressing supplier qualification criteria toward interoperability standards rather than proprietary ecosystems.
SASO tightened electrical-safety certification requirements now mandate redundant battery-management system circuits and thermal runaway containment testing before customs clearance. Importers redesigning lithium-ion pack electronics to satisfy these protocols face extended engineering timelines, with delivery-fleet operators bearing the brunt of product availability gaps during recertification windows.
Service-unbundling now separates hardware procurement from maintenance contracts in Saudi fleet negotiations. Logistics aggregators in Jeddah increasingly source e-bike chassis through capital expenditure budgets while contracting thermal-management specialists for battery lifecycle services, fragmenting traditional distributor revenue streams and favoring vendors with standalone technical service capabilities.
Saudi Arabia E-Bike Market Segmentation
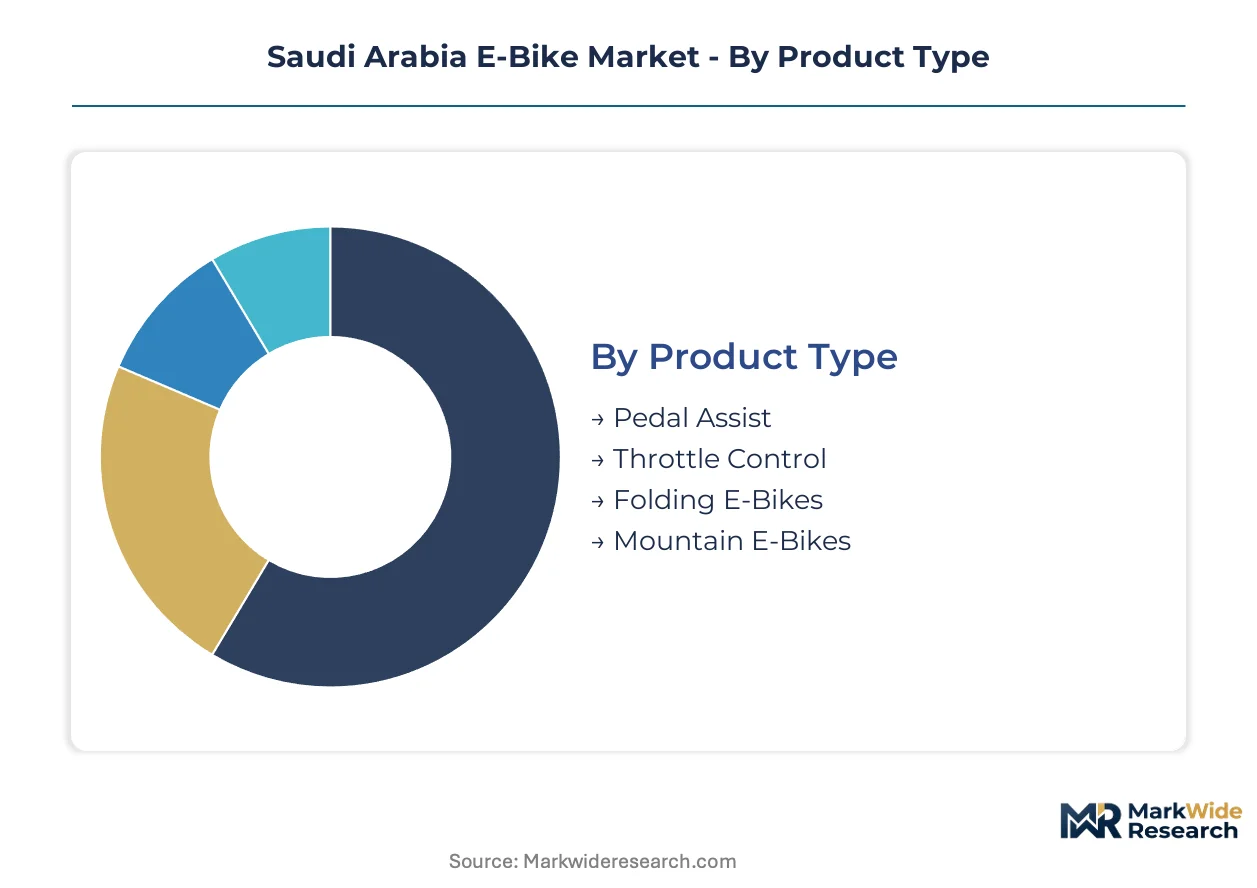
SASO certification protocols and Saudi Traffic Department vehicle-classification rules create divergent compliance pathways across product configurations. Fleet procurement managers and individual consumers face distinct technical requirements that reshape segment prioritization.
Product Type:
SASO electrical-safety standards and the Saudi Traffic Department's evolving registration rules differentiate pedal-assist from throttle-control configurations for road legality.
- Pedal Assist:Electric motor supplements rider pedaling effort through torque or cadence sensors, typically capped at 250 watts continuous output. Riyadh commuters seeking exercise-compatible transport concentrate procurement here, constrained by pedal-assist compliance requirements for unrestricted road registration.
- Throttle Control:Twist-grip or thumb-activated motor engagement delivers power independent of pedaling, enabling 750-watt peak outputs. Jeddah delivery-fleet operators prioritize route speed over rider exertion, though regulatory ambiguity around vehicle classification creates registration uncertainty for commercial operators.
- Folding E-Bikes:Collapsible frame designs with hinge mechanisms and reduced wheelbases suit multimodal transit integration.
- Mountain E-Bikes:Suspension-equipped frames with reinforced construction for trail and desert terrain applications.
Established volume favors Pedal Assist; emerging adoption favors Throttle Control.
Battery Type:
Desert-climate thermal management requirements and energy density trade-offs segment procurement across chemistry families.
- Lithium-Ion:Cylindrical or prismatic cells with 150-250 Wh/kg energy density and 500-1000 cycle life dominate the installed base. Riyadh and Jeddah fleet operators specify active-cooled pack designs to sustain 50°C ambient operation without degradation.
- Lithium Polymer:Pouch-cell construction enables flexible form factors and reduced weight, trading cost premiums for packaging efficiency. Folding e-bike manufacturers prioritize lithium-polymer configurations where frame integration constraints outweigh cost considerations.
- Lead-Acid:Mature flooded or sealed valve-regulated designs with lower energy density but established recycling infrastructure.
- Nickel-Metal Hydride:Intermediate energy density chemistry with reduced memory effect, now largely displaced by lithium alternatives in new procurement.
Current fleet specifications concentrate procurement toward Lithium-Ion; form-factor innovation expands Lithium Polymer placement.
Application:
End-use economics and infrastructure access patterns determine vehicle configuration requirements across buyer archetypes.
- Delivery Services:Commercial logistics operators prioritize payload capacity, route speed, and thermal reliability for sustained desert operation. Municipal zero-emission vehicle quotas in Riyadh and Jeddah accelerate fleet procurement timelines for last-mile electrification mandates.
- Commuting:Individual riders balance range, exercise compatibility, and parking security for daily urban transit. Red Sea tourism corridor development and municipal bike-lane investments in Riyadh and Jeddah expand addressable demand.
- Recreational Riding:Leisure-oriented users emphasize comfort features and aesthetic design for weekend and social use.
- Off-Roading:Desert-tourism operators and adventure riders seek ruggedized suspension and sealed electronics for sand and rock terrain.
Commercial fleet deployment expands fastest in Delivery Services; infrastructure investment unlocks Commuting volume.
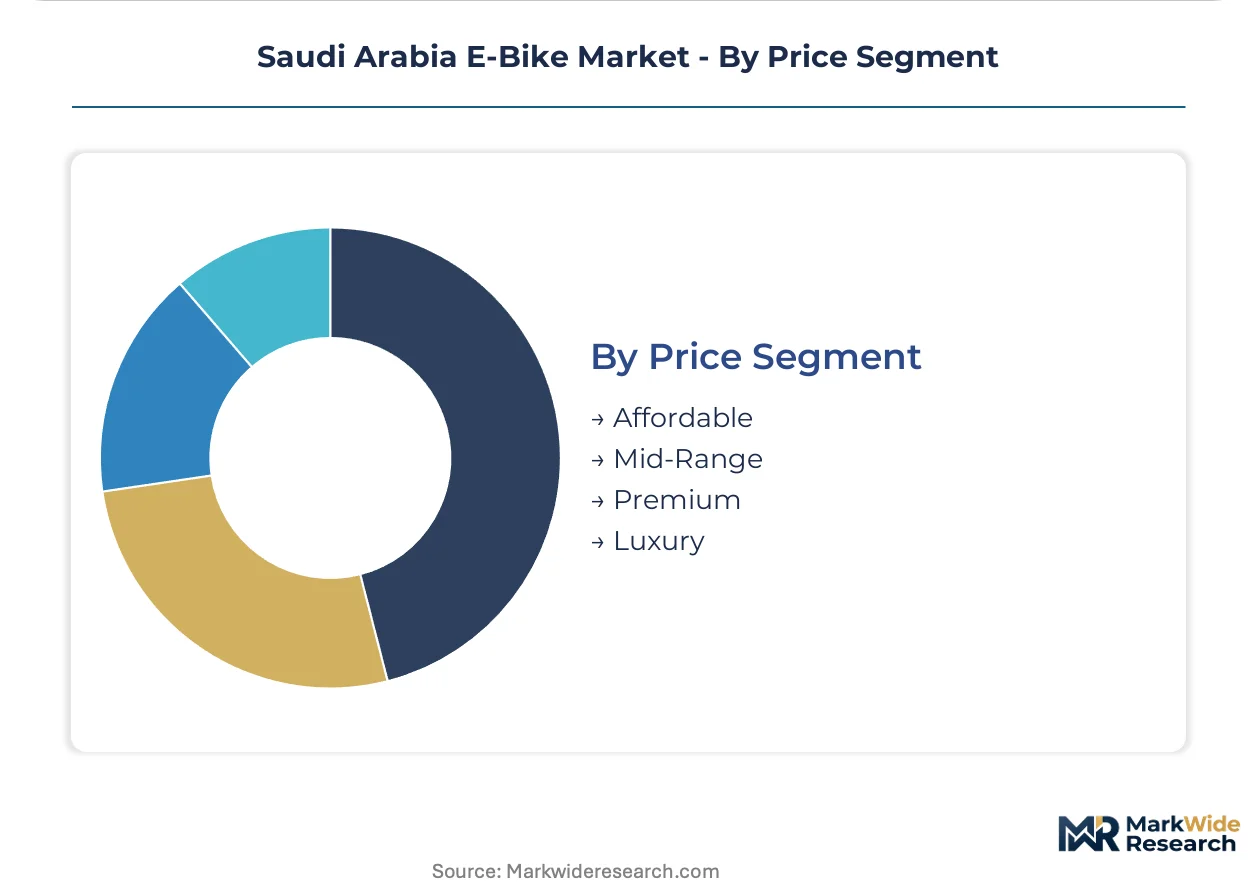
Price Segment:
Procurement budget structures bifurcate between capital-expenditure fleet programs and individual consumer discretionary spending.
- Mid-Range:Balanced component specifications with certified battery-management systems and domestic warranty coverage. Logistics aggregators in Riyadh and Jeddah concentrate bulk procurement here, satisfying SASO compliance requirements without premium feature loading.
- Premium:Enhanced thermal management, extended-range packs, and integrated telematics for fleet monitoring applications. Real-estate developers bundling e-bike infrastructure into Saudi Energy Efficiency Center-compliant commercial developments specify premium configurations for tenant amenity programs.
- Affordable:Entry-level specifications with reduced range and basic componentry for price-sensitive individual consumers.
- Luxury:Limited-production designs with custom frame geometry and concierge service arrangements for high-net-worth individuals.
Fleet procurement concentrates in Mid-Range; Premium gains share through bundled infrastructure development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Riyadh Metro network and Red Sea coastal development corridors anchor Saudi Arabia's e-bike deployment infrastructure, concentrating procurement in metropolitan transit zones and tourism corridors.
Riyadh
Municipal zero-emission vehicle quotas for commercial delivery permits drive fleet procurement at scale. SASO electrical-safety certification requirements compel importers to redesign battery-management systems before customs clearance. The King Abdullah Financial District and Diriyah Gate developments integrate micromobility access corridors as binding planning conditions.
Jeddah
Red Sea tourism corridor development creates captive demand clusters for rental and hospitality fleet operators. The Saudi Energy Efficiency Center mandates e-bike charging infrastructure in new commercial building codes. Logistics aggregators concentrate bulk procurement in the Jeddah Islamic Port hinterland for last-mile distribution networks.
Eastern Province
Industrial city master plans in Jubail and Ras Al-Khair incorporate employee transit solutions as sustainability compliance requirements. The Public Investment Fund's giga-project adjacent developments specify micromobility infrastructure in commercial zoning. Dhahran Techno Valley corporate campuses pilot fleet programs for inter-facility employee transport.
NEOM Northwest
The Line and Oxagon master plans mandate car-free mobility systems with electrified two-wheeler integration as core design principles. NEOM regulatory frameworks establish distinct vehicle-classification rules separate from national Saudi Traffic Department standards. Trojena and Sindalah island developments tender for ruggedized desert-climate configurations.
Makkah Province
Pilgrimage logistics operators evaluate e-bike fleets for inter-site transport during Hajj and Umrah seasons. Municipal authorities in Taif explore bike-lane investments for highland tourism positioning. The Haramain high-speed rail stations at King Abdulaziz International Airport create multimodal transit nodes with micromobility integration potential.
Saudi Arabia E-Bike Market Competitive Landscape
Listed leaders compete with private specialists across distribution reach and technical service capabilities. The vendor base fragments across Gulf Cooperation Council distributor networks, European premium specialists, and Asian manufacturing scale players. Three archetypes dominate: legacy bicycle manufacturers with established regional service infrastructure, desert-climate engineering specialists with thermal management capabilities, and logistics-focused aggregators with fleet procurement scale. Competitive moves concentrate on SASO certification compliance acceleration and after-sales thermal specialist training programs.
Within the legacy manufacturer tier, Giant Manufacturing Co. Ltd and Trek Bicycle Corporation occupy positions defined by showroom presence and service infrastructure density. Eveons Mobility Systems LLC exemplifies the desert-climate engineering archetype, with technical positioning centered on battery thermal management for extreme ambient temperature operation. These three companies represent the competitive vectors of distribution scale, premium service capability, and climate-hardened product engineering respectively.
| Leading Market Players |
|---|
| Accell Group |
| ONE Moto |
| Giant Manufacturing Co. Ltd |
| myStromer AG |
| Eveons Mobility Systems LLC |
| Trek Bicycle Corporation |
| Specialized Bicycle Components, Inc |
| Vego Group |
| TRINX Bikes |
| Others |
Value Network & Pricing Analysis
Eight-to-twelve-week SASO recertification delays for battery-management system redesigns compress inventory turns and concentrate pricing power among importers with pre-certified technical capabilities. Fleet procurement managers absorbing these lead-time premiums through capital expenditure budgets create tiered procurement access where compliance velocity determines contract eligibility.
Pricing Analysis
Volume-discount tiering structures separate logistics aggregators securing bulk chassis procurement from individual consumers purchasing through retail channels. Pricing stratifies across SASO-certified premium configurations with active thermal management, mid-range fleet specifications balancing compliance with cost, and economy tiers facing availability gaps during recertification windows. Cost compression in the mid-range fleet tier intensifies as logistics aggregators unbundle hardware from maintenance contracts. Individual commuters exhibit highest price sensitivity to battery replacement cycles, while real-estate developers bundling charging infrastructure into commercial amenities demonstrate lowest sensitivity to upfront premiums.
Supply Chain Analysis
China and South Korea anchor cathode precursor processing and battery cell manufacturing for Saudi-bound e-bike imports. Lithium carbonate and nickel sulfate feedstock dependencies draw from Chilean and Indonesian extraction operations, exposing importers to commodity price volatility and currency mismatch risks. Single-source vulnerability concentrates in East Asian battery-management system chipset fabrication. Distribution runs through Gulf Cooperation Council distributor networks with Riyadh and Jeddah logistics hubs serving last-mile fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery lifecycle service contracts are expanding faster than hardware unit sales as fleet operators unbundle thermal-management maintenance from capital procurement. This service-attach dynamic restructures vendor economics toward recurring technical revenue streams.
For Market Incumbents: Fortify after-sales thermal specialist training programs to capture unbundled battery lifecycle service contracts from logistics aggregators. Deepen backward integration into desert-climate battery pack assembly within Saudi Arabia to compress SASO recertification timelines and defend margin position against emerging climate-engineering specialists.
For New Entrants and Emerging Players: SASO certification fast-track partnerships with established testing laboratories open procurement channels during incumbent recertification gaps. White-space concentration sits in ruggedized desert-tourism rental configurations for Red Sea coastal operators, with go-to-market execution through hospitality procurement networks rather than traditional bicycle retail.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-integrated mobility play because giga-project master plans mandate micromobility access corridors as binding planning conditions. Acquisition targets should profile desert-climate engineering specialists with proprietary thermal management IP. The signal to watch is Public Investment Fund tender releases specifying car-free mobility system requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Fast-Track Investment | Accelerated customs clearance captures fleet procurement windows during competitor recertification delays. |
| Desert-Climate Battery Assembly Localization | In-country pack assembly compresses lead times and satisfies emerging local content preferences in giga-project tenders. |
| Thermal Specialist Training Academy | Standalone technical service capabilities capture unbundled maintenance contracts from logistics aggregators. |
| Solar-Integrated Charging Infrastructure Partnership | Saudi Energy Efficiency Center building code compliance opens bundled real-estate developer procurement channels. |
| Ruggedized Desert-Tourism Product Line | Red Sea coastal operator demand for sand and rock terrain configurations remains underserved by urban-optimized imports. |
Research Methodology
Cross-validation between fleet procurement manager interviews and customs clearance data anchors the qualitative findings on SASO certification friction. Primary fieldwork engaged logistics aggregator sourcing directors, thermal management engineering leads, Saudi distributor network managers, and real-estate developer sustainability officers. Secondary validation drew from SASO technical regulation filings, Saudi Traffic Department vehicle classification circulars, Public Investment Fund giga-project tender documentation, and Gulf Cooperation Council trade flow databases. Bottom-up unit shipment estimates triangulate against top-down fleet procurement budget disclosures.
Sensitivity analysis around battery replacement cycle assumptions and thermal degradation curves shapes volume projections across the modeling period. Segmentation dimensions include product type, battery chemistry, application, and price tier, with regional clusters defined by municipal infrastructure investment intensity. CAGRs derive from logistic curve adoption modeling calibrated to fleet electrification mandate compliance deadlines. Forecast inputs incorporate lithium carbonate price volatility bands and SASO recertification timeline distributions.
Underlying assumptions cover continued municipal zero-emission vehicle quota enforcement and stable lithium supply chain access, with deviation risk concentrated in throttle-control regulatory reclassification and giga-project timeline acceleration. Recalibration cycles align with material shifts in SASO technical regulation amendments and Public Investment Fund tender release patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Automotive Electric Vehicle Power System Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Russia Electric Cars Market