
 Gate Driver IC Market | 2026-2036
Gate Driver IC Market Size, Share, and Industry Trends Forecast 2026-2036
Gate Driver IC Market Intelligence
The shift toward wide-bandgap semiconductors like Gallium Nitride (GaN) and Silicon Carbide (SiC) is reshaping design requirements for gate driver ICs. Infineon Technologies leverages its deep expertise in power semiconductors to offer integrated solutions. Texas Instruments competes on the breadth of its analog and mixed-signal portfolio. STMicroelectronics differentiates through its focus on automotive and industrial-grade components meeting stringent reliability standards.
A gate driver IC is a power amplifier that accepts a low-power input from a controller and produces a high-current drive for a power transistor's gate. These components are critical for rapidly switching power MOSFETs or IGBTs, controlling switching losses via specific slew rates. While silicon-based MOSFET drivers remain the volume standard, GaN transistor drivers represent the fastest-growing technology segment. Demand from renewable energy systems, particularly for solar inverters and wind turbine converters, is a primary application driver.
Regulatory frameworks such as the EU’s RoHS directive on hazardous substances and energy efficiency standards set by the US EPA influence material composition and performance benchmarks. In China, GB standards for electronics and electric vehicles enforce strict safety and reliability criteria. These regulations collectively push for higher efficiency and more durable component designs. The primary strategic decision for manufacturers involves balancing investment in next-generation GaN and SiC technologies against optimizing existing silicon-based product lines.
Market Dynamics
The fundamental transition toward wide-bandgap semiconductors, specifically Gallium Nitride and Silicon Carbide, is the central force redefining performance expectations and design parameters for gate driver ICs, compelling a shift away from legacy silicon-based architectures.
Growth Catalysts
- Electric Vehicle Proliferation:Government mandates and consumer demand for electric vehicles create a massive need for efficient powertrain inverters, battery management systems, and onboard chargers, all of which rely on advanced gate driver ICs for power control.
- Renewable Energy Expansion:National clean energy targets, particularly in Europe and China, drive investment in solar inverters and wind turbine converters, which require high-performance gate drivers to maximize energy conversion efficiency and grid stability.
- Industrial Efficiency Standards:The push for Industry 4.0 and stricter energy consumption rules for electric motors and factory equipment necessitates the use of sophisticated gate drivers for precise control in variable-speed drives and robotic systems.
Market Restraints
- WBG Semiconductor Cost Premium:The higher material and fabrication costs associated with Gallium Nitride and Silicon Carbide substrates compared to traditional silicon create a significant price barrier for cost-sensitive applications, slowing mass-market adoption.
- System-Level Design Complexity:Migrating from silicon MOSFETs to fast-switching GaN or SiC transistors requires significant redesign of circuit layouts, thermal management, and control algorithms, posing a technical hurdle for engineering teams.
- Concentrated Substrate Supply:The supply chain for high-quality SiC and GaN wafers is concentrated among a few key suppliers, primarily in Asia, creating potential bottlenecks and price volatility for gate driver IC manufacturers globally.
Strategic Opportunities
- Integrated Power Stages:Developing modules that co-package the gate driver IC with GaN or SiC power transistors offers a path to higher performance, reduced system complexity, and a smaller footprint, appealing to designers in space-constrained applications.
- High-Frequency Power Conversion:Untapped demand exists in next-generation data center power supplies, 5G telecommunications equipment, and advanced medical imaging, all of which require compact, high-frequency power conversion enabled by advanced gate drivers.
- Grid-Scale Energy Storage:Grid modernization projects and the build-out of battery energy storage systems (BESS) create new applications for high-power gate drivers capable of managing bidirectional power flow with high reliability and efficiency.
Industry Challenges
- Advanced Thermal Management:The increased power density and faster switching speeds of GaN and SiC devices generate localized heat that is challenging to dissipate with conventional cooling methods, requiring new packaging and heatsink technologies.
- Reliability and Qualification Timelines:Establishing long-term reliability data for new GaN and SiC-based drivers to meet the stringent lifetime requirements of the automotive and industrial sectors is a time-consuming and capital-intensive process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gate Driver IC Market |
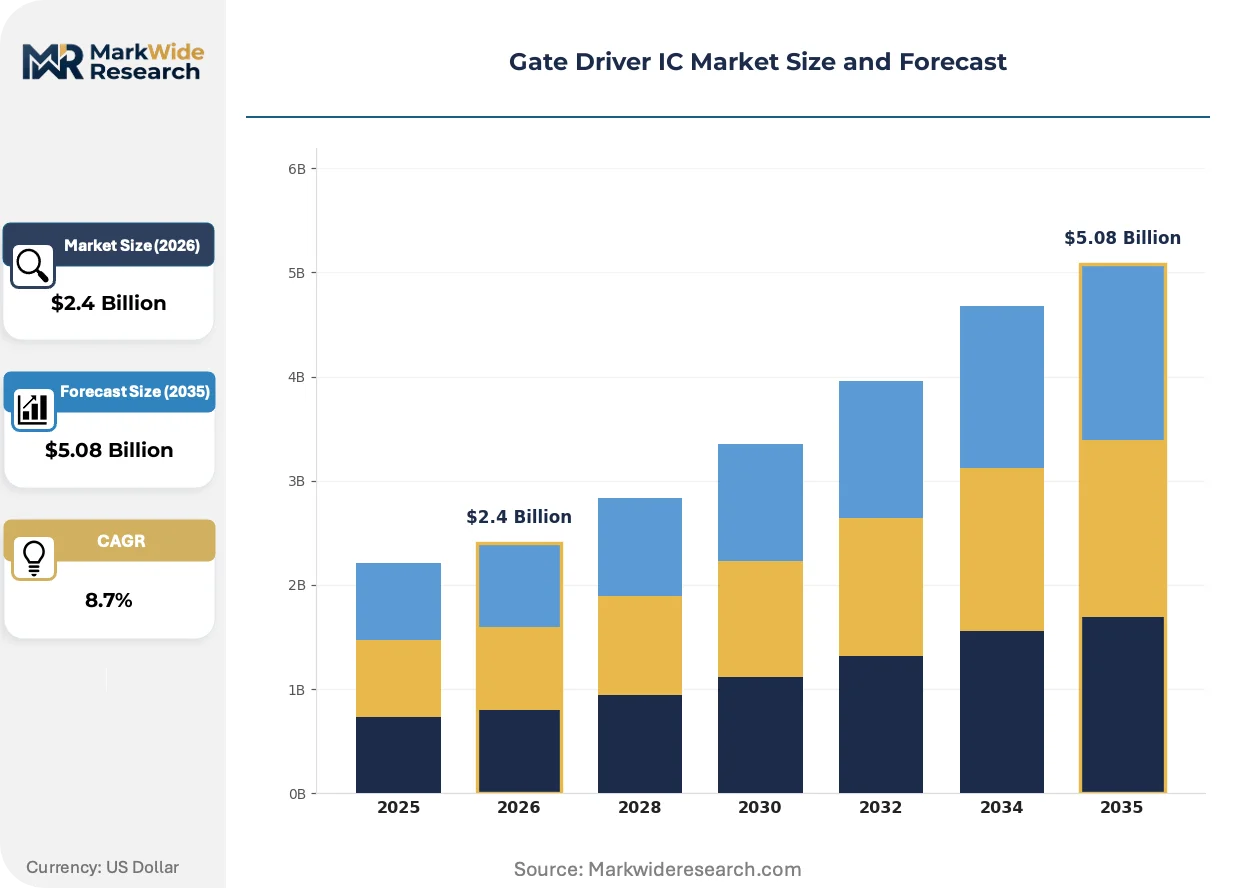
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Side Driver, Low-Side Driver, Half-Bridge Driver, Bootstrap Driver, Level-Shifting Driver Technology: Silicon MOSFET, GaN Transistor, IGBT, Bipolar Junction Transistor, CMOS Application: Electric Motor Control, Renewable Energy Systems, Consumer Appliances, Power Supply Units, Lighting Control End User: Consumer Electronics Manufacturers, Industrial Automation Firms, Tier-1 Automotive Suppliers, Telecommunication Equipment Makers, Aerospace Companies |
| Companies Covered | Infineon Technologies, Texas Instruments, STMicroelectronics, NXP Semiconductors, Renesas Electronics, ON Semiconductor, Toshiba, ROHM Semiconductor, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gate Driver IC Market Strategic Shifts & Innovations
Component-level innovation is converging with system-level design pressures, driven by stringent efficiency regulations and the need for faster development cycles. This dynamic alters how gate driver ICs are designed, selected, and integrated into final products.
Integrated gate drivers combine core driver functionality with on-chip protection features like over-current sensing, under-voltage lockout, and thermal shutdown. The automotive and industrial sectors are rapidly adopting these devices to improve system reliability and simplify safety certifications. This integration is hybridizing the discrete component model with a system-on-chip approach, reducing board space and overall component count in complex power systems.
The European Union's Green Deal establishes ambitious targets for carbon neutrality, directly influencing component selection for all power systems. This regulatory pressure forces engineers to minimize switching and conduction losses in applications from home appliances to factory motors. The industrial automation sector is most affected, responding by specifying higher-performance gate drivers that enable more efficient power conversion topologies and reduce overall energy consumption.
Design cycles are compressing as system engineers increasingly utilize reference designs and comprehensive evaluation kits from IC manufacturers. This behavior moves the component selection process much earlier in the development phase, displacing traditional, siloed procurement with a solutions-based evaluation. The trend is most visible in the competitive electric vehicle and renewable energy inverter markets, where speed-to-market is a critical commercial advantage.
Gate Driver IC Market Segmentation
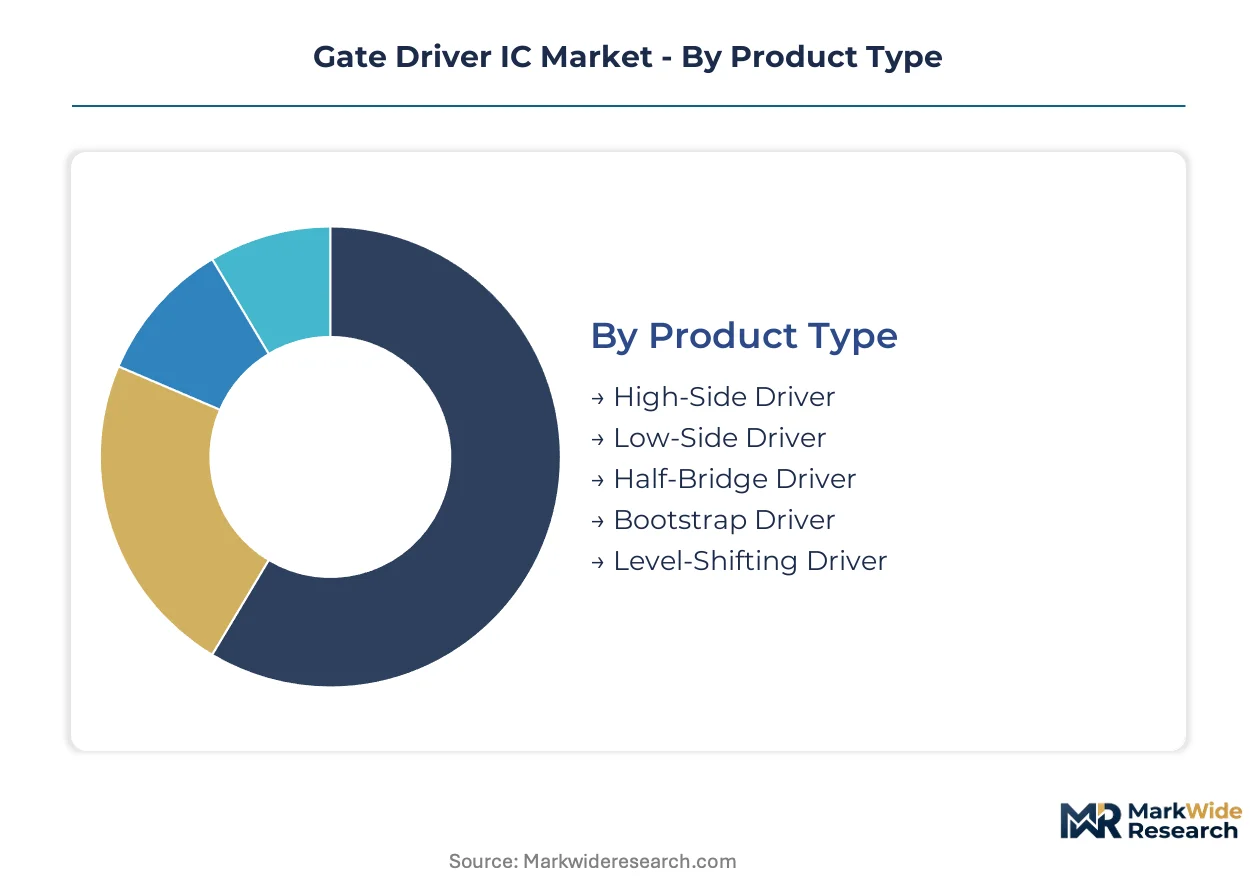
The Gate Driver IC market structure reflects diverse technical requirements and application-specific demands for power semiconductor control. Understanding these segments clarifies the varying performance needs and cost sensitivities across different end-use sectors. Manufacturers tailor gate driver IC designs to optimize for specific voltage levels, switching speeds, and integration complexities inherent in each segment.
Product Type:
The intensity of after-sales service requirements often correlates with the complexity and mission-critical nature of the gate driver product type, influencing design choices and qualification processes.
- Half-Bridge Driver:This product type integrates two gate drivers to control a pair of power switches in a half-bridge configuration, essential for bidirectional power flow. Demand concentrates in electric vehicle inverters and renewable energy systems, driven by the need for high efficiency and compact power conversion.
- High-Side Driver:High-side drivers manage power switches connected to the high-voltage rail, necessitating robust isolation and level-shifting capabilities. Industrial motor control and automotive powertrain systems require these devices to meet stringent safety standards and ensure reliable operation.
- Low-Side Driver:Low-side drivers control ground-referenced power switches, offering simpler design and cost-effectiveness for various applications.
- Bootstrap Driver:Bootstrap drivers provide a cost-effective method to generate the necessary gate voltage for high-side switches without an isolated power supply.
- Level-Shifting Driver:These drivers translate control signals from a low-voltage domain to a high-voltage power stage, crucial for mixed-signal power systems.
High-Side Driver holds the largest share; momentum sits with Half-Bridge Driver.
Technology:
The cost tiering for gate driver IC technologies is primarily dictated by material science and fabrication complexity, with wide-bandgap solutions commanding a premium over established silicon.
- GaN Transistor:Gate drivers for Gallium Nitride (GaN) transistors leverage wide-bandgap properties for extremely fast switching speeds and high-frequency operation. Electric vehicles and data center power supplies increasingly demand GaN drivers for their superior power density and efficiency.
- Silicon MOSFET:Silicon MOSFET-based gate drivers represent the established volume standard, offering a cost-effective solution for a broad range of power management applications. Consumer electronics and industrial power supplies rely on silicon MOSFET drivers for their proven reliability and mature supply chain.
- IGBT:Insulated Gate Bipolar Transistor (IGBT) drivers are designed for high-voltage, high-current applications, commonly found in industrial motor drives and renewable energy converters.
- CMOS:Complementary Metal-Oxide-Semiconductor (CMOS) technology provides low power consumption and high integration density for gate driver ICs, suitable for various digital control interfaces.
- Bipolar Junction Transistor:Bipolar Junction Transistor (BJT) drivers offer a robust and cost-effective solution for lower-frequency, lower-power switching applications.
The supply chain for Silicon MOSFET drivers is highly diversified, while GaN Transistor drivers face concentration among a few specialized wafer manufacturers.
Application:
The application scope for gate driver ICs ranges from high-power industrial systems to compact consumer devices, each presenting unique performance and integration challenges.
- Electric Motor Control:Gate driver ICs are fundamental for precise control of electric motors in industrial automation, robotics, and electric vehicles, enabling variable speed drives and energy savings. The EU Green Deal mandates stricter energy efficiency, driving demand for advanced motor control solutions.
- Renewable Energy Systems:Solar inverters and wind turbine converters rely on high-performance gate drivers to maximize power conversion efficiency and ensure grid stability. National clean energy targets in Europe and China are primary drivers for this application segment.
- Power Supply Units:Gate drivers enable efficient power conversion in various power supply units, from consumer electronics adapters to server power supplies.
- Consumer Appliances:Gate drivers optimize power management in household appliances, contributing to energy efficiency and compact designs.
- Lighting Control:Gate drivers facilitate efficient and precise control of LED lighting systems, supporting dimming functions and power factor correction.
Electric Motor Control accounts for substantial volume; Renewable Energy Systems demonstrate the steepest expansion trajectory.
End User:
The customer type for gate driver ICs spans across industries with varying demands for reliability, volume, and customization, from mass-market consumer goods to highly specialized aerospace components.
- Tier-1 Automotive Suppliers:These firms integrate gate driver ICs into critical automotive systems like EV powertrains, battery management, and advanced driver-assistance systems (ADAS). Stringent automotive reliability standards and long product lifecycles define component selection for these suppliers.
- Industrial Automation Firms:Industrial automation companies utilize gate drivers for factory equipment, robotic systems, and variable frequency drives, where precision and long-term durability are paramount. The push for Industry 4.0 initiatives necessitates high-performance and robust gate driver solutions.
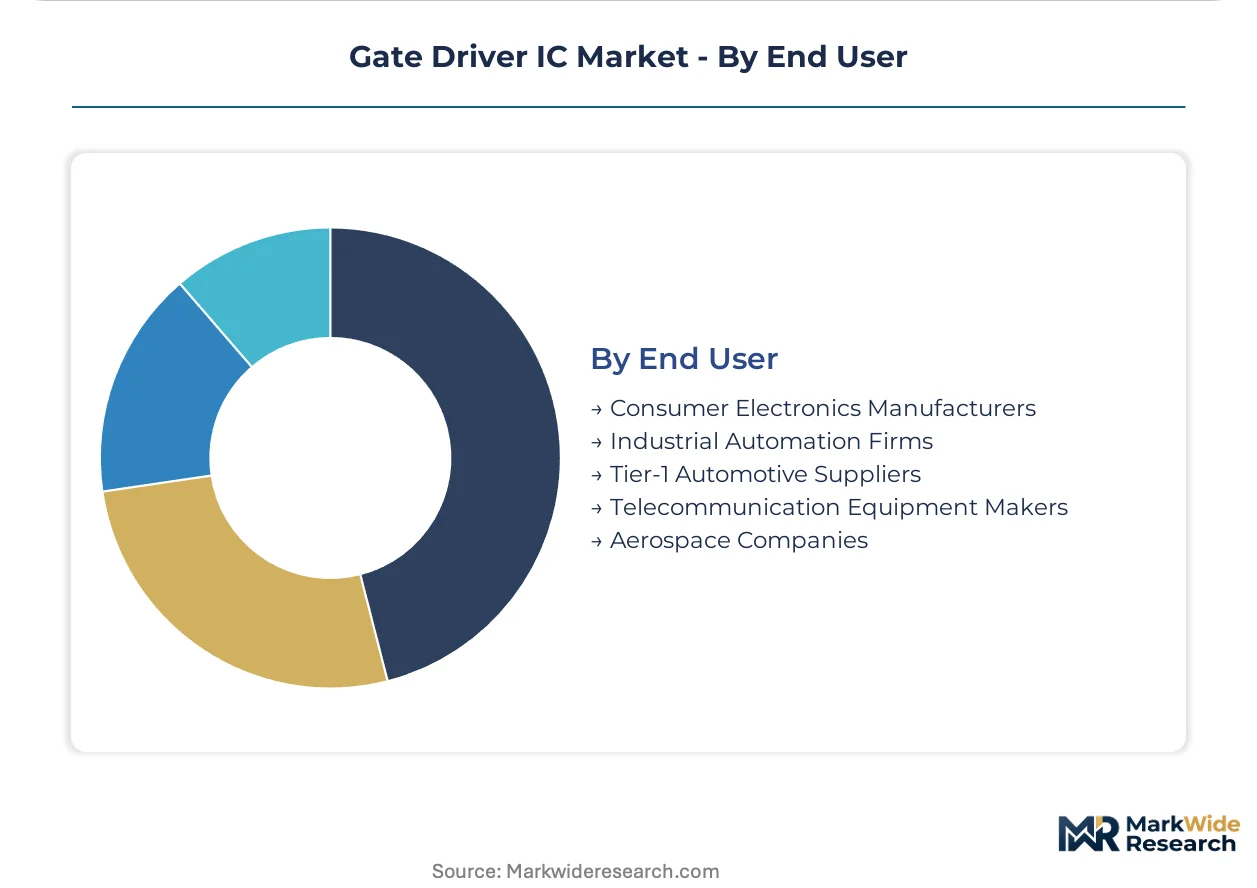
- Consumer Electronics Manufacturers:These manufacturers integrate gate drivers into devices such as smartphones, laptops, and home entertainment systems, prioritizing miniaturization and cost-efficiency.
- Telecommunication Equipment Makers:Gate drivers support power management in 5G infrastructure, base stations, and data communication equipment, requiring high-frequency operation and reliability.
- Aerospace Companies:Aerospace applications demand gate drivers with extreme reliability, radiation hardness, and extended temperature range capabilities for critical flight systems.
Industrial Automation Firms represent a mature market segment, while Tier-1 Automotive Suppliers exhibit significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Key buyer archetypes for gate driver ICs, particularly in electric vehicles, industrial automation, and renewable energy systems, are concentrated in specific global regions. These areas drive demand for high-performance power management solutions. Strategic investments align with these regional concentrations.
China
Electric vehicle proliferation and renewable energy expansion propel gate driver IC demand in China. GB standards for electronics and electric vehicles enforce strict safety and reliability criteria. The Yangtze River Delta region concentrates EV manufacturing and power electronics development.
Germany
Industrial automation and advanced automotive manufacturing drive demand for sophisticated gate driver ICs in Germany. The EU Green Deal mandates higher energy efficiency, directly influencing component selection for power systems. Bavaria serves as a hub for automotive and industrial technology development.
United States
Data center power supplies and electric vehicle powertrain inverters create substantial demand in the United States. The US EPA influences performance benchmarks through energy efficiency standards. Silicon Valley remains a focal point for power electronics R&D and technological innovation.
Japan
Automotive electronics and industrial robotics applications require high-frequency gate drivers across Japan. METI initiatives support advanced manufacturing and energy conservation within industrial sectors. The Kansai region concentrates power electronics and industrial equipment manufacturing.
South Korea
Battery management systems for electric vehicles and advanced consumer electronics drive gate driver IC demand in South Korea. Government support for EV infrastructure and energy efficiency targets shapes component integration. The Seoul Capital Area is a key center for semiconductor and automotive electronics.
Gate Driver IC Market Key Industry Players
Channel-controlling players compete with product-specialist players, defining the competitive landscape for gate driver ICs. The market exhibits a tiered structure, with established semiconductor giants alongside focused innovators. Strategic archetypes include integrated solution providers offering complete power management ecosystems, specialized wide-bandgap driver developers, and cost-optimized silicon driver suppliers serving high-volume applications. Companies primarily engage in portfolio diversification to address diverse application needs and form strategic partnerships to accelerate technology adoption.
Within the integrated solutions archetype, Infineon Technologies and Texas Instruments exemplify broad portfolio strategies, leveraging deep expertise across power semiconductors and analog mixed-signal domains. Infineon, a German-based firm, focuses on integrated solutions while Texas Instruments, a US-based entity, emphasizes its extensive analog and mixed-signal portfolio. STMicroelectronics, a European-based semiconductor firm, occupies a position focused on automotive and industrial-grade components, meeting stringent reliability standards. These firms collectively anchor market development by providing comprehensive gate driver IC solutions that address evolving performance and reliability requirements across various end-use sectors.
| Leading Market Players |
|---|
| Infineon Technologies |
| Texas Instruments |
| STMicroelectronics |
| NXP Semiconductors |
| Renesas Electronics |
| ON Semiconductor |
| Toshiba |
| ROHM Semiconductor |
| Mitsubishi Electric |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's expanding manufacturing capacity for electric vehicles and power electronics directly influences downstream gate driver IC pricing power. This concentration creates specific cost advantages for local integrators, impacting global competitive dynamics.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material costs for wide-bandgap substrates, define pricing for specialized gate driver ICs. Price differentiation stems from the integration of GaN or SiC technologies and adherence to stringent automotive or industrial reliability standards. Pricing pressure for silicon-based drivers intensifies due to commoditization and high volume production. Industrial automation firms and Tier-1 automotive suppliers exhibit lower price sensitivity, prioritizing performance and long-term reliability over initial component cost.
Supply Chain Analysis
TSMC and Samsung Foundry, alongside specialized SiC/GaN wafer manufacturers in Japan and Europe, anchor the fabrication capacity for advanced gate driver ICs. The supply chain draws from high-purity silicon and specialized Gallium Nitride or Silicon Carbide wafers as critical raw materials. A structural risk exists in the concentrated supply of high-quality WBG substrates, creating potential bottlenecks and price volatility. Distribution runs through direct sales channels to large OEMs and a network of specialized distributors serving smaller industrial and consumer electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is framed by a significant buyer-power shift, driven by the increasing consolidation among Tier-1 automotive suppliers and large industrial automation firms. These dominant buyers exert substantial influence over component specifications and pricing.
For Market Incumbents: Insulate core silicon product lines through continuous process optimization and cost reduction to counter commoditization. Invest aggressively in next-generation GaN and SiC driver development, focusing on integrated power stages to meet evolving efficiency demands. A primary threat stems from specialized wide-bandgap startups, necessitating strategic R&D in advanced thermal management and packaging. Leveraging existing customer relationships and certification investments provides a critical lever against new entrants.
For New Entrants and Emerging Players: Establish a beachhead in high-frequency power conversion applications, such as data center power supplies and 5G telecommunications equipment. These segments offer white-space opportunities due to their unique performance requirements and lower historical barrier to entry compared to automotive. The most penetrable segment for new players is specialized industrial power supplies requiring compact, high-efficiency solutions. A go-to-market angle focusing on reference designs and comprehensive evaluation kits simplifies adoption for system engineers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firms with established intellectual property in wide-bandgap materials and integrated driver solutions. The long-term viability of the gate driver IC market remains strong, driven by global electrification and efficiency mandates. Acquisition targets should include specialized GaN or SiC driver developers and companies with advanced packaging technologies. The commercialization milestones for next-generation WBG materials, particularly in automotive and renewable energy sectors, serve as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Integrated Power Stages | Offers higher performance and reduced system complexity for electric vehicle powertrain designers. |
| Expand GaN/SiC Wafer Sourcing | Mitigates supply chain risks and ensures material availability for next-generation products. |
| Strengthen Automotive Qualification | Meets stringent reliability standards for Tier-1 automotive suppliers and accelerates market penetration. |
| Develop Advanced Thermal Management | Addresses increased power density challenges in high-frequency power conversion designs. |
| Form Strategic Partnerships with OEMs | Secures long-term design wins and ensures product alignment with evolving application needs. |
Research Approach
Operator-level perspectives from power electronics design engineers, procurement managers at Tier-1 automotive suppliers, R&D directors at semiconductor firms, and regulatory compliance officers anchored the qualitative base. This primary research was triangulated with extensive secondary data sources, including company annual reports, patent databases, government energy reports from the EU and US EPA, and industry association publications. The approach utilized both bottom-up and top-down data validation for robust market sizing.
Scenario-bracketing framing informed the quantitative modeling, establishing plausible market growth trajectories across the analysis window. The analytical framework incorporated segmentation dimensions such as product type (Half-Bridge, High-Side), technology (GaN, SiC, Silicon), application (EV, Renewable Energy, Industrial Motor Control), and end-user segments. Compound Annual Growth Rates were derived from historical trends and projected adoption rates, with key industry-specific forecast inputs including wide-bandgap material cost trajectories and electric vehicle production volumes.
Stress conditions across geopolitical trade policies and unexpected shifts in EV adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and regulatory stability within the power electronics sector. Quarterly review of WBG material costs and EV production rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Mixed-Signal Microcontroller Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
APAC Analog IC Market