
 Integrated Circuit Market | 2026-2036
Integrated Circuit Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Circuit Market Analysis
Automotive electrification is realigning demand patterns across the Integrated Circuit landscape. NVIDIA Corporation leverages its GPU architecture leadership to dominate AI training and autonomous vehicle compute platforms. Samsung Electronics sustains vertical integration from memory fabrication to system-level packaging, anchoring its position across multiple product tiers. TSMC competes through pure-play foundry scale, controlling access to sub-3nm process nodes that define performance leadership in digital ICs.
An integrated circuit constitutes a miniaturized electronic circuit comprising semiconductor devices and passive components fabricated on a single substrate, typically silicon, with feature sizes now reaching atomic-scale dimensions below 3 nanometers in leading-edge production. These devices perform computation, signal processing, memory storage, and power management functions essential to virtually all electronic systems. Digital ICs command the largest revenue pool, driven by data center processors and smartphone SoCs, while mixed-signal ICs capture expanding margin pools in automotive sensor interfaces and IoT edge nodes. Analog ICs maintain structural importance in power management, though growth velocity trails digital categories.
Export control frameworks administered by the US Bureau of Industry and Security, alongside China's GB standards for domestic semiconductor procurement and the EU Chips Act funding criteria, collectively reshape where capital equipment ships and which fabs achieve qualified supplier status. REACH and RoHS compliance in Europe further constrain material selection and packaging chemistry across the supply base. Stakeholders must monitor how jurisdictional fragmentation in technology access rules redistributes design activity and manufacturing investment across competing regional clusters.
Market Dynamics
Automotive electrification and AI compute workloads are compressing development cycles while concentrating procurement power among hyperscale data center operators and tier-one automotive suppliers.
Growth Catalysts
- EU Chips Act capital allocation:Subsidy frameworks in Germany, France, and Italy are attracting EUV lithography equipment and advanced packaging investments that previously concentrated in East Asia.
- Advanced driver-assistance systems:Automotive OEMs in Japan and South Korea are qualifying domestic foundry capacity for sensor fusion processors and power management ICs.
- Silicon carbide substrate availability:Power semiconductor manufacturers are securing long-term supply agreements with substrate growers to support 800V EV platform ramps.
Market Restraints
- Neon gas supply concentration:Ukraine and Russian suppliers historically provided 50-60% of semiconductor-grade neon, creating input cost volatility since 2022.
- Leading-edge foundry duopoly:Sub-3nm logic production depends on equipment from ASML that ships to only Taiwan and South Korea facilities.
- Export control friction:US Bureau of Industry and Security licensing delays for China-bound manufacturing equipment extend fab construction timelines by 12-18 months.
Strategic Opportunities
- India PLI scheme for semiconductors:Central government incentives covering 50% of project cost are drawing display driver IC and mature-node logic investments.
- Chiplets and heterogeneous integration:Die-to-die interconnect standards are enabling fabless designers to mix process nodes within single packages.
- Edge AI inference acceleration:Industrial automation and smart city deployments in Vietnam and Indonesia are creating demand for low-power neural processing units.
Industry Challenges
- Process engineer scarcity:Atomic-layer deposition and EUV photoresist expertise commands 40-60% salary premiums as foundries compete for identical talent pools.
- Legacy node equipment sourcing:200mm wafer fab capacity expansion is constrained by second-hand tool availability and refurbishment lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Circuit Market |
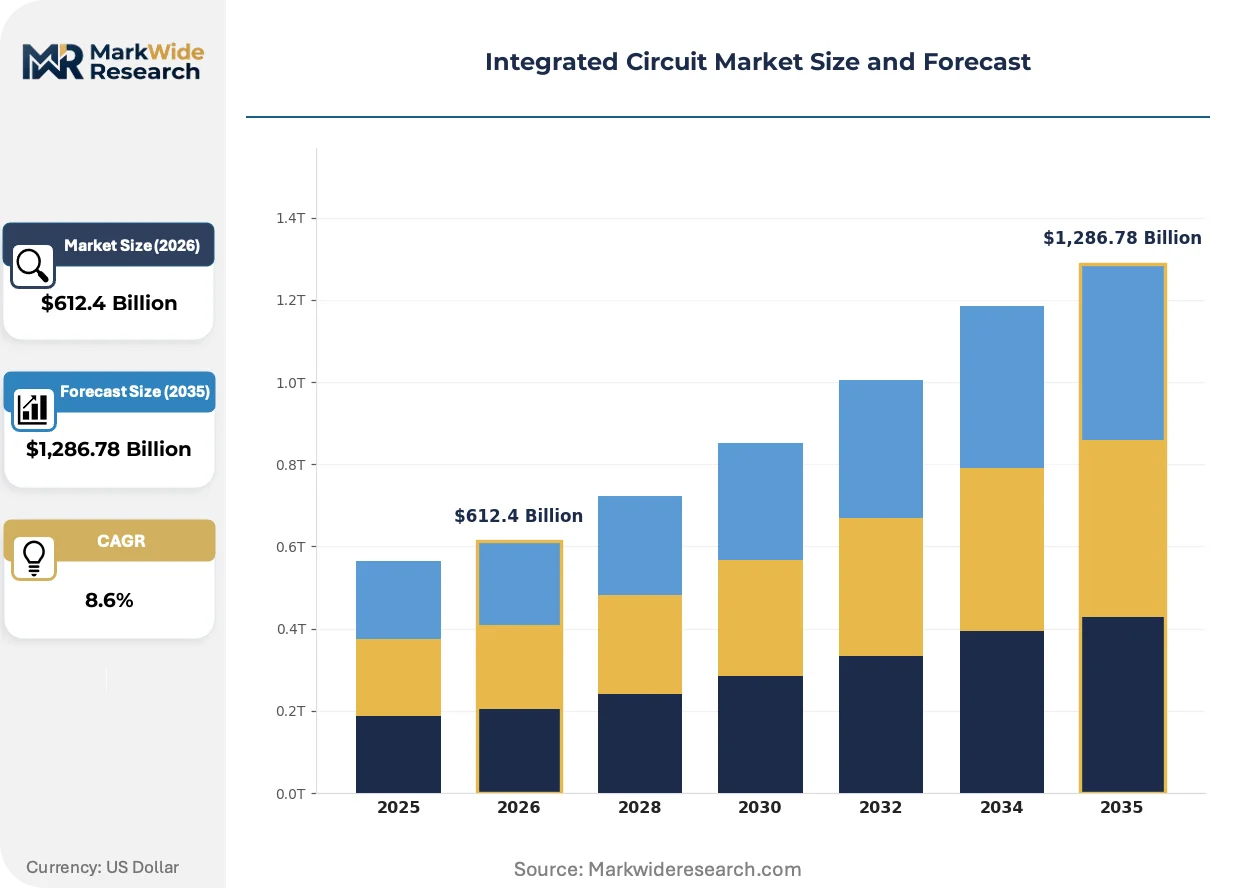
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,286.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-Signal ICs, Embedded ICs Technology: CMOS, Bipolar, BiCMOS, GaAs End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Application: Wearable Devices, Smart Home, IoT Solutions, Computing |
| Companies Covered | Samsung Electronics, Qualcomm Incorporated, NVIDIA Corporation, SK hynix, Advanced Micro Devices (AMD), Taiwan Semiconductor Manufacturing Company (TSMC), Intel Corporation, Micron Technology, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Circuit Market Emerging Trajectories
Process-node scaling economics are forcing architectural innovation at the package level rather than the transistor level, redistributing value capture across the supply chain.
Gate-all-around transistor architecture is integrating nanosheet geometries at the 2nm node to maintain electrostatic control as planar scaling exhausts. Samsung and TSMC are qualifying these processes for high-performance computing and smartphone SoC production. The technology is integrating memory bandwidth and logic density gains that previously required die shrinks.
REACH substance restrictions are compelling solder alloy reformulations and halogen-free substrate materials across European-bound automotive modules. ECHA candidate list updates are accelerating substitution timelines for legacy flame retardants in IC packaging. Module suppliers in Germany are redesigning thermal interface materials to maintain conductivity under revised compliance thresholds.
Hyperscale buyers are consolidating silicon procurement through direct foundry relationships, bypassing traditional distribution for advanced node wafers. Cloud service providers in the United States are negotiating multi-year capacity reservations that lock in allocation before fab construction completes. This concentration is visible in Arizona and Texas, where data center buildouts are synchronizing with announced domestic foundry ramps.
Integrated Circuit Market Segmentation
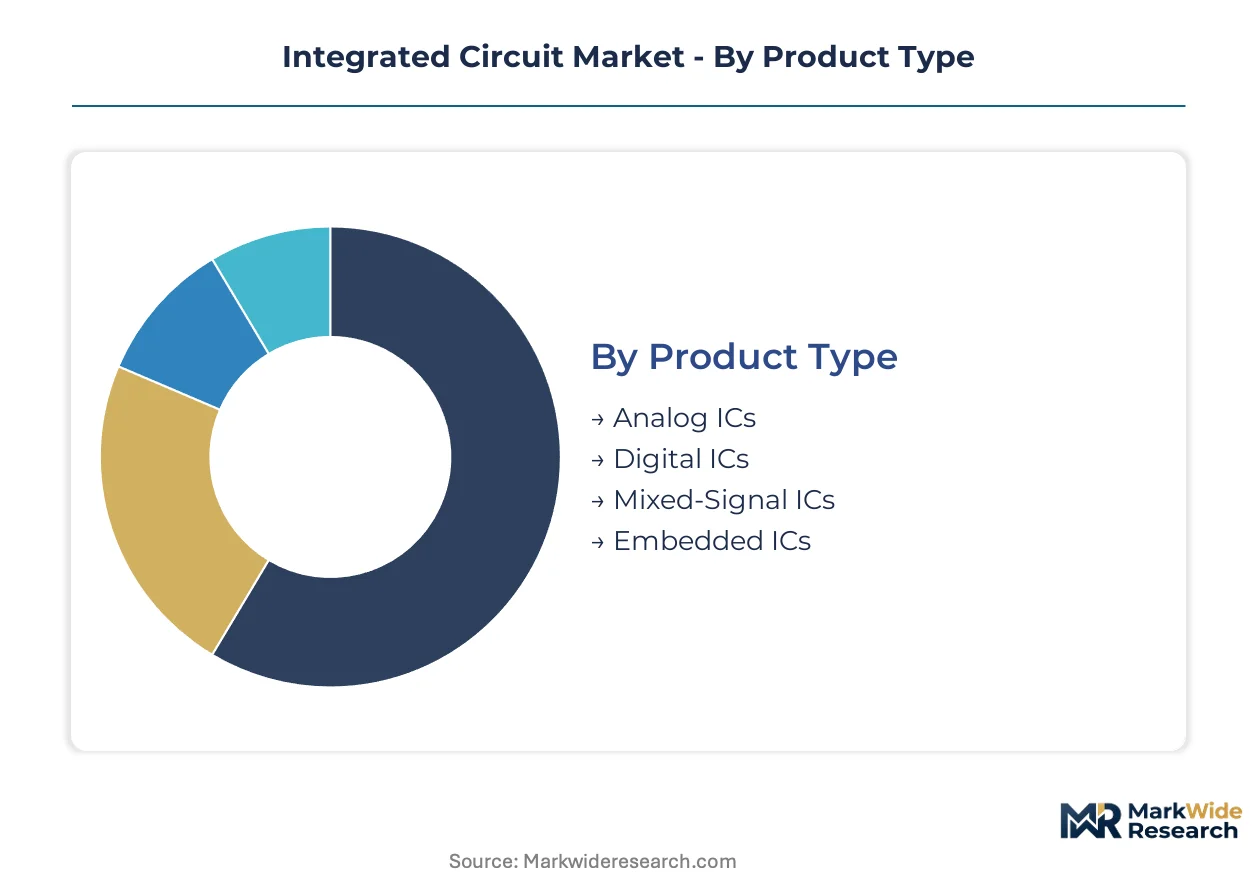
Integrated circuit procurement decisions pivot on performance thresholds, power budgets, and qualification timelines that vary sharply across end-use environments. Semiconductor buyers segment supply alternatives by functional architecture, fabrication technology, and deployment context to match die-level capabilities with system-level constraints.
Product Type:
Cost tier determines foundry selection and margin structure for each product category.
- Digital ICs:Logic gates, memory arrays, and microprocessors fabricated at nodes ranging from mature 28nm to leading-edge sub-3nm. Data center operators in the United States and smartphone OEMs in South Korea concentrate procurement here, with TSMC and Samsung commanding allocation queues that extend 18-24 months for advanced nodes.
- Analog ICs:Operational amplifiers, voltage regulators, and data converters operating across continuous signal ranges rather than discrete states. Texas and Arizona fabs specialize in these devices for automotive power management and industrial sensor conditioning, where noise immunity and temperature stability outweigh raw transistor density.
- Mixed-Signal ICs:ADCs and DACs bridging analog sensor inputs with digital processing cores. Foundries in Taiwan and Japan qualify these for ADAS radar modules and IoT edge nodes.
- Embedded ICs:Microcontrollers with integrated memory and peripherals on single die. Mature-node capacity in Malaysia and Vietnam serves white-goods and metering applications.
Digital ICs lead on scale; Mixed-Signal ICs lead on momentum.
Technology:
Process maturity curves and capital intensity separate technologies into distinct supplier ecosystems.
- CMOS:Complementary metal-oxide-semiconductor dominates volume production through scalable power-performance tradeoffs. Taiwan and South Korea facilities push this technology to atomic-scale dimensions for AI accelerators and mobile SoCs.
- Bipolar:Junction transistor architecture delivering higher current drive and linearity for RF power amplifiers. Discrete device manufacturers in Japan and Germany maintain specialty lines for radar and broadcast equipment.
- BiCMOS:Hybrid process combining CMOS density with bipolar speed for precision analog-digital interfaces. Automotive radar suppliers in France and Italy qualify these processes for 77GHz sensor modules.
- GaAs:Gallium arsenide substrates enabling millimeter-wave and optoelectronic applications beyond silicon limits. Defense and satellite communications procurement in the United States and Israel sustains this technology.
CMOS captures the widest deployment base; GaAs commands the steepest expansion trajectory in RF applications.
End User:
Qualification rigor and volume predictability shape how fabs prioritize capacity allocation across customer types.
- Automotive:AEC-Q100 qualification and ISO 26262 functional safety mandates govern IC selection for powertrain and chassis electronics. German and Japanese OEMs are qualifying domestic foundry capacity to reduce dependency on Taiwan supply chains.
- Consumer Electronics:Annual volume ramps and aggressive cost-down schedules characterize smartphone and wearable procurement. South Korea and China device assemblers negotiate directly with foundries for leading-edge wafer starts.
- Industrial Automation:Extended product lifecycles and harsh-environment reliability requirements favor mature-node supply continuity. Siemens and Schneider Electric facilities in Germany and France specify industrial-grade temperature ranges.
- Telecommunications:5G baseband processors and optical transceivers demand specialized RF and mixed-signal capabilities. Ericsson in Sweden and Nokia in Finland source through European packaging houses with REACH-compliant materials.
Consumer Electronics leads on wafer volume; Automotive leads on qualification-driven pricing power.
Application:
Form factor constraints and connectivity requirements determine package selection and die stacking architecture.
- Computing:CPUs, GPUs, and AI accelerators in data centers and personal devices. Hyperscale buyers in Virginia and Oregon reserve multi-year foundry capacity for training clusters.
- IoT Solutions:Low-power wireless microcontrollers for asset tracking and environmental monitoring. Dutch and Swiss industrial sensor vendors specify sub-1mW sleep states.
- Smart Home:Voice processors and connectivity hubs integrating multiple wireless protocols. Amazon and Google hardware teams in California and Washington specify edge inference capabilities.
- Wearable Devices:Miniaturized SoCs with integrated biosensors and Bluetooth Low Energy. Apple and Samsung design teams in California and Seoul drive die-shrink roadmaps for wrist-worn form factors.
Computing commands the highest silicon content per system; Wearable Devices is gaining share fastest through health-monitoring integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing fabrication investment as subsidy regimes in the United States, European Union, and Japan widen cost-of-compliance gaps against legacy manufacturing clusters. Capital equipment shipments now track government incentive disbursement schedules more closely than pure market demand signals.
United States
Hyperscale data center operators in Virginia and Oregon are reserving multi-year foundry capacity for AI training clusters. The CHIPS and Science Act directs EPA and Department of Commerce funding toward Arizona and Texas fab construction. Intel Corporation is expanding leading-edge production in Chandler, Arizona, while TSMC builds adjacent capacity for 3nm logic.
Taiwan
Apple and NVIDIA procurement commitments sustain allocation queues extending 18-24 months for sub-3nm wafer starts. The National Science and Technology Council coordinates domestic supply chain resilience programs. Hsinchu Science Park anchors the pure-play foundry ecosystem that commands disproportionate global logic production.
South Korea
Samsung Electronics and SK hynix are qualifying gate-all-around transistor processes for high-bandwidth memory and smartphone SoCs. METI-aligned subsidies support Yongin and Pyeongtaek fab complexes. The Pangyo cluster concentrates fabless design activity for automotive sensor fusion processors.
China
Domestic procurement mandates under GB standards are redirecting mature-node demand toward local foundries. MIIT licensing frameworks constrain EUV lithography access, extending development timelines for advanced logic. The Yangtze River Delta retains concentration in legacy node production for industrial and consumer applications.
Germany
Automotive OEMs in Stuttgart and Munich are qualifying domestic foundry capacity for AEC-Q100 power management ICs. The EU Chips Act allocates capital to Dresden and Magdeburg for 300mm logic and analog production. Infineon Technologies anchors the Saxony cluster expanding silicon carbide substrate fabrication for 800V EV platforms.
Integrated Circuit Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with IDMs controlling proprietary process nodes and pure-play foundries capturing fabless design wins. The market structure concentrates leading-edge logic in a duopoly of East Asian fabricators, while analog and power semiconductors sustain more fragmented, regionally distributed supply bases. Three archetypes dominate: vertically integrated memory-logic conglomerates, pure-play foundry operators, and fabless chip designers relying on external fabrication. Competitive moves center on multi-year capacity reservation agreements and heterogeneous packaging partnerships that lock in allocation before fab completion.
Within the scale-driven tier, Samsung Electronics exemplifies the integrated conglomerate archetype spanning memory fabrication to system-level packaging. Taiwan Semiconductor Manufacturing Company occupies the pure-play foundry position, controlling access to sub-3nm process nodes. NVIDIA Corporation represents the fabless design archetype, leveraging GPU architecture leadership to dominate AI training and autonomous vehicle compute platforms.
| Leading Market Players |
|---|
| Samsung Electronics |
| Qualcomm Incorporated |
| NVIDIA Corporation |
| SK hynix |
| Advanced Micro Devices (AMD) |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Intel Corporation |
| Micron Technology |
| Broadcom Inc. |
| Others |
Supply Flow & Price Mechanics
Captive foundry capacity at Intel and Samsung anchors both supply security and pricing leverage for leading-edge logic, insulating integrated circuit buyers from allocation volatility that pure-play dependence creates. This integration choice concentrates pricing power with IDMs while fabless designers absorb margin compression through multi-year reservation premiums.
Pricing Analysis
Distributor margins for mature-node analog ICs compress as hyperscale buyers negotiate direct foundry relationships for advanced logic wafers. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive-qualified devices from commercial-grade alternatives, with certification-driven premiums widening as ISO 26262 compliance costs escalate. Cost compression in mature-node embedded microcontrollers intensifies because second-hand 200mm equipment scarcity constrains capacity expansion. Automotive OEMs exhibit lowest price sensitivity due to qualification timelines, while consumer electronics assemblers drive aggressive cost-down schedules.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs now require qualified second sources for power management ICs previously sole-sourced from Taiwan. Supply concentrates in Taiwan, South Korea, and the United States for leading-edge logic, with neon gas purification and silicon carbide substrate growth anchoring raw material dependencies. Single-source vulnerability around ASML EUV lithography equipment creates structural risk for sub-3nm production nodes. Distribution runs through authorized distributors for small-batch industrial orders, while direct foundry contracts dominate hyperscale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated circuit fabrication investment functions as a geographic-arbitrage play where EU Chips Act subsidies in Dresden offset 15-20% cost disadvantages against Hsinchu production clusters. This differential redirects capital equipment shipments toward European greenfield sites.
For Market Incumbents: To counter foundry duopoly consolidation, IDMs should secure captive supply of silicon carbide substrates through backward integration into substrate growers, while simultaneously expanding 300mm analog capacity in Arizona and Texas to capture CHIPS Act allocation incentives. For New Entrants and Emerging Players: Begin with mature-node embedded microcontroller production for Indian white-goods and metering applications, where PLI scheme coverage reduces capital intensity. Target Vietnam and Indonesia industrial automation demand for low-power neural processing units, leveraging local system integrator partnerships as primary go-to-market channel. For Investors and Strategic Acquirers: Roll-up economics work for analog and power semiconductor specialists because customer qualification timelines create sticky revenue streams that resist commoditization. Monitor gate-all-around transistor yield ramps at Samsung and TSMC as inflection indicator for next-generation node economics viability.| Strategic Initiative | Industry Significance |
|---|---|
| Heterogeneous Packaging Partnership | Die-to-die interconnect standards enable fabless designers to mix process nodes within single packages, redistributing value capture. |
| Silicon Carbide Substrate Integration | Infineon's Saxony expansion anchors 800V EV platform supply security for Stuttgart and Munich automotive OEMs. |
| Multi-Year Capacity Reservation | Hyperscale buyers in Virginia and Oregon lock in allocation before Arizona and Texas fab construction completes. |
| Automotive Qualification Investment | AEC-Q100 certification opens procurement channels to German and Japanese OEMs reducing Taiwan dependency. |
| Edge AI Inference Acceleration | Industrial sensor vendors in the Netherlands and Switzerland specify sub-1mW sleep states for asset tracking applications. |
Methodological Framework
Bottom-up automotive and data center procurement modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with fabless design executives, foundry account managers, Tier 1 automotive supplier procurement leads, and semiconductor equipment specialists combined with secondary validation from SEC filings, SEMI equipment shipment data, and national subsidy disbursement records. Triangulation across these sources ensures demand-side consumption patterns align with supply-side wafer start announcements.
Input-output matrices map process node transitions, end-use application silicon content, and regional production cluster evolution across the projection horizon. Segmentation dimensions span product architecture, fabrication technology, end-user qualification requirements, and deployment application, with CAGRs derived from wafer demand elasticity and equipment investment lag structures. Forecast inputs incorporate EUV lithography deployment schedules and automotive electrification content-per-vehicle trajectories.
Several conditions sit outside the modeled scope, including sudden export control expansions, neon gas supply disruptions, and unanticipated process node yield failures. Deviation in gate-all-around transistor ramp timelines or CHIPS Act disbursement delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market