
 Global Flame Proof Lighting Market | 2026-2036
Global Flame Proof Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flame Proof Lighting Market Analysis
Modular fixture bundling is rebalancing procurement patterns across hazardous environments. R. STAHL AG anchors its position through deep specialization in German-engineered explosion-proof enclosures. Eaton leverages integrated power management portfolios to extend reach across oilfield services. Emerson Electric Co. competes through captive manufacturing of sealed driver assemblies for Zone 1 installations.
Flame proof lighting denotes sealed luminaires engineered to contain internal ignition and withstand explosive gas atmospheres, typically constructed with cast aluminum housings, tempered glass lenses, and flame-path joints measured to precise tolerances. These fixtures serve critical illumination roles in hydrocarbon processing, underground extraction, and chemical synthesis where volatile compounds persist. LED product type dominates value contribution as solid-state architecture eliminates filament failure modes and reduces thermal load in confined spaces. Explosion proof technology captures premium positioning due to mandatory certification burdens and specialized foundry capacity. Oil and Gas application leads volume absorption, though Chemical Processing exhibits faster trajectory as Asian capacity expansions multiply.
ATEX directives in Europe, IECEx schemes in Australia and Singapore, and OSHA standards enforced by the US Department of Labor collectively mandate third-party testing for ingress protection and surface temperature classification. Compliance complexity elevates barriers for unqualified suppliers while reinforcing pricing power among certified incumbents. Stakeholders must weigh certification portability against regional specification divergence when configuring distribution networks.
Market Dynamics
LED solid-state architecture is compressing replacement cycles while IECEx certification mandates in Singapore and Australia force foundry capacity consolidation among enclosure suppliers. Modular bundling contracts now dominate offshore platform procurement.
Growth Catalysts
- Deepwater exploration:Offshore operators in Brazil's pre-salt basins and Angola's Kwanza shelf require Zone 1-rated luminaires for subsea installation vessels. Rig commissioning schedules pull forward fixture orders.
- ATEX Directive 2014/34/EU:European chemical processors must replace legacy metal-halide installations with certified LED alternatives during planned turnaround windows.
- Phosphor-converted white LEDs:Solid-state emitters eliminate filament ignition risks while reducing thermal footprint in confined hydrocarbon processing modules.
Market Restraints
- Cast aluminum ingot volatility:Enclosure foundries in Germany and Italy face input cost swings that compress margin on standardized fixture housings.
- Third-party test queue congestion:IECEx and ATEX certification backlogs at notified bodies in the UK and Netherlands extend product launch timelines.
- Fluorescent fixture residual stock:Industrial maintenance departments in Eastern European petrochemical plants delay LED conversion to exhaust existing tube inventories.
Strategic Opportunities
- Indian petrochemical corridor:Reliance Industries' Jamnagar expansion and proposed complexes in Odisha create demand for flame-proof floodlighting in sulfur recovery units.
- Wireless monitoring convergence:Integration of luminaire-mounted vibration and temperature sensors enables predictive maintenance contracts in Norwegian North Sea platforms.
- US Inflation Reduction Act:Domestic content bonuses for energy-efficient industrial equipment accelerate LED retrofits in Texas and Louisiana refinery complexes.
Industry Challenges
- Flame-path machining precision:Tolerance control for cast aluminum joint surfaces requires specialized CNC programming expertise that foundries struggle to staff.
- Legacy conduit compatibility:Retrofit installations in 1970s-era Gulf Coast refineries demand custom adapter geometries that complicate standardized product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flame Proof Lighting Market |
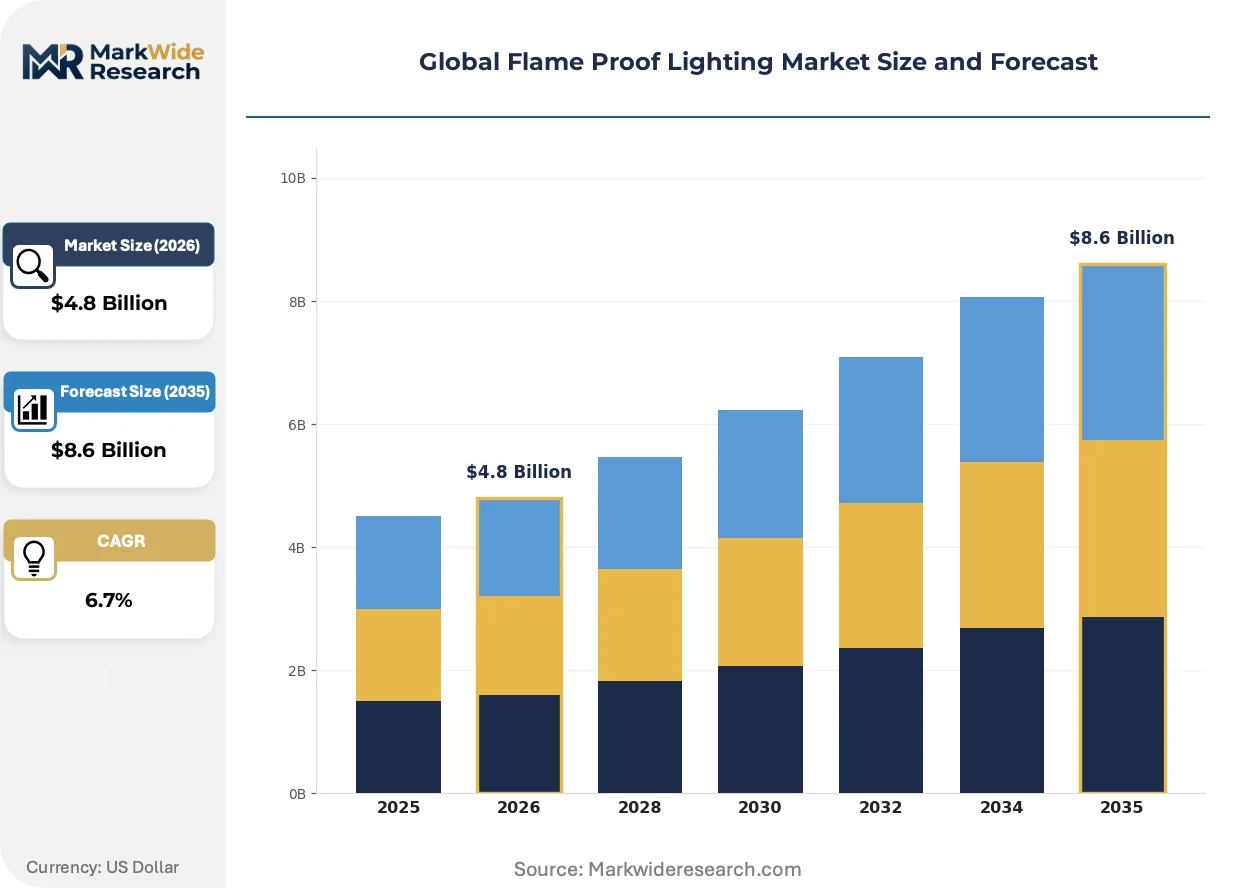
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
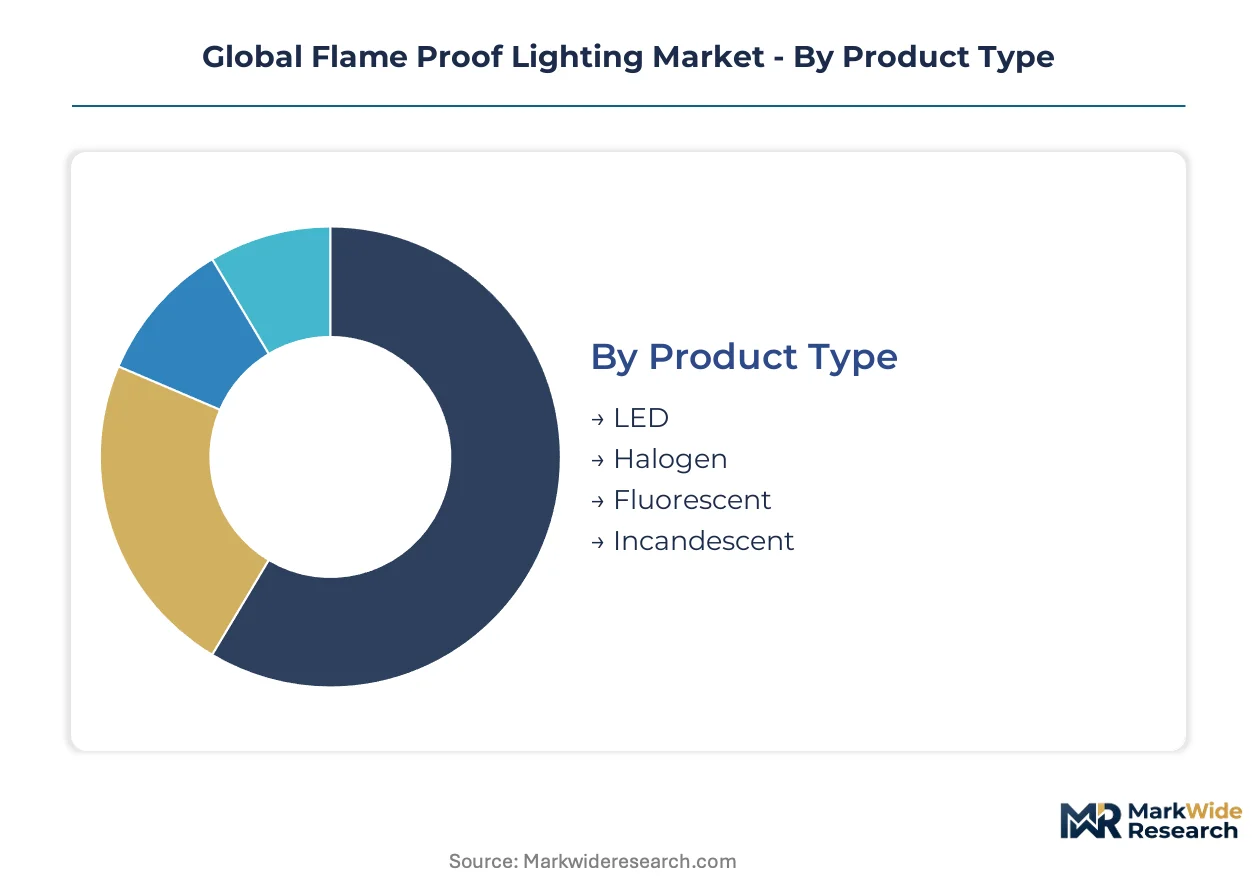
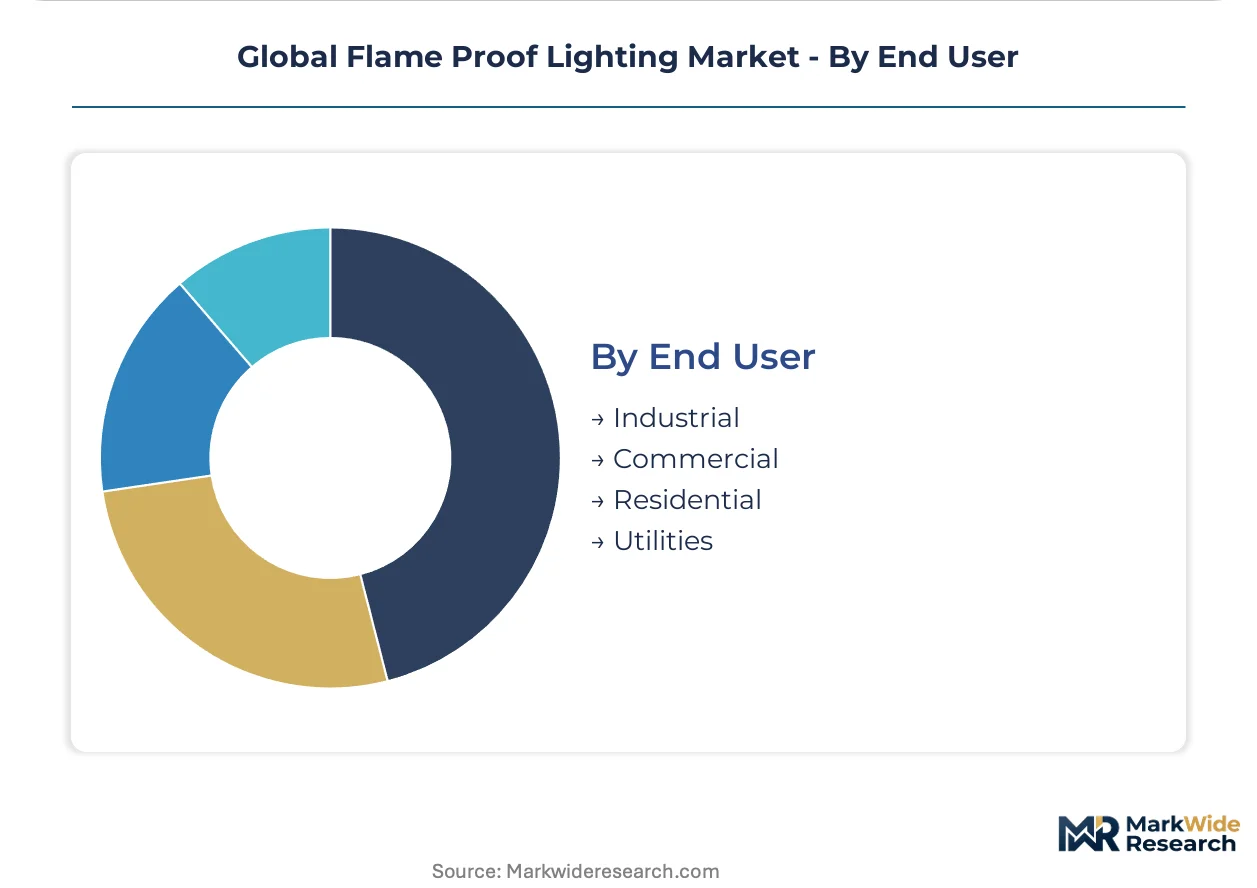
| Segmentation | Product Type: LED, Halogen, Fluorescent, Incandescent Technology: Explosion Proof, Dust Ignition Proof, Weatherproof, Corrosion Resistant Application: Oil & Gas, Mining, Chemical Processing, Manufacturing End User: Industrial, Commercial, Residential, Utilities |
| Companies Covered | Emerson Electric Co., R. STAHL AG, ABB, Larson Electronics LLC, Adolf Schuch GmbH, Eaton, Dialight, Phoenix Products LLC, Hubbell Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flame Proof Lighting Market Emerging Trajectories
Digital thread integration across design, certification, and field commissioning is compressing product development cycles. Three forces are actively restructuring competitive positioning.
Chip-on-board LED arrays with ceramic substrates are rewriting thermal management assumptions for high-lumen output in confined hazardous spaces. Offshore engineering contractors in Norway and the UK specify these packages for platform helideck and process area illumination. The technology is compressing fixture size-to-output ratios and enabling single-luminaire coverage of larger zone volumes.
REACH substance restrictions on hexavalent chromium coatings are forcing European foundries to convert to trivalent passivation or powder-coat alternatives for aluminum enclosures. Surface finish suppliers in Germany report qualification delays as chemical processors demand accelerated corrosion testing data. The regulation most affects legacy product lines serving North Sea installations with extended salt-exposure duty cycles.
Integrated service contracts now bundle fixture supply with periodic ingress protection testing and driver replacement scheduling. Engineering-procurement-construction firms in Saudi Arabia and the UAE specify these arrangements to reduce their maintenance labor exposure in remote desert processing sites. The model displaces spot purchasing through regional electrical distributors and locks in multi-year supplier relationships.
Global Flame Proof Lighting Market Segmentation
Certification requirements fragment procurement patterns across flame proof lighting segments. ATEX and IECEx mandates create divergent compliance burdens that reshape supplier selection criteria by product architecture and deployment environment.
Product Type:
ATEX Directive 2014/34/EU and IECEx schemes impose distinct testing protocols on solid-state versus legacy filament technologies, elevating documentation costs disproportionately across segments.
- LED:Solid-state emitters with ceramic substrates and sealed driver assemblies eliminate ignition risk from filament failure. Offshore platform operators in Brazil's pre-salt basins and Angola's Kwanza shelf specify these for helideck illumination where thermal management constraints dominate. Phosphor-converted white packages compress fixture size-to-output ratios while satisfying Zone 1 surface temperature classifications.
- Halogen:Tungsten-halogen capsules operate at elevated filament temperatures that demand enlarged flame-path joints and reinforced glass lenses. German chemical processors at BASF Ludwigshafen and Bayer Leverkusen sites retain these for high-CRI inspection tasks during planned turnarounds, though LED substitution accelerates.
- Fluorescent:Tube-based luminaires with sealed ballast enclosures persist in Eastern European petrochemical maintenance departments exhausting residual inventories.
- Incandescent:Legacy filament construction survives only in isolated mining applications with minimal ignition hazard classification.
Leading the category by volume: LED. Growing fastest: LED.
Technology:
Margin structures diverge sharply based on foundry specialization and third-party certification queue depth, with explosion-rated enclosures commanding premium positioning.
- Explosion Proof:Cast aluminum housings with precision-machined flame-path joints contain internal ignition per IEC 60079-1. German foundries in Stuttgart and Nuremberg anchor supply, though Singapore and Australia certification backlogs extend lead times. Oil & Gas applications in Saudi Arabia's Jubail and Yanbu corridors absorb the majority of output.
- Dust Ignition Proof:Enclosed and gasketed construction prevents combustible dust entry for grain handling and powder processing. Midwest US ethanol plants and Brazilian sugarcane processing facilities drive specification.
- Weatherproof:IP66-rated seals against moisture ingress serve coastal installations without explosive atmosphere classification.
- Corrosion Resistant:Trivalent chromium or powder-coat finishes replace hexavalent passivation under REACH restrictions, delaying qualification for North Sea salt-exposure duty cycles.
Highest margin capture: Explosion Proof. Steepest expansion trajectory: Dust Ignition Proof.
Application:
Procurement scale and replacement cycle timing vary dramatically by sector capital intensity and regulatory inspection frequency.
- Oil & Gas:Offshore platform commissioning schedules in Norway's North Sea and deepwater developments off Brazil pull fixture orders forward. Integrated service contracts now bundle supply with ingress protection testing and driver replacement scheduling.
- Chemical Processing:Asian capacity expansions at Reliance Jamnagar and proposed Odisha complexes multiply demand for sulfur recovery unit floodlighting. REACH substance restrictions force accelerated corrosion testing for European installations.
- Mining:Underground extraction in Australia's Bowen Basin and South Africa's platinum belt requires Zone 1-rated portable and fixed installations.
- Manufacturing:Paint finishing and solvent-handling operations in automotive plants specify flame-proof construction for spray booth illumination.
Dominant volume share: Oil & Gas. Gaining share fastest: Chemical Processing.
End User:
Customer sophistication and contract structure complexity stratify across facility scale and maintenance capability.
- Industrial:Petrochemical majors and engineering-procurement-construction firms in Saudi Arabia and UAE specify multi-year bundled arrangements to reduce maintenance labor exposure at remote desert sites.
- Commercial:Fuel storage terminals and distribution facilities require certified perimeter and canopy lighting.
- Residential:Minimal penetration limited to attached garage applications in hydrocarbon-proximate zones.
- Utilities:Natural gas compressor stations and LNG regasification terminals mandate explosion-rated emergency egress systems.
Primary revenue concentration: Industrial. Contract value growth: Utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Jubail and Yanbu industrial cities concentrate petrochemical investment under the country's National Industrial Development and Logistics Program. These zones attract integrated engineering-procurement-construction contracts that bundle flame-proof lighting with long-term service agreements.
United States
Texas and Louisiana refinery complexes drive LED retrofit demand following the Inflation Reduction Act's domestic content bonuses for energy-efficient industrial equipment. OSHA enforces hazardous location standards through its National Emphasis Program on refinery safety. The Gulf Coast petrochemical corridor from Houston to Lake Charles absorbs premium explosion-proof fixture volumes.
Germany
BASF Ludwigshafen and Bayer Leverkusen chemical sites retain halogen installations for high-CRI inspection tasks during planned turnarounds. REACH substance restrictions on hexavalent chromium coatings force trivalent passivation conversions at Stuttgart and Nuremberg foundries. The country's precision machining expertise anchors European flame-path joint manufacturing.
Brazil
Pre-salt basin offshore operators specify Zone 1-rated luminaires for subsea installation vessels and platform helideck illumination. ANVISA coordinates with IECEx schemes for equipment import certification. Rio de Janeiro engineering contractors pull fixture orders forward to match rig commissioning schedules.
India
Reliance Industries' Jamnagar expansion and proposed Odisha petrochemical complexes create demand for sulfur recovery unit floodlighting. The Bureau of Indian Standards enforces hazardous area equipment certification under CEA guidelines. Gujarat's Dahej and Hazira industrial belts concentrate procurement for integrated refinery-petrochemical projects.
Norway
North Sea platform operators adopt wireless monitoring convergence for predictive maintenance contracts on luminaire-mounted sensors. The Norwegian Labour Inspection Authority enforces ATEX-aligned offshore safety regulations. Stavanger engineering clusters specify ceramic substrate LED arrays for compact thermal management in confined process modules.
Global Flame Proof Lighting Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers and application verticals. The market exhibits moderate concentration with tiered positioning between integrated electrical majors and enclosure-focused fabricators. Three archetypes dominate: diversified industrial conglomerates with power management portfolios, German-engineered explosion-proof specialists, and integrated service contractors bundling supply with maintenance. Capacity expansion at notified-body-certified foundries and strategic partnerships for wireless monitoring integration represent the dominant competitive vectors.
Among diversified industrial conglomerates, Emerson Electric Co. and Eaton occupy positions spanning integrated power management and hazardous area illumination. R. STAHL AG exemplifies the focused specialist archetype with deep German engineering heritage in explosion-proof enclosures. These three anchors illustrate the competitive tension between breadth-driven conglomerate scale and depth-driven specialist certification expertise.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| R. STAHL AG |
| ABB |
| Larson Electronics LLC |
| Adolf Schuch GmbH |
| Eaton |
| Dialight |
| Phoenix Products LLC |
| Hubbell Incorporated |
| Others |
Supply Flow & Price Mechanics
Captive foundry operations at German enclosure specialists anchor supply positions while compressing competitor margins through controlled flame-path joint capacity. This backward integration into precision-machined cast aluminum housings simultaneously secures ATEX certification timelines and sustains premium pricing power against distributor-dependent rivals.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent above contract baselines reward foundries with excess IECEx-certified capacity, while spot inventory from Italian distributors trades at discounts to clear standardized housing stocks. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels segments buyer archetypes, with offshore engineering-procurement-construction firms least sensitive and Eastern European maintenance departments most price-responsive. Cost compression in economy-tier fluorescent retrofits is intensifying because residual inventory liquidations crowd replacement demand.
Supply Chain Analysis
Cast aluminum ingot supply rests on German and Italian smelter networks, with ceramic substrate LED arrays drawing from Japanese and Taiwanese semiconductor packaging specialists. Flame-path machining expertise concentrates in Stuttgart and Nuremberg manufacturing clusters, exposing the chain to single-source vulnerability in precision CNC programming labor. Distribution runs through Saudi and UAE-based engineering-procurement-construction contractors who bundle long-term service contracts with fixture supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification backlog congestion at UK and Netherlands notified bodies is accelerating consolidation, forcing undercapitalized enclosure fabricators toward distressed exit or acquisition.
For Market Incumbents: To counter foundry capacity constraints at IECEx-certified facilities, prioritize captive machining investments in German industrial corridors and accelerate wireless sensor integration roadmaps for predictive maintenance bundling. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian petrochemical corridor floodlighting offers white-space entry through Bureau of Indian Standards certification partnerships and sulfur recovery unit specialization. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap enclosure specialists with dormant ATEX portfolios, where long-term viability hinges on five-to-ten-year LED retrofit cycle capture; watch for IECEx queue clearance rates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Foundry Capacity Expansion | Stuttgart and Nuremberg machining investments compress competitor lead times at IECEx bottlenecks. |
| Wireless Sensor Integration | Luminaire-mounted vibration monitoring enables predictive maintenance contracts with Norwegian North Sea operators. |
| Long-term Service Contracting | Saudi engineering-procurement-construction firms reduce desert site labor exposure through bundled arrangements. |
| REACH-Compliant Surface Finish Conversion | Trivalent chromium passivation qualification delays at German foundries reshape North Sea corrosion-resistance supply. |
| Indian Certification Partnership | Bureau of Indian Standards alignment opens Jamnagar and Odisha petrochemical complex procurement channels. |
Methodological Framework
Document review covered IECEx and ATEX certification registries, SEC filings from electrical conglomerates, and petrochemical project development databases, complemented by interviews with plant engineers at BASF Ludwigshafen and Bayer Leverkusen, procurement leads at Saudi Aramco engineering subsidiaries, and maintenance directors at Gulf Coast refineries. Secondary validation drew from OSHA enforcement records, REACH substance restriction updates, and Bureau of Indian Standards hazardous area equipment notifications. Bottom-up fixture demand estimates triangulated against top-down petrochemical capital expenditure tracking.
Segment-level outputs across product type, technology tier, application vertical, and end-user archetype were generated through the projection horizon using driver elasticity models calibrated to offshore platform commissioning schedules and regulatory replacement mandates. CAGRs were derived from installation base turnover rates and LED substitution curves, with inputs from cast aluminum price indices and certification queue depth metrics.
Inputs from notified body publication schedules and foundry capacity surveys were available through the study window; gaps in real-time Eastern European maintenance department inventory data introduce uncertainty bands around fluorescent retrofit timing assumptions. Forecasts reflect documented elasticity relationships and documented regulatory enforcement intensities. A small set of triggers—IECEx queue clearance acceleration, REACH corrosion-testing qualification delays, and Indian petrochemical project sanctioning rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Lighting Management System Market
Lighting
Art and Museum Lighting Market
Lighting
Global Lamps Market
Lighting
Intelligent Lighting Market
Lighting
Industrial OLED Lighting Market
Lighting
Plasma Lighting Market
Lighting
Display Light Control Film Market
Lighting
Solar Rope Light Market
Lighting
Global Work Lights Market
Lighting
Vintage Bulb Market
Lighting
Europe Lighting Control Systems Market
Lighting
Smart Lighting Market
Lighting
COB Photo Light Market
Lighting
Photography Light Box Market
Lighting
Smart Industrial Illumination Market
Lighting
Industrial UV-C Disinfection Lighting Market