
 Europe Analog IC Market | 2026-2036
Europe Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Analog IC Market Insights
Silicon carbide is expanding its footprint in power management analog ICs, displacing traditional silicon substrates in high-temperature automotive applications. Infineon Technologies AG leverages its Dresden fab capacity to anchor European supply security for automotive-grade voltage regulators. STMicroelectronics NV competes through vertically integrated SiC wafer production from its Italian facilities. Texas Instruments Incorporated sustains design-in momentum across industrial automation accounts with broad operational amplifier portfolios.
Europe Analog ICs are integrated circuits that process continuous electrical signals across voltage, current, or frequency domains, typically fabricated on 180nm to 40nm process nodes with operating temperatures ranging from minus 40 to 175 degrees Celsius for automotive qualification. These devices serve as interface layers between digital systems and physical environments in power conversion, sensor conditioning, and audio amplification. Voltage regulators and data converters capture disproportionate margin pools as automotive 48V architectures and battery management systems multiply channel counts per vehicle. CMOS and BiCMOS technologies lead volume production, while GaN processes represent the fastest-growing technology tier for RF power and high-efficiency conversion segments.
EMA, REACH, and the EU Green Deal collectively constrain material selection and energy intensity across European analog IC fabrication, with REACH halogen restrictions directly impacting molding compound formulations and substrate bonding processes. CE marking and the F-Gas Regulation further shape thermal management system designs for industrial-grade power devices. Stakeholders must monitor substrate supply agreements and qualification timelines as SiC and GaN capacity commitments outpace installed European foundry expansion.
Market Dynamics
Automotive electrification is compressing design cycles for voltage regulators and battery management interfaces across European tier-one supply chains. Foundries in Dresden and Crolles are reallocating 180nm to 40nm capacity toward automotive qualification tiers as 48V architectures multiply analog channel counts per vehicle platform.
Growth Catalysts
- EU Green Deal decarbonization mandates:REACH compliance is forcing foundries toward gallium nitride substrates and reduced-halogen packaging, opening premium sockets for qualified suppliers.
- German industrial automation clusters:Machine tool and robotics OEMs are standardizing on programmable analog front-ends for sensor fusion, pulling data converter volumes.
- Silicon carbide substrate maturation:SiC wafer availability is expanding power management analog IC footprints in high-temperature automotive inverter applications.
Market Restraints
- Substrate supply concentration:European SiC and GaN wafer capacity commitments outpace installed foundry expansion, creating qualification bottlenecks for new entrants.
- REACH halogen restrictions:ECHA-mandated molding compound reformulations are extending substrate bonding process validation timelines by 6-12 months.
- Legacy silicon cost structures:Mature-node CMOS and BiCMOS processes face margin compression from 300mm silicon price volatility and energy-intensive thermal oxidation steps.
Strategic Opportunities
- French aerospace supply chain qualification:DO-254 and DO-178C certification gaps in European analog IC vendors create white space for radiation-hardened voltage reference suppliers.
- GaN-on-silicon RF power convergence:Base station and radar manufacturers are consolidating amplifier chains, opening multi-band analog control IC sockets.
- F-Gas Regulation thermal management:Industrial-grade power device vendors must redesign heat-spreader interfaces, creating attach opportunities for temperature sensor and protection IC specialists.
Industry Challenges
- Mixed-signal design talent scarcity:European universities graduate insufficient analog IC designers versed in both high-voltage power management and sub-micron digital integration.
- Automotive AEC-Q100 qualification timelines:Extended temperature cycling and ESD testing for minus 40 to 175 degrees Celsius operation compress product launch windows against Asian competitor cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Analog IC Market |
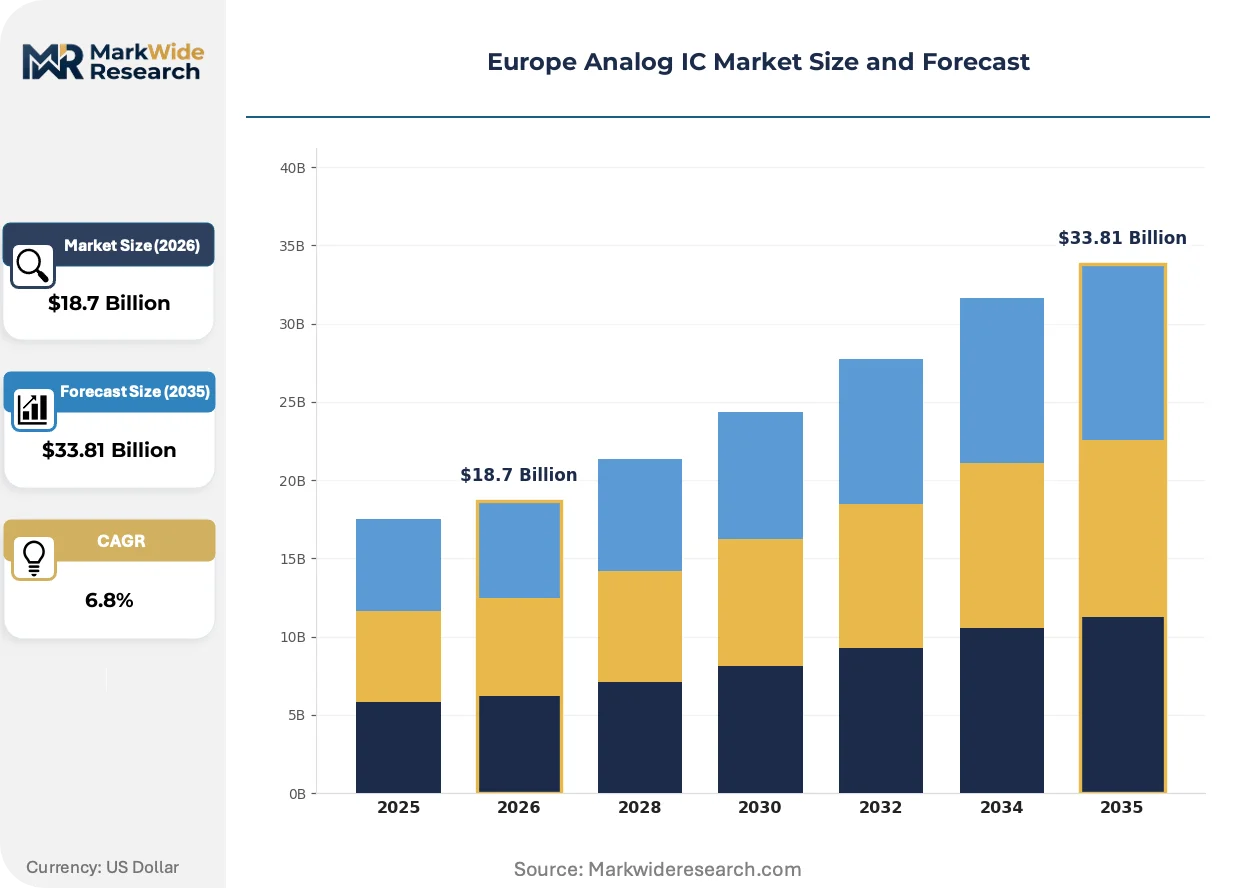
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Data Converters End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Technology: Bipolar, CMOS, BiCMOS, GaN Application: Signal Processing, Power Management, Audio Processing, Sensing |
| Companies Covered | STMicroelectronics NV, Microchip Technology Inc, Analog Devices Inc, Renesas Electronic Corporation, ON Semiconductor, Infineon Technologies AG, NXP Semiconductors NV, Skyworks Solutions Inc, Texas Instruments Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Analog IC Market Trends and Innovations
Process node diversification and compound semiconductor integration are fragmenting traditional analog IC roadmaps. European foundries are racing to anchor specialty process capabilities before Asian competitors consolidate GaN and SiC analog integration.
Gallium nitride power transistors are converging with precision gate driver analog ICs in single-package modules for 48V mild-hybrid inverters. German automotive tier-ones are adopting these integrated half-bridge solutions at twice the pace of silicon-based alternatives. This convergence is compressing discrete component supplier margins while elevating analog IC vendors with co-packaging expertise.
REACH substance restrictions are mandating lead-free solder alternatives and brominated flame-retardant elimination in IC molding compounds. ECHA enforcement is accelerating reformulation programs at packaging subcontractors across the Netherlands and Germany. High-reliability automotive and aerospace segments are absorbing 15-20% material cost premiums to maintain CE marking compliance.
Long-term supply agreements are displacing spot-market wafer procurement among European industrial automation OEMs. Buyers in Italy and Poland are locking 3-5 year foundry capacity reservations for voltage regulator and operational amplifier families. This behavioral shift concentrates procurement leverage among vertically integrated IDMs while squeezing fabless analog IC vendors without captive silicon or SiC supply.
Europe Analog IC Market Segmentation
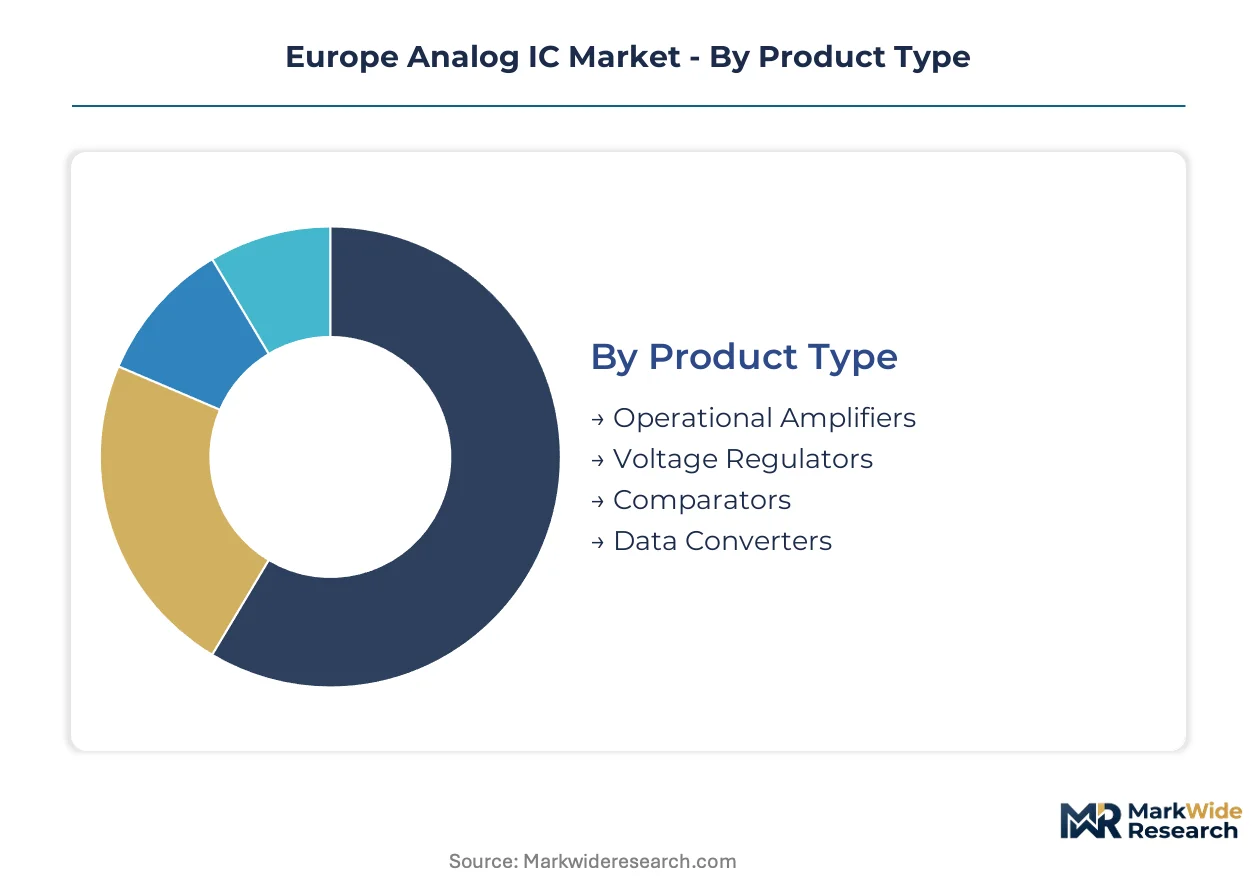
Europe Analog IC procurement patterns diverge sharply across product architectures and end-use verticals. Automotive qualification tiers, REACH compliance burdens, and foundry process availability reshape how buyers evaluate specifications and supplier relationships.
Product Type:
Buyers in this category differentiate primarily by channel density requirements and thermal operating envelopes rather than unit economics alone.
- Voltage Regulators:These devices manage power rail stability across input voltage variations, with automotive-grade variants supporting 48V mild-hybrid architectures multiplying channel counts per vehicle. German OEM procurement concentrates here as electrification accelerates.
- Data Converters:Analog-to-digital and digital-to-analog circuits bridge sensor outputs to digital processing cores. French aerospace and Italian industrial automation clusters pull precision converter volumes for telemetry and machine tool feedback loops.
- Operational Amplifiers:High-gain voltage amplifiers condition small sensor signals in closed-loop control systems.
- Comparators:High-speed switching devices trigger threshold-based protection circuits in battery management systems.
Voltage Regulators lead volumes today; Data Converters is gaining share fastest.
End User:
Application-specific qualification timelines and volume predictability separate procurement strategies across verticals.
- Automotive:AEC-Q100 qualification mandates minus 40 to 175 degrees Celsius operation with extended reliability testing. Tier-one suppliers in Germany and France lock long-term foundry capacity for voltage regulator and battery management interface families.
- Industrial Automation:Machine tool OEMs standardize on programmable analog front-ends for sensor fusion, pulling data converter volumes from Dresden and Crolles foundry output.
- Telecommunications:Base station manufacturers consolidate amplifier chains, opening sockets for multi-band analog control ICs.
- Consumer Electronics:Audio amplification and portable power management drive unit volumes with compressed margin structures.
Automotive commands the largest revenue pool; Industrial Automation shows the steepest expansion trajectory.
Technology:
Process maturity and substrate availability dictate sourcing security and qualification investment levels.
- CMOS:Dominant volume production technology leveraging mature-node cost structures across 180nm to 40nm geometries. Foundries in Dresden anchor European supply security for general-purpose analog functions.
- GaN:Gallium nitride processes enable high-efficiency RF power and conversion applications with superior switching characteristics. REACH halogen restrictions and EU Green Deal mandates accelerate substrate migration toward this tier.
- BiCMOS:Bipolar-CMOS integration combines high-speed analog performance with digital logic density for mixed-signal systems.
- Bipolar:Legacy junction-isolated processes retain niche positions in precision voltage references and high-voltage linear regulators.
CMOS retains volume leadership; GaN is climbing the fastest among emerging process tiers.
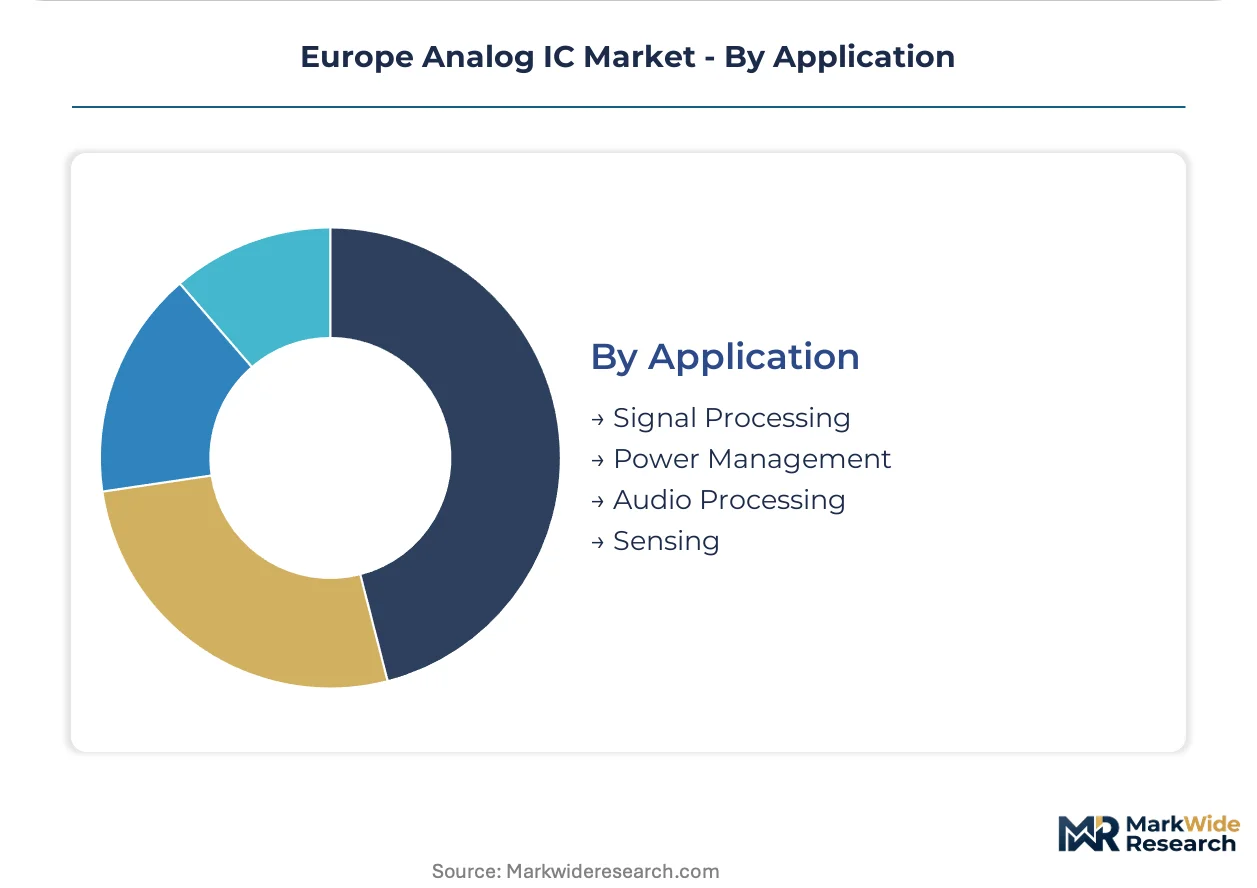
Application:
Functional integration requirements and thermal management constraints reshape component selection criteria.
- Power Management:Voltage regulation, battery charging, and energy conversion circuits dominate silicon carbide and gallium nitride adoption curves. SiC wafer availability from Italian facilities expands footprints in high-temperature automotive inverter applications.
- Signal Processing:Conditioning and filtering circuits bridge physical sensors to digital systems. German robotics OEMs standardize on programmable analog front-ends for multi-sensor fusion architectures.
- Sensing:Temperature, current, and position detection interfaces require precision references and low-noise amplification stages.
- Audio Processing:Consumer and automotive infotainment systems drive codec and amplifier integration with stringent electromagnetic compatibility requirements.
Power Management leads application revenue; Signal Processing is expanding most quickly as sensor proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters anchor European analog IC procurement, pulling voltage regulators and data converters from foundries in Dresden and Crolles as automotive electrification accelerates across the continent.
Germany
Machine tool OEMs in Bavaria and Baden-Württemberg standardize on programmable analog front-ends for sensor fusion architectures. The EU Green Deal decarbonization mandates push Munich-based automotive tier-ones toward gallium nitride substrates for 48V mild-hybrid inverters. Dresden's foundry corridor concentrates capacity reservations for AEC-Q100 qualified voltage regulators.
France
Aerospace manufacturers in Toulouse and Paris-Saclay drive demand for radiation-hardened voltage references and precision data converters. REACH halogen restrictions from ECHA extend substrate bonding validation timelines for Crolles-based packaging subcontractors. The Île-de-France cluster specializes in DO-254 certified analog ICs for satellite and avionics applications.
Italy
STMicroelectronics' SiC wafer production from Catania and Agrate Brianza anchors European supply security for high-temperature automotive power management. Industrial automation OEMs in Emilia-Romagna lock long-term foundry agreements for operational amplifier families. CE marking compliance absorbs material cost premiums for lead-free solder alternatives in molding compounds.
Netherlands
ASML's lithography ecosystem in Eindhoven supports precision analog IC fabrication for RF power applications. F-Gas Regulation thermal management requirements reshape heat-spreader interface designs for industrial-grade power devices. The Brainport region concentrates GaN-on-silicon process development for base station amplifier chains.
Poland
Automotive wiring harness manufacturers in Silesia and Lower Silesia multiply analog channel counts per vehicle platform for German OEM supply chains. Buyers in Warsaw and Kraków lock 3-5 year capacity reservations for voltage regulator families. The country's central European logistics position attracts packaging subcontractor investment for REACH-compliant molding compound reformulations.
Europe Analog IC Market Competitive Landscape
Global majors compete with regional champions across automotive qualification tiers and compound semiconductor integration. The vendor base stratifies between vertically integrated IDMs with captive SiC supply and fabless analog IC vendors dependent on foundry partnerships. Three archetypes dominate: scale-driven broadliners with operational amplifier portfolios, specialty power management houses with GaN co-packaging expertise, and aerospace-certified precision suppliers. Capacity expansion and strategic foundry partnerships constitute the dominant competitive moves as substrate supply agreements displace spot-market procurement.
Among European-anchored fabricators, Infineon Technologies AG and STMicroelectronics NV exemplify the vertically integrated archetype with in-house SiC wafer production, while Texas Instruments Incorporated occupies a position as a scale-driven broadliner sustaining design-in momentum across industrial automation accounts. These three companies represent contrasting strategic postures on the spectrum from captive substrate control to foundry-dependent flexibility.
| Leading Market Players |
|---|
| STMicroelectronics NV |
| Microchip Technology Inc |
| Analog Devices Inc |
| Renesas Electronic Corporation |
| ON Semiconductor |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Skyworks Solutions Inc |
| Texas Instruments Incorporated |
| Others |
Pricing and Supply Chain Analysis
Specialized analog IC design talent concentrated in Dresden and Catania feeds labor-cost differentials that separate premium automotive-grade voltage regulators from economy-tier consumer amplifiers. REACH-compliant molding compound reformulations and SiC substrate premiums widen pricing spreads between certified and uncertified supply tiers.
Pricing Analysis
Input-cost pass-through from gallium nitride wafer premiums and energy-intensive thermal oxidation steps shapes contract-based long-term offtake as the dominant pricing structure. Price differentiation rests on AEC-Q100 certification grade and volume scale commitments, with automotive tier-ones absorbing material premiums for CE marking compliance. Cost compression in mature-node CMOS operational amplifiers is intensifying because 300mm silicon price volatility squeezes foundry margins. Consumer electronics buyers exhibit highest price sensitivity, while aerospace manufacturers in Toulouse show lowest sensitivity due to DO-254 qualification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Italian SiC wafer production from STMicroelectronics' Catania facilities, which anchors European high-temperature power management supply. Raw material dependencies draw from germanium substrates for precision references, copper lead frames for thermal dissipation, and halogen-free epoxy molding compounds. Tariff exposure on GaN-on-silicon wafers sourced from Asian foundries constitutes the primary structural risk. Distribution runs through authorized distributors serving German automotive clusters and direct foundry relationships for French aerospace contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Analog IC procurement has shifted toward late-cycle quality specifications as automotive 48V architectures and REACH compliance mandates elevate certified supply premiums over spot-market alternatives.
For Market Incumbents: Extend captive SiC wafer capacity through backward integration into substrate production or long-term supply agreements with Italian facilities. Infineon Technologies AG's Dresden fab model demonstrates how foundry capacity reservations lock out fabless competitors. Prioritize AEC-Q100 qualification investment to defend against Asian competitors compressing automotive launch windows. For New Entrants and Emerging Players: Launch via specialized radiation-hardened voltage reference supply to French aerospace manufacturers facing DO-254 certification gaps among European vendors. White-space targets include GaN-on-silicon RF power modules for Netherlands-based base station manufacturers and temperature sensor ICs for F-Gas Regulation thermal management redesigns. Poland's automotive wiring harness cluster offers the most penetrable geography for voltage regulator design-ins. For Investors and Strategic Acquirers: Automotive tier-one suppliers are the most active acquirer in this space, seeking analog IC capabilities for 48V mild-hybrid platform integration. Long-term viability over a 5-10 year horizon favors vertically integrated IDMs with captive compound semiconductor supply over fabless vendors dependent on foundry partnerships. Watch SiC wafer capacity expansion announcements from European facilities as the critical inflection indicator for supply security repricing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-Silicon Process Development | Brainport region foundries capture RF power sockets from Netherlands base station manufacturers. |
| REACH-Compliant Packaging Reformulation | ECHA-mandated halogen restrictions extend qualification timelines for German molding compound subcontractors. |
| Long-Term Foundry Capacity Reservation | Italian industrial automation OEMs lock 3-5 year agreements for operational amplifier supply security. |
| AEC-Q100 Automotive Qualification | Dresden fab corridor anchors European supply for minus 40 to 175 degrees Celsius voltage regulators. |
| SiC Wafer Vertical Integration | Catania production facilities secure high-temperature inverter supply for German electrification programs. |
Research Methodology
Direct dialogue with analog IC design engineers, automotive tier-one procurement directors, foundry operations managers, and ECHA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from SEC 10-K filings of major semiconductor vendors, ECHA substance restriction updates, CE marking technical documentation, and vehicle production databases. Bottom-up and top-down triangulation cross-checked wafer capacity announcements against end-use demand signals from German industrial automation clusters.
Bottom-up modeling built from product-level specifications, process node yields, and substrate cost structures across the projection horizon. Segmentation dimensions included voltage regulator channel density, data converter precision tiers, GaN versus CMOS technology nodes, and automotive versus industrial end-use qualification levels. CAGRs were derived from installed base replacement cycles and content-per-vehicle expansion in 48V architectures. Forecast inputs incorporated REACH enforcement timelines and SiC substrate availability from European wafer facilities.
Several conditions sit outside the modeled scope, including geopolitical disruptions to gallium nitride substrate trade flows and unannounced ECHA substance restriction expansions beyond current halogen mandates. Forecasts reflect assumptions about AEC-Q100 qualification timeline stability and automotive platform electrification commitment durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market