
 Global Photonic Integrated Circuits (PIC) Market | 2026-2036
Global Photonic Integrated Circuits (PIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photonic Integrated Circuits (PIC) Market Intelligence
The direct-to-cloud procurement channel is rewriting how photonic integrated circuits reach end users. Intel Corporation leverages captive silicon photonics foundry capacity to control wafer supply from design to package. Broadcom Inc. anchors its position through backward integration into indium phosphide laser fabrication. Lumentum Operations LLC differentiates via specialized pump lasers and 3D sensing modules that extend its reach beyond telecom.
Photonic integrated circuits monolithically combine active and passive optical components on a single chip, typically fabricated on 200mm or 300mm wafers using CMOS-compatible processes to achieve sub-micron waveguide precision for terabit-scale data transmission. Silicon Photonics dominates volume production due to semiconductor infrastructure reuse, while Indium Phosphide retains margin pools in high-performance laser and modulator applications where direct bandgap properties prove essential. Arrayed Waveguide Grating technology leads wavelength multiplexing deployments in data centers, whereas Ring Resonator architectures are gaining traction in optical computing prototypes.
The FDA regulates PIC-based biomedical sensors through device classification pathways, while the FCC governs optical transmission equipment certification for telecom deployment in the United States. REACH and RoHS frameworks in Europe constrain material selection for gallium arsenide and indium phosphide devices, shaping foundry chemistry compliance costs. China's MIIT enforces GB standards for domestic optical module interoperability, creating market access conditions for foreign suppliers. Stakeholders must monitor which regulatory jurisdiction's certification timeline becomes the critical path for multi-region product launches.
Market Dynamics
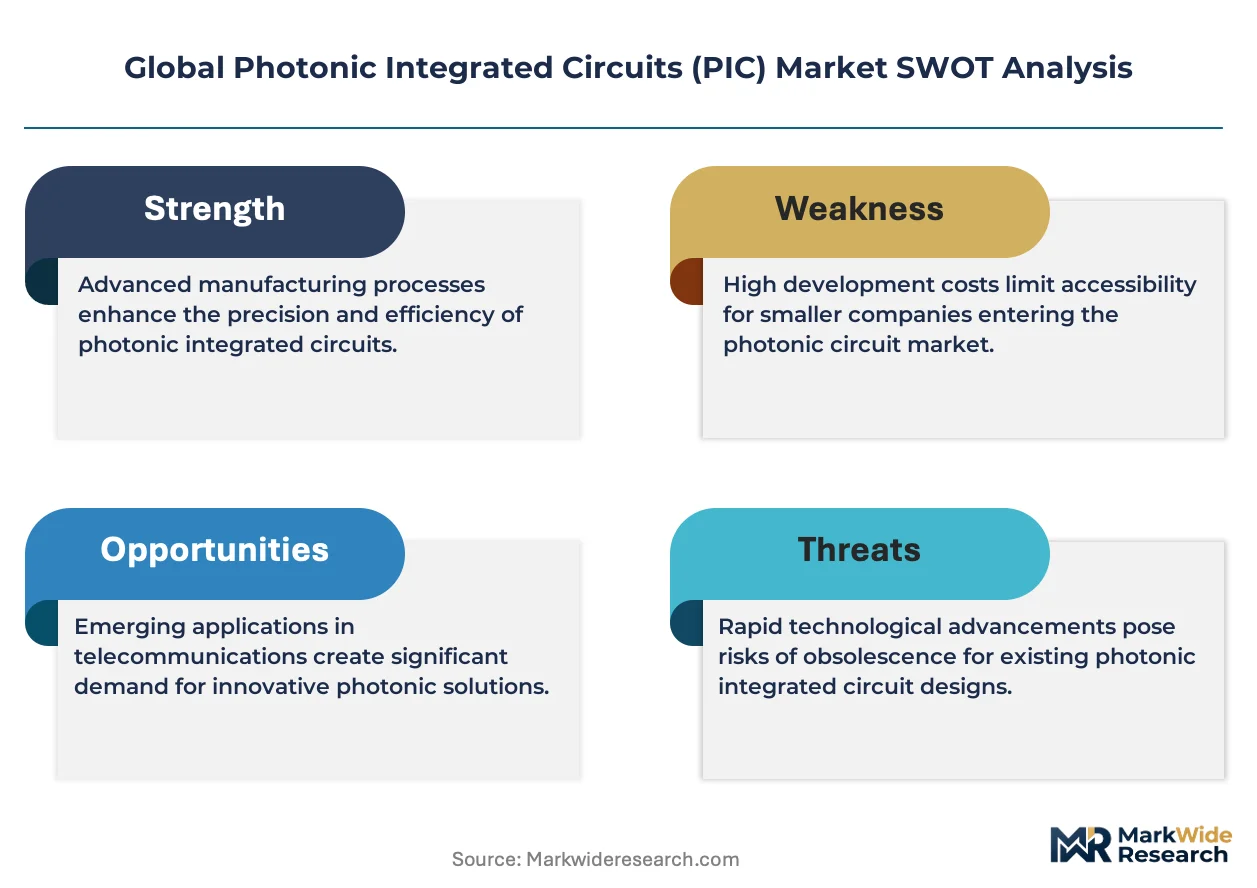
Silicon Photonics process maturation is collapsing the cost curve for optical interconnects, forcing legacy discrete component suppliers to retool or exit as data center operators consolidate procurement around monolithic PIC platforms.
Growth Catalysts
- Data Center Bandwidth Density:Hyperscale operators in the United States are deploying 800G optical modules at rack scale, creating pull-through demand for co-packaged optics and linear drive PICs.
- China's MIIT GB Standards:Domestic interoperability mandates for 400G/800G optical modules are accelerating foundry investments in Shanghai and Shenzhen, locking in captive supply chains for local equipment vendors.
- Indium Phosphide Laser Integration:Direct bandgap properties enable high-performance modulators for coherent transmission, preserving margin pools in long-haul telecom applications where silicon photonics hits thermal limits.
Market Restraints
- EUV Lithography Bottlenecks:300mm silicon photonics wafers compete with advanced logic for TSMC and Intel foundry capacity, constraining volume ramps during semiconductor supercycles.
- Indium Phosphide Substrate Concentration:Two Japanese suppliers control 80% of high-purity InP wafer supply, creating single-source vulnerability for telecom-grade laser fabrication.
- REACH RoHS Material Constraints:European chemical restrictions on gallium arsenide and indium phosphide processing chemistry inflate foundry compliance costs and limit recycling pathways.
Strategic Opportunities
- Optical Computing Prototypes:Ring resonator architectures in German research clusters are advancing photonic matrix multiplication for AI inference, opening pre-commercial design wins.
- Biomedical Sensor Miniaturization:FDA's breakthrough device pathway for PIC-based lab-on-chip diagnostics is compressing certification timelines for glucose and pathogen detection platforms.
- Co-Packaged Optics Adoption:Switch silicon vendors are integrating photonics chiplets at package level, displacing pluggable modules and capturing margin from optical component suppliers.
Industry Challenges
- Packaging Thermomechanical Yield:Thermal expansion mismatch between silicon photonics dies and organic substrates drives fiber attach failures, requiring precision alignment equipment that extends capital cycles.
- Multi-Jurisdiction Certification Synchronization:Products must clear FDA device classification, FCC Part 15/68 telecom certification, and China MIIT GB testing in parallel, with the slowest timeline dictating launch windows.
- Cross-Domain Talent Scarcity:PIC design requires simultaneous mastery of CMOS process physics, waveguide electromagnetics, and optoelectronic device modeling, with fewer than 200 qualified engineers graduating annually from top programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photonic Integrated Circuits (PIC) Market |
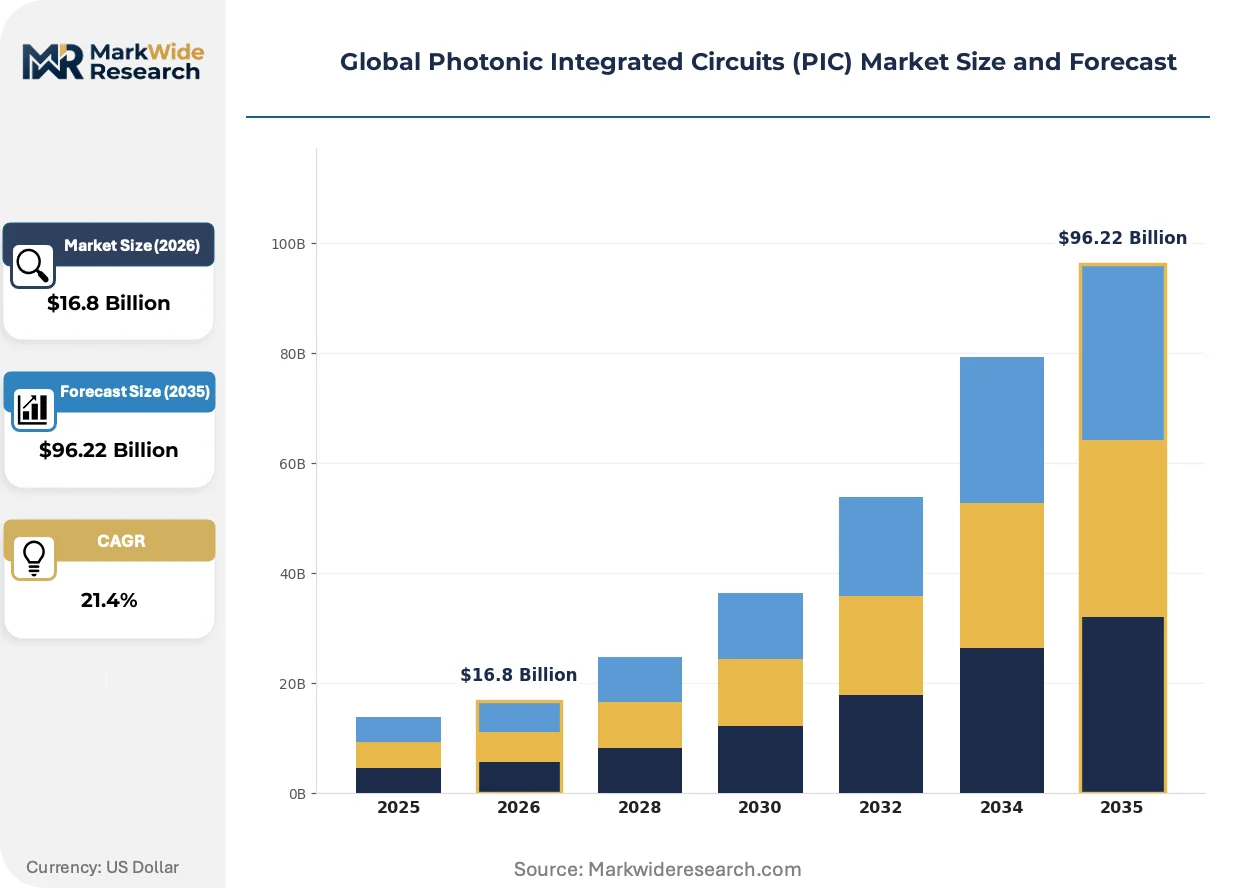
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $96.22 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indium Phosphide, Silicon Photonics, Gallium Arsenide, Silicon Nitride Technology: Electro-absorption Modulator, Mach-Zehnder Modulator, Ring Resonator, Arrayed Waveguide Grating Application: Data Centers, Telecommunication, Sensors, Optical Computing End User: Cloud Service Providers, Network Operators, Sensor Manufacturers, Computing Hardware Vendors |
| Companies Covered | Intel Corporation, Infinera Corporation, Cisco Systems, Inc., Broadcom Inc., Lumentum Operations LLC, Ciena Corporation, MACOM, EMCORE Corporation, Acacia Communications, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photonic Integrated Circuits (PIC) Market Strategic Shifts & Innovations
Monolithic integration is collapsing the traditional boundary between electronic and photonic design, forcing semiconductor toolchains to absorb optical simulation and foundries to qualify new process modules.
Thin-film lithium niobate modulators are rendering obsolete legacy bulk-crystal designs in coherent transmission. Cloud operators deploying 800G ZR pluggables are qualifying these devices for metro distances. The technology is compressing power consumption per bit by half, shifting procurement criteria from raw bandwidth to energy efficiency.
REACH authorization requirements for gallium arsenide and indium phosphide process chemistry are forcing European foundries to substitute precursor materials. ECHA's 2024 sunset dates for several high-volume etchants are accelerating qualification of atomic layer deposition alternatives. German and Dutch cleanroom operators are absorbing 15-20% chemistry cost increases to maintain CE marking access.
Direct-to-cloud procurement contracts are bypassing traditional optical component distributors. Hyperscale buyers in the United States are negotiating multi-year wafer supply agreements directly with captive silicon photonics foundries. This channel compression is squeezing distributor margins and forcing catalog vendors to pivot toward design services and small-batch prototyping for mid-market enterprises.
Global Photonic Integrated Circuits (PIC) Market Segmentation
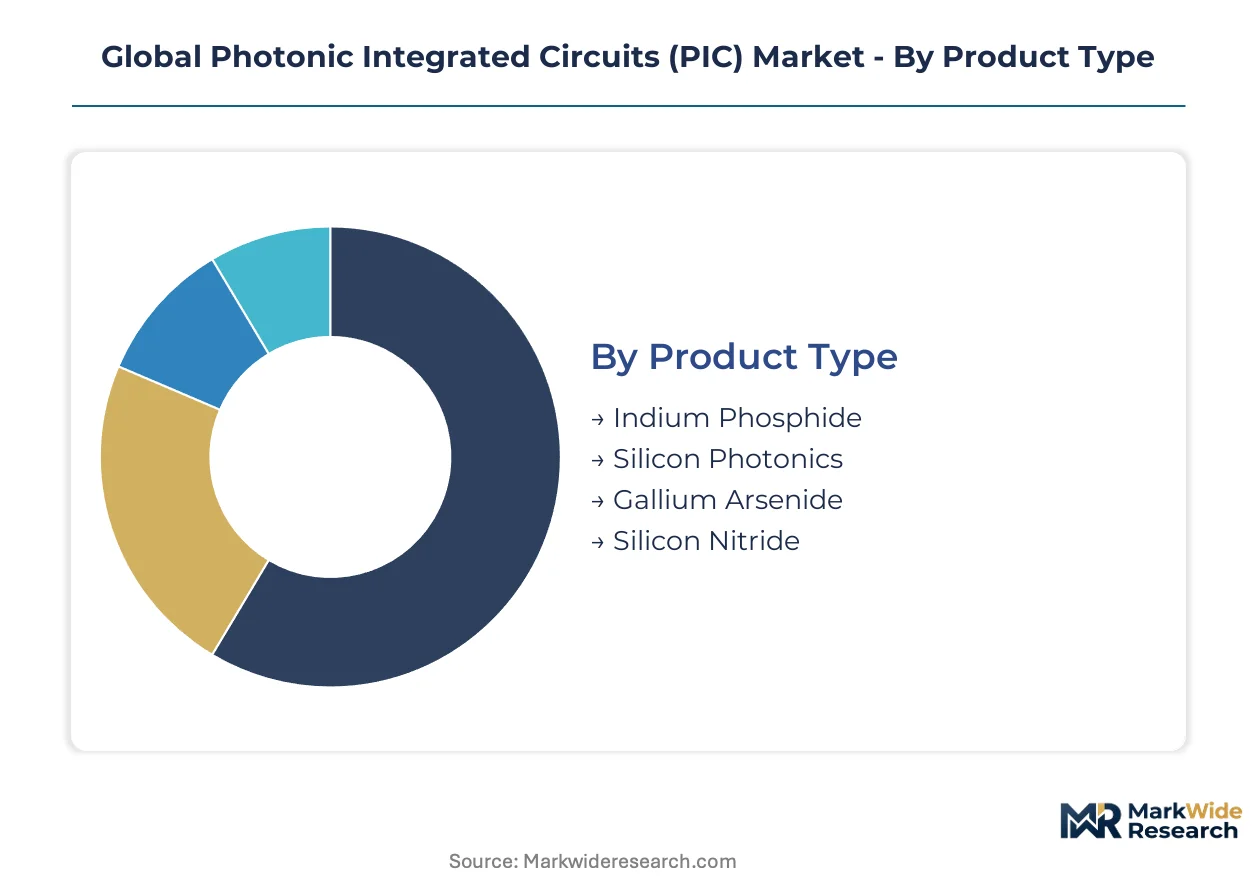
Segmentation in photonic integrated circuits reveals how material platforms, modulation architectures, and end-use requirements partition margin pools across the value chain. Each dimension carries distinct capital intensity, foundry compatibility, and certification pathways that shape supplier positioning.
Product Type:
After-sales service intensity varies sharply across material platforms, with compound semiconductor devices requiring specialized recalibration and foundry-level rework that silicon-based alternatives rarely need.
- Silicon Photonics:Monolithic integration leverages existing 300mm CMOS infrastructure for optical interconnects at data center scale. Hyperscale procurement in the United States concentrates here for co-packaged optics and linear drive applications where semiconductor economics dominate.
- Indium Phosphide:Direct bandgap properties enable high-performance lasers and modulators for coherent transmission beyond silicon thermal limits. Long-haul telecom deployments in China and Germany preserve premium margin pools despite substrate supply concentration from Japanese suppliers.
- Gallium Arsenide:Vertical-cavity surface-emitting laser arrays serve 3D sensing and short-reach optical links with established packaging protocols.
- Silicon Nitride:Ultra-low propagation loss suits frequency comb generation and precision sensing where waveguide quality factor determines performance.
By volume, Silicon Photonics leads. By growth pace, Silicon Nitride is expanding most quickly in emerging optical computing prototypes.
Technology:
Cost tier stratification separates legacy telecom-qualified modulators from emerging architectures still accumulating field hours and reliability data.
- Mach-Zehnder Modulator:Mature interferometric designs dominate coherent transmission with proven thermal stability and bias-free operation over extended temperature ranges. Network operators in Germany standardize procurement around these devices for metro and long-haul fiber links.
- Ring Resonator:Compact footprint and wavelength selectivity enable dense optical switching matrices for AI inference acceleration. Research clusters in Germany and the United States are qualifying these architectures for photonic matrix multiplication in pre-commercial optical computing platforms.
- Electro-absorption Modulator:Monolithic integration with laser sources reduces assembly complexity in compact transceiver form factors.
- Arrayed Waveguide Grating:Passive wavelength demultiplexing serves coarse and dense WDM deployments with no active thermal management burden.
Mach-Zehnder devices command the largest installed base. Ring resonator designs are climbing the fastest as cloud operators evaluate co-packaged optical switching.
Application:
Customer type determines specification rigor, with cloud procurement teams driving commoditization pressure that sensor and computing segments have so far resisted.
- Data Centers:Rack-scale 800G optical module deployment creates concentrated demand for high-volume, low-power interconnects. Hyperscale operators in the United States negotiate direct wafer supply agreements that bypass traditional component distribution.
- Telecommunication:Coherent transmission infrastructure requires hermetic packaging and decades-long reliability guarantees that inflate qualification timelines and preserve incumbent supplier positions.
- Sensors:Biomedical and environmental detection platforms leverage PIC miniaturization for point-of-care diagnostics where FDA breakthrough device pathways compress certification schedules.
- Optical Computing:Matrix multiplication and analog photonic accelerators remain pre-commercial, with design wins contingent on demonstration of energy efficiency advantages over electronic alternatives.
Data center applications generate the highest shipment volumes. Optical computing represents the steepest expansion trajectory contingent on successful AI inference demonstrations.
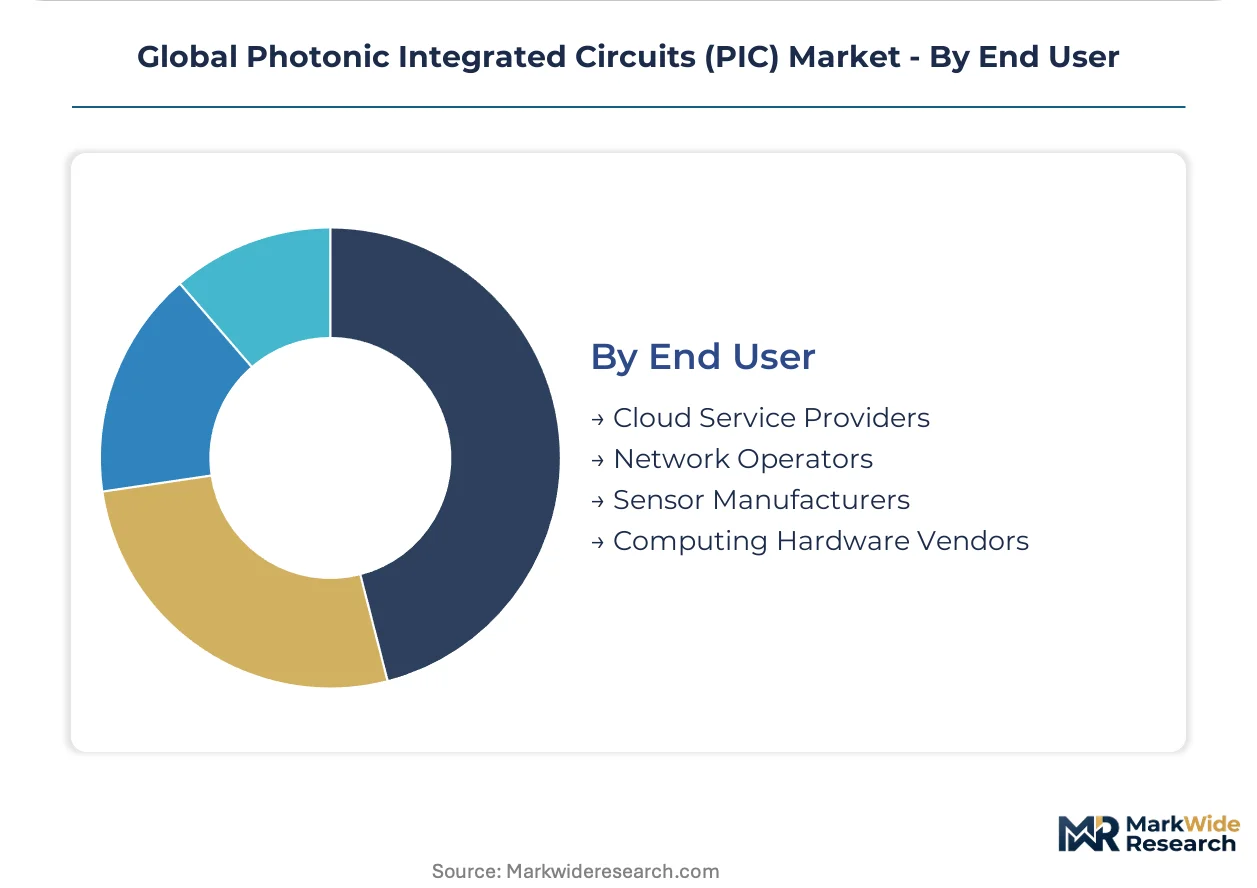
End User:
Geographic procurement concentration aligns with national semiconductor strategies, creating divergent qualification requirements across regulatory jurisdictions.
- Cloud Service Providers:Direct-to-cloud procurement channels compress distributor margins and demand multi-year volume commitments from captive foundries. United States-based hyperscalers anchor global silicon photonics wafer consumption.
- Network Operators:Incumbent telecom carriers in China and Germany maintain stringent reliability standards and backward compatibility requirements that slow technology transitions.
- Sensor Manufacturers:FDA-regulated biomedical device firms and industrial monitoring specialists require traceable manufacturing records and extended environmental testing protocols.
- Computing Hardware Vendors:Switch silicon vendors integrating photonics chiplets at package level are displacing traditional pluggable module suppliers and capturing optical margin pools.
Cloud service providers drive the largest procurement volumes. Computing hardware vendors are gaining share fastest through co-packaged optics integration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landings at Virginia Beach and Los Angeles anchor trans-Pacific bandwidth flows that drive PIC demand in United States data centers. China's Yangtze River Delta fiber backbones connect Shanghai's foundry clusters to Beijing's cloud computing campuses. Germany's DE-CIX internet exchange in Frankfurt funnels European data traffic through photonic switching hubs.
United States
Hyperscale operators in Ashburn and Santa Clara are deploying 800G optical modules at rack scale, creating concentrated demand for co-packaged silicon photonics. The FCC governs optical transmission equipment certification under Part 15 and Part 68 rules, with compliance timelines often dictating product launch windows. Intel's captive foundry in Hillsboro, Oregon controls wafer supply from design to package for domestic cloud procurement.
China
Domestic equipment vendors in Shenzhen and Wuhan are scaling 400G/800G optical module production for national cloud infrastructure buildouts. MIIT enforces GB standards for optical module interoperability, creating certification requirements that foreign suppliers must clear for market access. Shanghai's Zhangjiang Hi-Tech Park hosts foundry investments accelerating captive supply chain formation for local PIC consumption.
Germany
Network operators in Frankfurt and Munich maintain stringent reliability standards for coherent transmission infrastructure spanning metro and long-haul fiber links. REACH and RoHS frameworks constrain material selection for indium phosphide device processing, inflating foundry compliance costs by 15-20%. Berlin-Adlershof research clusters are qualifying ring resonator architectures for photonic matrix multiplication in pre-commercial optical computing platforms.
Japan
Two domestic suppliers control 80% of high-purity indium phosphide wafer supply for telecom-grade laser fabrication, creating single-source vulnerability for global PIC production. METI coordinates national semiconductor strategy investments targeting compound semiconductor ecosystem resilience. Tsukuba's photonics research institutes are advancing thin-film lithium niobate modulator qualification for coherent transmission applications.
South Korea
Memory semiconductor giants in Gyeonggi Province are evaluating photonics chiplets for package-level integration with high-bandwidth compute silicon. MFDS regulates PIC-based biomedical sensors through device classification pathways separate from telecom certification. Seoul's Pangyo Techno Valley hosts optical component specialists supplying both domestic electronics vendors and export markets.
Global Photonic Integrated Circuits (PIC) Market Key Industry Players
On the supply side, the industry is consolidating around captive foundry capacity and backward integration into laser fabrication. Tier-one semiconductor vendors with in-house silicon photonics processes are displacing legacy discrete optical assemblers. Two strategic archetypes dominate: CMOS-compatible platform operators leveraging 300mm wafer economics, and compound semiconductor specialists preserving margin pools in high-performance laser applications. Competitive moves center on multi-year wafer supply agreements with hyperscale buyers and qualification of alternative substrate materials to reduce indium phosphide supply concentration.
Within the captive foundry tier, Intel Corporation exemplifies vertical control from design through packaging, while Broadcom Inc. anchors a position through upstream laser fabrication capabilities. Lumentum Operations LLC occupies a specialized niche extending beyond telecom into sensing applications. These three entities represent distinct competitive postures: semiconductor infrastructure reuse, compound semiconductor margin capture, and application diversification beyond traditional optical interconnects.
| Leading Market Players |
|---|
| Intel Corporation |
| Infinera Corporation |
| Cisco Systems, Inc. |
| Broadcom Inc. |
| Lumentum Operations LLC |
| Ciena Corporation |
| MACOM |
| EMCORE Corporation |
| Acacia Communications, Inc. |
| Others |
Cost & Logistics Intelligence
Shanghai's Zhangjiang Hi-Tech Park foundry cluster concentrates 300mm silicon photonics capacity that feeds directly into hyperscale procurement negotiations, compressing distributor margins and shifting pricing power toward captive wafer supply agreements. This geographic concentration of advanced fabrication enables volume-discount tiering that rewards multi-year commitments from United States cloud operators while squeezing smaller module vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates telecom-grade indium phosphide devices with hermetic packaging guarantees from data center silicon photonics modules and consumer-grade sensing components. Price differentiation hinges on certification grade—FCC Part 68 and China MIIT GB compliance timelines inflate premium tier quotes—and volume scale, where hyperscale direct procurement captures 40-60% discounts off catalog pricing. Cost compression in the standard tier intensifies as switch silicon vendors integrate photonics chiplets and displace pluggable module suppliers. Cloud service providers exhibit the highest price sensitivity, demanding energy-per-bit metrics in procurement criteria, while biomedical sensor manufacturers prioritize FDA breakthrough device pathway speed over unit cost.
Supply Chain Analysis
Export control regimes restricting extreme ultraviolet lithography equipment and compound semiconductor precursor chemicals constrain foundry capacity allocation between silicon photonics and advanced logic nodes. Geographic supply concentration centers on Taiwan and the United States for 300mm CMOS-compatible fabrication, Japan for high-purity indium phosphide substrates, and Germany for specialized lithium niobate modulator processing. Raw material dependencies include silicon-on-insulator wafers, indium phosphide ingots from Sumitomo and JX Nippon, and rare-earth doped fibers for amplifier applications. Single-source vulnerability in Japanese substrate supply creates structural risk for telecom-grade laser fabrication. Distribution runs through direct-to-cloud procurement channels that bypass traditional optical component distributors, with hyperscale buyers negotiating wafer supply agreements directly with Intel, TSMC, and domestic Chinese foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across material platforms and application requirements creates entry niches for specialists, as data center commoditization pressure diverges from biomedical and optical computing premium margin pools.
For Market Incumbents: Insulate coherent transmission margins by securing long-term indium phosphide substrate supply agreements with Japanese suppliers before alternative qualification completes. Defend silicon photonics volume positions through backward integration into laser fabrication, matching Broadcom's compound semiconductor capabilities. Prioritize certification investment in FDA breakthrough device pathways for biomedical sensor diversification, reducing exposure to hyperscale procurement compression. For New Entrants and Emerging Players: Mid-market enterprise data centers in Germany and South Korea represent the most penetrable entry point, as these buyers lack direct-to-cloud procurement scale but demand energy efficiency metrics absent from catalog vendor offerings. Optical computing research clusters in Berlin-Adlershof and United States national laboratories offer design win opportunities before commercial volume requirements materialize. Go-to-market positioning should emphasize design services and small-batch prototyping rather than competing on wafer volume commitments. For Investors and Strategic Acquirers: Long-term, this sits as a compound semiconductor infrastructure play because silicon photonics process maturation will commoditize optical interconnects while indium phosphide and thin-film lithium niobate retain premium margin pools in coherent transmission and sensing applications. Acquisition targets should display captive foundry relationships or specialized packaging capabilities for thermomechanical yield management. The signal to watch is qualification timelines for alternative indium phosphide substrate suppliers, which would decompress supply constraints and reset margin structures across telecom-grade laser fabrication.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Investment | Intel's Hillsboro facility demonstrates vertical control from design through packaging for domestic cloud procurement. |
| Backward Integration into Laser Fabrication | Broadcom's indium phosphide capabilities preserve margin pools where silicon photonics hits thermal limits. |
| Biomedical Sensor Certification Pathway | FDA breakthrough device status compresses timelines for glucose and pathogen detection platform commercialization. |
| Co-Packaged Optics Integration | Switch silicon vendors capturing optical margin pools displace traditional pluggable module suppliers at package level. |
| Alternative Substrate Qualification | Reducing dependence on Japanese indium phosphide suppliers mitigates single-source vulnerability for telecom-grade fabrication. |
Research Approach
Initial hypotheses were tested against primary input from PIC design engineers, foundry operations directors, hyperscale procurement managers, and telecom network planning officers and refined through secondary validation against SEC filings from optical component vendors, FCC equipment authorization databases, China MIIT GB standard releases, and ECHA REACH authorization updates. Bottom-up triangulation across wafer supply agreements and top-down reconciliation against national semiconductor strategy disclosures anchored volume estimates.
Demand-supply balance framing shaped the analytical framework across the projection horizon, modeling segmentation dimensions including material platform, modulation architecture, application vertical, and end-user procurement channel. CAGRs derived from foundry capacity expansion announcements, hyperscaler capex disclosures, and optical module shipment data. Industry-specific forecast inputs included EUV lithography capacity allocation schedules and indium phosphide substrate supply commitments from Japanese suppliers.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, compound semiconductor precursor chemical pricing, or data center construction timelines would shift the trajectory. Forecasts reflect assumptions regarding process yield maturation and regulatory certification synchronization across FDA, FCC, and MIIT jurisdictions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Mixed Signal IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Japan Analog IC Market