
 Global Small Cell Power Amplifier Market | 2026-2036
Global Small Cell Power Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Cell Power Amplifier Market Intelligence
Gallium Nitride (GaN) semiconductor fabrication capacity for radio frequency applications is consolidating among a few specialized foundries. Qorvo leverages its extensive portfolio of RF front-end modules to serve diverse small cell configurations. NXP Semiconductors competes strongly in the market with its LDMOS and advanced GaN technologies for cellular infrastructure. Skyworks Solutions specializes in highly integrated and power-efficient solutions for 5G small cell systems.
A small cell power amplifier is a critical radio frequency component designed to boost signal strength for transmission in compact base stations. These devices must maintain high linearity and efficiency, often measured by Error Vector Magnitude (EVM), while operating across a wide range of 4G and 5G frequency bands. The 5G NR technology segment represents the fastest-growing category, demanding amplifiers with wider bandwidth. Indoor installations for enterprises and private networks constitute a significant volume segment, prioritizing power efficiency and compact form factors.
Regulatory bodies like the US Federal Communications Commission (FCC) and China's Ministry of Industry and Information Technology (MIIT) govern spectrum allocation and device certification. Conformance with standards from organizations such as the European Telecommunications Standards Institute (ETSI) is mandatory for market access, influencing design and testing protocols. Component selection strategy, particularly the trade-off between Gallium Nitride and LDMOS technologies, remains a critical decision point for system OEMs.
Market Dynamics
The central dynamic shaping the market is the relentless network densification driven by telecom operators to deliver 5G mobile broadband. This requires a massive rollout of small cells, directly fueling demand for power amplifiers optimized for new spectrum bands.
Growth Catalysts
- 5G NR Technology Transition:The shift to 5G New Radio standards necessitates power amplifiers capable of handling wider bandwidths and complex modulation schemes like 256-QAM, which is a direct catalyst for next-generation component sales.
- Private Network Deployment:Enterprises are increasingly deploying private 4G and 5G networks for industrial automation and secure campus connectivity, creating a high-volume demand segment for indoor small cell systems and their associated power amplifiers.
- Spectrum Availability:Regulatory actions by bodies such as the US Federal Communications Commission (FCC) and China's MIIT to release new mid-band and millimeter-wave spectrum directly stimulate investment in compatible small cell hardware.
Market Restraints
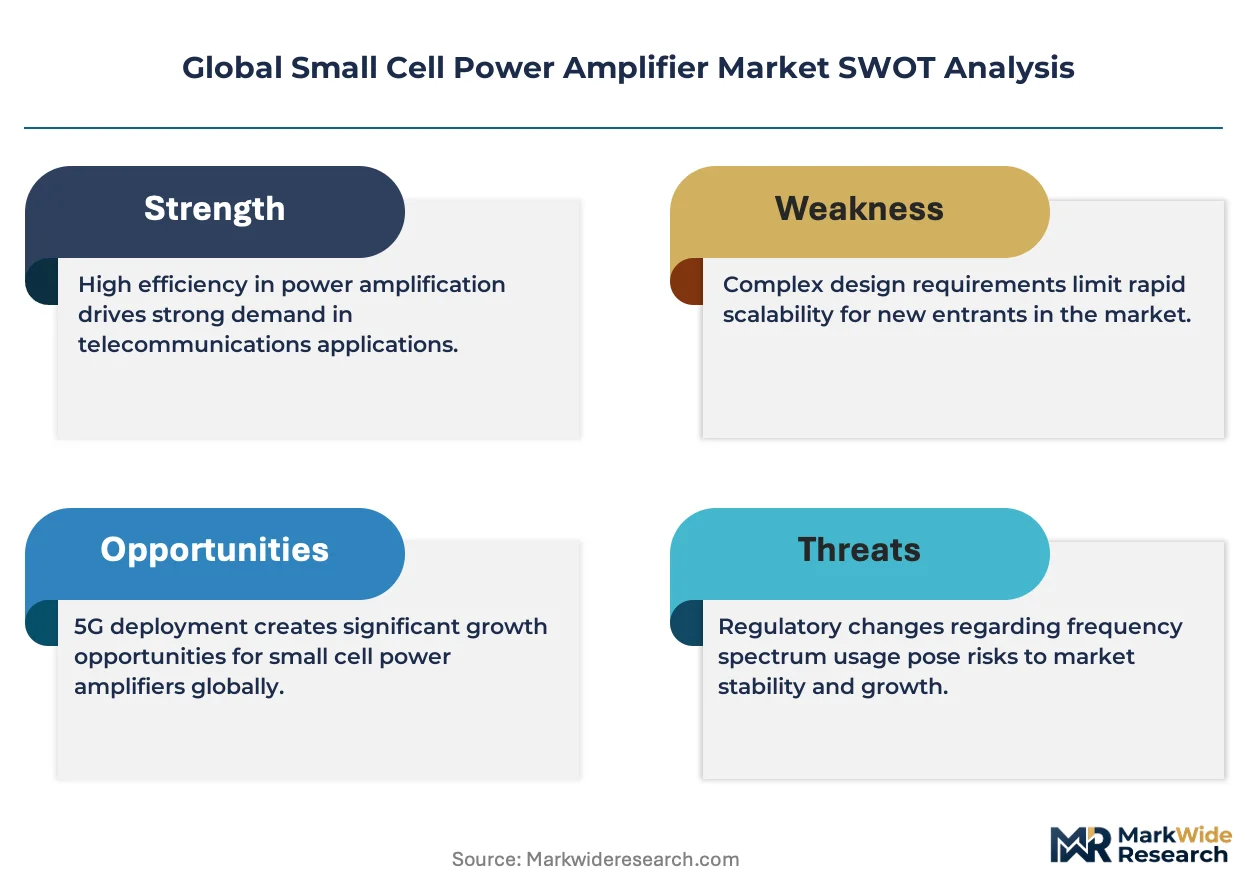
- GaN Cost Premium:The higher substrate and fabrication cost of Gallium Nitride (GaN) technology compared to established LDMOS acts as a restraint, particularly for cost-sensitive, large-scale deployments in developing markets.
- Thermal Management Complexity:Increasing power density within compact small cell enclosures creates significant thermal challenges, requiring advanced heat dissipation solutions that add to the overall system cost and design complexity.
- Foundry Concentration:The fabrication of high-performance RF GaN devices is concentrated among a few specialized foundries, creating potential supply chain bottlenecks and giving these suppliers significant pricing power.
Strategic Opportunities
- Open RAN Architectures:The move towards Open Radio Access Network (O-RAN) standards disaggregates hardware and software, creating opportunities for specialized power amplifier vendors to sell directly to system integrators and new market entrants.
- Multi-Band Amplifier Development:There is a significant opportunity in designing highly integrated power amplifiers that can operate across multiple 4G and 5G frequency bands, reducing component count and simplifying small cell radio design.
- Emerging Market Expansion:Regions such as India and Southeast Asia are in the early stages of their 5G build-outs, representing a substantial, underpenetrated geographic opportunity for small cell component suppliers over the next decade.
Industry Challenges
- Digital Pre-Distortion Integration:Achieving optimal linearity and efficiency requires tight integration and co-design between the power amplifier and the digital pre-distortion (DPD) algorithm, a complex engineering challenge for system designers.
- Stringent Certification Requirements:Navigating the lengthy and rigorous device certification processes mandated by bodies like the ETSI in Europe can significantly delay time-to-market for new power amplifier products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Cell Power Amplifier Market |
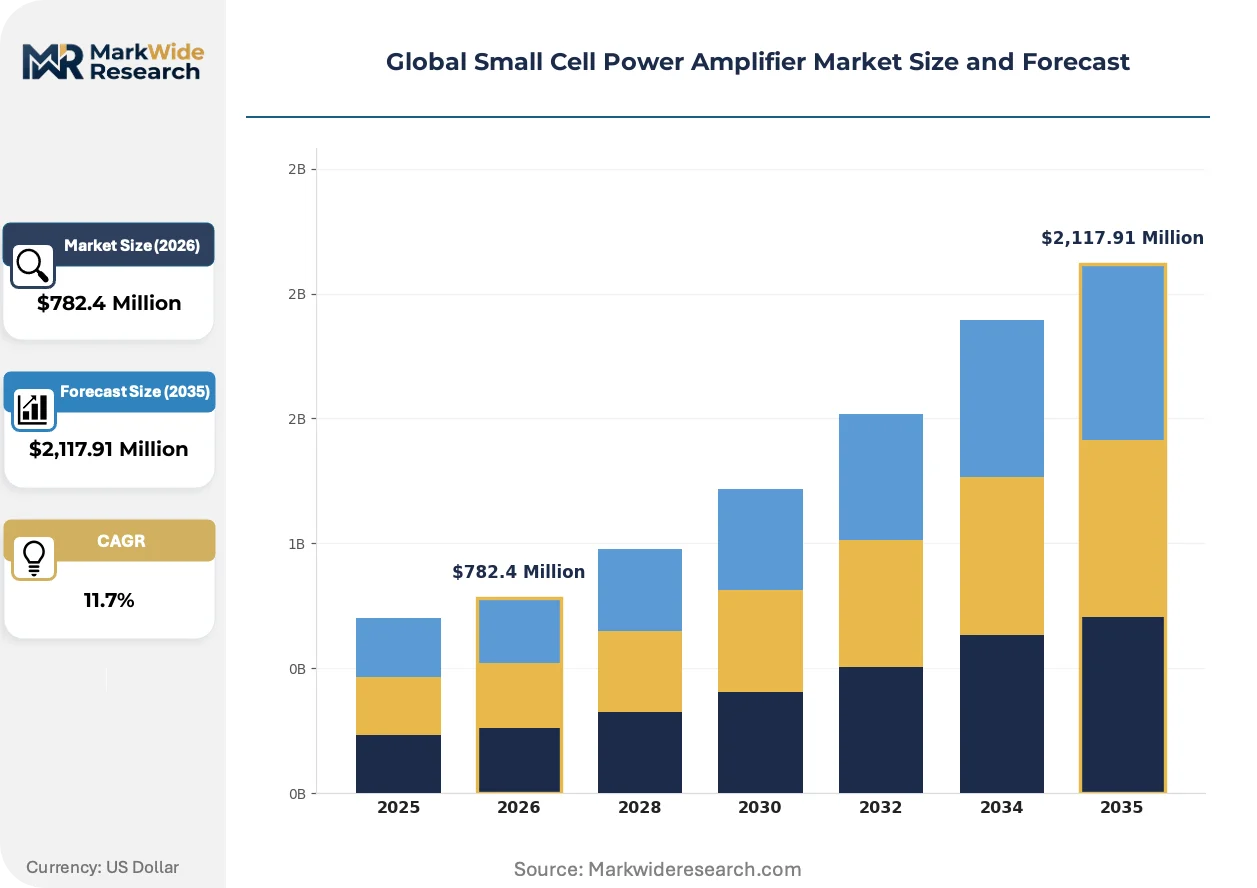
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $2,117.91 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Amplifiers, Class D Amplifiers, Integrated Circuits, Power Sensors End User: Telecom Service Providers, Enterprises, Government Agencies, OEMs Technology: 4G LTE, 5G NR, Wi-Fi, TDD Installation Type: Indoor, Outdoor, In-vehicle, Desktop |
| Companies Covered | Broadcom, Qorvo, NXP Semiconductors, Texas Instruments, Skyworks Solutions, Qualcomm, RFHIC Corporation, Infineon Technologies, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Cell Power Amplifier Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward higher integration and efficiency to meet the performance and cost demands of dense 5G networks. This is driving fundamental shifts in semiconductor material choice, regulatory alignment, and component sourcing models across the ecosystem.
Gallium Nitride (GaN) provides superior power efficiency and bandwidth performance essential for high-frequency 5G applications. System OEMs are specifying GaN for virtually all new outdoor and high-capacity indoor small cell designs to meet stringent linearity and power requirements. This rapid adoption is consolidating the performance segment of the market around GaN-based solutions, pushing LDMOS technology into legacy or lower-frequency roles.
China's Ministry of Industry and Information Technology (MIIT) has allocated significant spectrum in the sub-6 GHz and millimeter-wave ranges to accelerate its national 5G infrastructure program. This policy directly fuels massive procurement cycles for small cell equipment from domestic telecom operators. The power amplifier segment is most impacted, as components must be specifically designed to meet MIIT's band plans and emissions certifications to gain market access.
A shift toward disaggregated network models, especially Open RAN, is changing how components are specified and bought. Instead of sourcing complete base stations from a single OEM, network operators and integrators are purchasing radio units and power amplifiers from a more diverse set of vendors. This trend is particularly evident in private network deployments for industrial use in North America and Europe, fostering a more competitive component landscape.
Global Small Cell Power Amplifier Market Segmentation
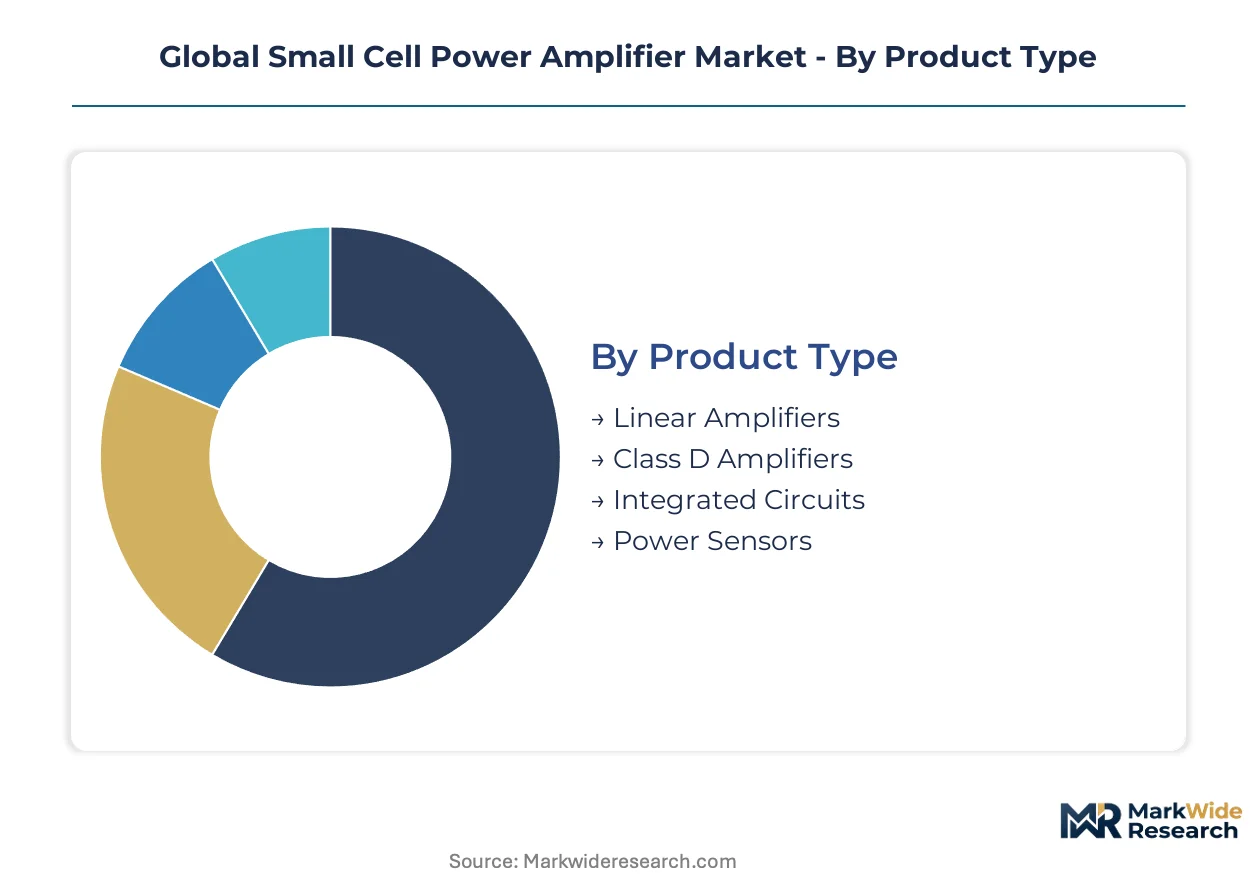
The global small cell power amplifier market exhibits diverse segmentation, reflecting varied technological requirements, deployment scenarios, and end-user demands. Understanding these segments is crucial for component manufacturers to align product development with specific market needs and for network operators to optimize infrastructure investments.
Product Type:
The market for small cell power amplifiers differentiates components based on their core operational specifications and design principles.
- Linear Amplifiers:These devices maintain signal fidelity across wide bandwidths, crucial for complex 5G NR modulations like 256-QAM. Demand is concentrating in high-capacity outdoor and enterprise indoor small cells, driven by stringent linearity and error vector magnitude (EVM) requirements.
- Class D Amplifiers:These amplifiers offer high power efficiency, converting most input power into output power with minimal heat dissipation. Their compact form factor and energy savings are particularly valuable for cost-sensitive, high-volume deployments in developing markets.
- Integrated Circuits:These solutions combine multiple RF functions onto a single chip, reducing board space and simplifying design. Demand is strong in compact indoor small cells and private network equipment, where space constraints and rapid deployment are critical considerations.
- Power Sensors:These components accurately measure RF power levels, enabling real-time monitoring and dynamic power adjustments. They are essential for optimizing network performance and ensuring regulatory compliance across diverse small cell deployments.
Mature deployment sits with Class D Amplifiers. Newer deployment is concentrated in Linear Amplifiers.
End User:
Demand for small cell power amplifiers varies significantly across different customer segments, each with distinct network requirements.
- Telecom Service Providers:These entities deploy small cells for network densification, enhancing mobile broadband coverage and capacity. Their procurement focuses on high-performance, scalable power amplifiers capable of supporting millions of subscribers across global 4G and 5G networks.
- Enterprises:Businesses install small cells to create private 4G/5G networks for industrial automation, smart buildings, and secure campus connectivity. This segment prioritizes power amplifiers with robust security features, compact form factors, and seamless integration into existing IT infrastructure.
- Government Agencies:Public sector bodies utilize small cells for mission-critical communications, smart city initiatives, and public safety networks. Their requirements often include high reliability, secure operation, and compliance with specific national communication standards.
- OEMs:Original Equipment Manufacturers integrate power amplifiers into their small cell radio units and base station products. Their focus is on component performance, cost-effectiveness, and ease of integration into their proprietary hardware designs.
Enterprises and Government Agencies are driving specialized deployments, while Telecom Service Providers continue to represent the largest volume segment.
Technology:
The small cell power amplifier market is characterized by a rapid evolution in underlying wireless communication technologies.
- 5G NR:This technology segment represents the forefront of network evolution, demanding power amplifiers with wider bandwidths and support for complex modulation schemes. China's massive 5G infrastructure build-out program significantly drives demand for these advanced components.
- 4G LTE:This established technology continues to see significant investment in densification, particularly in emerging markets and for enterprise private networks. Power amplifiers for 4G LTE require high efficiency and robust performance across various frequency bands.
- Wi-Fi:Small cell power amplifiers for Wi-Fi applications focus on enhancing indoor coverage and capacity, particularly for public Wi-Fi hotspots and enterprise wireless networks. These components prioritize power efficiency and cost-effectiveness.
- TDD:Time Division Duplex technology requires power amplifiers capable of rapid switching between transmit and receive modes. This is critical for efficient spectrum utilization in many 4G and 5G deployments, especially in mid-band frequencies.
5G NR technology is expanding most quickly, while 4G LTE maintains a substantial installed base.
Installation Type:
Small cell power amplifier deployment scenarios are categorized by their physical environment and operational context.
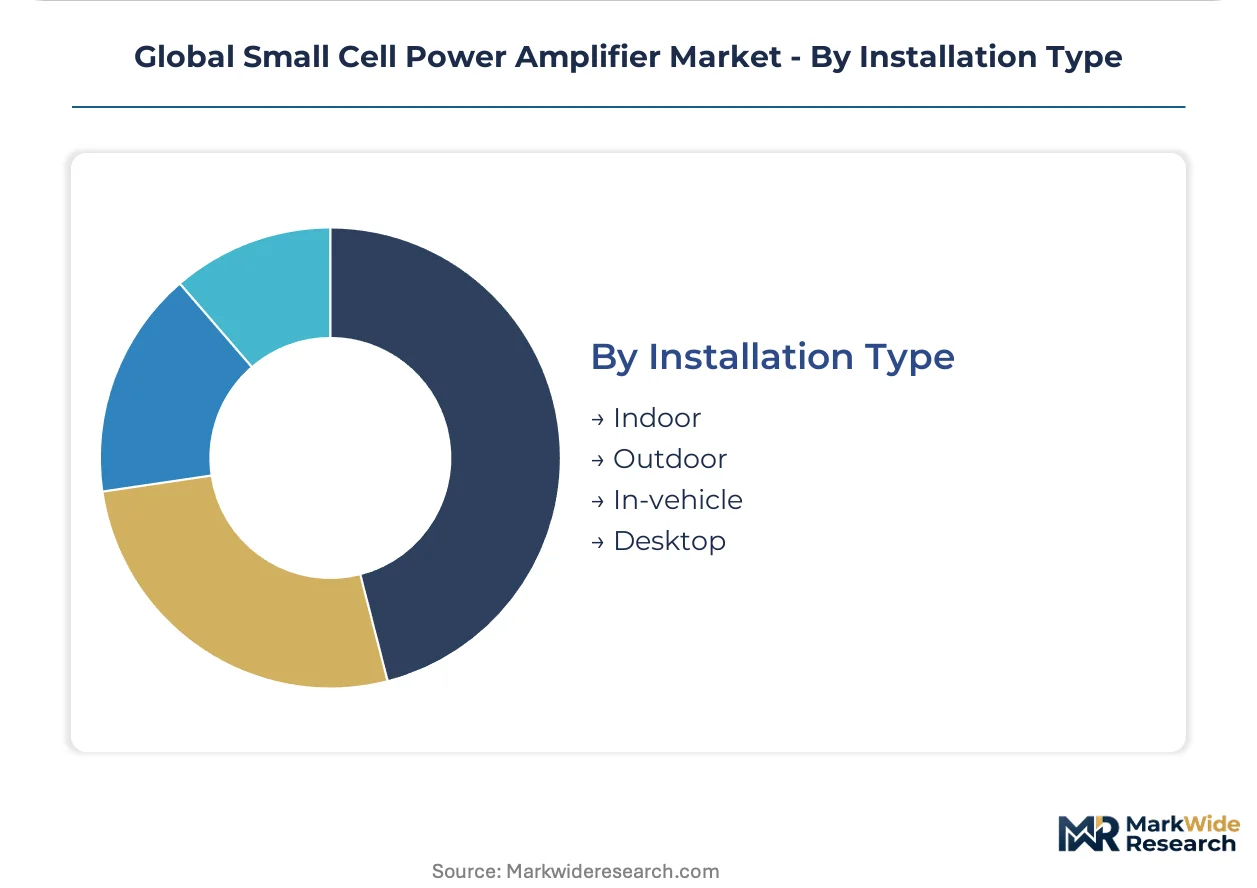
- Indoor:These installations cater to enterprise buildings, public venues, and residential complexes, providing localized coverage and capacity. Indoor small cells prioritize compact size, low power consumption, and aesthetic integration, creating a high-volume segment.
- Outdoor:Outdoor small cells are deployed on street furniture, utility poles, and building facades to offload macro cell traffic and fill coverage gaps. These require robust, weather-resistant power amplifiers capable of high output power and broad temperature range operation.
- In-vehicle:This segment includes small cells deployed within transportation systems like buses, trains, and autonomous vehicles. Power amplifiers for this use case need to withstand vibration, operate reliably in mobile environments, and integrate with vehicle power systems.
- Desktop:Desktop small cell units are typically plug-and-play devices for small offices or homes, offering easy deployment. Power amplifiers in these units emphasize simplicity, low cost, and minimal heat generation for consumer-grade applications.
Indoor installations represent a high-volume segment, whereas Outdoor deployments address broader coverage and capacity needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor manufacturing anchors the global small cell power amplifier market. Demand for these components is geographically diverse, reflecting varied stages of 5G deployment and regulatory frameworks. Each region presents unique opportunities and challenges for component suppliers.
China
The country's massive 5G infrastructure build-out program drives significant demand for advanced power amplifiers. China's Ministry of Industry and Information Technology (MIIT) allocates spectrum in sub-6 GHz and millimeter-wave bands, shaping component design. Shenzhen's technology manufacturing ecosystem serves as a primary hub for small cell equipment production.
United States
Robust 5G NR deployment and enterprise private network initiatives generate substantial demand. The US Federal Communications Commission (FCC) actively releases new mid-band and millimeter-wave spectrum, stimulating hardware investment. Silicon Valley's semiconductor research and development centers lead innovation in RF technologies.
Germany
Enterprise private networks for industrial automation are a key demand driver for small cell power amplifiers. Conformance with European Telecommunications Standards Institute (ETSI) standards is mandatory for market access. Bavaria's industrial technology clusters are active in developing and deploying advanced manufacturing solutions.
India
Early stages of 5G build-out represent a significant, underpenetrated geographic opportunity. Government spectrum auctions and initiatives accelerate network densification across urban and rural areas. Bengaluru's burgeoning IT and telecom R&D sector supports local network infrastructure development.
South Korea
Advanced 5G adoption and high-capacity network requirements sustain strong demand for sophisticated power amplifiers. Government incentives and policies encourage rapid 5G rollout and technological leadership. Gyeonggi Province's semiconductor industry forms a critical part of the global supply chain for these components.
Global Small Cell Power Amplifier Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue highly integrated and specialized RF front-end solutions. The market exhibits a tiered structure, with a few large integrated device manufacturers (IDMs) competing with specialized RF component providers. Strategic archetypes include broad-portfolio semiconductor giants, dedicated RF power amplifier specialists, and niche GaN foundry services. Technology licensing and strategic partnerships are dominant competitive moves among market participants.
RF specialists like Qorvo leverage their extensive portfolio of RF front-end modules to serve diverse small cell configurations. NXP Semiconductors exemplifies a major semiconductor company competing strongly with both LDMOS and advanced GaN technologies for cellular infrastructure. Skyworks Solutions represents a focused player specializing in highly integrated and power-efficient solutions tailored for 5G small cell systems.
| Leading Market Players |
|---|
| Broadcom |
| Qorvo |
| NXP Semiconductors |
| Texas Instruments |
| Skyworks Solutions |
| Qualcomm |
| RFHIC Corporation |
| Infineon Technologies |
| Analog Devices |
| Others |
Cost & Logistics Intelligence
Energy efficiency mandates from bodies like ETSI gate qualified supply access for small cell power amplifiers, directly influencing premium-tier pricing. These regulations ensure components meet stringent performance criteria, particularly for 5G NR deployments.
Pricing Analysis
Warranty and service bundling often differentiate small cell power amplifier pricing, particularly for specialized enterprise deployments requiring ongoing support. Per-unit transactional pricing dominates for standard components, though larger OEM contracts feature long-term offtake agreements. Price differentiation stems from GaN technology performance and stringent regulatory certifications like ETSI conformance. Pricing pressure arises from the higher substrate cost of GaN, making cost-sensitive developing markets the most price-sensitive segment.
Supply Chain Analysis
Gallium Nitride (GaN) wafer supply heavily relies on specialized foundries primarily located in East Asia, particularly South Korea and Taiwan. These foundries produce the critical substrates for high-performance RF devices. Geographic concentration creates single-source vulnerability, a significant supply chain risk for advanced components. Distribution runs through integrated device manufacturers and specialized RF component providers, who then supply small cell OEMs and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The small cell power amplifier market is consolidating, driven by stringent certification requirements that favor established players with deep regulatory expertise. This pressure is forcing out weaker players unable to meet the complex compliance demands for 5G NR technology.
For Market Incumbents:Extend GaN technology leadership by investing in advanced material science and next-generation packaging solutions. Incumbents must also deepen their expertise in digital pre-distortion (DPD) algorithm co-design to counter performance challenges from new entrants in Open RAN architectures. This strategic R&D investment protects against margin erosion from commoditization of older LDMOS technologies.
For New Entrants and Emerging Players:Multi-band amplifier development offers a technology-first wedge into the fragmented Open RAN ecosystem. New entrants should target highly integrated solutions for enterprise private networks in North America and Europe, where specialized performance outweighs volume-driven cost sensitivity. A direct-to-system integrator go-to-market angle bypasses traditional OEM channels.
For Investors and Strategic Acquirers:China's MIIT policy shifts regarding domestic GaN production are the leading indicator for long-term supply chain stability and pricing. Over a 5-10 year window, the market remains viable due to continuous 5G network densification. Investors should target specialized GaN foundry services or advanced DPD algorithm developers for strategic acquisition. The accelerated adoption of Open RAN architectures in Tier 1 telecom networks signals further market disaggregation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand GaN Fabrication Capacity | Ensures supply resilience for high-performance 5G components. |
| Develop Multi-Band RF Front-Ends | Reduces component count and simplifies small cell radio designs. |
| Invest in DPD Co-Design Platforms | Optimizes linearity and power efficiency for complex 5G modulations. |
| Secure ETSI/FCC/MIIT Certifications | Mandatory for market access in regulated US, European, and Chinese markets. |
| Form Open RAN Ecosystem Partnerships | Accesses new sales channels and system integrators in disaggregated networks. |
Research Approach
Trade association data, regulatory filings from the FCC and MIIT, and company annual reports anchored secondary inputs for this study. Primary research involved interviews with RF engineers, product managers from leading component suppliers, and telecom network architects. This approach ensured a robust understanding of market dynamics through both bottom-up component analysis and top-down network deployment strategies.
Market granularity was modeled across product type, end user, technology, and installation type, with a specific focus on semiconductor material adoption. Compound Annual Growth Rates were derived from historical growth patterns and projected 5G NR deployment speeds across the analysis window. Private network investment trends and regulatory spectrum allocations served as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including rapid geopolitical shifts impacting supply chains or unexpected material science breakthroughs. Forecasts reflect assumptions about stable regulatory environments and consistent 5G rollout trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
High Reliability Oscillators Market
RF Components
Wireless Module Market
RF Components
Power Amplifier Market
RF Components
Radio Frequency Front End Market
RF Components
Coaxial Splitters Market
RF Components
Multilayer Coupled Inductor Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
Small Signal Mosfets Market
RF Components
Wi-Fi Module Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
RF Microwave MLCC Market
RF Components
5G Gain Block Amplifier Market
RF Components
Flat Antenna Market
RF Components
Acoustic Wave Filters Market
RF Components
Europe Small Signal Transistor Market
RF Components
RFID Tags Market