
 Rugged IC Market | 2026-2036
Rugged IC Market Size, Share, and Industry Trends Forecast 2026-2036
Rugged IC Market Outlook
Asian foundry capacity for ceramic substrate packaging is decoupling from standard consumer IC supply chains as defense-qualified production lines command dedicated cleanroom allocations. Jabil leverages its vertical integration across PCB fabrication and IC assembly to secure long-term military contracts. Benchmark Electronics sustains competitive positioning through AS9100-certified facilities in North America. TTM Technologies anchors its rugged IC revenue in aerospace laminates with enhanced thermal management properties.
Rugged ICs are integrated circuits engineered to operate across extreme temperature ranges, typically rated for -55°C to +125°C, with hermetic sealing and ceramic or metal packaging that prevents moisture ingress and radiation-induced latch-up. These devices serve mission-critical functions in avionics, armored vehicle electronics, and downhole drilling systems where commercial-grade silicon would experience catastrophic failure. Military application demand leads the segment structure due to sustained procurement from defense ministries and prime contractors with multi-year program budgets. FPGA technology represents the fastest-growing technology category as reprogrammable logic enables field-upgradable radar and electronic warfare platforms without hardware replacement. Mixed-signal architectures occupy the deepest margin pools by combining precision analog sensing with digital signal processing in single-die solutions that reduce SWaP constraints.
FDA oversight of medical device electronics and FCC Part 15 emissions rules create dual compliance burdens for rugged IC suppliers serving both military and healthcare instrumentation end users. The EPA's restrictions on hexavalent chromium in metal plating force substrate manufacturers to qualify alternative passivation chemistries for connector housings. MIL-STD-883H test methods from the U.S. Department of Defense remain the de facto global benchmark for qualification, with deviations requiring customer-specific validation protocols. Stakeholders must monitor how export control expansions under the U.S. Bureau of Industry and Security affect cross-border shipment of radiation-hardened microcontrollers to allied defense programs.
Market Dynamics
Defense procurement cycles are compressing qualification timelines for radiation-hardened components, forcing foundries to parallelize MIL-STD-883H testing with design validation rather than running sequential stage-gates.
Growth Catalysts
- FPGA reprogrammability:Field-upgradable logic arrays eliminate hardware replacement costs in electronic warfare platforms, cutting deployment timelines from years to months.
- MIL-STD-883H thermal cycling:Tightened U.S. Department of Defense protocols for ceramic package integrity are filtering out marginal suppliers and concentrating procurement among qualified vendors.
- Bavarian aerospace corridor:Industrial automation OEMs in southern Germany source radiation-tolerant power amplifiers for satellite manufacturing, creating dedicated demand clusters.
Market Restraints
- Hexavalent chromium restrictions:EPA plating regulations force substrate manufacturers to requalify alternative passivation chemistries, extending connector housing certification by 8-14 months.
- Ceramic substrate supply concentration:Asian foundry capacity for defense-qualified packaging operates on dedicated cleanroom allocations, creating allocation risk during surge procurement.
- Dual-use compliance burden:FDA medical device oversight layered with FCC Part 15 emissions rules forces rugged IC suppliers to maintain parallel quality systems for healthcare and military end users.
Strategic Opportunities
- Downhole drilling systems:Oilfield service contractors in North Dakota and Texas require hermetically sealed controllers rated for 200°C ambient operation, a specification bracket above commercial industrial grades.
- AS9100-certified contract manufacturing:Aerospace laminates with enhanced thermal management properties anchor revenue streams for North American assembly houses serving prime contractors.
- Export control arbitrage:Bureau of Industry and Security restrictions on radiation-hardened microcontroller shipments create compliance service opportunities for logistics providers navigating allied defense program exceptions.
Industry Challenges
- SWaP-constrained integration:Mixed-signal architectures combining precision analog sensing with digital processing require rare cross-functional design teams fluent in both domains.
- Hermetic sealing equipment:Electron beam welding systems for ceramic package closure carry 7-figure capital costs and 18-month lead times, freezing out mid-tier entrants.
- Customer-specific validation protocols:Deviations from MIL-STD-883H benchmarks demand bilateral negotiation with defense primes, extending sales cycles and freezing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugged IC Market |
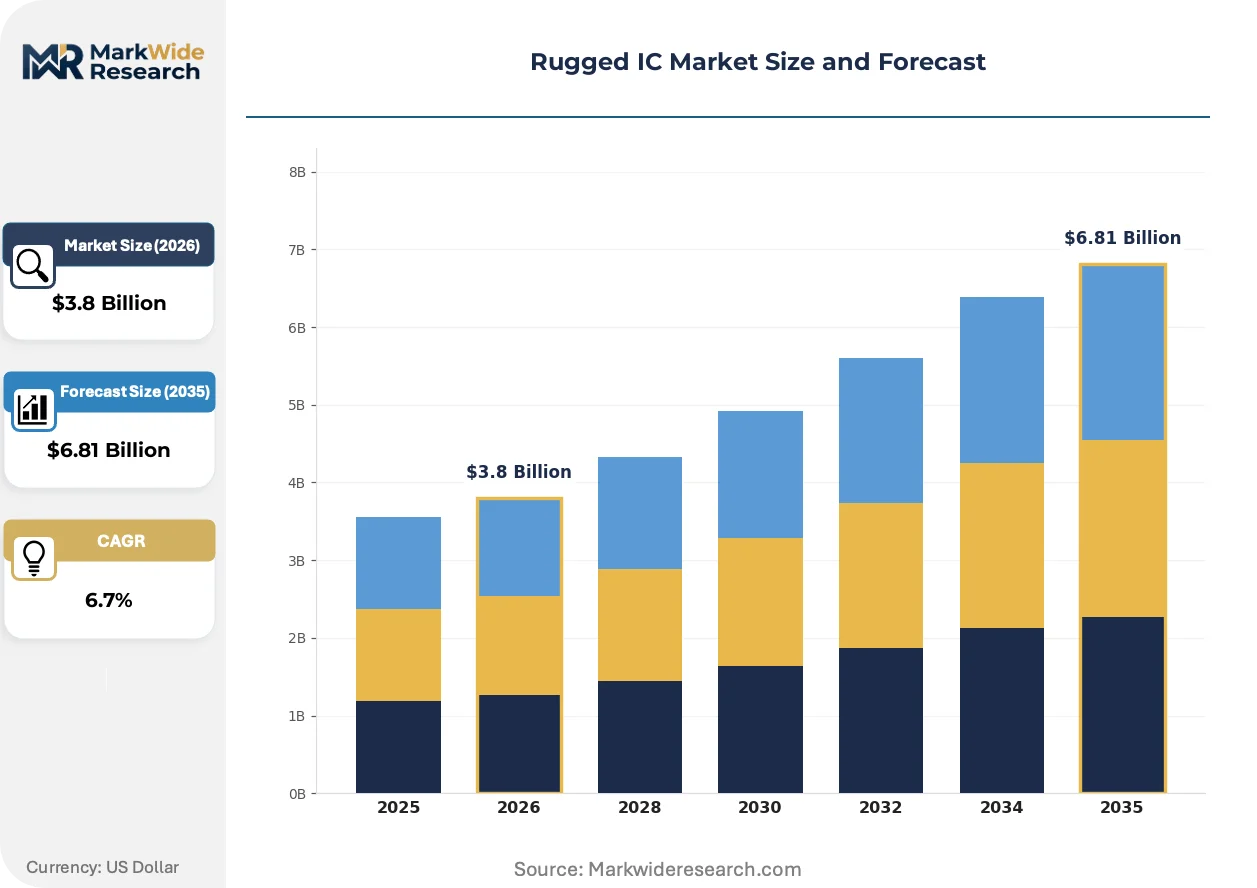
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RF Modules, Power Amplifiers, Sensors, Microcontrollers Application: Military, Automotive, Industrial Automation, Aerospace Technology: Analog, Digital, Mixed-Signal, FPGA End User: OEMs, System Integrators, Research Institutions, Government |
| Companies Covered | Jabil, Benchmark Electronics, Firan Technology Group Corporation, Summit Interconnect, Advanced Circuits, TTM Technologies, Amphenol Printed Circuits, APCT, Sanmina Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugged IC Market Strategic Shifts
Reprogrammable logic and heterogeneous integration are compressing the traditional boundary between discrete analog components and digital signal processing, reshaping how ruggedized systems achieve fault tolerance.
Silicon-germanium heterojunction bipolar transistors are consolidating the front-end signal conditioning chain in radar receivers. Defense primes in the United States and Germany have adopted SiGe BiCMOS processes for active electronically scanned arrays, collapsing separate LNA and mixer stages into single-die solutions. This consolidation is compressing board area requirements by 40-60% while maintaining noise figures below 2 dB.
REACH substance restrictions on lead-bearing solders are forcing European aerospace suppliers to qualify silver-sintered die-attach materials for high-reliability thermal interfaces. ECHA candidate list expansions covering bismuth and indium alloys are triggering reformulation cycles in hermetic package sealing. German satellite manufacturers now require full material declaration documentation upstream of AS9100 audits, shifting compliance burden to tier-two substrate vendors.
Armored vehicle electronics programs are unbundling hardware procurement from sustainment contracts, separating initial platform integration from decade-long spares and upgrade pathways. This unbundling is fragmenting buying authority across program offices and depot maintenance operations, forcing IC suppliers to maintain dual sales channels. The pattern is most visible in U.S. Army Ground Vehicle Systems Center acquisitions, where prime contractors now compete separately for production lots and field service engineering.
Rugged IC Market Segmentation
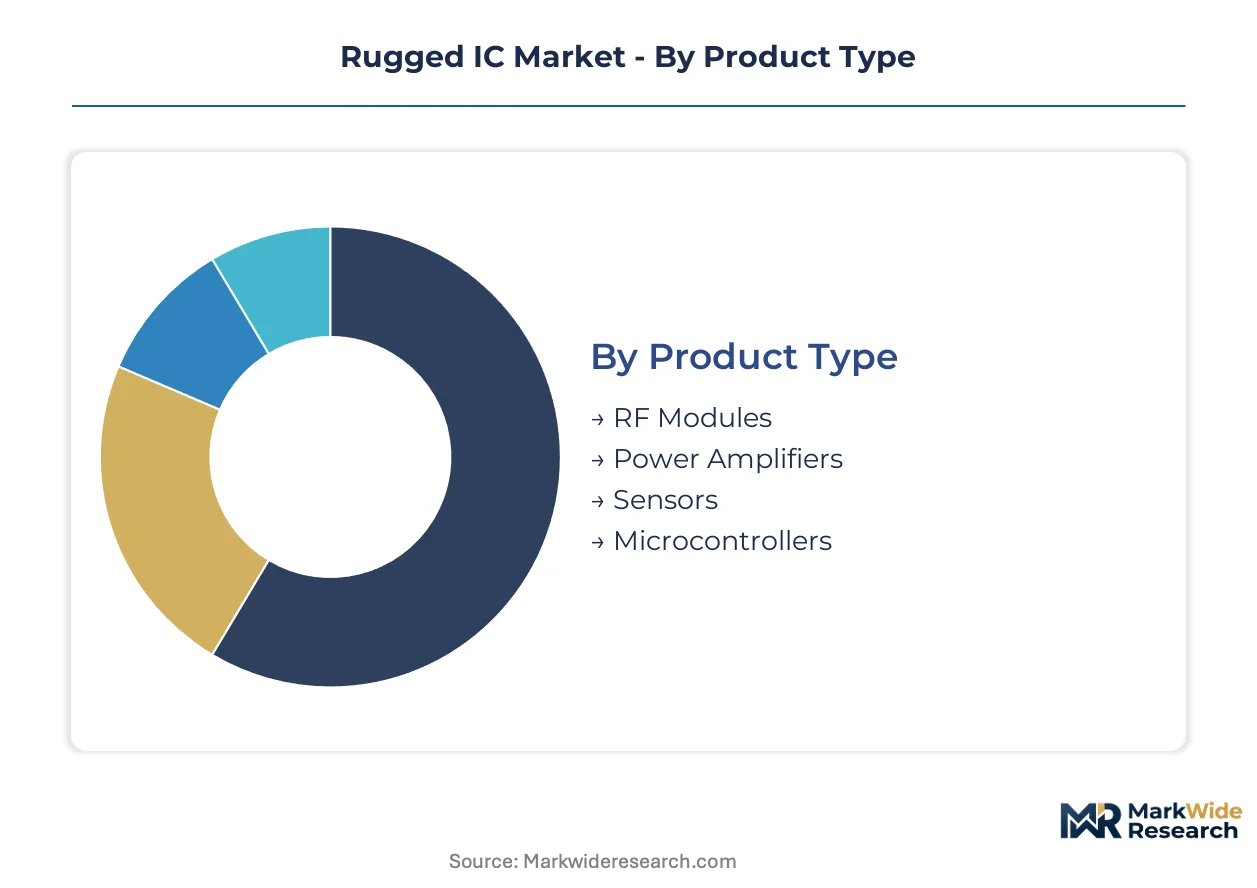
Rugged IC procurement patterns diverge sharply across application environments, with military programs prioritizing radiation hardness while industrial buyers optimize for thermal cycling endurance. Segmentation reveals how qualification requirements and replacement economics shape supplier-customer relationships across defense, aerospace, and energy sectors.
Product Type:
Upgrade cycles in legacy defense platforms are compressing procurement timelines, with field-replaceable modules now specified for 15-year service intervals rather than platform-matched lifespans.
- RF Modules:Front-end signal conditioning assemblies integrating LNA, mixer, and filter stages in hermetic metal-ceramic housings. U.S. Army electronic warfare programs in Aberdeen are driving demand for GaN-on-SiC power amplifiers with 40% bandwidth improvement over legacy GaAs designs.
- Power Amplifiers:Radiation-tolerant output stages delivering 100W+ continuous wave operation for satellite downlinks. Bavarian aerospace manufacturers in Ottobrunn source these specifically for geostationary telecommunications payloads requiring 15-year orbital reliability.
- Sensors:MEMS-based inertial measurement units with MIL-STD-810 shock qualification.
- Microcontrollers:Hardened 32-bit cores with latch-up immunity for avionics bus controllers.
Microcontrollers sit at the top of the volume ranking, with RF Modules climbing the fastest.
Application:
Cost-tier stratification separates military-qualified supply chains from commercial-industrial alternatives, with AS9100 certification adding 35-45% premium over standard automotive-grade components.
- Military:Battlefield communications and electronic warfare systems requiring full MIL-STD-883H qualification. Pentagon procurement offices are unbundling hardware acquisition from decade-long sustainment contracts, fragmenting buying authority across program offices and depot maintenance operations.
- Aerospace:Satellite avionics and launch vehicle guidance with radiation hardness assurance. German manufacturers in Bremen and Ottobrunn anchor European demand for latch-up-immune power management ICs in low-earth-orbit constellations.
- Automotive:Underhood engine controllers rated for 150°C ambient operation.
- Industrial Automation:Programmable logic controllers for foundry and smelting environments.
Military applications command the deepest margin pools, while Aerospace gains share fastest on constellation deployment timelines.
Technology:
Customer-type segmentation separates defense primes with captive qualification labs from commercial system integrators relying on vendor-supplied test data.
- FPGA:Reprogrammable logic arrays enabling field-upgradable radar and electronic warfare platforms without hardware replacement. Lockheed Martin and Raytheon programs are collapsing deployment timelines from years to months through in-flight reconfiguration capabilities.
- Mixed-Signal:Single-die solutions combining precision analog sensing with digital signal processing. These architectures occupy the deepest margin pools by reducing SWaP constraints in constrained avionics enclosures.
- Analog:Discrete voltage references and operational amplifiers with extended temperature ratings.
- Digital:Standard cell ASICs with radiation-hardened library elements.
Mixed-Signal dominates current revenue contribution, with FPGA expanding most quickly on reprogrammability premiums.
End User:
Supply concentration patterns favor OEMs with captive cleanroom allocations over fragmented research procurement.
- OEMs:Prime contractors and tier-one subsystem suppliers with direct defense program relationships. Boeing, Northrop Grumman, and BAE Systems maintain approved vendor lists that freeze out unqualified competitors for multi-year production lots.
- System Integrators:Mid-tier contractors assembling board-level solutions for platform integrators. These buyers face compressed qualification timelines as defense procurement cycles accelerate, forcing parallelized testing strategies.
- Government:Direct defense ministry procurement for strategic stockpiles.
- Research Institutions:National laboratories and university consortia with prototype-scale volumes.
OEMs sit at the top of the volume ranking, with System Integrators climbing the fastest on subcontractor consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply between Germany's Bavarian aerospace corridor and the Pentagon's unbundled acquisition model, while Asian foundry capacity concentrates in Taiwan and South Korea under dedicated cleanroom allocations.
United States
Pentagon procurement offices are fragmenting buying authority across program offices and depot maintenance operations through unbundled hardware-sustainment contracts. MIL-STD-883H qualification protocols from the U.S. Department of Defense tighten thermal cycling test standards for ceramic package integrity. Aberdeen Proving Ground anchors U.S. Army electronic warfare demand for GaN-on-SiC power amplifiers with 40% bandwidth improvement over legacy designs.
Germany
Bavarian aerospace manufacturers in Ottobrunn source radiation-tolerant power amplifiers specifically for geostationary telecommunications payloads requiring 15-year orbital reliability. ECHA REACH substance restrictions on lead-bearing solders force qualification of silver-sintered die-attach materials for high-reliability thermal interfaces. Bremen satellite manufacturers now require full material declaration documentation upstream of AS9100 audits, shifting compliance burden to tier-two substrate vendors.
Taiwan
Foundry capacity for ceramic substrate packaging operates on dedicated cleanroom allocations decoupled from standard consumer IC supply chains. The island's national technology development programs prioritize defense-qualified production lines for hardened microcontroller output. Hsinchu Science Park anchors radiation-hardened process development serving NATO-aligned defense programs.
South Korea
MFDS oversight creates parallel compliance tracks for medical device electronics alongside military procurement requirements. The country's national semiconductor initiative directs foundry investment toward heterogeneous integration processes for mixed-signal rugged ICs. Seoul Capital Area clusters house backend assembly operations for hermetically sealed controllers rated for 200°C ambient operation in downhole drilling applications.
Japan
METI industrial policy supports domestic capability in electron beam welding systems for ceramic package closure, equipment carrying 7-figure capital costs and 18-month lead times. JIS standards for extended temperature-rated components provide alternative qualification pathways for suppliers serving dual-use medical-military end markets. Kyushu region maintains specialized cleanroom allocations for defense-qualified ceramic substrate production.
Rugged IC Market Competitive Environment
North American producers anchor the premium-tier qualification vector; Asian specialists hold process-scale positions in ceramic substrate fabrication. The vendor base stratifies across three tiers: defense primes with captive qualification labs, AS9100-certified contract manufacturers, and mid-tier system integrators facing compressed testing timelines. Two dominant competitive moves are reshaping positioning: vertical integration across PCB fabrication and IC assembly, and geographic expansion of AS9100-certified facilities to capture unbundled sustainment contracts.
Within the vertically integrated tier, Jabil and Benchmark Electronics exemplify archetypes combining PCB fabrication with IC assembly capabilities. TTM Technologies occupies a position anchored in aerospace laminates with enhanced thermal management properties. These three companies represent distinct strategic postures: Jabil leverages captive supply chains for long-term military contracts; Benchmark Electronics sustains positioning through North American AS9100-certified facilities; TTM Technologies concentrates revenue in thermal-management substrate solutions.
| Leading Market Players |
|---|
| Jabil |
| Benchmark Electronics |
| Firan Technology Group Corporation |
| Summit Interconnect |
| Advanced Circuits |
| TTM Technologies |
| Amphenol Printed Circuits |
| APCT |
| Sanmina Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive cleanroom allocations in Taiwan and South Korea anchor both supply security and pricing power for defense-qualified ceramic substrate packaging, creating a structural premium over standard consumer IC supply chains that hardened microcontroller buyers cannot arbitrage away.
Pricing Analysis
Capacity additions in Taiwan are reshaping price floors for radiation-hardened microcontroller output, though dedicated defense-qualified lines command sustained premiums over commercial foundry slots. Three-tier pricing structure across MIL-STD-883H certified, AS9100-qualified, and industrial-grade tiers separates procurement channels. Cost compression in the industrial-grade tier intensifies because Asian foundries divert capacity toward higher-margin defense allocations. System integrators face the sharpest price sensitivity, while prime contractors with captive vendor lists exhibit minimal elasticity.
Supply Chain Analysis
Ceramic substrate supply rests on Japanese specialty chemical producers for high-purity alumina feedstock and Taiwanese foundries for co-fired multilayer fabrication. Raw material dependencies include bismuth-telluride thermoelectric materials, silver-sintered die-attach pastes, and hermetic sealing alloys. Single-source vulnerability concentrates in electron beam welding equipment where Japanese producers hold effective supply control. Distribution runs through AS9100-certified contract manufacturers serving defense primes directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between EPA hexavalent chromium restrictions in the United States and ECHA REACH substance regulations in Germany, where alternative passivation chemistry qualification timelines diverge by 6-8 months and create cost differentials for connector housing procurement.
For Market Incumbents: Deploy AS9100 certification expansion to lock in unbundled sustainment contracts fragmenting across Pentagon program offices. Backward integration into ceramic substrate fabrication defends margin position against allocation risk during surge procurement. Electron beam welding capacity in Japan represents a critical chokepoint to control. For New Entrants and Emerging Players: Capture downhole drilling controller demand in North Dakota and Texas where 200°C ambient ratings exceed commercial industrial grades but fall below full MIL-STD-883H qualification burdens. Foundry service partnerships with Taiwanese cleanroom operators provide the essential go-to-market pathway without capital-intensive equipment investments. For Investors and Strategic Acquirers: Consolidation pressure builds where mixed-signal design teams fluent in both precision analog and digital processing remain scarce relative to reprogrammable logic demand. Five-to-ten year viability favors acquiring system integrators with existing prime contractor relationships over de novo qualification attempts. Watch for Bureau of Industry and Security export control expansion as inflection signal for cross-border shipment restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Expansion | Captures unbundled Pentagon sustainment contracts fragmenting across depot maintenance operations. |
| Ceramic Substrate Backward Integration | Secures dedicated cleanroom allocations decoupled from consumer IC supply chain volatility. |
| SiGe BiCMOS Process Adoption | Consolidates radar front-end signal conditioning chains for active electronically scanned arrays. |
| Silver-Sintered Die-Attach Qualification | Addresses ECHA REACH restrictions on lead-bearing solders for European aerospace thermal interfaces. |
| Export Control Compliance Services | Navigates Bureau of Industry and Security restrictions on radiation-hardened microcontroller shipments. |
Study Parameters
Multiple input streams — defense procurement officer interviews, foundry operations data, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary discussions with prime contractor supply chain directors, AS9100-certified contract manufacturing executives, and Bureau of Industry and Security compliance specialists informed qualification timeline assumptions. Secondary validation drew from MIL-STD-883H test protocol documentation, ECHA REACH substance restriction updates, and Pentagon budget justification materials. Bottom-up unit demand projections and top-down defense electronics spending allocations were triangulated for cross-verification.
Data-stream reconciliation across product type, application environment, technology node, and end-user procurement channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-specific growth differentials rather than uniform market expansion. Modeled inputs included FPGA reprogrammability premiums, mixed-signal SWaP reduction values, and radiation hardness assurance testing costs.
Defense procurement cycle compression, EPA plating regulation enforcement intensity, and Asian foundry allocation policy shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding qualification protocol stability and allied defense program budget continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
Automotive IC Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Ultra Large Scale Ics Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Asia Pacific Integrated Circuit (IC) Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Display Driver IC Market