
 Electric Vehicle Edrive Test System Market | 2026-2036
Electric Vehicle Edrive Test System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Edrive Test System Market Insights
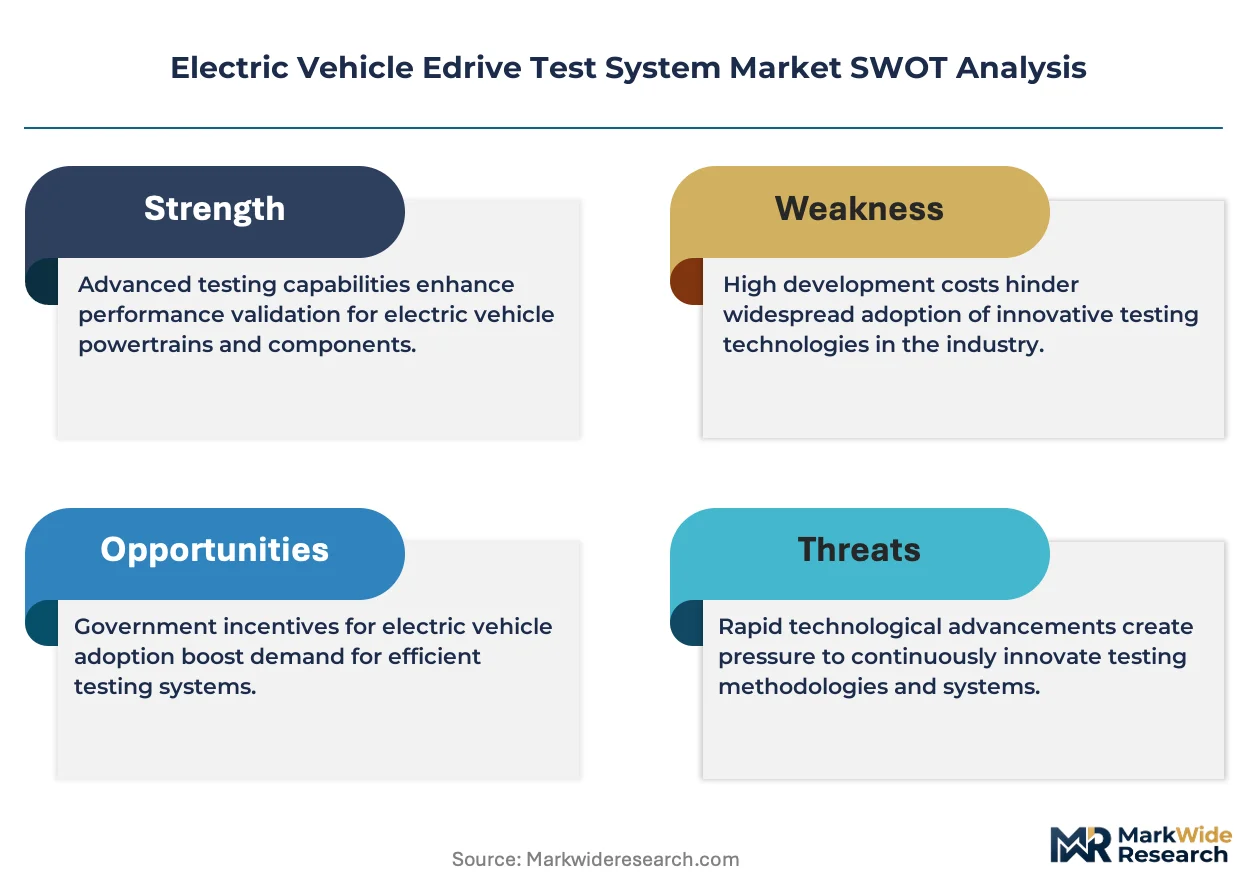
800V architecture migration is reconfiguring how e-drive test systems validate inverter switching losses and thermal cycling profiles. Keysight Technologies leverages its power electronics measurement heritage to anchor high-bandwidth waveform capture for SiC-based inverters. AVL List GmbH sustains dominance in full-vehicle dynamometer integration, while Chroma ATE Inc. competes on cost-optimized powertrain test benches for tier-one component suppliers.
An electric vehicle e-drive test system comprises dynamometers, power analyzers, battery emulators, and environmental chambers that replicate real-world load profiles to verify torque ripple, efficiency maps, and thermal limits of integrated motor-inverter-gearbox units. Powertrain Test Systems generate the largest revenue share due to OEM requirements for full-system validation before platform release, while Battery Test Systems represent the fastest-expanding segment as cell-to-pack architectures demand simultaneous electrical, thermal, and abuse testing. Motor Test Systems occupy a mature niche serving remanufacturing and aftermarket quality assurance with lower capital intensity.
EPA, NHTSA, and EU Green Deal frameworks mandate validated efficiency claims and traceable test documentation for zero-emission vehicle certification, directly expanding demand for repeatable, auditable test protocols. China's MIIT enforces GB standards for electric drive system efficiency that require domestic manufacturers to maintain certified test laboratories. Stakeholders must monitor how battery passport requirements and evolving cybersecurity standards for over-the-air calibration reshape capital allocation between physical test assets and virtual validation platforms.
Market Dynamics
Platform electrification timelines are compressing validation cycles as OEMs race to certify 800V architectures before model-year launches, forcing test labs to parallelize dynamometer scheduling and thermal chamber utilization.
Growth Catalysts
- EPA tailpipe efficiency mandates:Validated e-axle efficiency claims now require traceable dynamometer documentation, expanding demand for auditable test protocols across US validation centers.
- Silicon carbide inverter penetration:Wide-bandgap semiconductors switch at higher frequencies than IGBTs, necessitating upgraded power analyzers with bandwidth exceeding 10 MHz for accurate loss characterization.
- China MIIT GB standards:Domestic manufacturers must maintain certified laboratories for electric drive system efficiency, creating captive test facility buildouts among BYD and CATL supplier networks.
Market Restraints
- High-voltage safety infrastructure:800V test cells require arc-flash containment and interlock systems that add 30-40% to facility capex versus legacy 400V installations.
- Specialized technician scarcity:Power electronics calibration expertise concentrates in Germany, Japan, and the US, constraining test lab expansion in emerging manufacturing clusters.
- Copper and rare-earth magnet volatility:Motor dynamometer load units depend on permanent magnet materials subject to supply concentration in Chinese processing facilities.
Strategic Opportunities
- India PLI scheme for auto:Domestic EV production incentives are triggering component supplier entry, creating demand for cost-optimized motor test benches without full-vehicle dynamometer integration.
- Battery passport traceability:EU Green Deal documentation requirements for cell-to-pack testing are expanding revenue pools for combined electrical-thermal-abuse test system vendors.
- Virtual-physical hybrid validation:Software-in-the-loop platforms are converging with hardware dynamometers, enabling tier-one suppliers to front-load calibration before physical prototypes arrive.
Industry Challenges
- Cybersecurity certification for OTA calibration:UN R155 and ISO/SAE 21434 requirements are adding documentation layers to test system software validation, extending commissioning timelines.
- Legacy 400V test asset stranding:Existing dynamometer investments face utilization pressure as 800V platforms dominate new program launches, forcing retrofit-or-replace decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Edrive Test System Market |
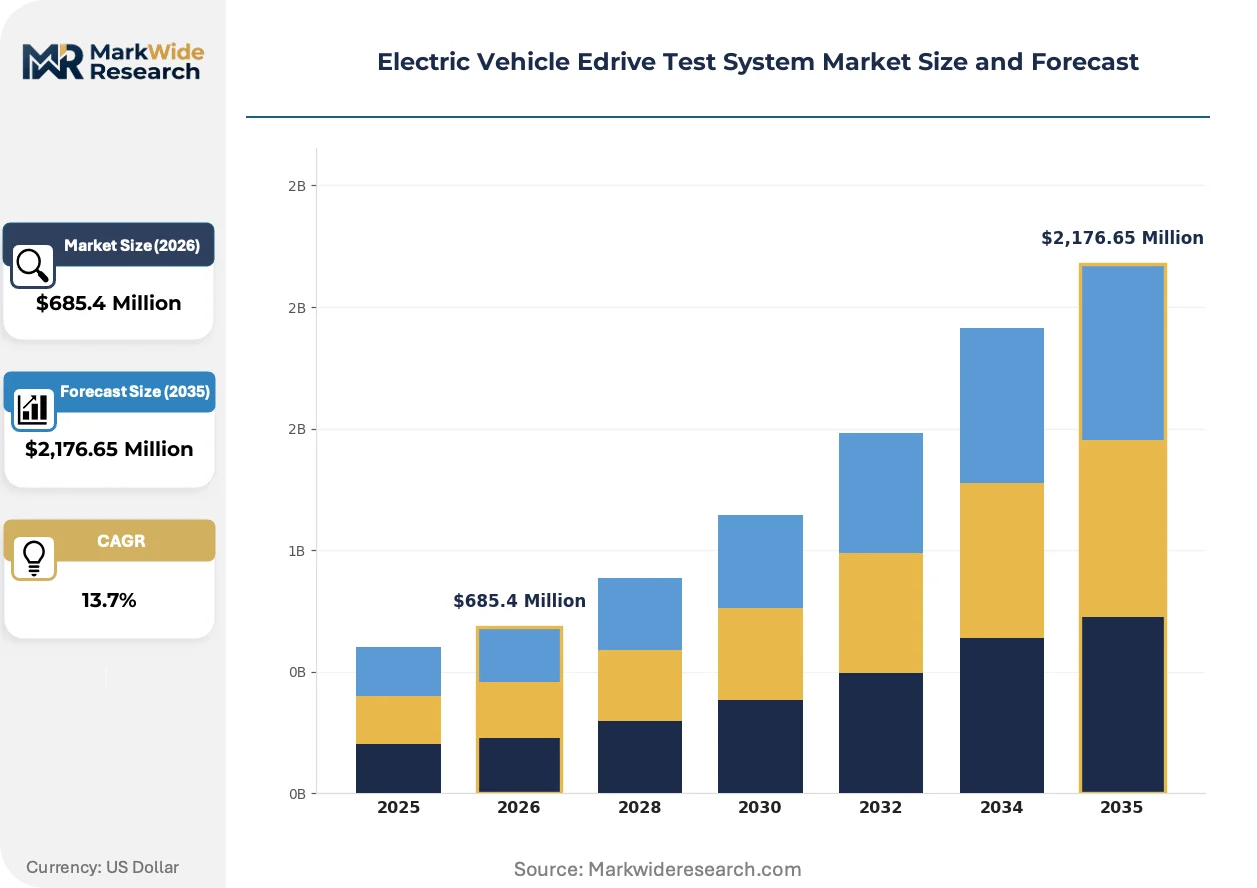
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powertrain Test Systems, Battery Test Systems, Motor Test Systems, Drive Cycle Simulators Technology: Electric Motors, Power Electronics, Control Systems, Data Acquisition Systems End User: Automakers, Research Institutions, Component Manufacturers, Fleet Operators Application: Performance Testing, Durability Testing, Safety Testing, Compliance Testing |
| Companies Covered | Keysight Technologies, National Instruments, Chroma ATE Inc., AVL List GmbH, HORIBA, Rohde & Schwarz, Ametek Inc., Arbin Instruments, Dewesoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Edrive Test System Market Trends and Innovations
Test methodology is bifurcating between high-fidelity physical validation for certification and accelerated virtual platforms for design iteration, with the boundary between them shifting toward earlier development phases.
Silicon carbide-based inverters are migrating from niche performance applications to mainstream B and C-segment platforms. Tier-one suppliers in Germany and South Korea are adopting 800V architectures for volume models launching 2026-2028. This transition is compressing the window for test system vendors to validate switching loss measurement accuracy before platform freezes.
Euro 7 emission frameworks are extending validation requirements to brake particulate and tire wear, indirectly tightening e-drive efficiency targets as OEMs seek offset credits through powertrain optimization. The regulation most affects integrated e-axle suppliers serving European OEMs, who are consolidating test schedules to capture efficiency map data across wider temperature and load ranges.
Service unbundling is separating test execution from equipment ownership. Tier-two motor suppliers in China and India are migrating toward per-hour dynamometer rental models rather than capital purchases, with AVL and Horiba establishing regional test-as-a-service facilities to capture this demand. The shift is most visible among battery and motor startups lacking balance sheet capacity for captive labs.
Electric Vehicle Edrive Test System Market Segmentation
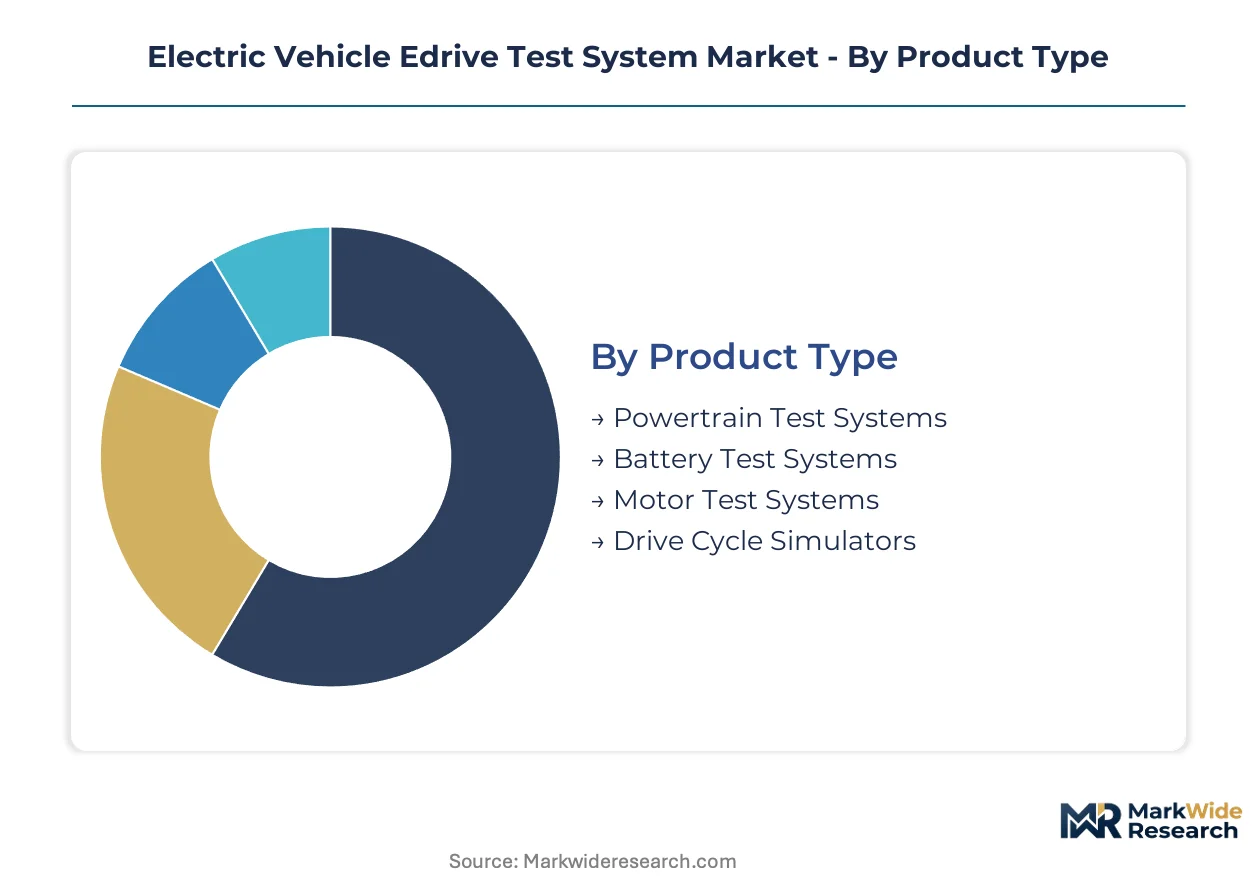
Test system segmentation reveals distinct service intensity profiles across product categories. Powertrain and battery platforms demand continuous calibration support and software updates, while motor test benches operate with lower aftermarket attachment.
Product Type:
After-sales service intensity varies sharply across test system categories, with integrated powertrain platforms requiring multi-year calibration contracts versus standalone motor benches that ship with limited service obligations.
- Powertrain Test Systems:Full-vehicle dynamometer configurations integrate motor, inverter, and gearbox validation in synchronized load profiles. OEM validation labs in Germany and Japan concentrate procurement here ahead of platform certification deadlines, driven by EPA and Euro 7 documentation requirements.
- Battery Test Systems:Cell-to-pack architectures demand simultaneous electrical, thermal, and abuse testing chambers with 24/7 monitoring capabilities. China's MIIT GB standards enforcement has triggered captive facility buildouts among domestic cell suppliers, creating sustained demand for combined thermal-electrical test platforms.
- Motor Test Systems:Remanufacturing and aftermarket quality assurance applications with lower capital intensity.
- Drive Cycle Simulators:Software-defined load profile generation for early-stage calibration without physical dynamometer allocation.
By volume, Powertrain Test Systems leads. By growth pace, Battery Test Systems is ahead.
Technology:
Cost tier stratification separates high-bandwidth power electronics measurement from standardized control and data acquisition components.
- Power Electronics:Wide-bandgap semiconductor validation demands power analyzers exceeding 10 MHz bandwidth for accurate SiC switching loss characterization. German and South Korean tier-one suppliers are upgrading test cells ahead of 800V platform launches.
- Electric Motors:Dynamometer load units with permanent magnet torque sensors remain the volume anchor, though rare-earth supply concentration through Chinese processing facilities creates procurement risk.
- Control Systems:Hardware-in-the-loop platforms enabling software validation before physical prototype availability.
- Data Acquisition Systems:High-channel-count waveform capture for thermal and electrical parameter logging during extended durability cycles.
By installed base, Electric Motors leads. By upgrade urgency, Power Electronics is expanding most quickly.
End User:
Customer type determines capital deployment patterns, with automakers favoring captive integration against component suppliers preferring rental or outsourced test execution.
- Automakers:OEM validation labs require full-vehicle dynamometer integration with traceable documentation chains for EPA and EU Green Deal certification. US and European manufacturers are parallelizing test schedules to compress 800V platform validation windows.
- Component Manufacturers:Tier-one and tier-two suppliers increasingly favor per-hour dynamometer rental models over balance-sheet-intensive facility ownership, particularly in India and China where startup motor suppliers lack capital for captive labs.
- Research Institutions:University and national laboratory procurement focused on methodology development and pre-competitive standard setting.
- Fleet Operators:Emerging demand for remanufacturing quality assurance as commercial EV deployment scales.
By capital deployed, Automakers leads. By contract flexibility, Component Manufacturers is climbing the fastest.
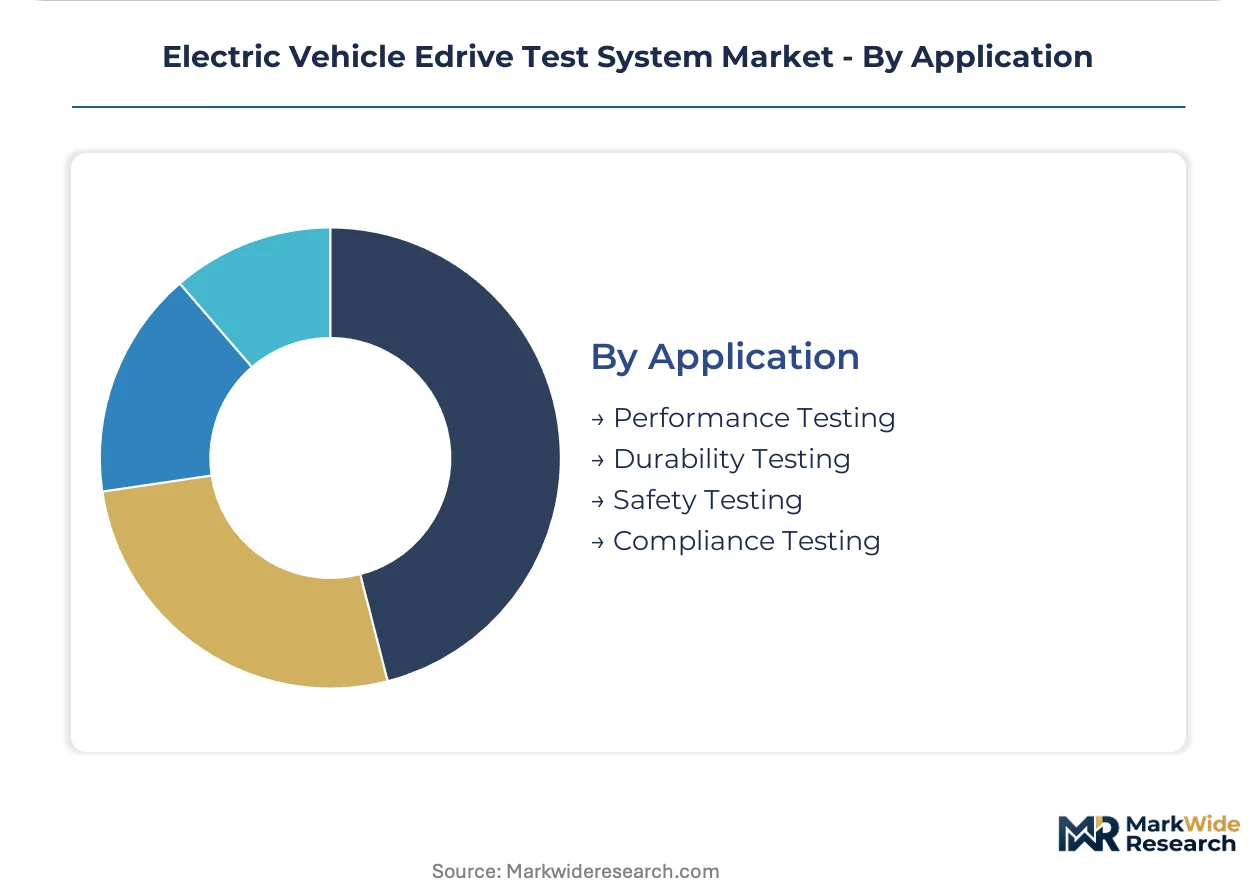
Application:
Maturity stage differentiation separates established compliance protocols from emerging safety and durability requirements tied to battery passport and cybersecurity mandates.
- Performance Testing:Efficiency map generation and torque ripple characterization across temperature and load ranges. European integrated e-axle suppliers are consolidating test schedules to capture wider operational envelopes for Euro 7 offset credit optimization.
- Compliance Testing:Validated efficiency claims with traceable documentation for EPA, NHTSA, and China MIIT certification. Regulatory expansion across multiple geographies is standardizing protocol requirements and equipment specifications.
- Durability Testing:Extended thermal cycling and mechanical load profiles for warranty validation.
- Safety Testing:Abuse testing protocols for thermal runaway characterization and arc-flash containment verification in high-voltage configurations.
By protocol standardization, Compliance Testing leads. By scope expansion, Safety Testing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in test equipment reveal China as the dominant net exporter of e-drive validation systems, while the United States and Germany remain substantial importers upgrading legacy facilities for 800V platform certification. Equipment flows concentrate from East Asian manufacturing clusters toward European and North American OEM validation centers.
China
BYD and CATL supplier networks operate the largest captive test facilities globally. MIIT enforces GB standards for electric drive system efficiency that mandate certified laboratories for domestic manufacturers. Shenzhen and Ningbo industrial clusters host concentrated buildouts of combined electrical-thermal test platforms serving cell-to-pack architectures.
United States
EPA tailpipe efficiency mandates require validated e-axle efficiency claims with traceable dynamometer documentation. NHTSA certification protocols are expanding demand for auditable test protocols across US validation centers. Michigan and California OEM labs are parallelizing test schedules to compress 800V platform validation windows ahead of model-year launches.
Germany
Tier-one integrated e-axle suppliers are consolidating test schedules to capture efficiency map data across wider temperature ranges for Euro 7 offset credit optimization. KBA enforcement of EU Green Deal documentation requirements is standardizing protocol specifications. Stuttgart and Munich industrial corridors anchor European power electronics measurement expertise for SiC inverter validation.
Japan
METI industrial policy supports domestic semiconductor and automotive test equipment supply chains. JIS standards for electric motor efficiency create compliance-driven procurement cycles. Nagoya and Tokyo metropolitan areas concentrate dynamometer manufacturing and calibration service capabilities for regional OEMs.
South Korea
Domestic battery and automotive OEMs are adopting 800V architectures for volume models launching 2026-2028. MFDS-aligned safety documentation requirements are tightening validation protocols for high-voltage systems. Seoul Capital Area and Busan-Ulsan clusters are upgrading power analyzer bandwidth capabilities for wide-bandgap semiconductor characterization.
Electric Vehicle Edrive Test System Market Competitive Landscape
On the supply side, the industry is tiered between integrated full-system providers and specialized component test vendors. German and Austrian engineering groups anchor high-end powertrain dynamometer integration. East Asian electronics manufacturers compete on cost-optimized bench configurations. Strategic moves center on test-as-a-service facility expansion and software-in-the-loop platform convergence with hardware assets.
Within the measurement instrumentation tier, Keysight Technologies exemplifies power electronics heritage applied to high-bandwidth waveform capture. AVL List GmbH occupies a position in full-vehicle dynamometer integration anchored by European automotive relationships. Chroma ATE Inc. represents cost-optimized powertrain test bench supply for tier-one component manufacturers in East Asian markets.
| Leading Market Players |
|---|
| Keysight Technologies |
| National Instruments |
| Chroma ATE Inc. |
| AVL List GmbH |
| HORIBA |
| Rohde & Schwarz |
| Ametek Inc. |
| Arbin Instruments |
| Dewesoft |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam maritime freight corridors transmit cost volatility from East Asian manufacturing clusters directly into European and North American test equipment pricing, amplifying differentiation between premium integrated systems and modular bench configurations as buyers consolidate procurement volumes.
Pricing Analysis
The 800V-versus-400V technology-generation pricing gap separates three distinct tiers: legacy 400V test benches at economy positioning, transitional dual-voltage platforms at standard grade, and native 800V systems commanding premium placement. Three-tier pricing structure across premium, standard, and economy levels reflects certification bandwidth requirements and after-sales calibration bundling. Cost compression in economy tiers is intensifying because tier-two suppliers in India and China favor per-hour rental models over capital purchases. Component manufacturers exhibit highest price sensitivity due to constrained balance sheets, while OEM validation labs prioritize traceable documentation chains over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for power analyzer and dynamometer load unit procurement. Manufacturing concentrates in China, Germany, and Japan, with permanent magnet torque sensors drawing from Chinese rare-earth processing facilities and precision power electronics resting on South Korean semiconductor supply. Single-source vulnerability in SiC wafer supply constrains inverter test system output. Distribution runs through direct OEM relationships for integrated powertrain platforms and regional distributor networks for modular motor test benches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated tier-one component suppliers and captive OEM labs, fragmenting demand among smaller tier-two motor and battery startups lacking capital for facility ownership.
For Market Incumbents: Build switching-cost moats through multi-year calibration service contracts and software update subscriptions. AVL and Horiba should expand test-as-a-service facility footprints in India and Southeast Asia to capture rental-model demand from capital-constrained entrants. SiC inverter validation expertise represents a defendable capability gap as 800V platforms proliferate. Capacity addition in South Korea and Germany anchors proximity to tier-one supplier engineering centers. For New Entrants and Emerging Players: Mid-market motor test benches for India's PLI-scheme component suppliers represent the most penetrable entry point, bypassing integrated powertrain dynamometer competition with AVL and Horiba. Cost-optimized battery cell test chambers for Southeast Asian gigafactory projects offer secondary white space. Go-to-market execution should emphasize per-hour rental partnerships with established regional test facility operators rather than direct capital equipment sales. For Investors and Strategic Acquirers: Specialized power electronics measurement boutiques with SiC inverter calibration IP and existing relationships with German or South Korean tier-one suppliers present the most attractive acquisition target archetype. Long-term viability hinges on software-in-the-loop convergence capabilities and cybersecurity certification for OTA calibration documentation. Watch for 800V platform freeze announcements from major OEMs as inflection indicators for test system upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Test-as-a-Service Facility Expansion | Captures rental-model demand from India's PLI-scheme component suppliers without capital equipment sales friction. |
| SiC Inverter Calibration IP Acquisition | Secures bandwidth expertise exceeding 10 MHz for switching loss characterization ahead of 800V platform freezes. |
| Cybersecurity Certification Investment | Enables UN R155 and ISO/SAE 21434 documentation for OTA calibration test system software validation. |
| Software-in-the-Loop Platform Convergence | Front-loads calibration workflows before physical prototype availability, compressing OEM validation timelines. |
| Regional Calibration Service Hub Buildout | Positions aftermarket support proximity to Shenzhen and Ningbo industrial clusters serving CATL supplier networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with OEM platform engineers, tier-one supplier procurement leads, test facility operations managers, and power electronics calibration specialists. Secondary validation drew from EPA certification documentation, China MIIT GB standard filings, EU Green Deal regulatory texts, and SEC equipment manufacturer disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from production database analysis.
Calibration against historical platform launch cycles and documented test cell procurement timelines anchored volume projections across the analysis window. Segmentation dimensions modeled include test system product category, semiconductor technology generation, end-user capital deployment pattern, and regional regulatory enforcement intensity. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion. Industry-specific inputs incorporated 800V architecture migration timelines and battery passport documentation requirements.
Practitioners should monitor SiC inverter platform freeze announcements, battery passport enforcement dates, and 800V model launch schedules for early signals of test capacity demand inflection. Forecasts reflect assumptions regarding regulatory timeline adherence and OEM electrification program execution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Electrical Conductivity Meters Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
India Electrical Testing Services Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
AI-Assisted NDT Data Analytics and Defect Characterization Platforms Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Metrology Services Market
Test and Measurement
United States Probe Station Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Tube Tester Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Leak Testing Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market
Test and Measurement
Paperless Recorders Market
Test and Measurement
Shape Measuring Devices Market