
 Galvanic Isolation Market | 2026-2036
Galvanic Isolation Market Size, Share, and Industry Trends Forecast 2026-2036
Galvanic Isolation Market Analysis
Aftermarket service revenue for legacy optocoupler replacement is rewriting margin distribution across the value chain. Texas Instruments leverages its integrated manufacturing footprint to sustain pricing power in high-reliability industrial grades. Analog Devices anchors its position through dense R&D investment in magnetic coupling architectures. Infineon Technologies competes on silicon carbide integration, extending its reach into automotive traction inverters.
Galvanic isolation denotes the electrical separation of two circuits to prevent current flow between them while permitting signal or power transfer, typically achieved through magnetic induction, optical transmission, or capacitive coupling with isolation ratings spanning kilovolts. Its primary purpose is protecting personnel and sensitive electronics from ground loops, transient overvoltages, and differential potentials in high-voltage environments. Digital isolators command the fastest expansion trajectory as system designers abandon aging optocoupler designs for higher-speed, lower-power alternatives. Capacitive couplers occupy a specialized niche in compact consumer electronics where board space constraints dominate specification sheets.
FDA 21 CFR Part 820 quality system regulations and IEC 60601-1 medical safety standards enforce stringent isolation barriers in patient-connected equipment, directly shaping product certification requirements and design architectures. The EPA's energy efficiency mandates and EU RoHS substance restrictions further constrain material selections and manufacturing processes for isolation components. Stakeholders must monitor the divergence between automotive ISO 26262 functional safety grades and industrial IEC 61508 certifications as these standards evolve toward incompatible test regimes.
Market Dynamics
Digital isolators are compressing replacement cycles across industrial automation as engineers abandon optocoupler architectures for magnetic and capacitive alternatives that slash board space and power budgets. This technology transition is redistributing margin pools from discrete component suppliers toward integrated solution providers while tightening certification requirements for mixed-signal designs.
Growth Catalysts
- EV Battery Management Systems:High-voltage traction architectures in electric vehicles mandate reinforced isolation barriers between power stages and control electronics, with automotive OEMs specifying 5kV+ ratings for onboard chargers and DC-DC converters.
- IEC 60601-1 Medical Standards:Patient-connected equipment regulations in the United States and European Union enforce creepage and clearance distances that drive demand for reinforced isolation in diagnostic imaging and life-support systems.
- Silicon Carbide Integration:Wide-bandgap power semiconductors operating at switching frequencies above 100kHz require isolation devices with sub-10ns propagation delays, a specification band where magnetic couplers outperform legacy alternatives.
Market Restraints
- Specialized Magnetic Core Supply:Ferrite and nanocrystalline core materials for high-frequency transformers concentrate among Japanese and German suppliers, exposing isolator manufacturers to alloying element price volatility and allocation risk.
- Certification Timeline Compression:Divergence between automotive ISO 26262 functional safety grades and industrial IEC 61508 test regimes forces dual-track qualification programs that extend time-to-revenue by 8-14 months for multi-market products.
- Capacitive Coupler Limitations:Capacitive isolation architectures face inherent common-mode transient immunity constraints above 25kV/μs, restricting their deployment in motor drive and grid-tied inverter applications where dv/dt stress peaks higher.
Strategic Opportunities
- India Industrial Automation:The country's PLI scheme for manufacturing automation equipment creates localized demand for isolation components in programmable logic controllers and variable frequency drives as domestic production scales.
- Renewable Energy Inverters:Photovoltaic string inverters and energy storage systems require galvanic separation between DC input stages and AC grid interfaces, with isolation ratings trending toward 1500V working voltage for utility-scale installations.
- Chiplet-Based Integration:2.5D and 3D packaging architectures enable monolithic integration of isolation barriers with signal conditioning and power management, collapsing bill-of-materials count in space-constrained medical wearables.
Industry Challenges
- Mixed-Signal Design Expertise:Isolation product development demands rare combinations of high-voltage physics, RF magnetics, and semiconductor process knowledge, with talent scarcity most acute in analog IC design centers across Germany and the United States.
- Legacy System Integration:Industrial retrofit projects require galvanic isolators that maintain signal compatibility with 4-20mA current loops and RS-485 networks while adding modern digital diagnostics, complicating firmware architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galvanic Isolation Market |
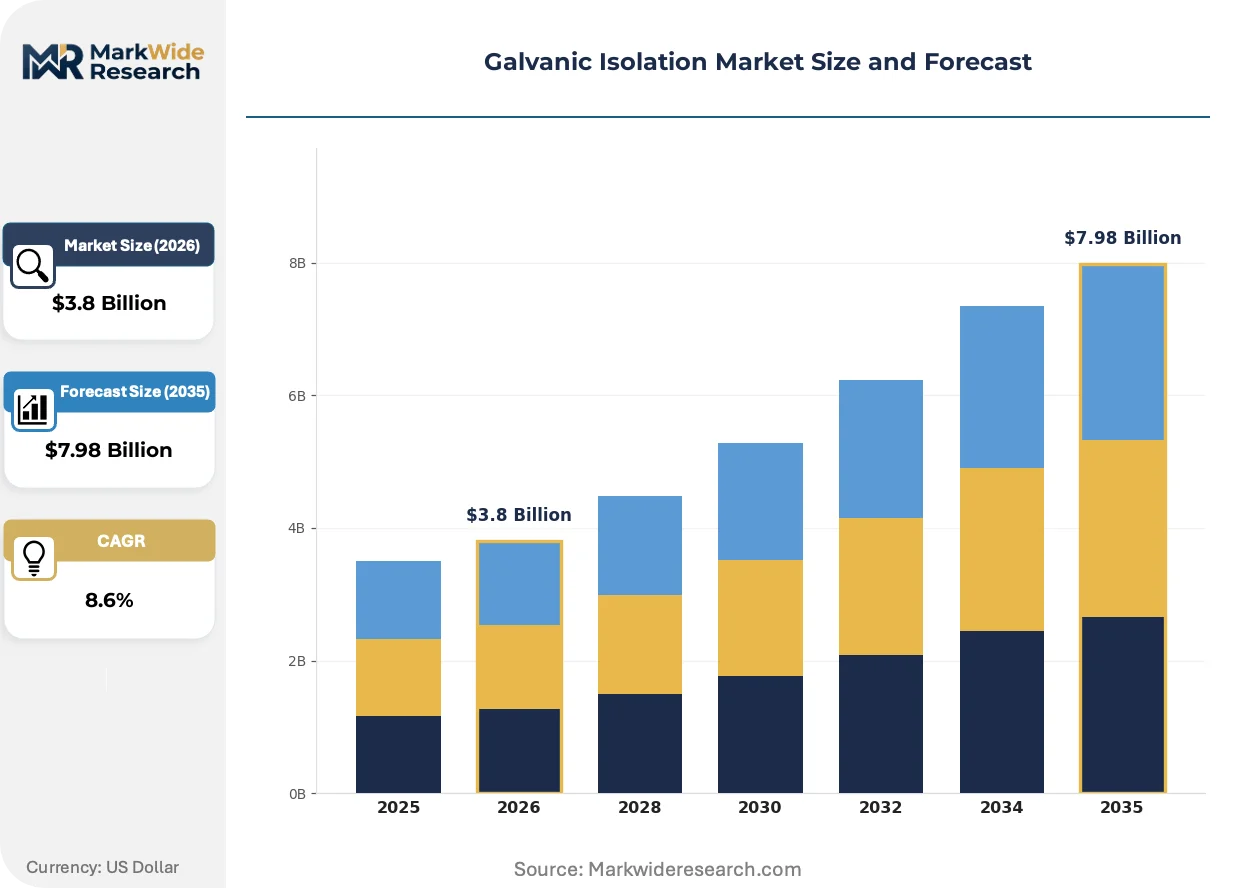
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Optoisolators, Capacitive Couplers, Digital Isolators Technology: Galvanic Optocoupler, Magnetic Coupling, Capacitive Isolation, Fiber Optic End User: Industrial Automation, Medical Devices, Consumer Electronics, Telecommunications Application: Signal Isolation, Power Supply, Data Communication, Measurement |
| Companies Covered | Texas Instruments, Analog Devices, Broadcom, Infineon Technologies, STMicroelectronics, ROHM Semiconductor, Schneider Electric, Pepperl+Fuchs, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galvanic Isolation Market Emerging Trajectories
Magnetic coupling architectures are displacing optoelectronic isolation across every major voltage class as system designers prioritize speed, reliability, and miniaturization in electrified applications. Three converging developments are compressing technology adoption cycles and reshaping competitive positioning.
Integrated magnetic isolators combining transformer windings with CMOS signal conditioning on single dice are rendering obsolete discrete optocoupler plus driver configurations in servo motor controls and factory automation networks. Automotive Tier-1 suppliers in Germany and Japan have accelerated qualification timelines for these devices, recognizing that propagation delays below 10ns enable tighter current-loop bandwidth in traction inverters. The structural consequence is margin compression for standalone optocoupler vendors unable to pivot toward monolithic magnetic solutions.
The European Union's RoHS substance restrictions and REACH chemical registration requirements are constraining material selections for isolation barriers in medical and consumer electronics, with particular scrutiny on halogenated flame retardants in package molding compounds. Manufacturers serving the EU market are reformulating epoxy systems and accelerating transitions to green molding compounds that maintain 5kV isolation ratings. Medical device OEMs in Ireland and the Netherlands are now specifying full material disclosure as a procurement gate, forcing upstream component suppliers to document substance chains through tier-three suppliers.
Certification-driven procurement is consolidating supplier relationships as industrial buyers prioritize isolators pre-qualified to multiple safety standards rather than managing parallel qualification tracks. Distributors in the United States are responding with value-added programming services that bundle isolation components with documentation packages for FDA 510(k) submissions and UL file reviews. This behavioral shift is most pronounced among mid-sized medical device manufacturers in Minnesota and Massachusetts, where lean quality teams lack bandwidth for extensive component-level validation.
Galvanic Isolation Market Segmentation
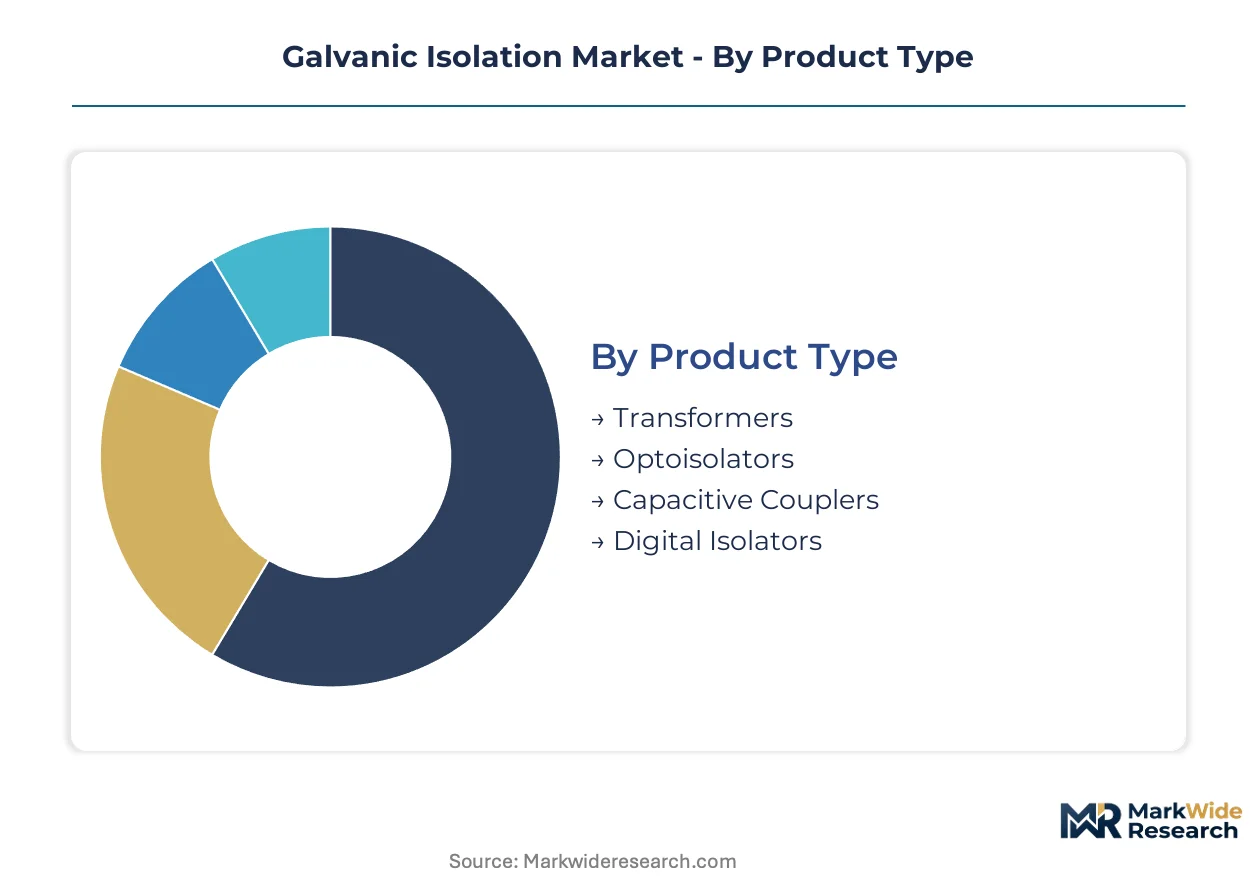
Galvanic isolation architectures fragment across four distinct dimensions, each carrying divergent margin profiles and aftermarket service intensities. Product type and technology categories concentrate value capture among integrated solution providers, while end-user and application segments determine qualification timelines and regulatory compliance burdens.
Product Type:
Aftermarket service revenue varies dramatically across isolation product categories, with legacy optoisolator replacement cycles generating recurring revenue streams that digital isolator vendors cannot replicate.
- Digital Isolators:These CMOS-based devices integrate transformer windings with signal conditioning on monolithic dice, achieving sub-10ns propagation delays. Demand concentrates in Germany's automotive traction inverter clusters and Japan's servo motor control suppliers, driven by silicon carbide switching frequencies exceeding 100kHz.
- Transformers:Discrete magnetic components utilizing ferrite or nanocrystalline cores deliver isolation ratings above 5kV for grid-tied applications. Procurement in China's utility-scale solar installations and India's PLI-backed manufacturing automation corridors sustains volume leadership despite slower growth trajectories.
- Optoisolators:LED-phototransistor pairs dominate legacy industrial retrofit projects requiring 4-20mA loop compatibility.
- Capacitive Couplers:Silicon-dielectric barriers serve space-constrained consumer electronics in South Korea's smartphone supply chain.
By volume, Transformers leads. By growth pace, Digital Isolators is ahead.
Technology:
Technology selection directly determines certification pathway complexity and the divergence between automotive ISO 26262 and industrial IEC 61508 qualification regimes.
- Magnetic Coupling:Transformer-based architectures transmit signals through inductive coupling across insulated windings, achieving reinforced isolation without optical degradation. Germany's KBA-regulated automotive suppliers and Japan's METI-industrial automation sector prioritize these devices for 150°C ambient operation in traction inverters.
- Capacitive Isolation:Silicon dioxide barriers modulate electric fields across micrometer-scale gaps, minimizing board area in medical wearables. Ireland's FDA-registered device manufacturers and the Netherlands' CE-marking clusters specify these for patient-connected equipment under IEC 60601-1.
- Galvanic Optocoupler:Light-based transmission persists in cost-sensitive industrial retrofit applications.
- Fiber Optic:Glass-fiber isolation serves high-voltage grid infrastructure with immunity to electromagnetic interference.
Magnetic Coupling commands the highest average selling prices. Capacitive Isolation is climbing the fastest among emerging architectures.
End User:
End-user concentration shapes geographic demand clustering and the intensity of regulatory documentation requirements upstream suppliers must maintain.
- Industrial Automation:Programmable logic controllers and variable frequency drives require reinforced isolation between high-voltage power stages and 24V control circuits. Germany's Ruhr industrial corridor and China's Jiangsu manufacturing zones specify 2.5kV working voltage ratings as baseline requirements.
- Medical Devices:Patient-connected diagnostic imaging and life-support systems mandate creepage distances enforced by FDA 21 CFR Part 820 and EU MDR. Minnesota and Massachusetts device manufacturers now require tier-three material disclosure from isolation component suppliers.
- Consumer Electronics:Compact chargers and adapters in South Korea and Taiwan drive demand for sub-3mm package heights.
- Telecommunications:Base station power supplies and data center infrastructure require isolation for 48V DC distribution systems.
Industrial Automation generates the largest absolute revenue. Medical Devices carries the steepest expansion trajectory given tightening safety standards.
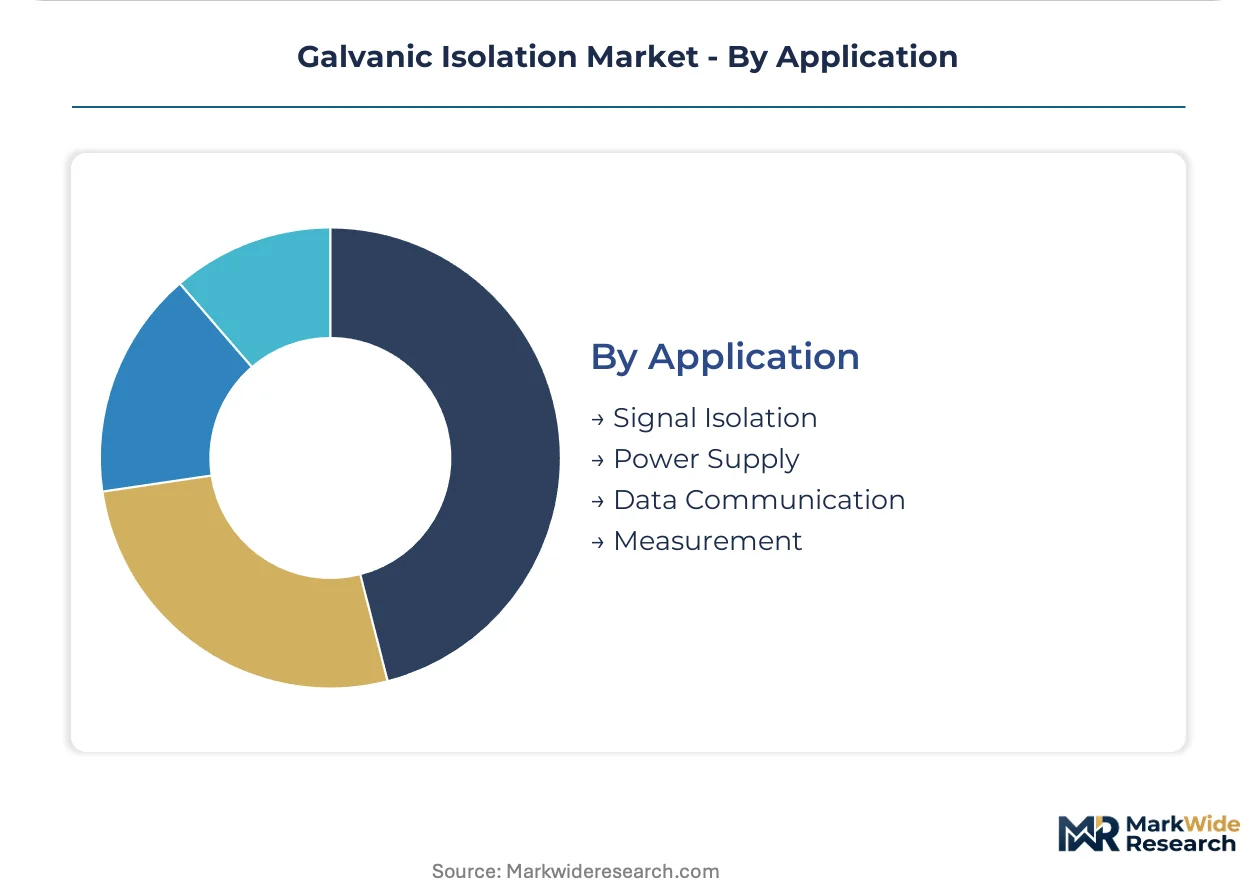
Application:
Application segmentation reveals divergent performance specifications, with signal integrity requirements in data communication contrasting sharply with power handling priorities in supply applications.
- Signal Isolation:High-speed digital interfaces between ground domains require propagation delays below 50ns for RS-485 and CAN bus networks. Germany's automotive Tier-1 suppliers and Japan's factory automation integrators specify magnetic couplers for sub-10ns performance in servo feedback loops.
- Power Supply:Isolated DC-DC converters for gate drivers and auxiliary supplies demand 5kV transient withstand capability. China's EV onboard charger manufacturers and India's renewable energy inverter producers drive procurement for 1500V working voltage ratings.
- Data Communication:Ethernet and USB isolation protects sensitive computing equipment from ground potential differences.
- Measurement:Precision analog front-ends in test equipment require isolation with minimal signal distortion.
Power Supply dominates unit shipments. Signal Isolation is gaining share fastest as digitalization penetrates industrial control systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's EV manufacturing zones exhibit the highest price elasticity, squeezing margins on standard-grade isolators, while Germany's automotive Tier-1 suppliers absorb premium pricing for ISO 26262-certified devices without volume attrition.
United States
FDA 21 CFR Part 820 quality system regulations and medical device clusters in Minnesota and Massachusetts drive reinforced isolation procurement for patient-connected equipment. Minnesota-based OEMs now mandate tier-three material disclosure from component suppliers, extending qualification timelines. The FDA's 510(k) submission requirements concentrate sourcing decisions among pre-qualified vendor pools.
Germany
KBA-regulated automotive suppliers in Bavaria and Baden-Württemberg specify magnetic couplers for traction inverters operating at 150°C ambient. The Ruhr industrial corridor's programmable logic controller manufacturers anchor demand for 2.5kV working voltage ratings. METI-aligned Japanese automation vendors compete directly with domestic suppliers in servo motor control applications.
China
MIIT industrial policy and dual carbon goals accelerate silicon carbide traction inverter deployment, requiring sub-10ns propagation delay isolators. Jiangsu manufacturing zones and Yangtze River Delta EV battery facilities concentrate procurement for 5kV+ rated onboard chargers. GB standards divergence from IEC frameworks forces parallel certification tracks for export-bound production.
India
PLI scheme incentives for manufacturing automation equipment generate localized demand in Gujarat and Maharashtra for programmable logic controller isolation components. CEA grid regulations mandate 1500V working voltage ratings for utility-scale solar inverters. Tamil Nadu's renewable energy manufacturing clusters attract component suppliers establishing captive production.
Japan
METI industrial automation standards and JIS certification requirements reinforce magnetic coupling preferences in Nagoya's servo motor control supply chain. Automotive Tier-1 suppliers in Kanto accelerate qualification timelines for integrated magnetic isolators. Sub-10ns propagation delay specifications propagate from traction inverter designs into factory automation networks.
Galvanic Isolation Market Vendor Landscape
Integrated solution providers and discrete component specialists split the market along certification-complexity lines. Texas Instruments and Analog Devices anchor the premium tier through captive manufacturing and dense R&D investment, while mid-scale magnetic component fabricators serve cost-sensitive industrial retrofit segments. Two competitive moves dominate: silicon carbide integration partnerships extending into automotive traction inverters, and backward integration into ferrite core materials to secure alloying element supply.
Within the integrated semiconductor tier, Texas Instruments, Analog Devices, and Infineon Technologies exemplify divergent technology bets. Texas Instruments leverages its manufacturing footprint to sustain pricing power in high-reliability industrial grades. Analog Devices occupies a position defined by magnetic coupling architecture specialization. Infineon Technologies represents the wide-bandgap integration archetype, extending reach through silicon carbide traction inverter partnerships. These three anchors collectively illustrate how technology-platform choices stratify competitive positioning across automotive and industrial end-markets.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Broadcom |
| Infineon Technologies |
| STMicroelectronics |
| ROHM Semiconductor |
| Schneider Electric |
| Pepperl+Fuchs |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's ferrite and nanocrystalline core manufacturing clusters concentrate upstream capacity for high-frequency transformer materials, translating into asymmetric pricing power for Japanese and German suppliers who command premium allocations during alloying element shortages. Buyers in China's Yangtze River Delta EV manufacturing zones exploit this concentration through aggressive volume consolidation, while Germany's automotive Tier-1 suppliers absorb cost pass-throughs without demand destruction due to ISO 26262 certification lock-in.
Pricing Analysis
Aftermarket service revenue for legacy optocoupler replacement sustains lifetime value capture that digital isolator vendors cannot replicate through transactional hardware sales alone. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal performance tier, with KBA-regulated automotive suppliers in Germany paying 40-60% premiums for 150°C-rated magnetic couplers. Cost compression in standard-grade industrial isolators intensifies as Chinese programmable logic controller manufacturers consolidate procurement around domestic magnetic component fabricators. Medical device OEMs in Minnesota and Massachusetts exhibit lowest price sensitivity due to FDA 510(k) resubmission costs, while India's PLI-backed automation equipment makers drive hardest bargain on 2.5kV working voltage ratings.
Supply Chain Analysis
Export control regimes limiting wide-bandgap semiconductor and advanced magnetic core technology flows constrain supply security for automotive traction inverter programs. Ferrite core production draws from Japan's TDK-EPCOS facilities, Germany's Vacuumschmelze nanocrystalline operations, and China's Yantai Zhenghai Magnetic Materials capacity. Critical dependencies include nickel-zinc ferrite powders, cobalt-based amorphous alloys, and high-purity silicon dioxide dielectrics for capacitive barriers. Single-source vulnerability concentrates in Japanese suppliers controlling 70%+ of automotive-grade nanocrystalline ribbon output. Distribution runs through Arrow Electronics and Avnet in North America, Rutronik in Europe, and WPG Holdings in Asia-Pacific, with value-added programming services bundling isolation components with FDA 510(k) documentation packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Galvanic isolation is shifting toward platform-economics dynamics as chiplet-based 2.5D and 3D packaging architectures enable monolithic integration of isolation barriers with signal conditioning, collapsing traditional component boundaries into interoperable subsystem platforms.
For Market Incumbents: Build certification moats by pre-qualifying magnetic couplers to both ISO 26262 ASIL-D and IEC 61508 SIL-3 tiers simultaneously, compressing rival time-to-revenue by 8-14 months. Backward integration into ferrite core materials secures alloying element supply against Japanese and German allocation risk. Channel control through distributor value-added programming services locks in mid-sized medical device manufacturers lacking internal validation bandwidth. For New Entrants and Emerging Players: Pursue India's PLI scheme for manufacturing automation equipment as the most penetrable geography, where localized programmable logic controller production generates unmet demand for 2.5kV-rated isolation components. Target renewable energy inverter applications in Tamil Nadu's manufacturing clusters, where CEA grid regulations mandate 1500V working voltage ratings with limited incumbent pre-qualification. Go-to-market angle: bundle isolation components with tier-three material disclosure documentation to satisfy Minnesota and Massachusetts OEM procurement gates. For Investors and Strategic Acquirers: Long-term, this sits as a standards-convergence play because divergence between automotive ISO 26262 and industrial IEC 61508 test regimes forces dual-track qualification programs that extend time-to-revenue, favoring acquirers with capital to absorb 8-14 month timeline compression. Target magnetic coupling architecture specialists with dense R&D investment and captive CMOS process integration. Watch silicon carbide traction inverter deployment rates as inflection indicator—sub-10ns propagation delay specifications propagate from automotive designs into factory automation networks, accelerating magnetic isolator displacement of optocouplers.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet-Based Integration | 2.5D and 3D packaging collapses bill-of-materials count in space-constrained medical wearables. |
| Dual-Certification Pre-Qualification | Simultaneous ISO 26262 and IEC 61508 qualification compresses rival time-to-revenue by 8-14 months. |
| Backward Integration into Ferrite Cores | Captive supply of nickel-zinc ferrite and nanocrystalline alloys insulates against Japanese allocation risk. |
| Value-Added Programming Services | Distributor bundling of FDA 510(k) documentation packages locks in lean Minnesota medical device quality teams. |
| Silicon Carbide Partnership | Traction inverter alliances with automotive OEMs propagate sub-10ns propagation delay specifications into industrial automation. |
Methodological Framework
A spread of perspectives from isolation product managers at Texas Instruments and Analog Devices, automotive Tier-1 supplier procurement directors in Germany and Japan, medical device quality engineers in Minnesota and Massachusetts, and ferrite core material specialists at TDK-EPCOS converged on the working assumptions through structured primary interviews. Secondary validation drew from SEC 10-K filings, FDA 510(k) submission databases, IEC and ISO standard revision dockets, and customs trade data for magnetic core material flows. Bottom-up segment sizing triangulated against top-down macroeconomic overlays.
Demand-supply balance framing anchored the analytical framework, with capacity utilization at Japanese and German ferrite core facilities cross-referenced against procurement pipelines from China's EV manufacturing zones and India's PLI-backed automation corridors. Segmentation dimensions modeled included product type, coupling technology, end-user industry, application function, and regional regulatory cluster. CAGRs were derived from slope-intercept analysis of historical shipment data and forward-looking capacity announcements. Industry-specific inputs incorporated silicon carbide traction inverter deployment schedules and IEC 60601-1 medical safety standard revision timelines.
Macroeconomic conditions sit as an overlay; deviation in alloying element prices, automotive production volumes, or renewable energy installation rates would shift the trajectory. Forecasts reflect assumptions about certification timeline compression and standards convergence that material shifts in ISO 26262 or IEC 61508 test regime divergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Lead-Free Solder Paste Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
Germany MLCC Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market