
 United States Integrated Circuits Market | 2026-2036
United States Integrated Circuits Market Size, Share, and Industry Trends Forecast 2026-2036
United States Integrated Circuits Market Insights
The EPA's emerging framework for perfluorinated compound disclosure in semiconductor manufacturing is realigning cleanroom chemistry standards across domestic fabs. Intel Corporation leverages its captive Arizona and Oregon fabrication network to sustain process node development without overseas dependency. Texas Instruments anchors its 300-millimeter analog capacity in Richardson, Texas, competing on cost structure rather than leading-edge geometry. NVIDIA Corporation specializes in GPU architectures that dominate AI training workloads, differentiating through software-coupled hardware ecosystems.
Integrated circuits are miniaturized electronic assemblies of transistors, resistors, and capacitors fabricated on monocrystalline silicon wafers using photolithography with feature sizes now approaching single-digit nanometers; their primary purpose is to process, store, or transmit electrical signals in computational and control systems. Analog ICs occupy mature margin pools in power management and signal conditioning where process longevity exceeds digital product cycles. Digital ICs lead absolute revenue contribution as CMOS-based microprocessors and memory devices underpin cloud infrastructure expansion. Automotive application demand is accelerating fastest as electrified powertrains and sensor fusion architectures multiply chip content per vehicle platform.
The CHIPS and Science Act directs NIST and the Department of Commerce in administering domestic production incentives, while EPA enforcement of PFAS reporting obligations shapes chemical supply chain compliance costs for wafer fabrication. OSHA's semiconductor industry standards govern hazardous energy control and cleanroom worker exposure limits, affecting operational expenditure benchmarks across fabs. Stakeholders must monitor how BIS export control classifications on advanced lithography equipment evolve, as these determinations will constrain or enable domestic capability progression at specific technology thresholds.
Market Dynamics
The CHIPS and Science Act is restructuring domestic fabrication economics by channeling federal incentives toward captive wafer production, compressing reliance on overseas foundry capacity for strategic process nodes.
Growth Catalysts
- Defense procurement mandates:Pentagon acquisition directives for radiation-hardened semiconductors are accelerating orders from domestic foundries serving satellite and missile systems.
- EPA PFAS disclosure framework:The emerging perfluorinated compound reporting rules are forcing cleanroom chemistry upgrades that favor fabs with capital reserves for compliance infrastructure.
- Electrified automotive platforms:Battery management systems and sensor fusion architectures are multiplying chip content per vehicle, pulling analog and power IC demand from Texas and Arizona fabs.
Market Restraints
- Lithography equipment concentration:Extreme ultraviolet scanner availability remains bottlenecked by Dutch and Japanese supplier output, constraining domestic leading-edge capacity expansion regardless of capital availability.
- Fluorinated gas supply volatility:Process gas inputs for etch and deposition face price instability tied to European chemical plant operating rates and export license timelines.
- Legacy node margin compression:Mature process geometries face pricing pressure from Taiwanese and Chinese foundry scale advantages that US-based analog specialists cannot match on cost structure alone.
Strategic Opportunities
- Chiplets and heterogeneous integration:Advanced packaging architectures enabling multi-die systems are creating white space for domestic OSAT capacity expansion outside traditional wafer fabrication.
- DOE clean energy manufacturing credits:Inflation Reduction Act provisions for domestic production equipment are offsetting depreciation schedules for new fab construction in New York and Ohio.
- Space commercialization:Low-earth orbit satellite constellations are generating demand for radiation-tolerant components that legacy automotive and industrial fabs can retool to supply.
Industry Challenges
- Process engineer scarcity:Advanced node development requires specialists in atomic layer deposition and EUV photoresist chemistry that US university pipelines currently underproduce.
- Cleanroom construction timelines:HEPA filtration infrastructure and vibration-isolation foundations for 300-millimeter facilities routinely extend project schedules beyond original capital commitment windows.
- BIS license classification uncertainty:Export control determinations on deposition and etch equipment lack predictable timelines, freezing procurement decisions for fabs targeting sub-7 nanometer capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Integrated Circuits Market |
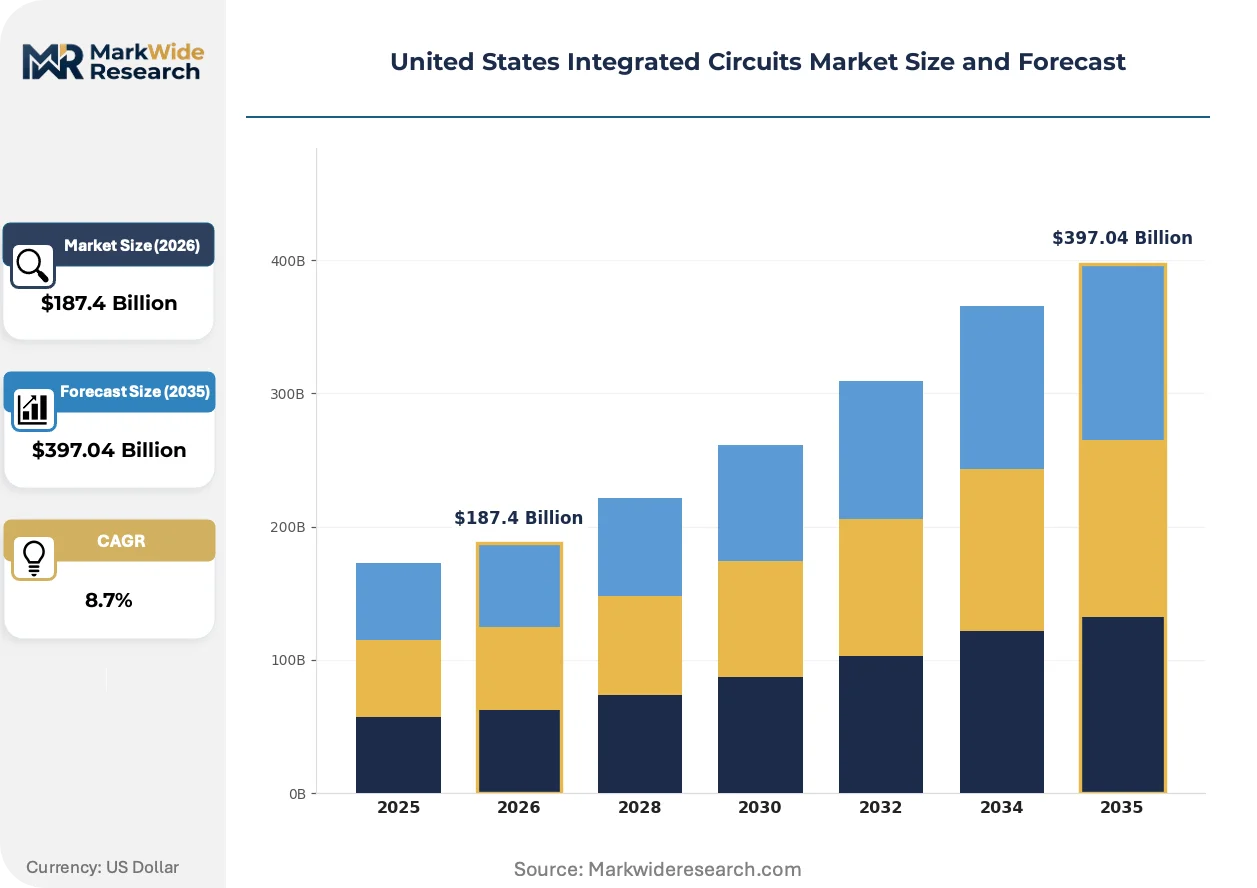
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-Signal ICs, Power ICs Application: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Electronics Manufacturers Technology: CMOS, BiCMOS, Biodegradable, High-Density |
| Companies Covered | Intel Corporation, Texas Instruments, Analog Devices, Micron Technology, Qualcomm Technologies, Broadcom, NVIDIA Corporation, GlobalFoundries, NXP Semiconductors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Integrated Circuits Market Trends and Innovations
Wafer-level packaging and heterogeneous integration architectures are compressing traditional boundaries between front-end fabrication and back-end assembly, redrawing competitive advantage around interposer technology rather than transistor density alone.
Gallium nitride power semiconductors is electrifying traction inverter and onboard charger designs across electric vehicle platforms. Automotive Tier 1 suppliers are qualifying GaN devices for 800-volt architectures at accelerated timelines compared to silicon carbide ramps. This transition is compressing incumbent silicon MOSFET market positions in high-frequency power conversion applications.
OSHA's updated semiconductor industry standards for hazardous energy control and cleanroom chemical exposure are mandating revised operational protocols across domestic fabs. The regulatory burden falls heaviest on legacy facilities in Oregon and Arizona retrofitting infrastructure rather than greenfield sites. Equipment vendors are responding with integrated safety monitoring systems that bundle compliance automation into new tool purchases.
Defense contractors are consolidating procurement through qualified manufacturer lists rather than merchant market spot purchases, concentrating volume with fabs holding Trusted Foundry accreditation. This behavioral shift is displacing open-market distribution for radiation-hardened and secure microelectronics. The Pentagon's demand concentration is most visible in Arizona and Texas, where accredited captive and merchant foundries cluster.
United States Integrated Circuits Market Segmentation
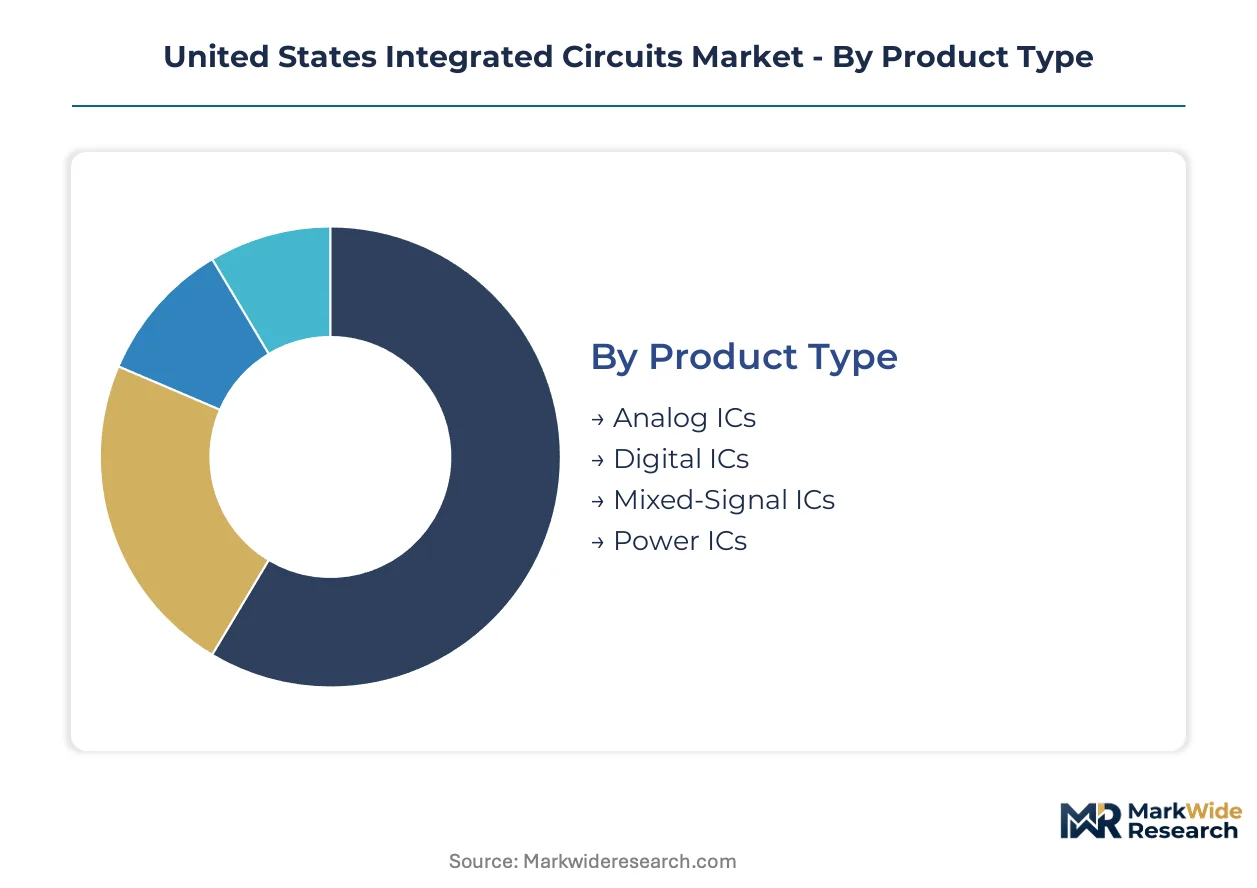
Integrated circuits fragment into distinct technology and demand clusters that shape capital deployment patterns across domestic fabs. Each segmentation axis reveals where process node investments concentrate versus where mature geometries sustain margin pools.
Product Type:
Capital intensity varies sharply across product categories, with leading-edge digital fabrication demanding multibillion-dollar cleanroom investments while analog processes run on depreciated equipment.
- Digital ICs:Microprocessors and memory devices fabricated at sub-7 nanometer geometries require EUV lithography scanners costing over $150 million per unit. Cloud infrastructure expansion in Virginia and Oregon data center corridors is pulling advanced CMOS wafer starts from Intel's Arizona and Oregon captive networks.
- Analog ICs:Power management and signal conditioning chips utilize mature process nodes with equipment depreciation cycles exceeding fifteen years. Texas Instruments anchors 300-millimeter analog capacity in Richardson, Texas, competing on cost structure rather than geometry scaling.
- Mixed-Signal ICs:Data converters and interface chips blending analog and digital functions on single die. Automotive sensor fusion architectures in Michigan and Ohio are expanding demand for precision mixed-signal components.
- Power ICs:Voltage regulators and motor drivers for electrified platforms. Gallium nitride qualification timelines for 800-volt EV architectures are compressing traditional silicon MOSFET positions in high-frequency conversion.
Digital ICs absorb the bulk of installed capacity; Power ICs is expanding most quickly.
Application:
Application segmentation tracks where chip content per unit is multiplying fastest, revealing which end-use verticals justify greenfield fab construction.
- Automotive:Battery management systems and sensor fusion architectures are multiplying semiconductor content per vehicle platform. Electrified powertrains from Detroit Three OEMs and Tesla's Austin operations are pulling analog and power IC demand from Texas and Arizona fabs.
- Consumer Electronics:Smartphones and wearables drive leading-edge process node requirements. Design activity concentrates in California and Washington state, though wafer fabrication increasingly sources from domestic CHIPS Act incentivized facilities.
- Telecommunications:Baseband processors and RF front-end modules for 5G infrastructure. Network equipment deployment by Verizon and AT&T is sustaining demand for high-frequency mixed-signal components.
- Industrial Equipment:Programmable logic controllers and motor drives for factory automation. Midwest manufacturing corridors in Illinois and Ohio are expanding industrial semiconductor procurement through qualified supplier lists.
Automotive claims the steepest expansion trajectory; Consumer Electronics retains the largest absolute volume position.
End User:
End user structure determines procurement channel economics, with direct OEM relationships commanding volume discounts that aftermarket channels cannot match.
- OEMs:Original equipment manufacturers in automotive and aerospace sectors consolidate procurement through qualified manufacturer lists. Pentagon acquisition directives concentrate radiation-hardened orders with Arizona and Texas fabs holding Trusted Foundry accreditation.
- Tier-1 Suppliers:Delphi, Bosch, and Denso operations in South Carolina and Tennessee intermediate between chip vendors and vehicle assembly plants. These suppliers are qualifying GaN devices for 800-volt architectures at accelerated timelines.
- Aftermarket Providers:Replacement component distributors serving repair and upgrade demand. Channel margins compress where Taiwanese and Chinese foundry scale advantages dominate legacy node supply.
- Electronics Manufacturers:Contract manufacturers and EMS providers assembling finished systems. Foxconn and Jabil facilities in Wisconsin and Florida are expanding domestic component sourcing to satisfy CHIPS Act domestic content requirements.
OEMs dominate procurement volume; Tier-1 Suppliers are gaining share fastest through direct foundry partnerships.
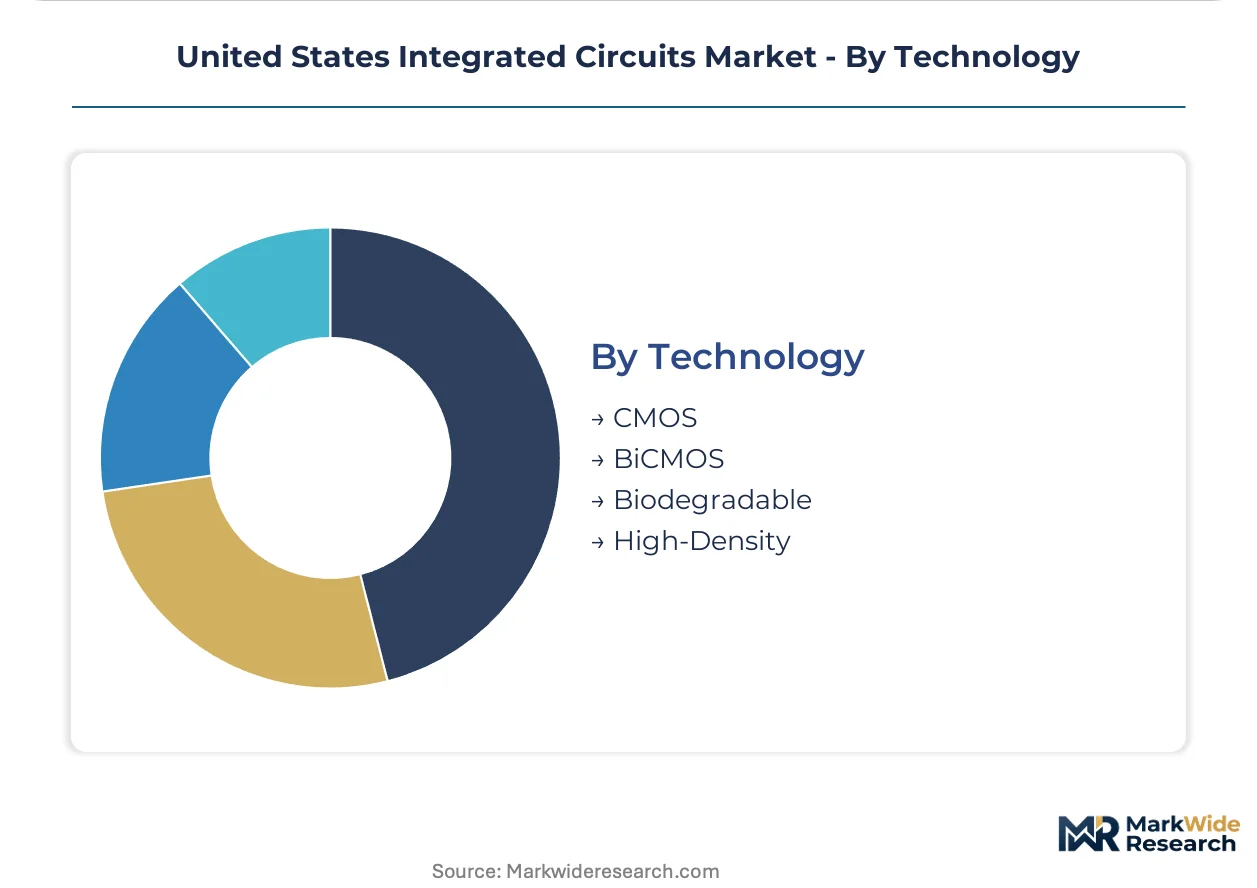
Technology:
Technology segmentation separates commoditized process platforms from emerging architectures that command patent-protected premiums.
- CMOS:Complementary metal-oxide-semiconductor dominates microprocessor and memory fabrication. Intel Corporation leverages captive Arizona and Oregon networks to sustain process node development without overseas dependency.
- BiCMOS:Bipolar-CMOS integration for high-speed analog and RF applications. Defense contractors are accelerating procurement of BiCMOS-based secure microelectronics from domestic qualified sources.
- High-Density:Three-dimensional stacking and advanced packaging architectures. Chiplets and heterogeneous integration are creating white space for domestic OSAT capacity expansion outside traditional wafer fabrication.
- Biodegradable:Emerging substrate materials for temporary medical and environmental monitoring applications. EPA PFAS disclosure frameworks are indirectly accelerating research into alternative chemistries for specialty semiconductor applications.
CMOS commands the overwhelming share of wafer starts; High-Density packaging is climbing the fastest as transistor scaling slows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic fabrication capacity lags consumption by a substantial margin, with Arizona, Texas, and New York absorbing the bulk of CHIPS Act capital while legacy demand clusters in California and Oregon remain import-dependent for leading-edge geometries.
Arizona
Phoenix and Chandler host the densest concentration of new 300-millimeter fab construction, with Intel Corporation and Taiwan Semiconductor Manufacturing Company expanding captive and merchant capacity simultaneously. EPA PFAS disclosure frameworks are accelerating cleanroom chemistry upgrades at existing facilities. Defense procurement mandates from Pentagon acquisition directives are concentrating radiation-hardened orders with Trusted Foundry-accredited operations in the Phoenix metro corridor.
Texas
Richardson and Dallas anchor analog and power semiconductor production, with Texas Instruments sustaining 300-millimeter capacity expansion for automotive battery management systems. The CHIPS and Science Act directs Department of Commerce incentives toward domestic fabrication in this corridor. Electrified powertrain demand from Tesla's Austin Gigafactory and Detroit Three suppliers is pulling analog IC wafer starts from local foundries.
New York
Albany and the Hudson Valley concentrate research-intensive development through the Albany Nanotech Complex and GlobalFoundries' Malta fabrication campus. Inflation Reduction Act clean energy manufacturing credits are offsetting depreciation schedules for new fab construction. DOE funding for domestic production equipment is accelerating tool procurement timelines for facilities targeting advanced packaging architectures.
Oregon
Hillsboro and Portland sustain Intel's captive development network for process node advancement without overseas dependency. OSHA's updated semiconductor industry standards for hazardous energy control are mandating operational protocol revisions at legacy facilities. Cloud infrastructure expansion in Pacific Northwest data center corridors is pulling advanced CMOS wafer starts from local fabrication networks.
California
San Jose and Silicon Valley concentrate fabless design activity for AI training accelerators and 5G baseband processors, though wafer fabrication increasingly sources from domestic CHIPS Act-incentivized facilities. BIS export control classifications on advanced lithography equipment are constraining local capability progression at specific technology thresholds. NVIDIA Corporation's GPU architecture development in Santa Clara exemplifies software-coupled hardware ecosystem differentiation.
United States Integrated Circuits Market Competitive Landscape
The competitive structure tilts toward integrated device manufacturers with captive fabrication networks rather than fabless specialists dependent on merchant foundry access. Market concentration reflects multibillion-dollar cleanroom investments that create barriers to entry at leading-edge geometries. Three archetypes dominate: vertically integrated analog specialists competing on cost structure, captive digital fabricators sustaining process node development, and fabless architecture designers coupling hardware to software ecosystems. Dominant competitive moves include strategic partnerships for advanced packaging capacity and geographic expansion to secure CHIPS Act incentive eligibility.
Among domestic integrated device manufacturers, Intel Corporation, Texas Instruments, and Analog Devices exemplify the vertically integrated archetype that sustains domestic fabrication without overseas dependency. Intel Corporation occupies a position anchored in Arizona and Oregon captive networks for process node development. Texas Instruments represents the analog specialist tier competing on cost structure rather than leading-edge geometry at its Richardson, Texas 300-millimeter campus. Analog Devices sits within the mixed-signal tier serving automotive sensor fusion architectures in Michigan and Ohio.
| Leading Market Players |
|---|
| Intel Corporation |
| Texas Instruments |
| Analog Devices |
| Micron Technology |
| Qualcomm Technologies |
| Broadcom |
| NVIDIA Corporation |
| GlobalFoundries |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
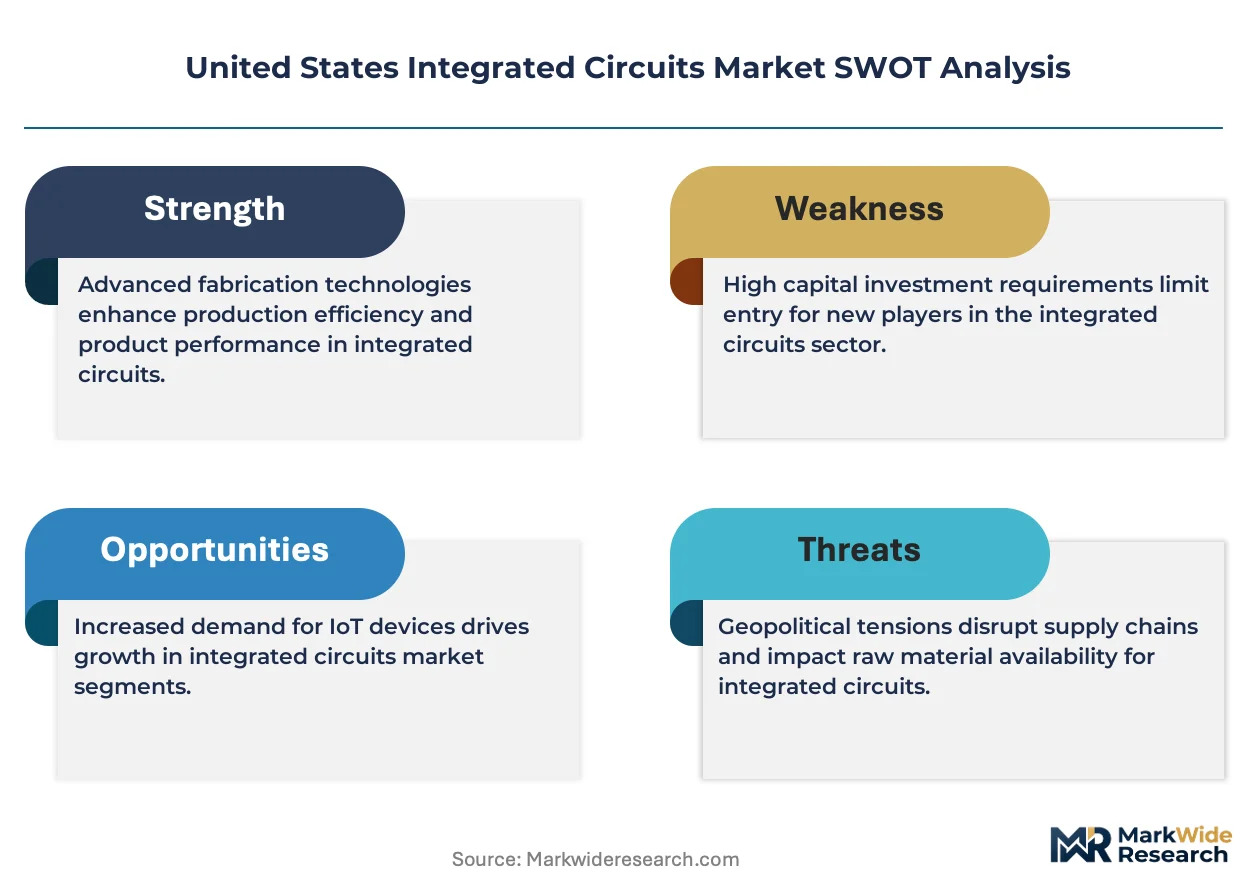
CHIPS Act-financed fabrication facilities in Arizona and Texas anchor supply-side concentration that grants compliant domestic foundries pricing power over automotive and defense procurement channels. EPA PFAS disclosure mandates create compliance cost differentials that favor capital-rich incumbents, compressing margin flexibility for legacy facilities retrofitting cleanroom chemistry infrastructure.
Pricing Analysis
Cost-down pressure on mature analog nodes accelerates because Taiwanese and Chinese foundry scale advantages outmatch US-based cost structures at geometries above 28 nanometers. Contract-based long-term offtake agreements dominate defense and automotive procurement, with volume scale and Trusted Foundry certification tier as the primary price differentiation drivers. Pricing softness reflects legacy node oversupply from Asian merchant foundries. Tier-1 automotive suppliers exhibit highest price sensitivity; Pentagon acquisition offices demonstrate lowest sensitivity due to mission-critical qualification requirements.
Supply Chain Analysis
Process engineer scarcity in Arizona and Oregon constrains domestic EUV lithography scanner deployment regardless of capital availability. Taiwan, South Korea, and the Netherlands concentrate critical supply for extreme ultraviolet scanners, high-purity fluorinated process gases, and advanced photoresist chemistries. The supply chain draws from single-source vulnerability in Dutch lithography equipment where BIS export license timelines create procurement freezes. Distribution runs through qualified manufacturer lists for defense applications and direct foundry partnerships for automotive Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Integrated Circuits Market operates as a cost-of-compliance arena where EPA PFAS reporting obligations and OSHA cleanroom standards erect capital barriers that protect accredited incumbents from undercapitalized challengers.
For Market Incumbents: Anticipate margin compression at mature nodes by accelerating heterogeneous integration packaging investments in New York and Ohio facilities. Secure backward integration into gallium nitride substrate supply before automotive qualification windows close. Defensive consolidation through Trusted Foundry accreditation maintenance protects Pentagon procurement channels from merchant market displacement. For New Entrants and Emerging Players: Defense contractor procurement offices represent the most penetrable channel for radiation-hardened specialty suppliers lacking scale for automotive volume. Target space commercialization applications where low-earth orbit satellite constellations demand radiation-tolerant components that legacy automotive fabs can retool to supply. A foundry-service-subscription go-to-market angle bypasses upfront capacity commitment barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor analog specialists with depreciated 300-millimeter equipment in Texas and Arizona where CHIPS Act incentives offset retooling costs. Long-term viability hinges on captive automotive qualification pipelines rather than merchant spot market exposure. The signal to monitor is BIS lithography equipment license approval velocity for sub-7 nanometer capability progression.| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Accreditation | Pentagon procurement mandates concentrate volume with accredited Arizona and Texas fabs. |
| Heterogeneous Integration Capacity | Chiplets architectures create white space for domestic OSAT expansion outside wafer fabrication. |
| Gallium Nitride Qualification | Automotive Tier-1 suppliers accelerate 800-volt architecture timelines compressing silicon MOSFET positions. |
| PFAS Compliance Infrastructure | EPA disclosure frameworks favor fabs with capital reserves for cleanroom chemistry upgrades. |
| Process Engineer Pipeline Development | Atomic layer deposition and EUV photoresist specialization shortages constrain advanced node progression. |
Research Methodology
Independent corroboration across foundry operations executives, defense procurement officers, automotive Tier-1 supplier engineering directors, and EPA regulatory affairs leads underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings, BIS export control determinations, CHIPS Act NIST incentive disbursement records, and OSHA semiconductor industry standard updates. Bottom-up wafer start projections from individual fab announcements reconcile with top-down consumption estimates from cloud infrastructure and automotive OEM procurement disclosures.
Comparable-period anchoring to historical capital expenditure cycles and foundry utilization rates structures the projection horizon. The analytical framework segments by product type, application vertical, end-user procurement channel, and technology node geometry. CAGRs derive from installed capacity expansion schedules mapped against demand pull from electrified automotive platforms and defense procurement mandates. Forecast inputs incorporate lithography equipment delivery timelines and cleanroom construction completion rates.
Caveats apply where BIS export license classification uncertainty or European fluorinated gas supply disruptions could materially shift the outlook. Forecasts embed assumptions regarding CHIPS Act incentive continuity and EPA enforcement intensity that regulatory revision could invalidate. A small set of triggers—lithography scanner delivery schedules, automotive platform electrification cadence, and Pentagon acquisition directive revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Touch Controller IC Market
IC (Integrated Circuits)
Application Specific Analog IC Market
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market