
 Gastroretentive Drug Delivery Systems Market | 2026-2036
Gastroretentive Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Gastroretentive Drug Delivery Systems Market Intelligence
The EU Green Deal is recalibrating pharmaceutical manufacturing standards across Europe, pushing contract manufacturers toward biodegradable polymer alternatives. Catalent leverages its biologics expertise to sustain leadership in complex oral dosage development. Lonza anchors European production capacity for gastroretentive excipients. Evonik Industries AG specializes in functional polymer coatings that control gastric retention duration.
Gastroretentive drug delivery systems employ buoyant, bioadhesive, or expandable formulations to prolong gastric residence time, typically achieving six to twelve hours of retention through density manipulation or mucosal adhesion. These systems primarily serve patients requiring sustained plasma levels of narrow therapeutic index drugs. Floating tablets dominate current revenue pools due to established manufacturing scalability and clinician familiarity. Novel biopolymer technology represents the fastest-expanding segment as alginate and chitosan derivatives gain regulatory traction for improved biocompatibility. Hydrogels occupy a mature niche with stable margins in antibiotic delivery applications.
The FDA enforces bioequivalence standards that directly shape gastroretentive formulation development timelines and clinical trial designs. EMA's MDR framework and REACH chemical safety protocols govern polymer sourcing and device classification across European markets. ISO 13485 quality management requirements filter market access for system component suppliers. Stakeholders must monitor evolving pharmacopeial monographs for novel excipients as regulatory science races to keep pace with biopolymer innovation.
Market Dynamics
The FDA's quality-by-design guidelines are compressing formulation development timelines while forcing polymer suppliers to validate excipient performance under gastric conditions before clinical trials commence. This regulatory pressure is restructuring competitive positioning around pre-validated material libraries rather than custom synthesis capabilities.
Growth Catalysts
- Floating tablet adoption:Hospital pharmacies serving diabetes management patients are standardizing on buoyant formulations to achieve sustained plasma levels of narrow therapeutic index drugs.
- EU Green Deal polymer mandates:Biodegradable alternatives to synthetic excipients are gaining formulary preference as contract manufacturers retool European production lines.
- Chronic disease prevalence:The United States, Germany, and Japan are concentrating demand for specialized gastric retention therapies among aging patient populations.
Market Restraints
- Alginate supply concentration:Seaweed harvesting disruptions in specific coastal regions create raw material volatility for bioadhesive formulations.
- REACH compliance costs:European polymer importers face extended chemical safety documentation timelines that delay novel excipient market entry.
- Biopharmaceutical substitution:Injectable GLP-1 therapies are capturing patient share previously targeted by oral gastroretentive diabetes treatments.
Strategic Opportunities
- Antibiotic delivery hydrogels:Mature manufacturing infrastructure supports margin expansion in hospital-acquired infection protocols.
- Japanese PMDA fast-track pathways:Novel chitosan derivatives qualify for accelerated review when demonstrating improved biocompatibility profiles.
- Direct-to-clinic polymer sourcing:Specialty compounders are bypassing traditional distributor networks to capture formulation development partnerships.
Industry Challenges
- Bioequivalence study design:FDA scintigraphy requirements demand specialized imaging capabilities that extend clinical validation timelines.
- ISO 13485 certification gaps:Component suppliers struggle to demonstrate quality management compliance for device-drug combination products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastroretentive Drug Delivery Systems Market |
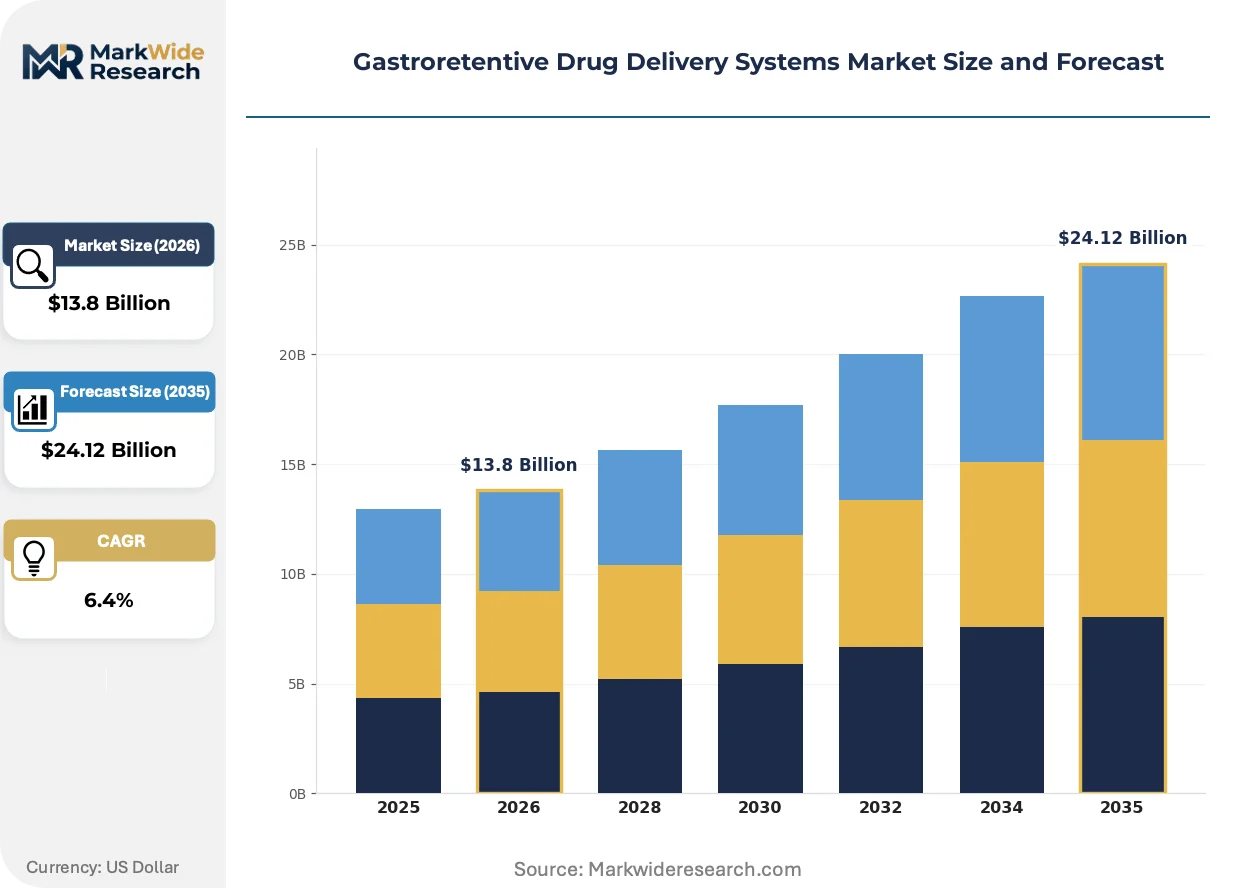
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogels, Floating Tablets, Bioadhesive Systems, Multiparticulate Systems Technology: Polymer-based, Osmotic, Novel Biopolymer, Film-coated End User: Pharmaceutical Companies, Research Institutions, Contract Manufacturers, Hospitals Application: Diabetes Management, Pain Relief, Antiretroviral Therapy, Antibiotic Delivery |
| Companies Covered | Catalent, Lonza, Evonik Industries AG, Colorcon, Quotient Sciences, F. Hoffmann-La Roche, GlaxoSmithKline, Pfizer Inc., Sun Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastroretentive Drug Delivery Systems Market Strategic Shifts & Innovations
Novel biopolymer technology is unifying formulation performance with sustainability credentials as alginate and chitosan derivatives displace petroleum-based excipients. This convergence is compressing the gap between regulatory approval and commercial manufacturing scale.
Functional polymer coatings from Evonik Industries AG are unifying gastric retention duration control with tunable release kinetics. Specialty pharmaceutical manufacturers are adopting these materials at accelerated pace for pediatric and geriatric formulations. The technology is unifying previously separate formulation development and regulatory submission pathways.
REACH chemical safety protocols are forcing polymer suppliers to document excipient fate in gastric environments before European market authorization. Industrial consequence includes mandatory biodegradability testing that adds twelve to eighteen months to qualification timelines. Hydrogel-based antibiotic delivery systems face the steepest compliance burden due to complex polymer-solvent interactions.
Hospital pharmacy procurement committees are consolidating supplier relationships around pre-qualified excipient portfolios rather than project-specific sourcing. This concentration is displacing regional compounders in favor of vertically integrated material-science firms with validated regulatory dossiers. The United States exhibits the most pronounced consolidation as health system mergers reduce vendor counts.
Gastroretentive Drug Delivery Systems Market Segmentation
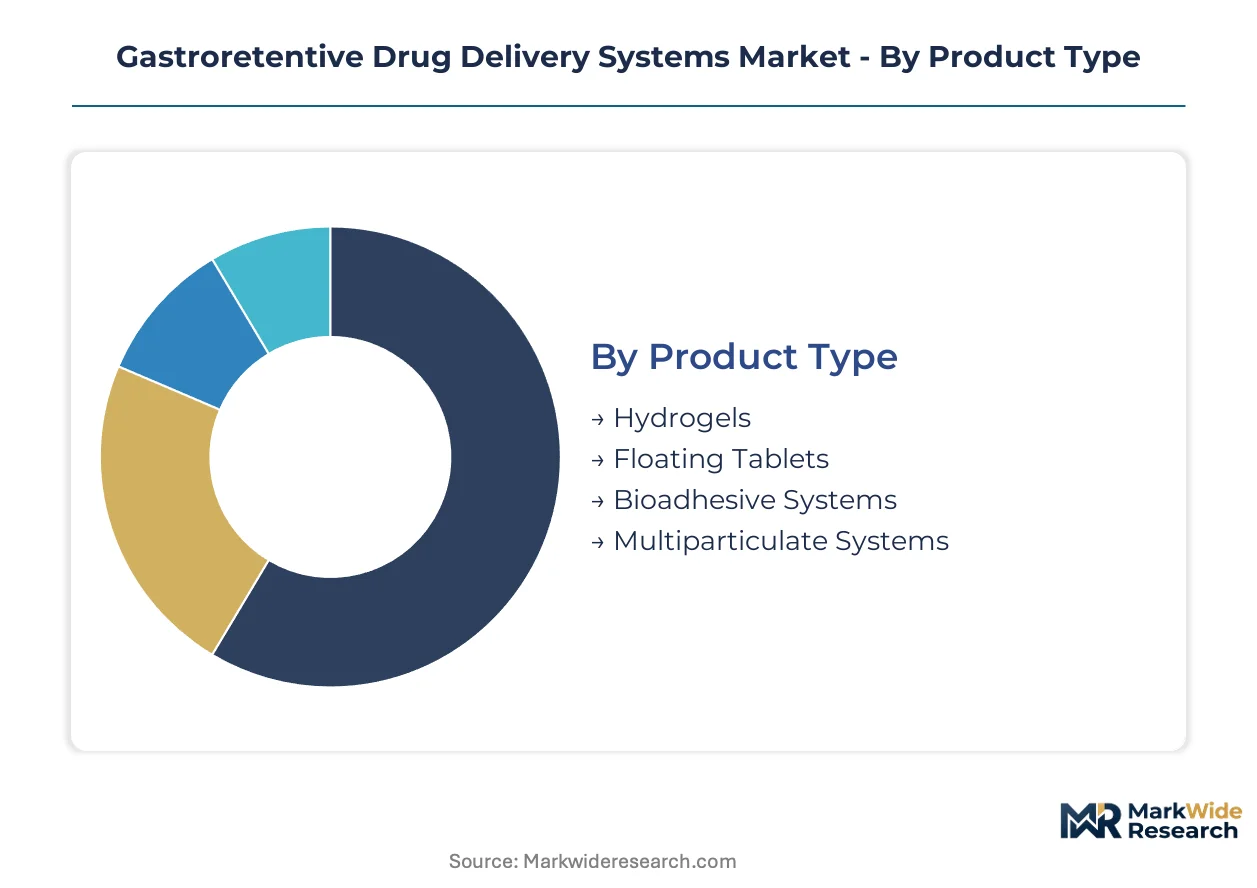
Gastroretentive drug delivery systems fragment across formulation physics, manufacturing technology, and clinical application. Each segmentation axis reveals distinct margin structures and regulatory pathways that shape vendor specialization.
Product Type:
Customization intensity varies sharply across this category, from standardized floating tablet platforms to patient-specific hydrogel formulations requiring compounding expertise.
- Floating Tablets:Buoyant core-shell architectures achieve gastric retention through density differentials below 1.0 g/cm³. Hospital pharmacies in the United States and Germany standardize these for diabetes patients requiring sustained narrow-therapeutic-index drug exposure. Manufacturing scalability and FDA bioequivalence precedent support formulary dominance.
- Hydrogels:Three-dimensional polymer networks swell upon hydration to achieve mechanical retention against gastric emptying. Antibiotic delivery applications in hospital-acquired infection protocols concentrate demand in Japan and Germany. REACH compliance burdens for polymer-solvent interactions extend European qualification timelines.
- Bioadhesive Systems:Mucoadhesive polymers such as carbopol and chitosan derivatives prolong residence through electrostatic adhesion to gastric mucosa.
- Multiparticulate Systems:Dispersed microspheres or beads distribute retention risk across numerous discrete units, reducing dose-dumping probability.
Leading the category by volume: Floating Tablets. Growing fastest: Hydrogels.
Technology:
Cost tier separation distinguishes commodity polymer platforms from premium biopolymer alternatives commanding sustainability premiums.
- Novel Biopolymer:Alginate and chitosan derivatives displace petroleum-based excipients under EU Green Deal mandates. Japanese PMDA fast-track pathways accelerate approval for formulations demonstrating superior biocompatibility profiles. Seaweed harvesting concentration in specific coastal regions creates raw material volatility.
- Polymer-based:Established synthetic excipients such as HPMC and Eudragit dominate current manufacturing throughput. Contract manufacturers retool European production lines toward biodegradable alternatives, compressing legacy margins.
- Osmotic:Semipermeable membrane systems control drug release through osmotic pressure differentials independent of gastric pH.
- Film-coated:Functional polymer coatings from specialty suppliers tune gastric retention duration alongside release kinetics.
Dominating current revenue: Polymer-based. Expanding most quickly: Novel Biopolymer.
End User:
Customer type determines procurement sophistication, from research-scale flexibility to hospital pharmacy formulary consolidation.
- Pharmaceutical Companies:Integrated drug developers validate excipient libraries under FDA quality-by-design guidelines before clinical trial initiation. Pre-validated material portfolios compress formulation timelines versus custom synthesis routes.
- Contract Manufacturers:European CDMOs anchor production capacity for gastroretentive excipients while absorbing REACH chemical safety documentation costs.
- Research Institutions:Academic centers explore chitosan derivative biocompatibility for pediatric and geriatric applications.
- Hospitals:Pharmacy procurement committees consolidate supplier relationships around pre-qualified excipient portfolios, displacing regional compounders.
Capturing largest procurement volume: Pharmaceutical Companies. Procurement consolidation accelerating fastest: Hospitals.
Application:
Maturity gradient separates established antibiotic protocols from emerging diabetes management applications facing biopharmaceutical substitution pressure.
- Diabetes Management:Sustained-release formulations for oral hypoglycemics target narrow therapeutic index drugs requiring stable plasma levels. Injectable GLP-1 therapies capture patient share previously addressed by gastroretentive oral alternatives.
- Antibiotic Delivery:Hydrogel-based systems achieve localized gastric infection control with mature manufacturing infrastructure supporting margin expansion.
- Pain Relief:Extended-release NSAID formulations reduce dosing frequency for chronic pain patients.
- Antiretroviral Therapy:Gastric retention improves bioavailability of protease inhibitors with pH-dependent solubility profiles.
Highest revenue concentration: Antibiotic Delivery. Facing steepest competitive pressure: Diabetes Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors European pharmaceutical innovation for gastroretentive formulations, with the Rhine corridor connecting Swiss headquarters to German manufacturing clusters and French regulatory science centers.
United States
Hospital pharmacy procurement committees in the United States consolidate supplier relationships around pre-qualified excipient portfolios as health system mergers reduce vendor counts. FDA quality-by-design guidelines compress formulation development timelines while forcing polymer validation under gastric conditions before clinical trials commence. Greater Boston hosts contract manufacturers retooling toward biodegradable alternatives.
Germany
German contract manufacturers anchor European production capacity for gastroretentive excipients while absorbing REACH chemical safety documentation costs. The EU Green Deal recalibrates pharmaceutical manufacturing standards, pushing producers toward biodegradable polymer alternatives. The Rhine-Main industrial corridor concentrates hydrogel manufacturing infrastructure for antibiotic delivery applications.
Japan
Aging patient populations in Japan concentrate demand for specialized gastric retention therapies among chronic disease management protocols. PMDA fast-track pathways accelerate review for novel chitosan derivatives demonstrating improved biocompatibility profiles. The Kanto region around Tokyo hosts research institutions exploring pediatric and geriatric formulation applications.
Switzerland
Swiss pharmaceutical clusters leverage biologics expertise to sustain leadership positions in complex oral dosage development. Swissmedic regulations align with EMA frameworks while maintaining distinct polymer validation requirements for device-drug combination products. Basel-based innovation centers specialize in functional polymer coatings controlling gastric retention duration.
India
Indian pharmaceutical manufacturers expand export-oriented production of floating tablet platforms for diabetes management markets. CDSCO bioequivalence standards shape clinical trial designs for gastroretentive formulations targeting narrow therapeutic index drugs. Hyderabad and Ahmedabad clusters develop cost-competitive manufacturing infrastructure for polymer-based excipient supply.
Gastroretentive Drug Delivery Systems Market Key Industry Players
The competitive structure tilts toward vertically integrated material-science firms with validated regulatory dossiers rather than regional compounders. Pre-qualified excipient portfolios compress formulation timelines versus custom synthesis routes, concentrating procurement relationships. Three archetypes dominate: multinational CDMOs with biologics expertise, specialty polymer suppliers with functional coating capabilities, and research-scale compounders serving academic partnerships. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves as manufacturers retool for biodegradable alternatives.
Within the integrated CDMO tier, Catalent and Lonza occupy positions exemplifying scale-driven formulation development capabilities. Evonik Industries AG anchors the specialty polymer supplier archetype with German-based functional coating expertise. These three entities represent the competitive concentration around pre-validated material libraries that regulatory pressure has made decisive for market positioning.
| Leading Market Players |
|---|
| Catalent |
| Lonza |
| Evonik Industries AG |
| Colorcon |
| Quotient Sciences |
| F. Hoffmann-La Roche |
| GlaxoSmithKline |
| Pfizer Inc. |
| Sun Pharma |
| Others |
Cost & Logistics Intelligence
EU Green Deal mandates on biodegradable excipients gate qualified supply access and premium-tier pricing power for polymer suppliers serving European contract manufacturers. Hospital pharmacy procurement committees in the United States and Germany now demand pre-validated material libraries, compressing margins for regional compounders lacking REACH-compliant dossiers while rewarding vertically integrated firms with certified biodegradable alternatives.
Pricing Analysis
Outcome-based pricing anchors contract manufacturing agreements for gastroretentive formulations, with fees tied to bioequivalence study success rates and regulatory approval timelines. Three-tier pricing structure across premium, standard, and economy levels separates novel biopolymer formulations with PMDA fast-track eligibility from legacy HPMC platforms and commodity excipient supply. Pricing pressure stems from injectable GLP-1 therapies capturing diabetes patient share previously targeted by oral gastroretentive products. Research institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while integrated pharmaceutical companies prioritize qualification speed over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from FDA quality-by-design guidelines compel pharmaceutical companies to qualify multiple polymer suppliers before clinical trial initiation, extending vendor onboarding timelines. Supply concentrates in Germany, Japan, and coastal regions of France where seaweed harvesting supports alginate derivative production. Raw material dependencies include chitosan from crustacean processing, pharmaceutical-grade HPMC, and functional coating polymers from specialty chemical producers. Single-source vulnerability persists for novel biopolymer grades with limited qualified manufacturers. Distribution runs through direct-to-clinic polymer sourcing partnerships that bypass traditional distributor networks for formulation development collaborations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH chemical safety documentation and FDA bioequivalence standards create barrier-to-entry moats favoring incumbent players with pre-validated regulatory dossiers.
For Market Incumbents: Anchor market position through backward integration into seaweed harvesting operations for alginate supply security and captive production of chitosan derivatives. Expand European manufacturing footprint to absorb REACH compliance costs while competitors face extended qualification timelines. Biopharmaceutical substitution pressure from injectable diabetes therapies demands defensive portfolio diversification into antibiotic delivery hydrogels with mature hospital procurement relationships. For New Entrants and Emerging Players: Direct-to-clinic digital sourcing platforms offer the most penetrable entry vector, bypassing consolidated distributor networks serving hospital pharmacy procurement committees. Target research institutions exploring pediatric and geriatric chitosan applications with flexible small-batch manufacturing capabilities. White-space opportunity concentrates in Japanese PMDA fast-track pathways for biocompatibility-demonstrating formulations, where incumbent dossier advantages remain less entrenched. For Investors and Strategic Acquirers: Japanese PMDA approval of novel chitosan derivatives is the leading indicator that biopolymer innovation is achieving regulatory traction and premium pricing power. Long-term viability favors vertically integrated material-science firms with validated biodegradable polymer libraries over regional compounders dependent on custom synthesis margins. Acquisition target archetype: specialty coating suppliers with functional polymer expertise serving device-drug combination products. Signal to monitor: hospital system merger activity reducing vendor counts in United States procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Transition | EU Green Deal compliance secures formulary access with German hospital pharmacies. |
| PMDA Fast-Track Qualification | Accelerated Japanese approval for chitosan derivatives commands sustainability premiums. |
| Direct-to-Clinic Sourcing Partnerships | Bypasses distributor consolidation to capture formulation development relationships. |
| Seaweed Supply Integration | Backward integration into coastal harvesting mitigates alginate raw material volatility. |
| Hospital System GPO Alignment | Pre-qualified excipient portfolios secure procurement committee consolidation benefits. |
Research Approach
Multi-period observation of FDA bioequivalence filing trends and EMA polymer validation timelines anchored the trend analysis, supplemented by interviews with regulatory affairs directors at contract manufacturers, hospital pharmacy procurement managers, formulation development scientists, and excipient supply chain planners. Secondary validation drew from FDA quality-by-design guidance documents, REACH chemical safety registration databases, PMDA fast-track approval records, and ISO 13485 certification registries. Bottom-up excipient demand modeling triangulated against top-down pharmaceutical manufacturing capacity estimates.
Input-output matrices mapped formulation physics to manufacturing technology costs across product type, technology tier, end-user procurement sophistication, and clinical application maturity. CAGRs derived from segment-level demand elasticity coefficients applied to chronic disease prevalence projections and regulatory approval velocity indices. Industry-specific forecast inputs included hospital system merger pipeline data and seaweed harvest yield variability from major coastal production zones.
Inputs from regulatory filing databases and hospital procurement contract repositories were available through the study window; gaps in real-time polymer pricing transparency introduce uncertainty bands around excipient cost assumptions. Deviation in FDA scintigraphy requirement enforcement or EMA biodegradability testing timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Telehealth Device Market
Medical Devices
Cytology Brush Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
South Korea ECG Market
Medical Devices
IoT Medical Devices Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
Polymer-Based Prefilled Syringe Market