
 Electrocautery Devices Market | 2026-2036
Electrocautery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electrocautery Devices Market Analysis
Ambulatory surgical centers is rebalancing the end-use mix as outpatient electrosurgical procedures expand faster than inpatient volumes. Medtronic Plc leverages its broad hospital footprint to sustain recurring revenue from disposable accessories. Johnson & Johnson anchors its position through deep integration with surgical stapling workflows. Erbe Elektromedizin GmbH specializes in precision bipolar systems for minimally invasive applications.
Electrocautery devices generate controlled thermal energy via radiofrequency current to cut, coagulate, or desiccate tissue during surgical intervention, with typical operating frequencies between 300 kHz and 3 MHz to avoid neuromuscular stimulation. Monopolar devices dominate procedural volume in open surgery where large tissue areas require rapid dissection, while bipolar configurations command premium placement in neurosurgical and microvascular settings where thermal spread must be contained. Radiofrequency technology occupies the core platform architecture across most installed bases, though ultrasonic alternatives are carving share in laparoscopic applications where smoke plume reduction matters.
The FDA's 510(k) premarket notification framework governs electrosurgical device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for active therapeutic devices entering European markets. ISO 60601-2-2 sets international safety benchmarks for high-frequency surgical equipment performance, shaping manufacturer R&D priorities and testing protocols. Stakeholders must track how evolving energy-based device reclassification in major jurisdictions reshapes competitive access timelines and compliance investment thresholds.
Market Dynamics
Radiofrequency-based electrocautery platforms face mounting pressure from ultrasonic energy systems in laparoscopic suites, where smoke evacuation requirements and thermal precision demands are rewriting procurement criteria across hospital systems.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedural volume in the United States is pulling capital equipment purchases toward compact, mobile electrosurgical units designed for same-day discharge protocols.
- FDA 510(k) pathway efficiency:The streamlined premarket notification framework accelerates clearance timelines for electrosurgical accessories, compressing the gap between R&D completion and commercial deployment.
- Bipolar precision migration:Neurosurgical and microvascular specialties are standardizing on advanced bipolar configurations to contain thermal spread in delicate tissue planes.
Market Restraints
- Copper and silver electrode volatility:Raw material cost swings for conductive elements constrain gross margins on disposable cautery pencils and forceps.
- EU MDR clinical evidence burden:The Medical Device Regulation's intensified documentation requirements for active therapeutic devices extend European market entry timelines by 12-18 months.
- Ultrasonic energy substitution:Harmonic scalpel systems are capturing share in laparoscopic cholecystectomy and colorectal resection cases where smoke plume reduction carries OR throughput value.
Strategic Opportunities
- India surgical infrastructure buildout:Government hospital modernization programs under Ayushman Bharat are creating first-time demand for electrosurgical generators in tier-2 and tier-3 cities.
- AI-integrated energy delivery:Machine learning algorithms that modulate power output based on real-time tissue impedance feedback are converging with traditional RF platforms.
- Direct-to-ambulatory distribution:Manufacturer bypass of traditional distributor networks for ASCs is capturing margin and accelerating service response cycles.
Industry Challenges
- Biomedical technician specialization gaps:Servicing high-frequency surgical equipment requires RF engineering expertise that hospital in-house teams rarely possess, forcing reliance on OEM service contracts.
- Legacy generator fleet interoperability:Newer disposable electrodes often carry proprietary connectors that lock out competitive accessories, complicating hospital standardization efforts.
- ISO 60601-2-2 testing bottlenecks:Third-party electromagnetic compatibility certification queues are stretching lead times for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrocautery Devices Market |
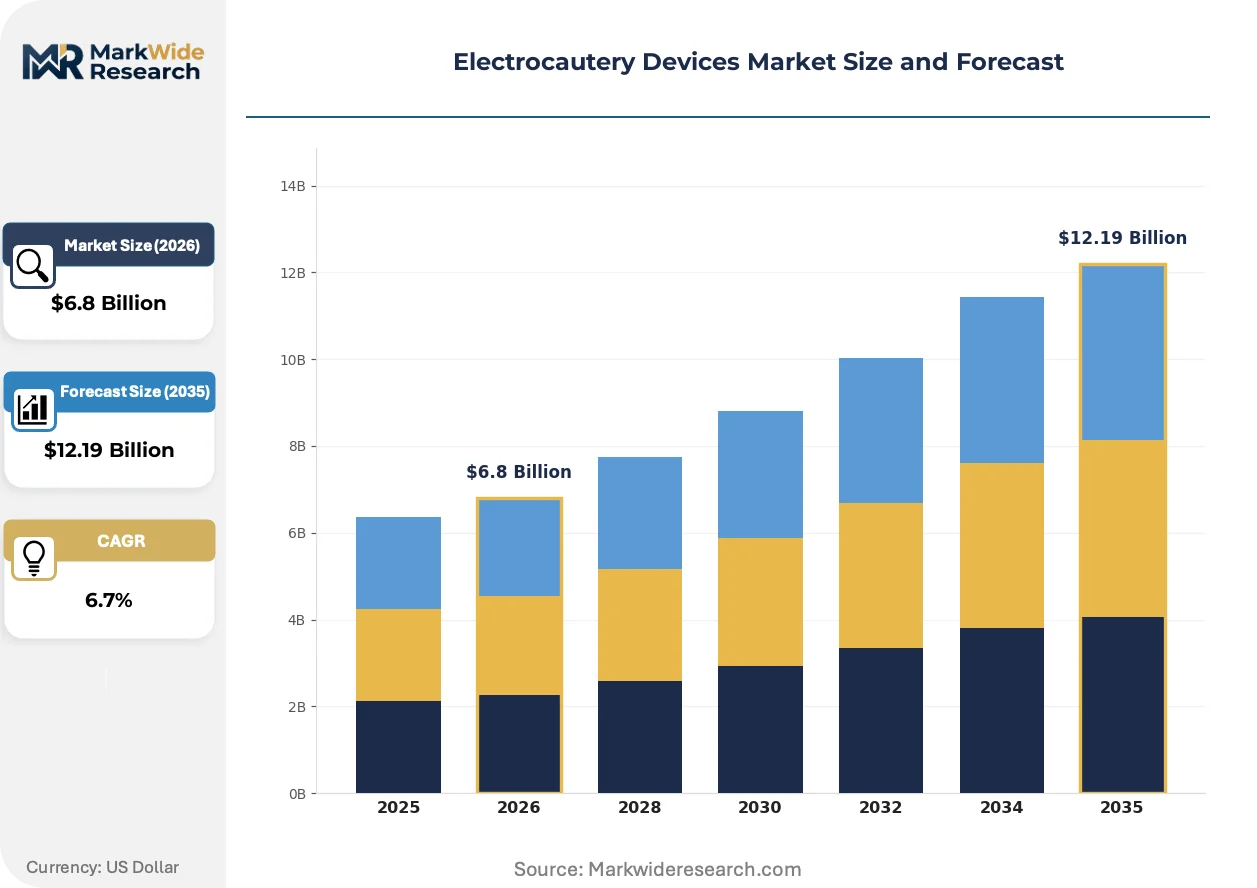
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopolar Devices, Bipolar Devices, Blades, Accessories Technology: Radiofrequency, Laser, Microwave, Ultrasonic Application: Surgical Procedures, Endoscopy, Dermatology, Gynecology End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions |
| Companies Covered | Medtronic Plc, Johnson & Johnson, Olympus Corporation, Boston Scientific Corporation, B. Braun Melsungen AG, CONMED Corporation, Erbe Elektromedizin GmbH, Smith & Nephew Plc, Bovie Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrocautery Devices Market Emerging Trajectories
Energy-based surgical platforms are undergoing platform-level reinvention as thermal precision, smoke management, and connectivity features become non-negotiable in purchasing decisions. Three developments are compressing competitive timelines.
Advanced vessel sealing technology is consolidating the fragmented landscape of hemostatic modalities. LigaSure and comparable bipolar sealing platforms now integrate feedback-controlled energy delivery that adapts to tissue impedance in real-time. Gynecologic and general surgery departments in the United States are standardizing on these systems for hysterectomy and colectomy procedures. This consolidation is compressing standalone monopolar generator placements as hospitals rationalize capital equipment footprints.
The EU Medical Device Regulation's reclassification of active surgical devices is forcing manufacturers to generate clinical performance data that 510(k) submissions previously avoided. High-frequency surgical equipment now faces notified body scrutiny comparable to implantable devices. European market entrants are responding by front-loading clinical trials and building post-market surveillance infrastructures that exceed legacy requirements.
Service contract unbundling is altering how ASCs acquire electrosurgical capability. Smaller outpatient facilities are rejecting traditional comprehensive coverage in favor of per-procedure electrode pricing with break-fix service only. This pattern is most visible in Texas and Florida ambulatory networks, where high case volumes make variable cost models preferable to fixed capital commitments.
Electrocautery Devices Market Segmentation
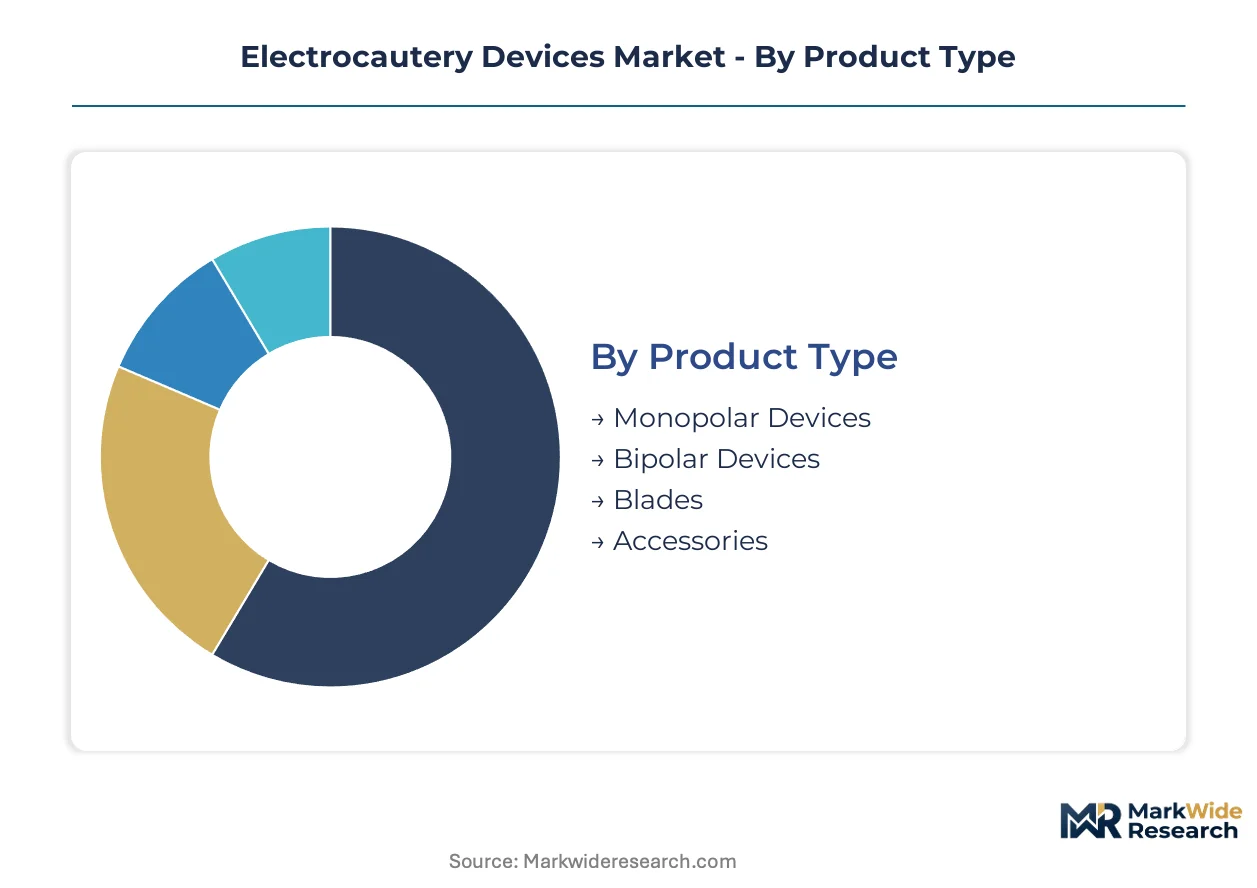
Electrocautery device purchasing decisions fragment across four critical dimensions, each carrying distinct upgrade cycles and margin profiles. Hospital procurement teams evaluate generator replacement timelines against accessory consumption rates, while ASCs prioritize compact footprints over legacy interoperability.
Product Type:
Replacement cycles for capital equipment and disposables diverge sharply, with generators refreshed every 7-10 years while electrodes turn over in single-procedure use.
- Monopolar Devices:These systems deploy a single active electrode with remote return pad, delivering high-current density for rapid tissue cutting in open abdominal and thoracic procedures. General surgery departments in the United States rely on monopolar platforms for cholecystectomy and hernia repair volume, though thermal spread concerns constrain adoption in delicate anatomical zones.
- Bipolar Devices:Current flows between two closely spaced tips, confining thermal damage to millimeter-scale tissue margins. Neurosurgical suites and microvascular operating rooms in Germany and Japan specify bipolar configurations where nerve preservation dictates outcomes, driving premium pricing over monopolar alternatives.
- Blades:Disposable cutting electrodes integrate tungsten or stainless steel tips with standardized handpiece connectors, consumed at rates tied to procedural throughput.
- Accessories:Return pads, footswitches, and smoke evacuation adapters complete the procedural ecosystem, generating recurring revenue streams independent of generator sales.
Monopolar devices sit at the top of the volume ranking, with bipolar configurations climbing the fastest as minimally invasive specialties expand.
Technology:
Energy modality selection determines smoke generation, thermal precision, and capital cost structure for surgical programs.
- Radiofrequency:Oscillating current between 300 kHz and 3 MHz cuts and coagulates through resistive heating, forming the installed base majority across hospital systems worldwide. RF generators from Erbe and Medtronic dominate OR footprints, though ultrasonic challengers are gaining laparoscopic share.
- Laser:Coherent light sources enable micron-scale ablation in ophthalmic and dermatological settings where mechanical contact risks tissue distortion. Capital costs and specialized training requirements limit deployment outside academic medical centers.
- Microwave:Electromagnetic radiation at 915 MHz or 2.45 GHz heats tissue through dielectric loss, finding hepatocellular carcinoma ablation applications in interventional radiology suites.
- Ultrasonic:Mechanical vibration at 55,500 Hz cuts and coagulates through protein denaturation, eliminating smoke plume and electrical current transmission risks. Johnson & Johnson's Harmonic platform captures cholecystectomy and colorectal resection cases where OR air quality regulations tighten.
Radiofrequency technology anchors installed base volume, with ultrasonic systems gaining share fastest in laparoscopic suites.
Application:
Procedure-specific energy requirements reshape device configuration demand across surgical service lines.
- Surgical Procedures:Open and minimally invasive interventions across general, cardiac, and orthopedic specialties consume the broadest electrocautery device spectrum, from high-wattage cutting modes to fine coagulation settings.
- Endoscopy:Flexible and rigid endoscopic platforms require compact, irrigation-compatible electrodes with precise thermal control to prevent luminal perforation.
- Dermatology:Office-based lesion removal and cosmetic procedures drive demand for portable, low-cost units with superficial penetration settings.
- Gynecology:Hysteroscopy and laparoscopic fertility procedures specify bipolar sealing technology for tubal and ovarian surgery.
Surgical procedures command the highest absolute volume, with endoscopy applications expanding most quickly as diagnostic and therapeutic volumes rise.
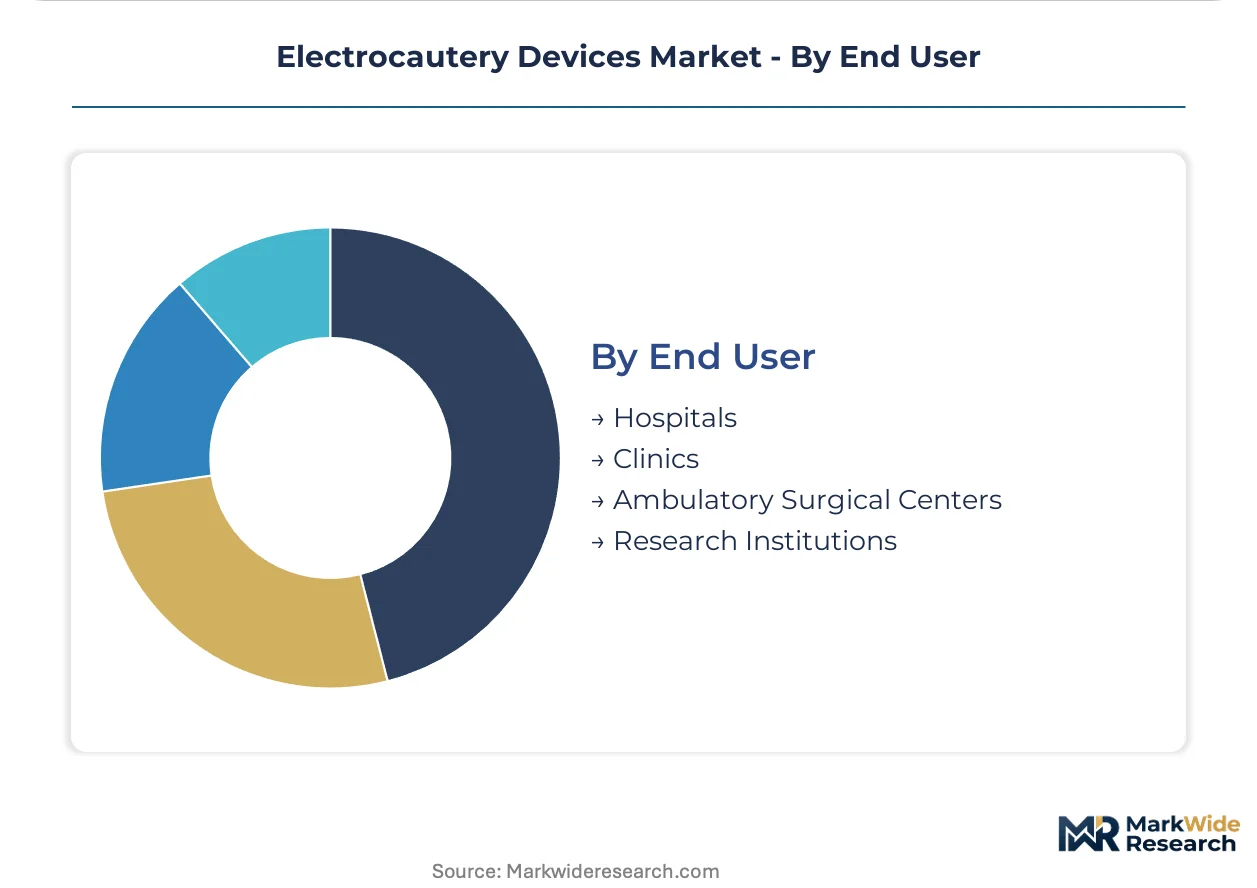
End User:
Facility scale and reimbursement structure determine capital allocation patterns and service contract preferences.
- Hospitals:Integrated delivery networks negotiate enterprise-wide generator standardization to simplify training and inventory management, amortizing capital across high surgical volumes.
- Clinics:Office-based procedural suites prioritize tabletop units with plug-and-play electrode compatibility over advanced feedback systems.
- Ambulatory Surgical Centers:Texas and Florida outpatient networks favor mobile generators with per-procedure electrode pricing models, rejecting fixed service contracts for variable cost structures aligned with case volume fluctuation.
- Research Institutions:Preclinical and translational surgery programs specify configurable research-grade platforms with open-architecture energy modulation for protocol development.
Hospitals retain the largest installed base position, with ambulatory surgical centers scaling fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis-St. Paul medical device corridor anchors global electrocautery device production and R&D concentration. Germany's precision engineering clusters and Japan's surgical robotics integration drive secondary demand poles. India's government hospital modernization programs are accelerating first-time generator installations in tier-2 cities.
United States
Ambulatory surgical centers in Texas and Florida are standardizing on mobile electrocautery units with per-procedure electrode pricing models. The FDA's 510(k) premarket notification framework compresses clearance timelines for electrosurgical accessories by 6-12 months versus full PMA pathways. Minneapolis-St. Paul hosts Medtronic's operational headquarters and a dense supplier ecosystem for RF generator components.
Germany
Neurosurgical suites in Tübingen and Heidelberg specify precision bipolar configurations where thermal containment preserves nerve function. The EU Medical Device Regulation's intensified clinical evidence requirements for active therapeutic devices extend market entry timelines. Baden-Württemberg's medical technology corridor clusters Erbe Elektromedizin and specialized component fabricators serving European OR installations.
Japan
Minimally invasive specialties in Tokyo and Osaka are integrating electrocautery platforms with surgical robotics for enhanced thermal precision. Japan's Pharmaceuticals and Medical Devices Agency maintains stringent electromagnetic compatibility standards under JIS T 0601-2-2. The Kansai region's device manufacturers supply bipolar forceps for microvascular applications across East Asian markets.
India
Government hospital modernization under Ayushman Bharat is creating first-time demand for electrosurgical generators in tier-2 and tier-3 cities. The Central Drugs Standard Control Organization regulates active therapeutic devices under Medical Device Rules 2017 with escalating classification rigor. Maharashtra's Mumbai-Pune industrial corridor hosts domestic assemblers and distributor networks serving northern and western state hospital systems.
China
Domestic manufacturers in Shanghai and Shenzhen are capturing mid-tier hospital procurement with cost-optimized RF generators. The National Medical Products Administration's 2021 revised classification rules for electrosurgical equipment impose clinical trial requirements previously waived. The Yangtze River Delta medical device cluster concentrates bipolar electrode production for both domestic consumption and Southeast Asian export.
Electrocautery Devices Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek complementary technology access and geographic reach. The vendor base consolidates around three tiers: diversified multinationals with full surgical workflow integration, specialized electrosurgical equipment houses with deep RF engineering heritage, and regional assemblers competing on capital cost. Two strategic archetypes prevail: hospital system integrators bundling generators with disposable ecosystems, and precision bipolar specialists commanding premium placement in neurosurgical settings. M&A activity and technology licensing agreements represent the dominant competitive vectors.
Among diversified multinational integrators, Medtronic Plc and Johnson & Johnson exemplify the hospital system bundling archetype through broad surgical portfolio alignment. Erbe Elektromedizin GmbH occupies the precision specialist tier with concentrated expertise in feedback-controlled energy delivery systems. These three entities represent distinct competitive positioning vectors without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Medtronic Plc |
| Johnson & Johnson |
| Olympus Corporation |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| CONMED Corporation |
| Erbe Elektromedizin GmbH |
| Smith & Nephew Plc |
| Bovie Medical Corporation |
| Others |
Supply Flow & Price Mechanics
Captive electrode production by German and Japanese precision manufacturers anchors both supply security and premium pricing power for bipolar forceps and sealing platforms. This backward integration into conductive component fabrication insulates tier-one suppliers from copper and silver volatility while locking hospital systems into proprietary accessory ecosystems.
Pricing Analysis
Copper and silver electrode cost pass-through dominates margin dynamics for disposable cautery pencils, with raw material swings compressing gross margins on standard monopolar accessories. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared precision bipolar systems from unbranded clinic-grade generators. Cost compression in the mid-tier is intensifying because ultrasonic energy substitutes are capturing laparoscopic volume. Ambulatory surgical centers exhibit highest price sensitivity, while neurosurgical suites accept premium positioning for thermal containment specifications.
Supply Chain Analysis
India's Medical Device Rules 2017 local-content mandates are reshaping sourcing patterns for domestic hospital modernization programs. Component fabrication concentrates in Germany, Japan, and the United States for precision RF generators, while electrode assembly feeds from China's Yangtze River Delta. Conductive alloys and ceramic insulators constitute critical input dependencies. Single-source vulnerability runs through specialized bipolar forceps tip suppliers. Distribution runs through GPO contracts for hospital systems and direct manufacturer relationships for ASC networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
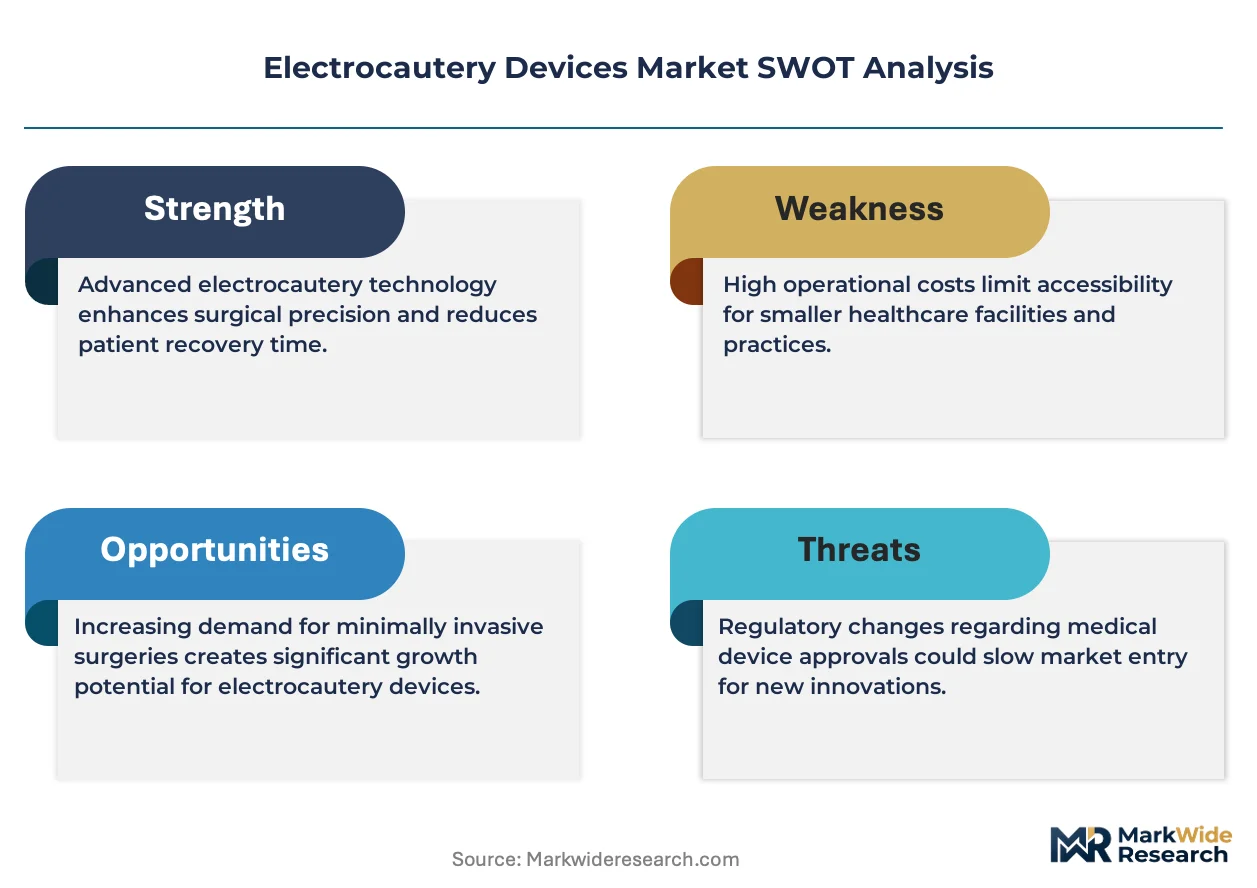
The electrocautery device market reads as a late-cycle quality story where outpatient migration and thermal precision demands are elevating specification floors across all buyer tiers.
For Market Incumbents: Cement hospital system loyalty by expanding proprietary electrode connector ecosystems that lock out competitive accessories, while accelerating FDA 510(k) clearance pipelines for AI-integrated feedback systems. Ultrasonic energy substitution in laparoscopic suites represents the primary displacement threat. Backward integration into conductive alloy sourcing insulates margin position against commodity volatility. For New Entrants and Emerging Players: Enter via India's tier-2 and tier-3 government hospital buildout under Ayushman Bharat, where first-time generator demand outpaces established supplier coverage. Mobile electrosurgical units for ASC networks in Texas and Florida offer the most penetrable white space. Direct-to-facility distribution bypassing traditional medical device distributors captures margin and accelerates service response cycles. For Investors and Strategic Acquirers: Roll-up economics work for precision bipolar specialists because hospital standardization trends are consolidating purchasing around platforms with integrated sealing technology and disposable ecosystems. The five-to-ten year viability window favors manufacturers with post-market surveillance infrastructures exceeding EU MDR requirements. Watch ultrasonic energy capture rates in laparoscopic cholecystectomy as the inflection signal for RF platform displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Buildout | Front-loaded trials satisfy notified body scrutiny for active therapeutic device reclassification. |
| AI-Integrated Energy Delivery Development | Machine learning modulation of power output based on tissue impedance feedback converges with RF platforms. |
| Direct-to-ASC Distribution Expansion | Manufacturer bypass of distributor networks captures margin and accelerates service response in outpatient settings. |
| Proprietary Connector Ecosystem Lock-in | Legacy generator fleet incompatibility with competitive accessories secures recurring electrode revenue streams. |
| India Hospital System Partnership | Ayushman Bharat modernization programs create first-time demand in tier-2 and tier-3 cities. |
Methodological Framework
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and ambulatory surgical center operators grounded qualitative findings, cross-referenced with FDA 510(k) clearance databases, EU MDR notified body guidance documents, hospital procurement records, and electrosurgical equipment service contract filings. Bottom-up and top-down triangulation validated volume estimates across product categories.
Bottom-up modeling of generator installed base and electrode consumption rates converged with top-down assessment of surgical procedural volume and capital equipment replacement cycles across the analysis window. Segmentation dimensions included energy modality, electrode configuration, application specialty, and facility type. CAGRs were derived from elasticity-adjusted demand curves incorporating outpatient migration patterns and regulatory clearance timeline shifts. Forecast inputs integrated raw material cost trajectories for conductive alloys and electromagnetic compatibility certification queue lengths.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time ASC pricing transparency and proprietary service contract terms introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding outpatient procedural volume trajectories and EU MDR implementation pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Foot and Ankle Devices Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Intubation Tubes Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Skincare Devices Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market