
 Japan Diabetes Drugs Market | 2026-2036
Japan Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Diabetes Drugs Market Foresight
Domestic pharmaceutical manufacturing is pivoting toward biologic drug substance capacity in Osaka and Kansai production corridors. Takeda Pharmaceutical Company Limited anchors its diabetes portfolio through in-house fermentation and formulation capabilities at legacy Osaka facilities. Novo Nordisk A/S competes in the Japanese insulin segment through specialized cold-chain distribution networks that extend from Copenhagen manufacturing to regional depots across Honshu. Eli Lilly and Company differentiates via co-development partnerships with domestic contract manufacturers, leveraging local regulatory expertise to accelerate product registration with PMDA.
Japan diabetes drugs comprise prescription pharmaceutical agents designed to regulate blood glucose levels through insulin supplementation, incretin pathway modulation, or renal glucose excretion inhibition, with formulations requiring stability testing at controlled temperatures between two and eight degrees Celsius for protein-based therapies. These agents serve to prevent microvascular complications including nephropathy and retinopathy in a patient population with elevated cardiovascular comorbidity burden. Insulin and GLP-1 Agonists command premium positioning due to biologic manufacturing complexity and refrigerated storage requirements, while SGLT2 Inhibitors gain share in outpatient settings through oral convenience and demonstrated heart failure risk reduction. DPP-4 Inhibitors occupy a mature revenue tier with multiple generic entrants compressing reimbursement pricing under Japan's biennial National Health Insurance drug price revisions.
PMDA reviews govern market entry timelines for novel diabetes therapies, with Japan's Ministry of Health, Labour and Welfare setting reimbursement prices through cost-effectiveness thresholds modeled on NICE frameworks. METI industrial policy promotes domestic biologics manufacturing through targeted subsidies for continuous bioprocessing equipment upgrades. Stakeholders must monitor PMDA's evolving biosimilar interchangeability guidelines and METI's pharmaceutical supply chain resilience mandates to anticipate shifts in competitive positioning and procurement requirements.
Market Dynamics
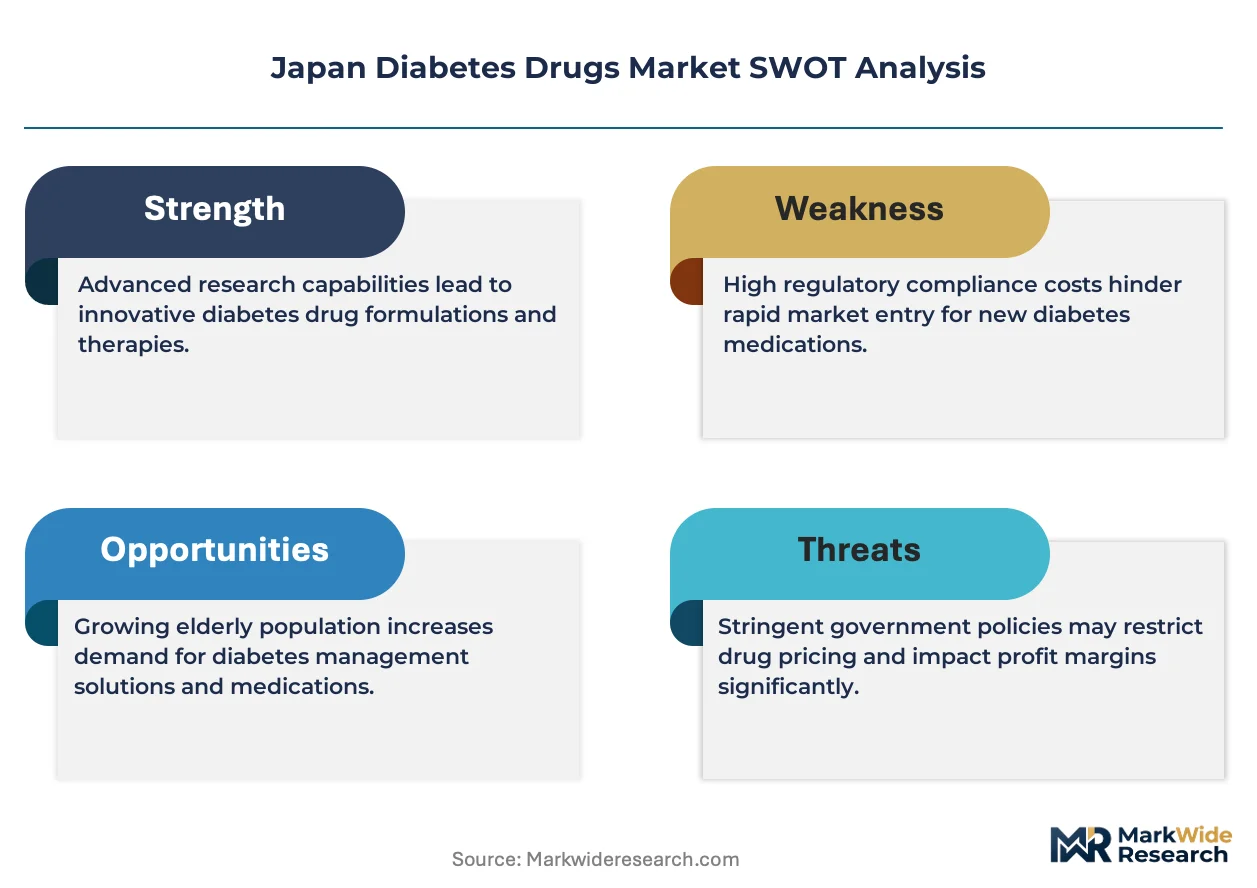
Japan's biennial National Health Insurance drug price revisions are compressing margins for oral antidiabetic agents while accelerating hospital migration toward injectable biologics with protected reimbursement tiers.
Growth Catalysts
- Biennial NHI Price Revision Framework:Japan's Ministry of Health, Labour and Welfare maintains premium reimbursement bands for biologic insulins and GLP-1 receptor agonists, incentivizing prescribing shifts toward higher-margin injectable therapies in tertiary care centers.
- Osaka-Kansai Production Corridor:METI subsidies for continuous bioprocessing equipment upgrades are expanding domestic fermentation capacity, reducing import dependency for active pharmaceutical ingredients used in protein-based diabetes treatments.
- Cardiorenal Protection Protocols:Specialist diabetes centers in Greater Tokyo are integrating SGLT2 inhibitors into heart failure prevention pathways, expanding addressable patient populations beyond glycemic control alone.
Market Restraints
- Reimbursement Compression Mechanics:Japan's biennial NHI price revisions systematically erode pricing for DPP-4 inhibitors as generic entrants multiply, collapsing revenue per prescription for manufacturers without biologic diversification.
- Cold-Chain Infrastructure Concentration:Insulin and GLP-1 agonist distribution depends on specialized refrigerated logistics networks concentrated in Honshu island depots, creating vulnerability to supply disruptions from Hokkaido or Kyushu manufacturing shortfalls.
- Biosimilar Substitution Uncertainty:PMDA's evolving interchangeability guidelines for follow-on biologics introduce formulary placement risk for originator insulin products as hospital procurement committees gain substitution authority.
Strategic Opportunities
- Kyushu Regional Expansion:Underpenetrated diabetes specialist density in Fukuoka and Saga prefectures offers whitespace for GLP-1 agonist detailing as hospital networks consolidate regional referral pathways.
- Digital Therapeutics Integration:PMDA's Sakigake fast-track designation for software-as-medical-device platforms enables convergence of continuous glucose monitoring data with automated insulin dosing algorithms in reimbursed care bundles.
- Home Infusion Channel Development:Japan's Community-based Integrated Care System reforms are expanding reimbursement for self-administered injectable therapies outside hospital settings, opening direct-to-patient distribution models.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Domestic universities produce insufficient fermentation science graduates to staff METI-subsidized capacity expansions in Osaka pharmaceutical manufacturing zones.
- PMDA Quality Management System Audits:Extended on-site inspection timelines for foreign contract manufacturing organizations delay product registration by 12-18 months, compressing effective patent life for novel diabetes therapies.
- Legacy DPP-4 Inhibitor Portfolio Stranding:Manufacturers face complex decisions on manufacturing line repurposing as generic substitution rates exceed 80 percent for oral gliptins under NHI price compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Diabetes Drugs Market |
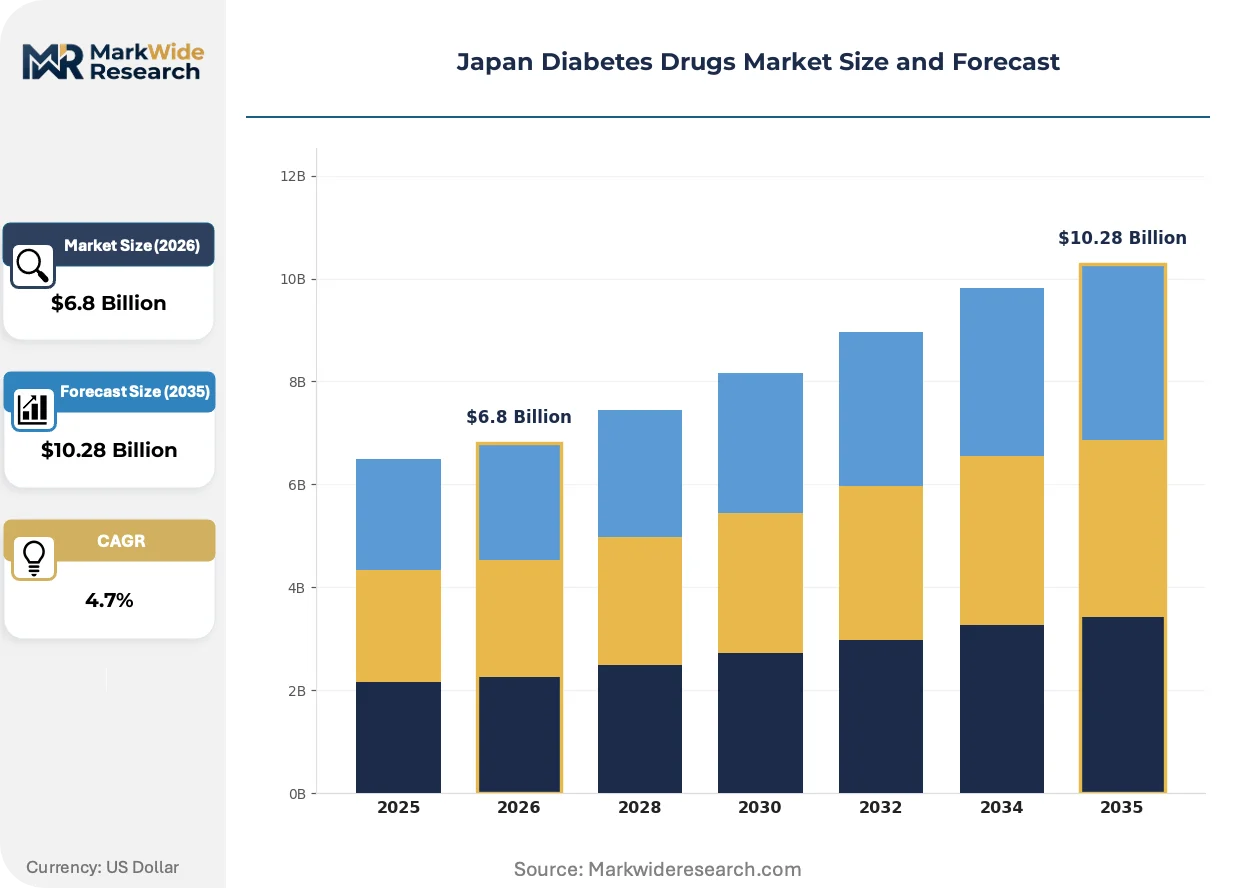
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Home Care, Retail Pharmacies Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes Distribution Channel: Direct Sales, Wholesalers, Online Pharmacies, Healthcare Providers |
| Companies Covered | Takeda Pharmaceutical Company Limited, Novo Nordisk A/S, Sanofi, Eli Lilly and Company, AstraZeneca, Boehringer Ingelheim, Merck & Co., Daiichi Sankyo Company, Astellas Pharma Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Diabetes Drugs Market Shifts & Advancements
Continuous glucose monitoring integration with automated insulin delivery systems is displacing conventional self-monitoring blood glucose protocols in Japanese tertiary care centers, reshaping device-pharmaceutical bundling strategies.
Dual-hormone artificial pancreas systems combining insulin and glucagon delivery are expanding into Type 1 diabetes management protocols at St. Luke's International Hospital and Juntendo University Hospital in Tokyo. Endocrinology departments in these centers are adopting closed-loop algorithms at twice the national average pace. The technology is compressing demand for conventional basal-bolus insulin regimens while creating new reimbursement negotiation complexity for integrated device-drug bundles.
METI's Pharmaceutical Supply Chain Resilience Mandate requires domestic buffer stock maintenance for critical biologics including insulin and GLP-1 agonists, effective fiscal year 2024. Pharmaceutical wholesalers must now hold 90-day inventory minimums at regional depots across Honshu, elevating working capital requirements. Cold-chain operators in the Kanto and Kansai regions are responding by consolidating depot networks to achieve economies of scale against mandated carrying costs.
Hospital pharmacy committees in Japan are unbundling diabetes drug procurement from device procurement, reversing decade-long bundled contracting practices. Specialist diabetes centers previously locked into single-source insulin pump and consumable agreements are now soliciting separate pharmaceutical tenders. This behavioral shift is most visible in the Greater Tokyo metropolitan area, where Tokyo Medical and Dental University Hospital and Keio University Hospital have issued unbundled GLP-1 agonist procurement specifications since 2023.
Japan Diabetes Drugs Market Segmentation
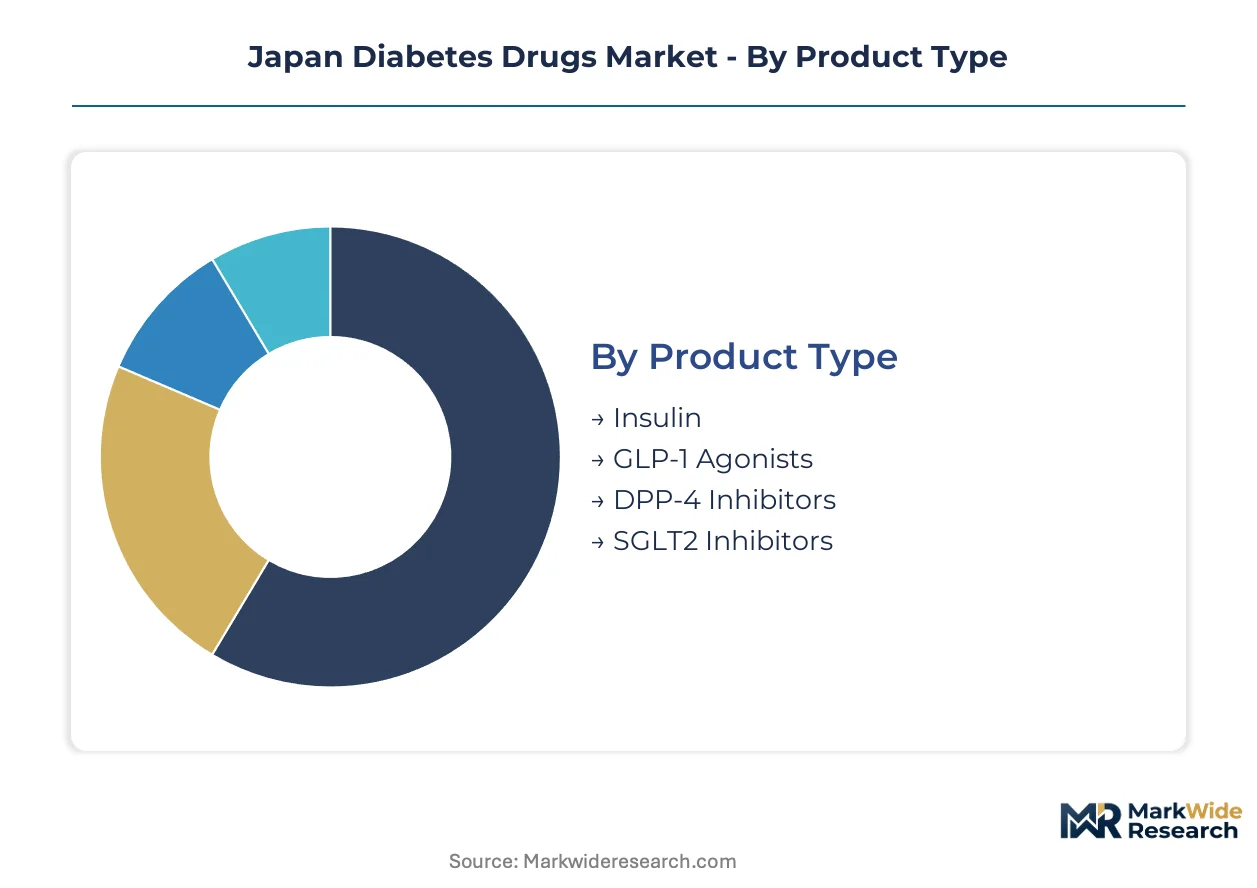
Japan's diabetes drug segmentation reflects divergent reimbursement tiers and prescribing hierarchies across tertiary centers versus community settings. Each dimension captures distinct procurement behaviors, cold-chain requirements, and patient access pathways that manufacturers must navigate.
Product Type:
Biologic manufacturing complexity and protected reimbursement bands are driving upgrade cycles from oral agents toward injectable protein therapies in Japanese hospital formularies.
- Insulin:Recombinant human and analog insulins require fermentation-based production with strict two-to-eight-degree Celsius stability protocols throughout distribution. Demand concentrates in Greater Tokyo's specialist diabetes centers where intensive insulin therapy protocols dominate Type 1 diabetes management, with METI's supply chain resilience mandate mandating 90-day buffer stocks at regional depots.
- GLP-1 Agonists:These glucagon-like peptide-1 receptor agonists modulate incretin pathways through subcutaneous delivery of peptide-based formulations. Osaka-Kansai production corridors are expanding fermentation capacity for these agents as hospital committees prioritize cardiometabolic risk reduction beyond glycemic control, though cold-chain infrastructure concentration in Honshu creates geographic vulnerability.
- DPP-4 Inhibitors:Oral gliptins face severe pricing compression under biennial NHI revisions with generic substitution rates exceeding 80 percent.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 inhibitors command outpatient preference through oral convenience and heart failure prevention protocols.
Insulin sits at the top of the volume ranking, with GLP-1 agonists climbing the fastest.
End User:
Care setting determines reimbursement pathway complexity and cold-chain handling requirements for temperature-sensitive biologics.
- Hospitals:Tertiary care centers in the Greater Tokyo metropolitan area anchor demand for injectable therapies, with specialist diabetes centers driving prescribing patterns for premium biologics under protected reimbursement tiers.
- Clinics:Community-based integrated care reforms are expanding clinic authority for injectable therapy initiation, though cold-chain infrastructure gaps in rural prefectures limit biologic penetration.
- Home Care:Self-administered GLP-1 agonists and insulin are gaining reimbursement eligibility outside institutional settings, opening direct-to-patient distribution models.
- Retail Pharmacies:Oral agent dispensing dominates this channel, with SGLT2 inhibitors capturing share through outpatient convenience positioning.
Hospitals retain the dominant volume position, while home care is expanding most quickly under reimbursement reforms.
Application:
Disease severity and complication risk profile shape therapy intensity and monitoring technology bundling decisions.
- Type 1 Diabetes:Absolute insulin deficiency mandates lifelong exogenous replacement, with closed-loop artificial pancreas systems displacing conventional basal-bolus regimens at St. Luke's International Hospital and Juntendo University Hospital.
- Type 2 Diabetes:Progressive beta-cell dysfunction drives stepwise escalation from oral agents to injectable therapies, with SGLT2 inhibitors and GLP-1 agonists gaining priority in cardiorenal protection protocols.
- Gestational Diabetes:Pregnancy-specific glycemic targets favor insulin over oral agents due to placental transfer safety profiles.
- Prediabetes:Lifestyle intervention dominance limits pharmaceutical penetration in this category.
Type 2 diabetes commands the largest patient population, with Type 1 diabetes showing the steepest technology integration trajectory.
Distribution Channel:
Cold-chain integrity requirements and procurement unbundling trends are reshaping channel economics for biologic therapies.
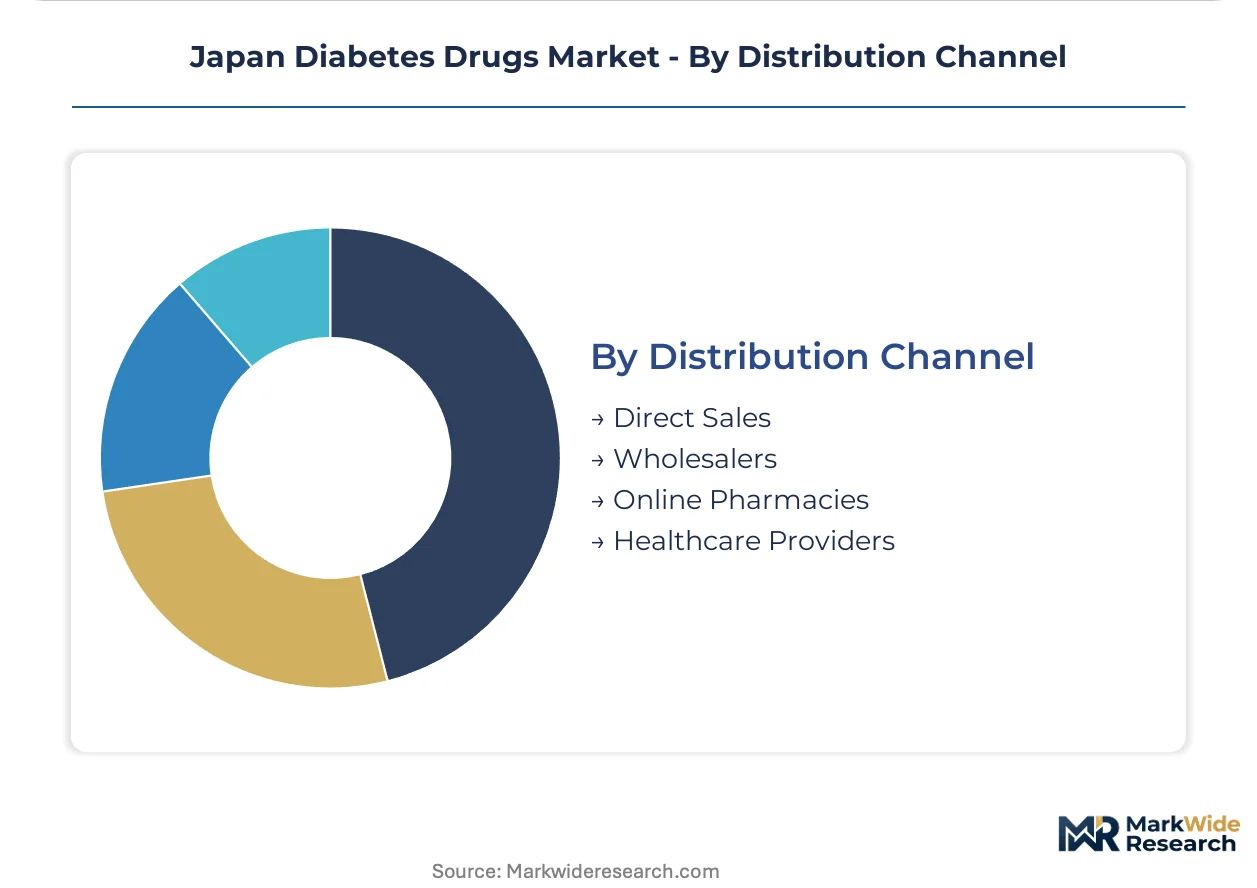
- Direct Sales:Manufacturer-to-hospital contracts for insulin and GLP-1 agonists bypass wholesaler markups, with specialized refrigerated logistics networks extending from Copenhagen manufacturing to Honshu regional depots.
- Wholesalers:Pharmaceutical distributors must maintain METI-mandated 90-day inventory minimums for critical biologics, elevating working capital requirements and driving depot consolidation in Kanto and Kansai regions.
- Online Pharmacies:Regulatory constraints limit biologic delivery through this channel due to temperature control verification challenges.
- Healthcare Providers:Integrated delivery networks are consolidating procurement authority, with unbundled pharmaceutical tenders separating drug from device purchasing.
Wholesalers handle the greatest transaction volume, though direct sales are gaining share fastest as hospital committees centralize procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with streamlined biologics approval pathways and subsidized fermentation capacity. Cost-of-compliance gaps between established and emerging manufacturing clusters are accelerating facility relocation decisions for temperature-sensitive diabetes therapies.
Kanto/Tokyo
Specialist diabetes centers at St. Luke's International Hospital and Juntendo University Hospital drive prescribing intensity for GLP-1 agonists and closed-loop insulin systems. METI's supply chain resilience mandate requires 90-day buffer stocks at regional depots across this corridor. Cold-chain operators are consolidating Kanto depot networks to achieve economies of scale against mandated carrying costs.
Kansai/Osaka
Domestic pharmaceutical manufacturing pivots toward biologic drug substance capacity in this production corridor. METI subsidies for continuous bioprocessing equipment upgrades expand fermentation capacity for protein-based diabetes treatments. Takeda Pharmaceutical Company Limited anchors in-house fermentation and formulation capabilities at legacy Osaka facilities.
Kyushu
Underpenetrated diabetes specialist density in Fukuoka and Saga prefectures offers whitespace for GLP-1 agonist detailing. Hospital networks are consolidating regional referral pathways that channel patients toward tertiary centers in Fukuoka City. Cold-chain infrastructure gaps in rural prefectures limit biologic penetration outside metropolitan clusters.
Chubu/Nagoya
Community-based integrated care reforms are expanding clinic authority for injectable therapy initiation across Aichi and Gifu prefectures. PMDA's Sakigake fast-track designation attracts digital therapeutics developers to this manufacturing hub. Regional pharmacy committees are unbundling diabetes drug procurement from device procurement.
Hokkaido
Geographic isolation creates supply vulnerability for insulin and GLP-1 agonist distribution dependent on Honshu-centered cold-chain networks. Sapporo medical centers maintain higher safety stock levels than national averages. METI-mandated buffer stock requirements elevate working capital burdens for wholesalers serving this northern island.
Japan Diabetes Drugs Market Competitive Landscape
Japanese producers anchor one tier through domestic fermentation capacity and PMDA regulatory expertise; European and North American multinationals hold another through specialized cold-chain distribution networks. The market exhibits tiered concentration with originator biologics commanding protected reimbursement bands and follow-on entrants facing substitution uncertainty. Three archetypes dominate: integrated domestic pharmaceutical conglomerates, multinational biologics specialists, and partnership-dependent innovators leveraging contract manufacturing. Competitive moves center on capacity expansion in Osaka-Kansai corridors and strategic co-development arrangements with domestic regulatory navigators.
Among Japan-based pharmaceutical conglomerates, Takeda Pharmaceutical Company Limited and Daiichi Sankyo Company occupy positions anchored by legacy manufacturing infrastructure and in-house bioprocessing capabilities. European biologics specialists Novo Nordisk A/S and Sanofi exemplify the multinational cold-chain archetype, extending specialized refrigerated logistics from continental manufacturing to regional depots across Honshu. These three companies represent distinct competitive postures: domestic vertical integration, multinational distribution scale, and hybrid partnership models.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Boehringer Ingelheim |
| Merck & Co. |
| Daiichi Sankyo Company |
| Astellas Pharma Inc. |
| Others |
Supply & Pricing Matrix
Continuous bioprocessing equipment upgrades across Osaka-Kansai fermentation corridors are simultaneously compressing unit production costs for GLP-1 agonists and concentrating active pharmaceutical ingredient supply within domestic manufacturing zones. This technological transition reshapes procurement economics as hospital formularies weigh imported versus domestically sourced biologics under METI's supply chain resilience mandates.
Pricing Analysis
Wholesaler markups on insulin and GLP-1 agonists reflect cold-chain handling premiums and METI-mandated 90-day buffer stock carrying costs. Three-tier pricing structure across originator biologics, follow-on biologics, and oral generics tracks manufacturing complexity and interchangeability uncertainty under evolving PMDA guidelines. Pricing pressure stems from biennial NHI price revisions systematically eroding DPP-4 inhibitor margins as generic substitution exceeds thresholds. Community clinics exhibit highest price sensitivity due to reimbursement compression, while tertiary centers in Greater Tokyo maintain formulary preference for premium biologics with protected reimbursement bands.
Supply Chain Analysis
Direct-to-hospital channels handle volume demand for temperature-sensitive biologics, bypassing wholesaler markups through manufacturer-negotiated contracts with specialist diabetes centers. Active pharmaceutical ingredient supply draws from Denmark, Japan, and Switzerland for fermentation-based insulin and peptide formulations. Cold-chain logistics rest on specialized refrigerated networks concentrated in Honshu regional depots, with single-source vulnerability from Kyushu or Hokkaido manufacturing shortfalls. Distribution runs through consolidated Kanto and Kansai depot networks achieving economies of scale against mandated inventory minimums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's diabetes drugs market functions as a geographic-arbitrage play where domestic fermentation capacity expansion in Osaka-Kansai corridors offers cost advantages against European import dependency, while PMDA regulatory expertise creates entry barriers for foreign contract manufacturers lacking local quality management system familiarity.
For Market Incumbents: Cement formulary positioning at St. Luke's International Hospital and Juntendo University Hospital through closed-loop artificial pancreas system bundling with insulin and GLP-1 agonist supply agreements. Expand in-house fermentation capacity at legacy Osaka facilities to capture METI subsidy flows and reduce import dependency exposure. Prioritize biosimilar interchangeability defense through real-world evidence generation supporting originator biologic prescribing continuity. For New Entrants and Emerging Players: Regional hospital networks in Fukuoka and Saga prefectures offer whitespace access as referral pathway consolidation channels patients toward tertiary centers with underpenetrated specialist density. Target community-based integrated care clinics gaining injectable therapy initiation authority under reimbursement reforms. Pursue co-development partnerships with domestic contract manufacturers leveraging PMDA regulatory navigation expertise to compress product registration timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic pharmaceutical conglomerates with stranded DPP-4 inhibitor portfolios facing manufacturing line repurposing decisions. Long-term viability hinges on biologic diversification success and digital therapeutics integration under Sakigake fast-track pathways. Acquisition targets include contract manufacturing organizations with established PMDA quality management system audit histories. Monitor PMDA biosimilar interchangeability guideline finalization as inflection indicator for originator biologic substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Capacity Expansion | METI subsidies accelerate domestic fermentation scale-up, reducing API import dependency for protein-based therapies. |
| Closed-Loop System Bundling | Artificial pancreas integration with insulin supply agreements locks in formulary placement at Tokyo tertiary centers. |
| Sakigake Digital Therapeutics Pathway | Software-as-medical-device fast-track enables glucose monitoring algorithm reimbursement within care bundles. |
| Regional Depot Consolidation | Cold-chain operators achieve economies of scale against METI-mandated 90-day buffer stock carrying costs. |
| Biosimilar Real-World Evidence Generation | Originator manufacturers defend interchangeability exclusion through clinical outcome differentiation studies. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors grounded qualitative findings in operational reality. Secondary validation drew from PMDA approval databases, NHI reimbursement price listings, METI industrial policy filings, and clinical trial registries. Bottom-up prescription volume modeling and top-down market size triangulation cross-verified segment-level estimates across the analysis window.
Output projections reflect patient population epidemiology, therapy escalation patterns, and reimbursement tier evolution across product type, end user, application, and distribution channel dimensions. CAGRs were derived from regression analysis of historical prescription trends against demographic and regulatory drivers. Forecast inputs incorporated specialist center prescribing intensity, generic substitution velocity, and cold-chain infrastructure expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA biosimilar interchangeability finalization, METI subsidy program continuity, and NHI price revision mechanics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Japan Pharmaceutical 3PL Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market