
 IoT Medical Devices Market | 2026-2036
IoT Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Medical Devices Market Intelligence
The remote patient monitoring application is expanding its share of the market, driven by the management of chronic diseases like diabetes and hypertension. Medtronic leverages its portfolio of implantable and wearable devices to capture this shift. Koninklijke Philips N.V. specializes in integrated solutions that connect hospital and home care environments. Siemens Healthineers AG competes through its strength in diagnostic imaging and digital health platforms.
IoT medical devices are physical instruments embedded with sensors and connectivity that transmit health data over a network without human intervention. Their primary purpose is to enable continuous monitoring, real-time alerts, and data-driven clinical decision-making for improved patient outcomes. Wearable devices, including smartwatches and biosensors, represent the fastest-growing product type category. Bluetooth and Wi-Fi technologies dominate connectivity protocols due to their ubiquity in consumer electronics and home networks.
The U.S. FDA's cybersecurity guidance and premarket submission requirements set a high bar for device security and validation. In Europe, the EMA and MDR framework govern data privacy and clinical evidence standards for connected medical products. Navigating the patchwork of national data localization laws and interoperability standards remains the central challenge for vendors seeking scale.
Market Dynamics
The fundamental shift of healthcare delivery from centralized hospital settings to distributed home and ambulatory environments is the central force shaping the market. This decentralization is driven by technological enablement and policy incentives for remote patient care, altering device design and data management requirements.
Growth Catalysts
- Reimbursement Policies:Favorable reimbursement codes for remote patient monitoring (RPM) services, established by bodies like the Centers for Medicare & Medicaid Services (CMS) in the United States, provide direct financial incentives for provider adoption.
- Chronic Disease Prevalence:The rising global incidence of chronic conditions such as COPD and heart failure necessitates continuous monitoring solutions, creating a persistent demand pull from both patients and public health systems.
- Connectivity Advancements:The proliferation of low-power, wide-area networks (LPWAN) and 5G technology expands the feasibility of reliable, real-time data transmission from medical devices in diverse settings, including rural areas.
Market Restraints
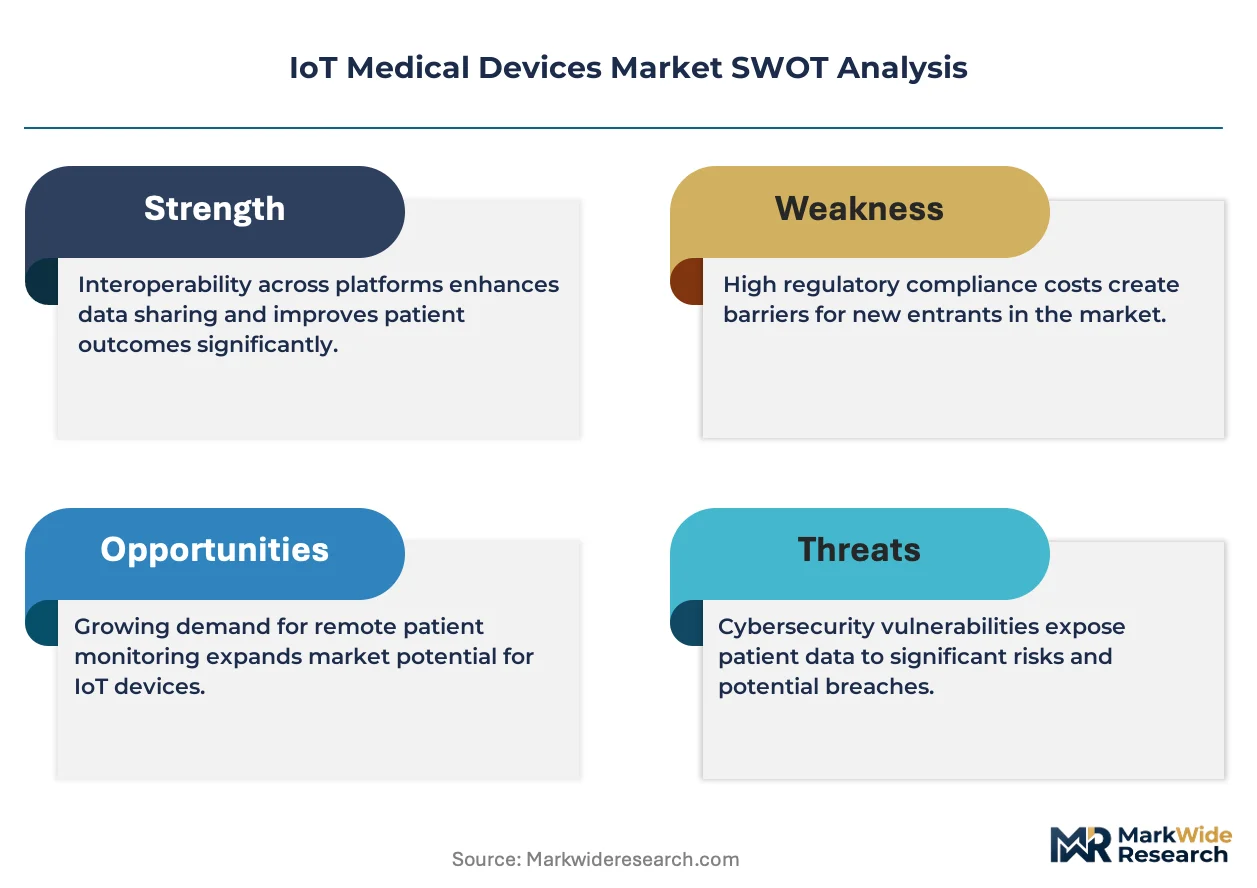
- Data Interoperability:A lack of universal communication standards between different device manufacturers and electronic health record (EHR) systems creates significant integration barriers, limiting the scalability of connected care ecosystems.
- Cybersecurity Vulnerabilities:Connected medical devices present an expanded attack surface for data breaches, with the high cost of securing endpoints to meet HIPAA and GDPR standards acting as a significant deterrent.
- High Implementation Costs:The substantial initial investment required for deploying integrated IoT infrastructure, including hardware, software platforms, and staff training, remains a primary barrier for smaller clinics and health systems in resource-limited regions.
Strategic Opportunities
- Predictive Analytics:The convergence of IoT sensor data with artificial intelligence and machine learning algorithms offers the opportunity to develop predictive models for disease progression and acute event forecasting, enabling proactive interventions.
- Emerging Economies:Markets such as Brazil and India present significant growth potential as their healthcare systems increasingly leapfrog traditional infrastructure in favor of digital-first, mobile-enabled health solutions to expand access.
- Software as a Medical Device (SaMD):Regulatory pathways for SaMD, such as those guided by the IMDRF framework, create opportunities for vendors to develop and monetize pure software solutions that analyze data from third-party hardware.
Industry Challenges
- Clinical Workflow Integration:A primary operational challenge is embedding IoT-generated data into clinical workflows without causing alert fatigue or increasing the administrative burden on physicians and nurses.
- Data Management Infrastructure:Providers face the challenge of building and maintaining robust IT infrastructure capable of ingesting, storing, and analyzing the massive data volumes generated by a fleet of continuous monitoring devices.
- Specialized Talent Scarcity:A persistent shortage of professionals with combined expertise in medical device engineering, cloud computing, and healthcare data privacy hinders product development and secure deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Medical Devices Market |
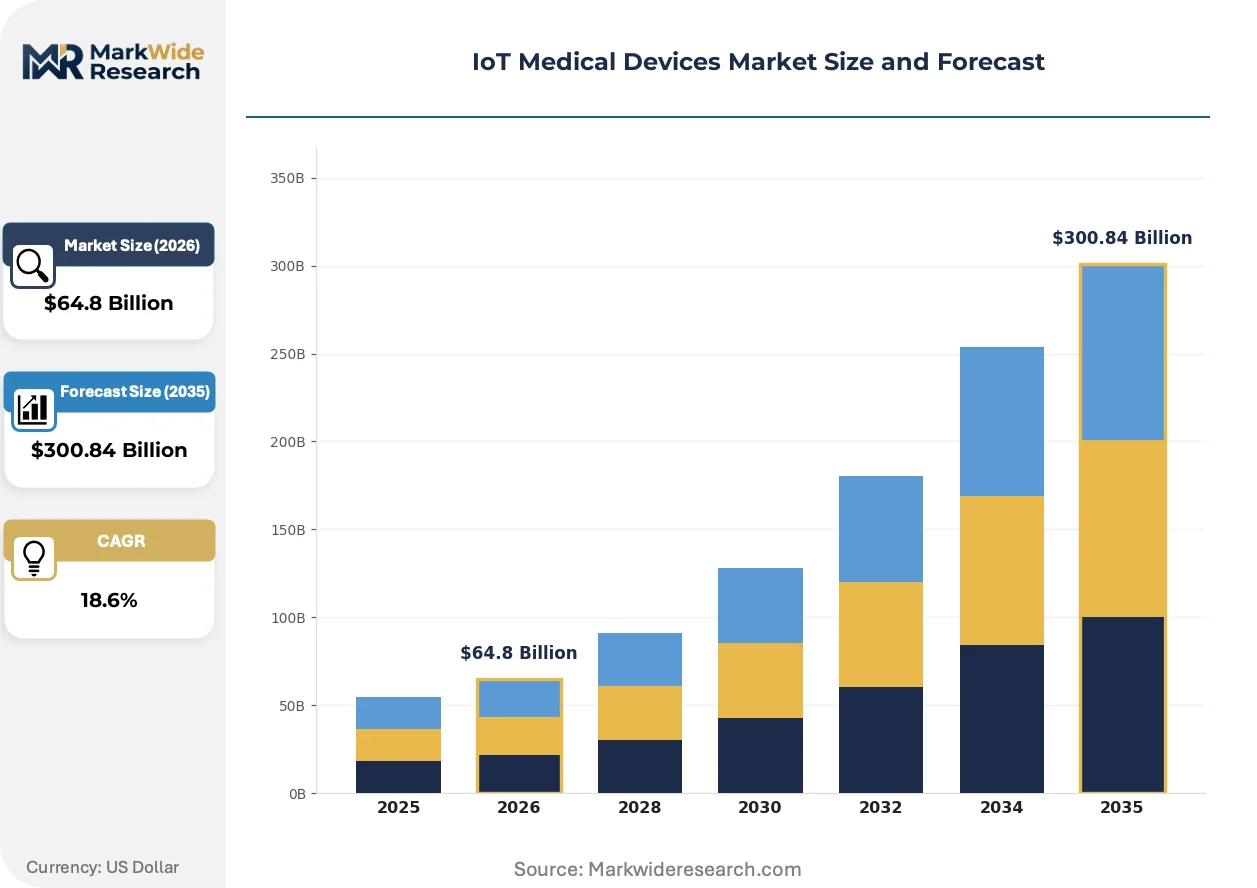
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $300.84 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring Systems, Implantable Devices, Diagnostic Equipment, Therapeutic Devices Technology: Bluetooth, Zigbee, Wi-Fi, Near Field Communication, LoRaWAN Application: Chronic Disease Management, Remote Patient Monitoring, Fitness & Wellness, Elder Care, Hospital Automation End User: Hospitals, Clinics, Home Healthcare Providers, Research Institutes, Telehealth Services |
| Companies Covered | Medtronic, GE Healthcare, Koninklijke Philips N.V., Abbott, Boston Scientific Corporation, OMRON Corporation, Johnson & Johnson, Siemens Healthineers AG, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Medical Devices Market Strategic Shifts & Innovations
The market is being reshaped by the fusion of consumer-grade electronics design with clinical-grade sensor accuracy. This trend is lowering barriers to adoption while simultaneously escalating expectations for device usability, connectivity, and data intelligence, pushing vendors to compete on software and ecosystem integration.
Edge computing, which embeds processing capabilities directly within the medical device, is a key innovation. Medical device manufacturers and hospital systems are adopting this technology for applications requiring immediate analysis, such as real-time arrhythmia detection in cardiac monitors or fall detection sensors for elderly patients. This architecture is decentralizing data analysis, moving it from remote cloud servers to the point of care and reducing network dependency.
Regulatory frameworks are evolving to address the unique aspects of connected devices. The European Union's Medical Device Regulation (MDR) imposes stringent requirements for clinical evidence and post-market surveillance, including specific rules for software and cybersecurity. This directly affects device developers targeting the EU, forcing more rigorous validation and lifecycle management processes to achieve and maintain CE marking for their connected products.
A notable behavioral shift is occurring in how healthcare providers acquire these technologies. Instead of purchasing standalone monitors, large health systems are increasingly entering enterprise-level partnerships for integrated platforms that bundle hardware, connectivity, and data analytics. This disrupts traditional departmental purchasing and favors vendors who can provide a comprehensive remote care solution. This trend is most advanced within integrated delivery networks in the United States and the UK's NHS Trusts.
IoT Medical Devices Market Segmentation
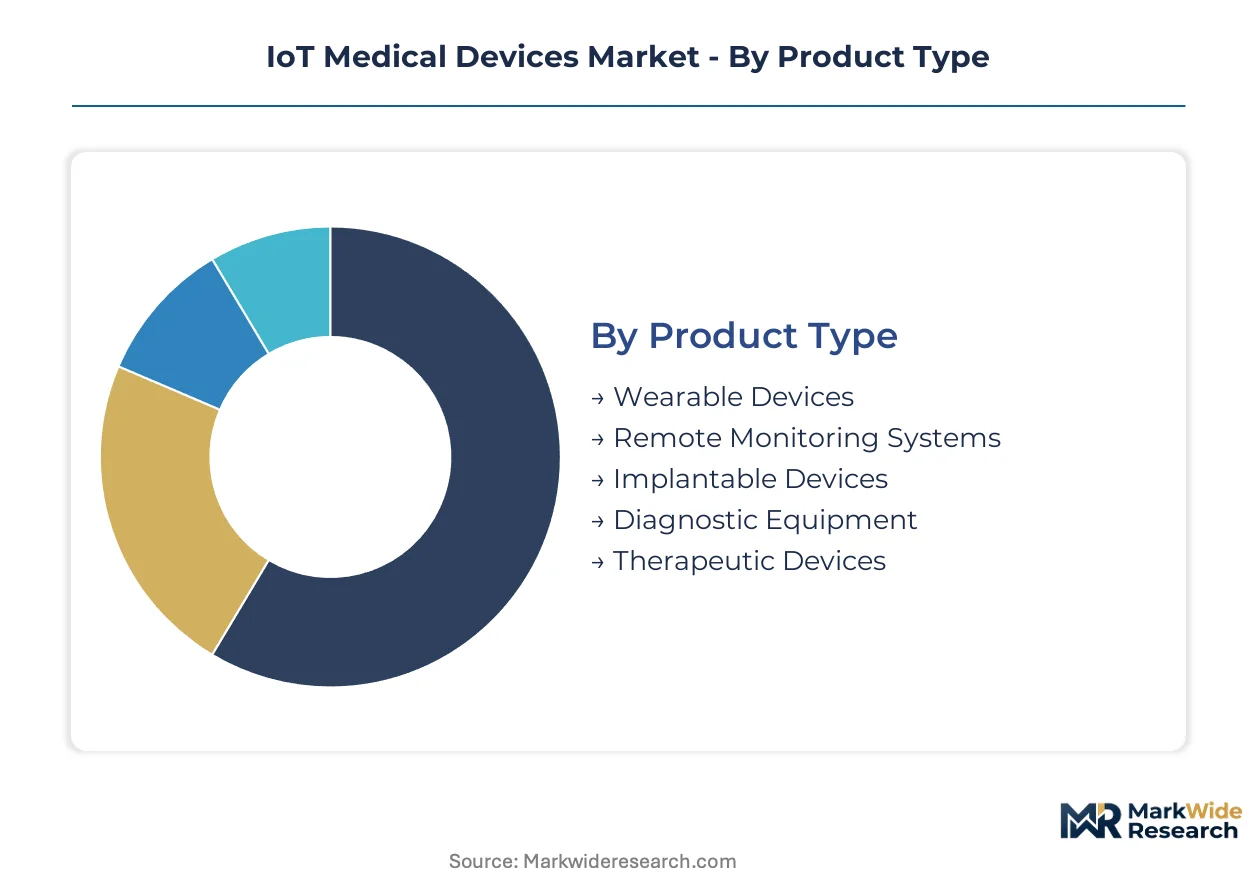
Understanding market segmentation clarifies how diverse product types, technologies, applications, and end-user groups shape demand for IoT medical devices. This structured analysis identifies key areas of investment and innovation, reflecting distinct buyer preferences and operational requirements across the healthcare ecosystem.
Product Type:
Device functionality and form factor heavily influence procurement decisions for IoT medical products.
- Wearable Devices:These include smartwatches, fitness trackers, and biosensors designed for continuous, non-invasive health monitoring. Demand concentrates in consumer health and preventative care, driven by a desire for personal health management and early detection.
- Remote Monitoring Systems:These integrated platforms collect and transmit patient health data from various sensors to healthcare providers. Their adoption is accelerating in chronic disease management, enabling continuous oversight of conditions like diabetes and hypertension.
- Implantable Devices:These are surgically placed devices, such as pacemakers or continuous glucose monitors, that provide long-term monitoring or therapeutic functions.
- Diagnostic Equipment:This segment includes connected imaging systems and laboratory devices that transmit data for remote analysis and clinical decision-making.
- Therapeutic Devices:These devices deliver treatment, such as smart insulin pumps or connected nebulizers, with remote management capabilities.
Wearable Devices leads on momentum; Remote Monitoring Systems leads on scale.
Technology:
Connectivity requirements dictate the choice of underlying communication protocols for IoT medical devices.
- Bluetooth:This short-range wireless technology enables secure, low-power data exchange between devices over personal area networks. Its ubiquity in consumer electronics makes it suitable for personal health devices and patient-worn sensors.
- Wi-Fi:This technology provides high-bandwidth data transmission over local area networks, facilitating robust connectivity within home and clinical environments. Wi-Fi supports the transfer of large data sets from diagnostic equipment and integrated systems.
- Zigbee:A low-power, low-data-rate wireless technology often used in mesh networks for home automation and smart health applications.
- Near Field Communication:This short-range, high-frequency wireless technology enables secure data exchange between devices in close proximity, ideal for identification and data transfer in clinical settings.
- LoRaWAN:A low-power, wide-area networking protocol designed for long-range, low-data-rate communication, suitable for remote monitoring in diverse geographical areas.
Wi-Fi technology facilitates broad device interoperability; LoRaWAN supports long-range data transmission efficiently.
Application:
Clinical need and patient care models shape the specific applications of IoT medical devices.
- Chronic Disease Management:This application focuses on continuous monitoring and data collection for conditions such as diabetes, heart failure, and COPD. Providers utilize these insights for proactive intervention and personalized care plans.
- Remote Patient Monitoring:This involves using IoT devices to collect health data from individuals outside traditional clinical settings, transmitting it to healthcare professionals. Policy incentives for remote patient care drive its expansion across various conditions.
- Fitness & Wellness:Devices in this category track physical activity, sleep patterns, and general health metrics for personal well-being and preventative health.
- Elder Care:This application leverages IoT devices for fall detection, medication reminders, and continuous monitoring to enhance safety and independence for seniors.
- Hospital Automation:IoT solutions optimize hospital operations, including asset tracking, environmental monitoring, and smart bed management, improving efficiency and resource allocation.
Remote Patient Monitoring is expanding its market share; Chronic Disease Management drives persistent demand.
End User:
The care delivery environment determines the specific requirements and deployment models for IoT medical devices.
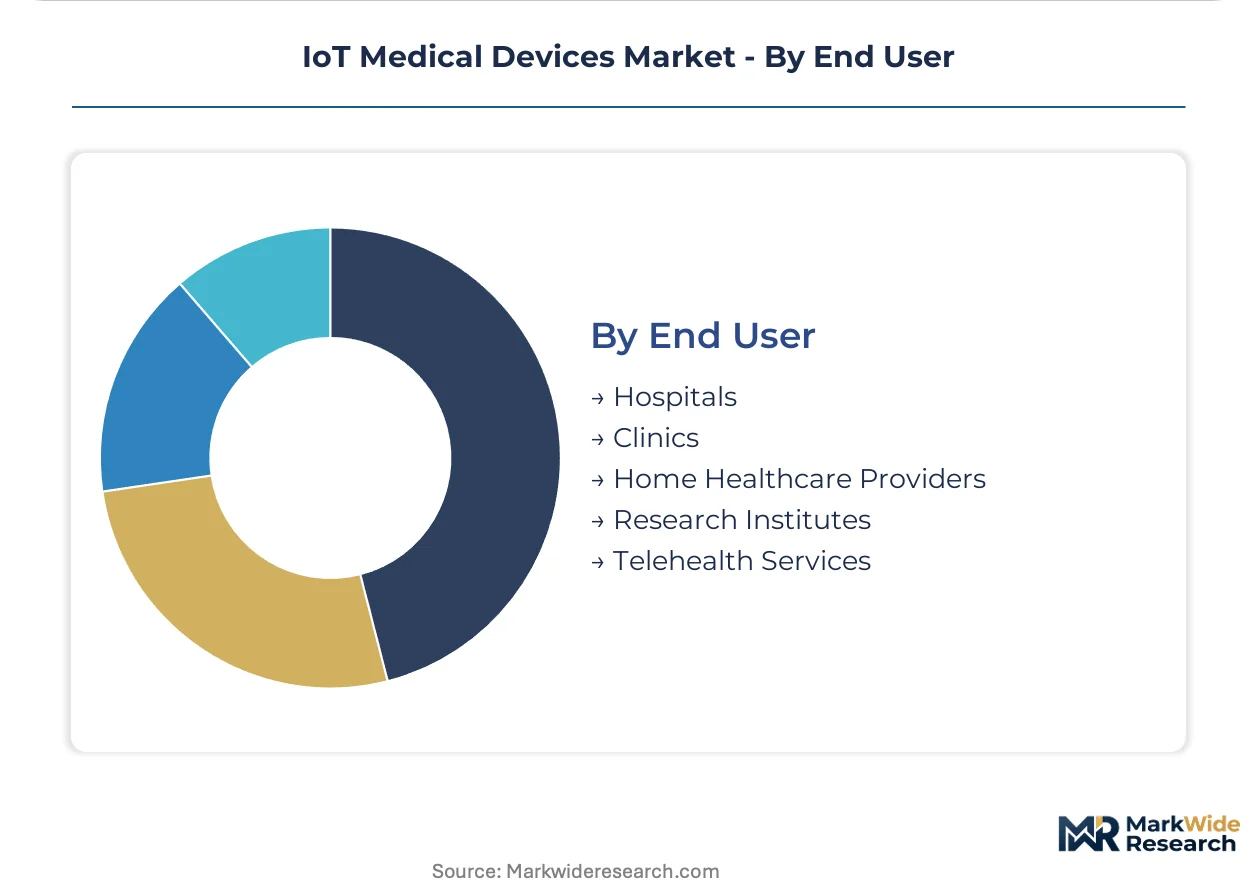
- Hospitals:These institutions deploy IoT devices for advanced diagnostic imaging, patient monitoring in critical care, and integrated digital health platforms. Large health systems increasingly seek enterprise-level partnerships for comprehensive solutions.
- Home Healthcare Providers:This segment focuses on delivering medical care and monitoring services directly to patients' residences, utilizing IoT devices for remote oversight and support. The decentralization of healthcare delivery fuels investment in this area.
- Clinics:Smaller outpatient facilities adopt IoT devices for localized patient monitoring, diagnostics, and efficient data management.
- Research Institutes:These organizations use IoT medical devices for clinical trials, data collection, and developing new medical technologies and therapies.
- Telehealth Services:Providers integrate IoT devices to enhance virtual consultations, enabling real-time data sharing and remote diagnostics for improved patient engagement.
Home Healthcare Providers represent a strategic shift in care delivery; Hospitals continue significant investment in digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's vibrant medical technology cluster drives significant innovation in IoT medical devices. This concentration of research institutions and startups fosters advanced product development and market adoption. Favorable policy incentives and a high prevalence of chronic diseases across North America further stimulate demand for connected health solutions.
United States
Demand for remote patient monitoring solutions is high, fueled by chronic conditions. The Centers for Medicare & Medicaid Services (CMS) provides favorable reimbursement codes, incentivizing provider adoption. California's tech ecosystem, particularly in Silicon Valley, actively develops connected health platforms and wearable devices.
Germany
European healthcare systems increasingly integrate IoT devices for efficient patient management. The European Medical Device Regulation (MDR) sets stringent standards for device safety and clinical evidence. The Munich region, a hub for MedTech companies, focuses on precision diagnostics and digital health solutions.
Japan
An aging population creates strong demand for elder care and continuous health monitoring devices. Regulatory bodies like PMDA guide market entry for innovative medical technologies. Tokyo's advanced technological infrastructure supports deployment of smart hospitals and connected home care systems.
India
Expanding healthcare access and a growing middle class increase the need for affordable digital health solutions. The country's national pharmaceutical regulator (CDSCO) shapes the regulatory landscape for medical devices. Bangalore, a major tech hub, invests significantly in telehealth platforms and IoT-enabled diagnostics.
China
Government initiatives to modernize healthcare infrastructure and address chronic disease drive IoT medical device adoption. The National Medical Products Administration (NMPA) oversees product approvals and quality standards. The Yangtze River Delta region, including Shanghai, is a key center for medical device manufacturing and digital health innovation.
IoT Medical Devices Market Key Industry Players
Strategic partnerships and technology licensing dominate the current landscape, as companies seek to integrate diverse IoT solutions and expand their ecosystem reach. The market exhibits a tiered structure, with established medical device manufacturers vying for market share alongside specialized digital health startups. Large incumbents focus on comprehensive platform offerings that span hospital and home care, while agile innovators target niche applications. Portfolio diversification across device types and geographic expansion into emerging economies are common competitive moves.
Among the established medical technology providers, Medtronic exemplifies leadership in implantable and wearable devices, particularly for chronic disease management, leveraging a broad product portfolio. Koninklijke Philips N.V. represents a comprehensive solutions approach, connecting hospital and home care environments through integrated platforms that emphasize seamless data flow. Siemens Healthineers AG, with its German heritage, occupies a strong position in diagnostic imaging and digital health platforms, leveraging its extensive installed base within clinical settings to drive data-driven decision-making. These entities anchor the premium tier, driving innovation in both hardware and software.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Abbott |
| Boston Scientific Corporation |
| OMRON Corporation |
| Johnson & Johnson |
| Siemens Healthineers AG |
| Baxter International |
| Others |
Cost & Logistics Intelligence
Semiconductor component pricing directly influences the final cost of IoT medical devices, cascading into various pricing tiers for end-users. This market's supply chain structure significantly impacts product affordability and accessibility.
Pricing Analysis
Rising input costs for specialized sensors and microcontrollers are directly passed through to device manufacturers, impacting final product pricing. The market predominantly uses a hybrid pricing model, combining per-unit hardware sales with subscription-based fees for data analytics platforms and remote monitoring services. Pricing stratifies across premium, standard, and economy tiers, driven by FDA/CE marking certification levels and comprehensive after-sales support. Pricing softness reflects increasing competition from agile startups in the wearable segment. Smaller clinics and resource-limited regions exhibit the highest price sensitivity, while large hospital systems prioritize integrated solutions and long-term value.
Supply Chain Analysis
Regional distribution centers facilitate the efficient delivery of IoT medical devices, often employing hub-and-spoke patterns for last-mile delivery to healthcare providers. Manufacturing and assembly primarily concentrate in China, Germany, and the United States. The supply chain relies heavily on microprocessors, specialized biosensors, and medical-grade plastics. A significant structural risk is single-source vulnerability for critical, high-performance components, which can disrupt production. Distribution runs through direct sales channels to large hospital systems and specialized value-added resellers serving home healthcare providers and smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT medical devices market represents a late-cycle quality story, driven by a pronounced demand shift toward clinical-grade accuracy and seamless data integration. Strategic moves must prioritize robust data security and interoperability to capture value.
For Market Incumbents: Anchor existing customer relationships by deepening vertical integration into proprietary software platforms and data analytics services. Acquire specialized AI/ML startups to bolster predictive analytics capabilities, countering disruption from agile digital health startups. Investment in robust cybersecurity certification, aligning with FDA guidance and GDPR, reinforces trust and market access. Consolidate fragmented offerings into comprehensive, enterprise-level solutions for large health systems.
For New Entrants and Emerging Players: Capture underserved niches by developing Software as a Medical Device (SaMD) solutions that integrate with third-party hardware for specific chronic conditions like early-stage cardiovascular monitoring. The home healthcare segment in emerging economies presents the most penetrable market due to rapidly expanding digital infrastructure. A focused go-to-market strategy involves strategic partnerships with local telehealth providers and mobile network operators to ensure widespread access and support. Prioritize user-friendly interfaces and robust data privacy features to build patient trust.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized platform providers demonstrating strong intellectual property in AI/ML for health data analytics. Long-term viability is anchored in the irreversible shift towards preventative care and value-based healthcare models. Target acquisition candidates are mid-sized companies with proven interoperability capabilities and established regulatory compliance frameworks. The signal to watch is increased regulatory clarity for AI/ML algorithms in medical devices, which will unlock further investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Medtronic and Philips are solidifying market presence through integrated platform offerings to large health systems. |
| CE Marking Pathway | Navigating the European Medical Device Regulation (MDR) ensures market access and compliance for connected products. |
| Software Companion Development | Developing SaMD solutions enhances data analysis capabilities for third-party hardware, aligning with IMDRF frameworks. |
| Reimbursement Strategy Expansion | Expanding favorable reimbursement codes for remote patient monitoring (RPM) services incentivizes provider adoption, especially from CMS. |
| Cloud Security Certification | Achieving advanced cloud security certifications addresses critical cybersecurity vulnerabilities and HIPAA/GDPR compliance. |
Research Approach
Direct dialogue with clinicians, biomedical engineers, hospital purchasing committees, and regulatory affairs specialists provided primary insights. This qualitative grounding was rigorously validated against extensive secondary data from FDA filings, EMA submissions, CMS Medicare data, and GPO contracts. A comprehensive bottom-up approach, combined with top-down market sizing, ensured robust data triangulation for accurate analysis.
A bottom-up analytical framework quantified market segments by product type, technology, application, end-user, and regional regulatory compliance across the analysis window. Compound Annual Growth Rates (CAGRs) were derived from historical growth rates and projected future demand drivers. Key forecast inputs included evolving chronic disease prevalence rates and anticipated changes in remote patient monitoring reimbursement policies.
Underlying measurement precision varies by segment; remote monitoring systems and wearable devices carry tighter precision. Forecasts reflect assumptions on regulatory frameworks and technological advancements. Significant cybersecurity breaches or global health policy shifts could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
ADA Substitute Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Patient Warming Devices Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Blood Collection Devices Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Infant Incubator Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market