
 Telehealth Device Market | 2026-2036
Telehealth Device Market Size, Share, and Industry Trends Forecast 2026-2036
Telehealth Device Market Insights
Buyer concentration among hospital networks and integrated delivery systems is hardening as large health systems centralize telehealth procurement under single vendor contracts. Medtronic leverages its cardiac monitoring portfolio to anchor long-term service agreements with major cardiology service lines. Koninklijke Philips N.V. sustains broad category coverage across patient monitoring and telemedicine infrastructure, competing on enterprise-scale deployments. AMD Global Telemedicine Inc. specializes in modular telemedicine kits designed for rural and ambulatory settings, occupying a differentiated niche below the enterprise tier.
Telehealth devices encompass hardware and software systems enabling synchronous and asynchronous clinical interaction, data transmission, and remote physiological monitoring, typically integrating FDA-cleared sensors with encrypted cloud connectivity and clinical workflow integration. Wearable devices and remote monitors lead current revenue pools, while AI Diagnostics within mobile health platforms represents the fastest-expanding margin segment as algorithm-based triage tools gain clinical acceptance. Telemedicine kits remain a fragmented, price-sensitive category where regional distributors control access to smaller provider accounts.
FDA digital health pre-certification and HIPAA security frameworks govern product entry and data handling in the United States, while the EU MDR and GDPR impose parallel conformity and privacy obligations for European market access. These regulatory architectures directly shape R&D allocation, with compliance costs favoring companies that can amortize certification investments across multi-product portfolios. Stakeholders must monitor reimbursement rulemaking at CMS and comparable national payers, as payment policy remains the decisive demand lever irrespective of device sophistication.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins as integrated delivery systems negotiate enterprise-wide telehealth contracts spanning multiple service lines and facilities.
Growth Catalysts
- Medicare Reimbursement Expansion:CMS coverage for remote therapeutic monitoring creates durable payment infrastructure for device manufacturers serving chronic disease management programs in the United States.
- FDA Pre-Certification Pathway:The agency's streamlined digital health review accelerates software-driven diagnostic tool clearances, reducing time-to-market for algorithm-based monitoring platforms.
- Cloud-Edge Convergence:Real-time physiological data processing at the network edge enables continuous cardiac and respiratory monitoring without latency-dependent hospital infrastructure.
Market Restraints
- Semiconductor Supply Concentration:Dependence on East Asian foundries for biometric sensor chips creates vulnerability to geopolitical disruption and allocation constraints.
- HIPAA Compliance Architecture:Encryption and audit requirements for protected health information transmission impose fixed engineering costs that disadvantage smaller device developers.
- Clinical Validation Burden:Algorithm-based diagnostic tools require prospective studies against gold-standard measurements, extending development timelines before commercial deployment.
Strategic Opportunities
- Rural Health Infrastructure:Federally qualified health centers and critical access hospitals in underserved United States regions present untapped demand for modular telemedicine deployment kits.
- AI-Augmented Triage:Machine learning integration with wearable ECG and pulse oximetry enables automated arrhythmia detection, reducing specialist interpretation burden.
- Medicaid Expansion States:Remote patient monitoring coverage under state Medicaid programs creates reimbursement pathways beyond traditional Medicare-eligible populations.
Industry Challenges
- Interoperability Standards Fragmentation:Proprietary data formats from competing platform vendors impede seamless electronic health record integration across multi-vendor hospital environments.
- Cybersecurity Certification Complexity:FDA 510(k) clearance combined with HITRUST certification creates dual-track compliance requirements that extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telehealth Device Market |
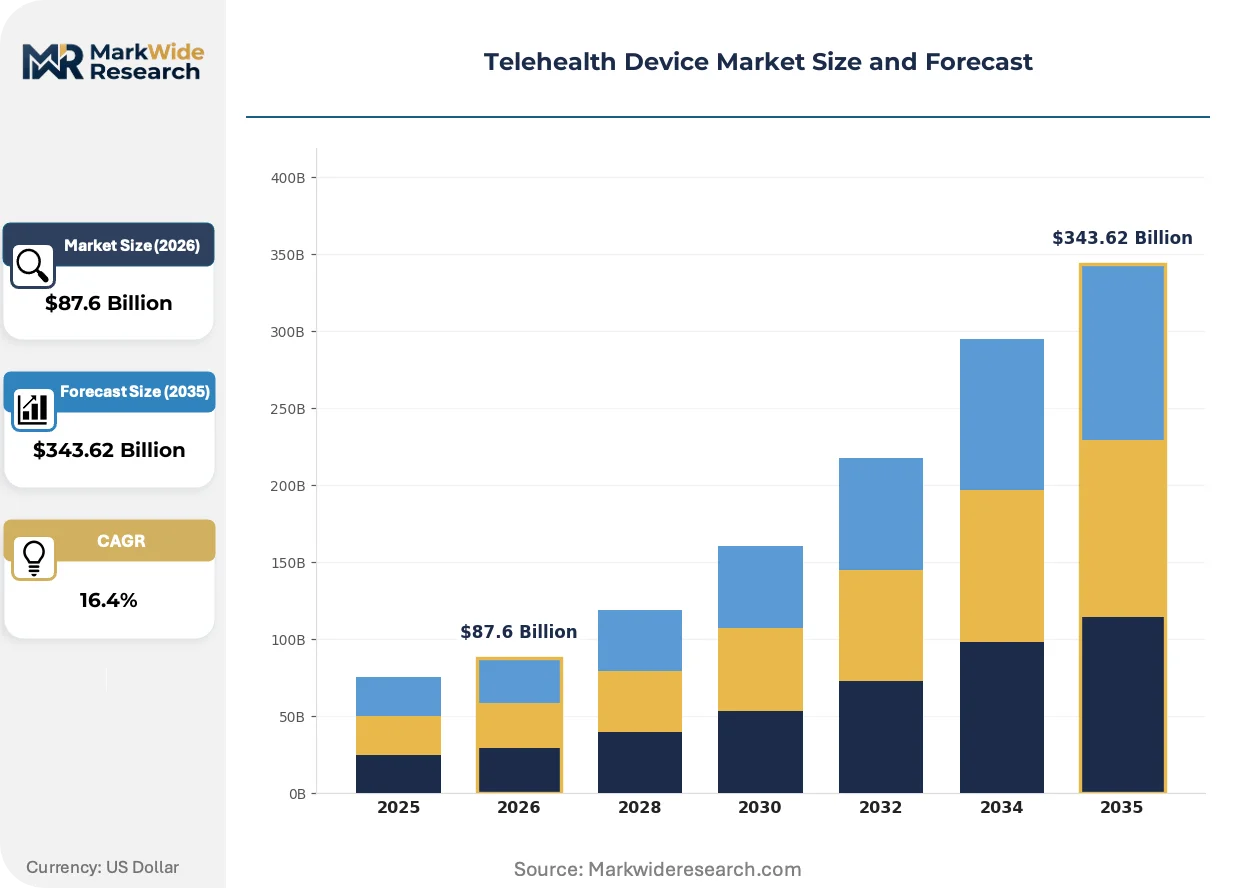
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $343.62 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitors, Mobile Apps, Telemedicine Kits End User: Patients, Healthcare Providers, Emergency Services, Home Care Agencies Technology: Video Conferencing, Mobile Health Platforms, AI Diagnostics, IoT Devices Application: Chronic Disease Management, Remote Consultation, Rehabilitation, Health Monitoring |
| Companies Covered | Medtronic, GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, AMD Global Telemedicine Inc., Aerotel Medical Systems, Honeywell Life Care Solutions, Global Med, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telehealth Device Market Trends and Innovations
Algorithmic diagnostic capabilities embedded in consumer-facing wearables are blurring the boundary between wellness tracking and clinical-grade monitoring, forcing regulatory recalibration and reimbursement redefinition.
Photoplethysmography sensors paired with machine learning inference engines are expanding into continuous blood pressure estimation and atrial fibrillation screening. Cardiology service lines at large health systems are piloting these tools for post-discharge monitoring. The technology is expanding into home-based heart failure management programs that previously required implanted devices.
The European Union Medical Device Regulation imposes stricter clinical evidence requirements for software-as-a-medical-device classifications than predecessor directives. Manufacturers must demonstrate equivalence or conduct prospective studies for algorithm updates. Cardiovascular diagnostic modules face the most stringent notified body scrutiny, with several United States-cleared platforms awaiting European conformity assessment.
Hospital supply chain departments are consolidating telehealth procurement under single-source agreements that bundle hardware, software licensing, and clinical workflow support. Integrated delivery networks are displacing point-of-care purchasing decisions with centralized vendor selection committees. This concentration is most visible in United States metropolitan markets where three-hospital systems control regional referral patterns.
Telehealth Device Market Segmentation
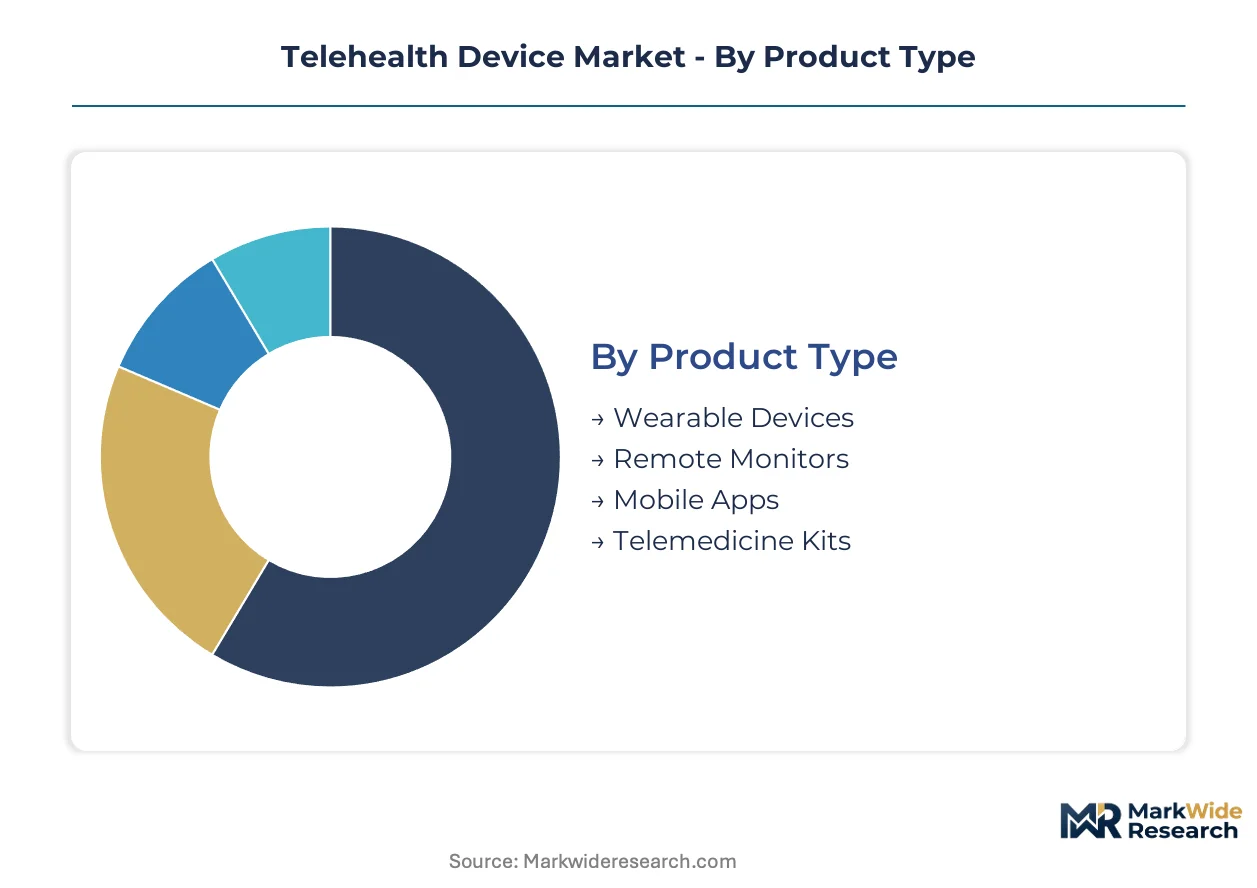
Device manufacturers align R&D roadmaps with reimbursement codes that favor specific form factors over others. Procurement consolidation among hospital systems rewards vendors who span multiple segment categories rather than single-product specialists.
Product Type:
Replacement cycles vary sharply across this category, with wearable devices refreshing every 18-24 months while telemedicine kits persist for 5-7 years in ambulatory deployments.
- Wearable Devices:Continuous physiological sensors embedded in wrist-worn or patch-based form factors transmit encrypted biometric streams to cloud platforms. Cardiology service lines at United States health systems drive procurement of FDA-cleared ECG wearables for post-discharge arrhythmia surveillance.
- Remote Monitors:Stationary bedside units capture vital signs through FDA-cleared sensors and integrate directly with electronic health record workflows. Home care agencies in Medicare Advantage networks represent the dominant demand channel for pulse oximetry and weight scale bundles.
- Mobile Apps:Software platforms enabling asynchronous clinical communication and medication adherence tracking.
- Telemedicine Kits:Modular hardware assemblies combining cameras, digital stethoscopes, and examination peripherals for point-of-care connectivity.
Wearable devices sit at the top of the volume ranking, with AI-augmented remote monitors climbing the fastest.
End User:
Cost tiers separate enterprise procurement from consumer-direct channels, with healthcare providers paying 3-4x per unit compared to patient self-pay segments.
- Healthcare Providers:Hospital systems and physician practices deploy enterprise-grade telehealth infrastructure across cardiology, pulmonology, and primary care service lines. Integrated delivery networks in United States metropolitan markets negotiate multi-facility contracts spanning hardware, software licensing, and clinical workflow support.
- Patients:Direct-to-consumer purchasers acquire wearable devices and mobile health subscriptions without institutional procurement intermediaries. Out-of-pocket spending concentrates on fitness-adjacent wellness trackers with optional clinical-grade feature unlocks.
- Emergency Services:Pre-hospital care teams utilize ruggedized telemedicine kits for field consultation with emergency physicians.
- Home Care Agencies:Medicare-certified organizations supply remote monitoring equipment to chronically ill beneficiaries under remote patient management reimbursement codes.
Healthcare providers command the highest absolute spending, though patient-direct channels are gaining share fastest through retail pharmacy distribution partnerships.
Technology:
Application requirements dictate technology selection, with synchronous clinical encounters demanding video infrastructure while asynchronous monitoring favors IoT sensor networks.
- AI Diagnostics:Machine learning algorithms embedded in mobile platforms or edge devices interpret physiological signals for automated triage and anomaly detection. Cardiology departments at academic medical centers pilot arrhythmia classification tools that reduce specialist interpretation burden.
- Mobile Health Platforms:Cloud-native software architectures enabling patient engagement, medication reminders, and care plan adherence tracking. Federally qualified health centers in rural United States regions deploy these platforms to extend specialist access without physical infrastructure investment.
- Video Conferencing:Real-time audiovisual connectivity for synchronous clinical consultations.
- IoT Devices:Networked sensors with embedded connectivity transmitting continuous biometric data streams.
Video conferencing retains the largest installed base, with AI diagnostics exhibiting the steepest expansion trajectory.
Application:
Margin profiles diverge across use cases, with chronic disease management commanding premium pricing due to recurring reimbursement while remote consultation faces commoditization pressure.
- Chronic Disease Management:Longitudinal monitoring programs for heart failure, diabetes, and COPD utilizing connected devices to reduce acute exacerbations. United States Medicare reimbursement for remote therapeutic monitoring sustains durable payment infrastructure for device manufacturers serving these populations.
- Remote Consultation:Virtual visit platforms replacing in-person primary care and specialty encounters. Health systems deploy these solutions across urgent care and behavioral health service lines where physical examination requirements are minimal.
- Rehabilitation:Telehealth-enabled physical and occupational therapy programs with motion tracking and remote supervision.
- Health Monitoring:Preventive surveillance applications targeting asymptomatic populations with wellness-oriented biometric tracking.
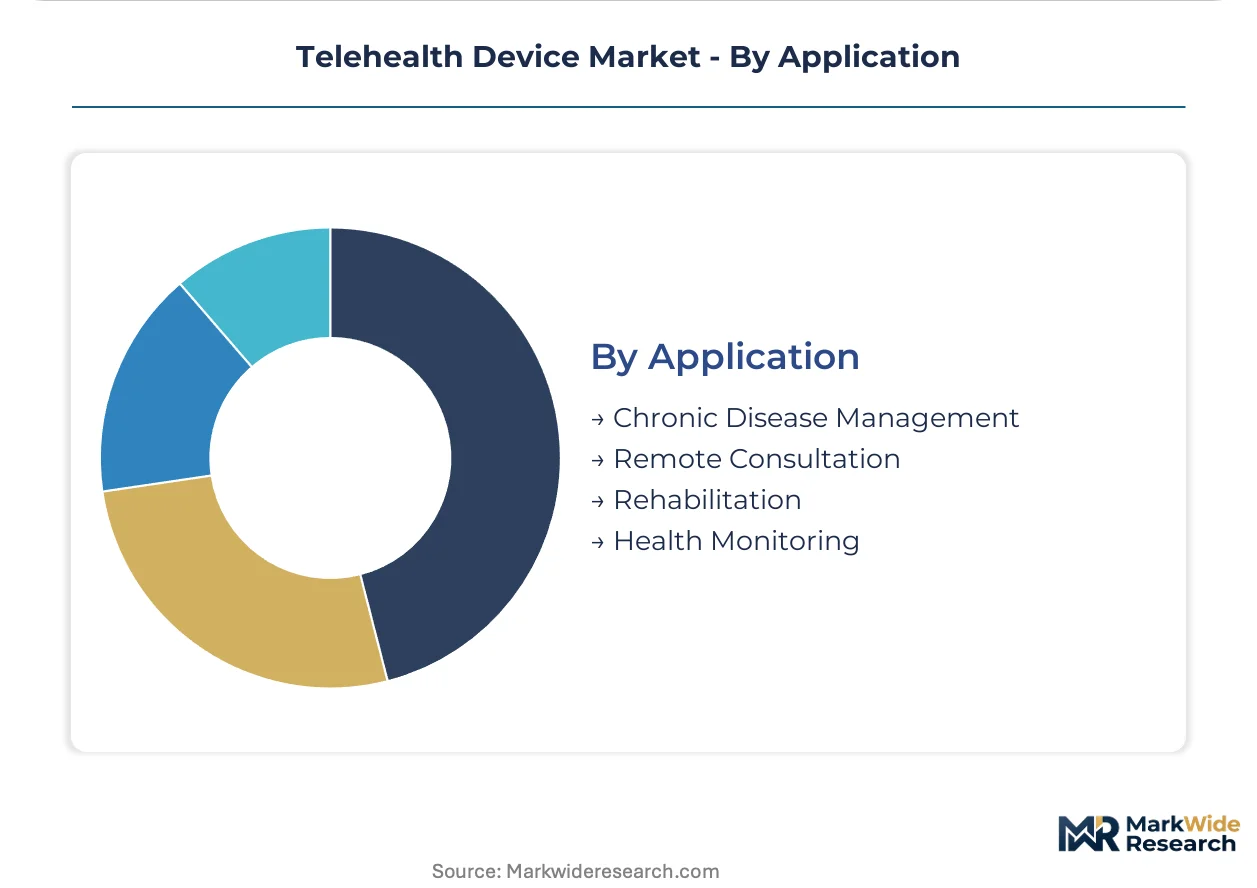
Chronic disease management dominates revenue concentration, with rehabilitation applications expanding most quickly through workers compensation and post-acute care channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands reimbursement-driven demand that outpaces Germany's regulatory-complexity-constrained adoption curve, while Asian markets accelerate through government digital health initiatives.
United States
CMS reimbursement codes for remote therapeutic monitoring sustain procurement volume across integrated delivery networks. FDA digital health pre-certification accelerates software-driven diagnostic clearances, compressing time-to-market for algorithm-based platforms. The Boston-Cambridge corridor anchors development concentration for wearable cardiac monitors targeting post-discharge arrhythmia surveillance.
Germany
Hospital digitization funding under the Hospital Future Act drives enterprise telehealth infrastructure deployment. EU MDR imposes stricter clinical evidence requirements for software-as-a-medical-device than predecessor directives, extending conformity timelines. The Rhine-Ruhr metropolitan region concentrates procurement decision-making for multi-facility health system contracts.
China
NMPA regulatory streamlining for innovative medical devices accelerates domestic telehealth platform commercialization. National digital health infrastructure investment prioritizes remote monitoring for chronic disease management in tier-2 and tier-3 cities. The Yangtze River Delta cluster dominates manufacturing scale for consumer-facing wearable biometric sensors.
Japan
Aging demographic pressure and specialist physician shortages expand reimbursement for home-based telehealth monitoring. PMDA guidance on software medical devices clarifies approval pathways for AI-augmented diagnostic tools. The Kanto region around Tokyo concentrates health system pilot programs for post-acute remote patient management.
United Kingdom
NHS Long Term Plan targets for virtual consultation volume reshape procurement priorities toward integrated telehealth platforms. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR timelines for certain device categories. The Greater Manchester health system exemplifies consolidated vendor selection for multi-hospital telemedicine deployment.
Telehealth Device Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Hospital procurement consolidation favors vendors spanning hardware, software, and clinical workflow support under single-source agreements. Three archetypes dominate: diversified medical technology conglomerates with cardiac monitoring portfolios, enterprise-scale infrastructure providers, and modular kit specialists targeting ambulatory and rural deployment. Competitive moves concentrate on strategic partnerships with health systems and portfolio expansion into adjacent monitoring categories.
Within the diversified conglomerate tier, Medtronic and Koninklijke Philips N.V. occupy positions anchoring long-term service agreements with major cardiology service lines. AMD Global Telemedicine Inc. exemplifies the modular specialist archetype, serving rural and ambulatory settings below the enterprise procurement tier. Siemens Healthineers and GE Healthcare represent European-origin diversified players competing on imaging-integrated telehealth infrastructure. These groupings illustrate how vendor selection increasingly favors multi-product portfolios capable of amortizing compliance investments across reimbursement-code-aligned device categories.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| AMD Global Telemedicine Inc. |
| Aerotel Medical Systems |
| Honeywell Life Care Solutions |
| Global Med |
| Philips Healthcare |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up device specialists have consolidated regional distribution networks across the United States, tightening working capital discipline while extracting pricing power through captive GPO channel access and volume-commitment contracts with integrated delivery networks.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing cluster are reshaping price floors for consumer-facing biometric sensors, pressuring margins on wearable ECG and pulse oximetry modules. Pricing stratifies across FDA-cleared clinical tiers, CE-marked export tiers, and unregulated wellness-oriented economy tiers, with certification level and after-sales service bundling as the primary differentiation drivers. Cost compression in the telemedicine kit category is intensifying because hospital supply chain departments now mandate five-year total cost of ownership guarantees. Home care agencies exhibit the highest price sensitivity due to thin Medicare reimbursement spreads, while academic medical centers prioritize clinical workflow integration over unit economics.
Supply Chain Analysis
Specialized firmware engineers and biomedical sensor calibration technicians remain concentrated in Taiwan, South Korea, and the coastal United States metro corridors, constraining expansion velocity for algorithm-driven diagnostic platforms. Component sourcing draws from Taiwanese foundries for biometric sensor ASICs, Japanese suppliers for high-precision optical modules, and domestic United States fabricators for HIPAA-compliant edge computing hardware. Single-source vulnerability concentrates in East Asian semiconductor fabrication, where geopolitical disruption risks cascade through FDA-cleared device production schedules. Distribution runs through group purchasing organizations and health system vendor selection committees rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
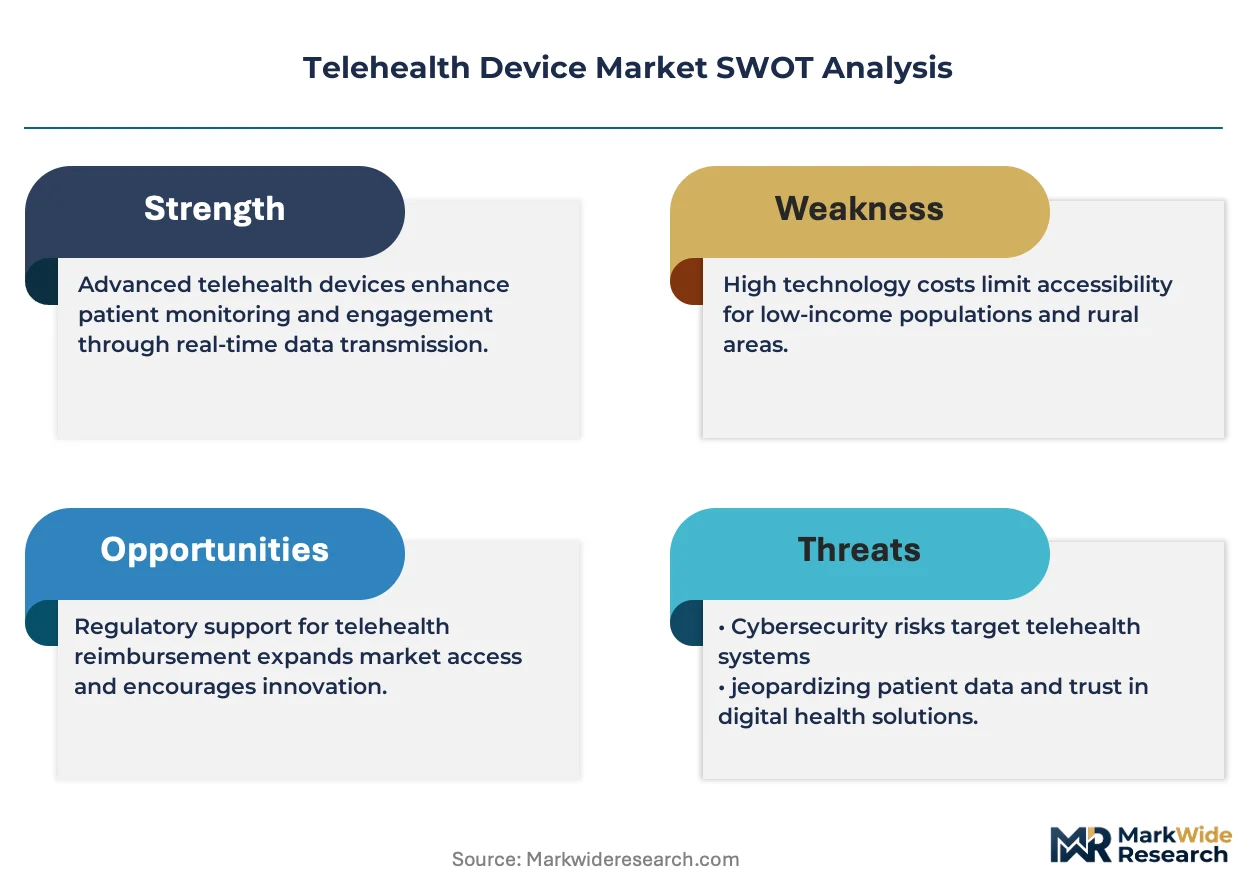
This market functions as a regulatory compounder where CMS reimbursement rulemaking for remote therapeutic monitoring creates durable demand infrastructure irrespective of macroeconomic cycles.
For Market Incumbents: Acquire FDA 510(k) clearance portfolios and associated clinical validation datasets to fortify against software-as-a-medical-device entrants lacking prospective study archives. Build backward integration into biometric sensor chip design to reduce allocation vulnerability from East Asian foundries. Anchor multi-facility service agreements with integrated delivery networks before procurement consolidation hardens vendor lock-in.
For New Entrants and Emerging Players: AI-augmented arrhythmia detection algorithms embedded in consumer wearables offer a technology-first wedge into post-discharge cardiac monitoring programs at community hospitals lacking specialist interpretation capacity. Rural federally qualified health centers and critical access hospitals in Medicaid expansion states represent the most penetrable deployment channel, with modular telemedicine kits requiring minimal clinical workflow reconfiguration serving as the optimal go-to-market vehicle.
For Investors and Strategic Acquirers: Valuations sit cheapest among modular kit specialists with established reimbursement code alignment but sub-scale enterprise sales infrastructure, presenting asymmetric upside if hospital procurement consolidation reverses toward point-of-care purchasing autonomy. Long-term viability hinges on sustained CMS payment infrastructure for remote patient monitoring across the chronic disease management window. Monitor FDA pre-certification pathway expansion velocity as the decisive inflection signal for software-driven diagnostic platform commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway Investment | Accelerates software-driven diagnostic clearances, compressing time-to-market for algorithm-based cardiac monitoring platforms. |
| Hospital System Partnership | Secures multi-facility procurement contracts spanning hardware, software licensing, and clinical workflow integration. |
| Reimbursement Strategy | Aligns device form factors with CMS remote therapeutic monitoring codes to capture Medicare Advantage chronic disease management spend. |
| Software Companion Development | Extends hardware margins through recurring SaaS revenue from AI-augmented triage and automated anomaly detection. |
| CE Marking Pathway | Unlocks European Union market access despite EU MDR stricter clinical evidence requirements for algorithm updates. |
Research Methodology
Multiple input streams — hospital procurement database analysis, CMS reimbursement rulemaking documentation, and FDA 510(k) clearance filings — were reconciled against primary interviews with biomedical engineers, GPO contracts managers, and cardiology service line directors. Secondary validation drew from hospital capital expenditure disclosures, medical device trade customs records, and CMS Medicare claims data. Bottom-up unit economics modeling and top-down reimbursement-driven demand estimation were triangulated to anchor volume projections.
Data-stream reconciliation across the analysis window applied segment-specific growth coefficients to wearable devices, remote monitors, mobile health platforms, and telemedicine kits, with technology deployment complexity and end-user procurement concentration as cross-cutting adjustment factors. CAGRs were derived from fitted growth curves calibrated to historical reimbursement expansion patterns and regulatory clearance velocity. Forecast inputs included FDA pre-certification pipeline depth and integrated delivery network vendor consolidation trajectories.
The model holds under stable CMS reimbursement infrastructure and continued FDA digital health pathway expansion; deviation in Medicare coverage determination reversals or EU MDR notified body capacity constraints would shift commercialization timelines and demand elasticity assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Global Abutment Implants Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Global Holter ECG Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Global Medical Dynamometer Market