
 Spinal Non-Fusion Technologies Market | 2026-2036
Spinal Non-Fusion Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Non-Fusion Technologies Market Analytics
Premium-grade titanium and cobalt-chromium construct specifications is bifurcating the competitive landscape into high-performance and cost-optimized tiers. Medtronic leverages its integrated surgical robotics platform to anchor premium positioning across cervical and lumbar disc replacement. Stryker sustains differentiated channel control through its Stryker Sustainability Solutions reprocessing arm, which competes on total cost of ownership. NuVasive specializes in lateral single-position surgery workflows that reduce operative time and hospital length of stay.
Spinal non-fusion technologies encompass motion-preserving implants and biologic interventions designed to restore segmental stability without eliminating native spinal kinematics, typically employing ultra-high molecular weight polyethylene cores with metallic endplates engineered to withstand 10 million cycles of fatigue loading under ISO 18192-1 protocols. These systems serve the primary purpose of treating symptomatic degenerative disc pathology while preserving adjacent-level biomechanics. Artificial discs currently occupy the largest revenue pool among product categories, though dynamic stabilization devices represent the fastest-expanding segment as surgeons seek hybrid constructs for multilevel pathology. Minimally invasive surgery technology leads procedural adoption, while robotic surgery platforms command the highest capital intensity and per-case disposable economics.
The FDA's premarket approval pathway and the European Medicines Agency's MDR conformity requirements collectively shape product development timelines and clinical evidence thresholds for disc arthroplasty systems. Health Technology Assessment bodies in Germany and France impose additional economic evidence requirements that filter market access for premium-tier implants. Stakeholders must monitor evolving NICE guidance in the United Kingdom and CMS national coverage determinations in the United States, as these decisions directly determine reimbursement parity between fusion and non-fusion alternatives.
Market Dynamics
The FDA's breakthrough device designation pathway is compressing commercialization timelines for disc replacement systems while simultaneously elevating clinical evidence thresholds, creating a bifurcation between well-capitalized innovators and resource-constrained entrants.
Growth Catalysts
- Commercial Payer Coverage Expansion:United States insurers are broadening prior authorization pathways for cervical arthroplasty, reducing patient out-of-pocket burden and accelerating procedural volume in ambulatory surgical centers.
- ISO 18192-1 Protocol Maturation:Standardized fatigue testing methodologies for metallic endplates and polyethylene cores are reducing regulatory uncertainty and streamlining 510(k) submission preparation for implant developers.
- Aging Demographics:The United States population aged 65 and above is driving symptomatic degenerative disc disease prevalence, expanding the addressable candidate pool for motion-preserving interventions.
Market Restraints
- Premium Alloy Cost Volatility:Cobalt-chromium and titanium feedstock price fluctuations are compressing gross margins for manufacturers committed to high-performance construct specifications.
- European MDR Compliance Burden:The European Medicines Agency's heightened clinical evidence requirements for Class III implantable devices are extending time-to-market and straining notified body capacity.
- Fusion Surgery Substitution Threat:Established anterior cervical discectomy and fusion procedures retain reimbursement parity and surgeon familiarity, limiting non-fusion penetration in budget-constrained health systems.
Strategic Opportunities
- Hybrid Construct Adoption:Multilevel pathology treatment protocols are converging artificial disc replacement with dynamic stabilization devices, creating demand for integrated surgical planning platforms.
- Lateral Single-Position Surgery Workflows:Operating room efficiency gains from reduced patient repositioning are driving preference for specialized retractor systems and compatible implant geometries.
- CMS National Coverage Determination Tailwinds:Potential Medicare reimbursement parity expansion for lumbar disc arthroplasty would unlock procedural volume in the United States hospital outpatient setting.
Industry Challenges
- Surgeon Training Pipeline Constraints:Motion-preserving implant placement demands specialized technique mastery that conflicts with compressed fellowship timelines and declining spinal surgery residency slots.
- Robotic Platform Capex Intensity:Capital equipment acquisition costs for navigation-assisted disc replacement are straining ambulatory surgical center balance sheets and slowing technology diffusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Non-Fusion Technologies Market |
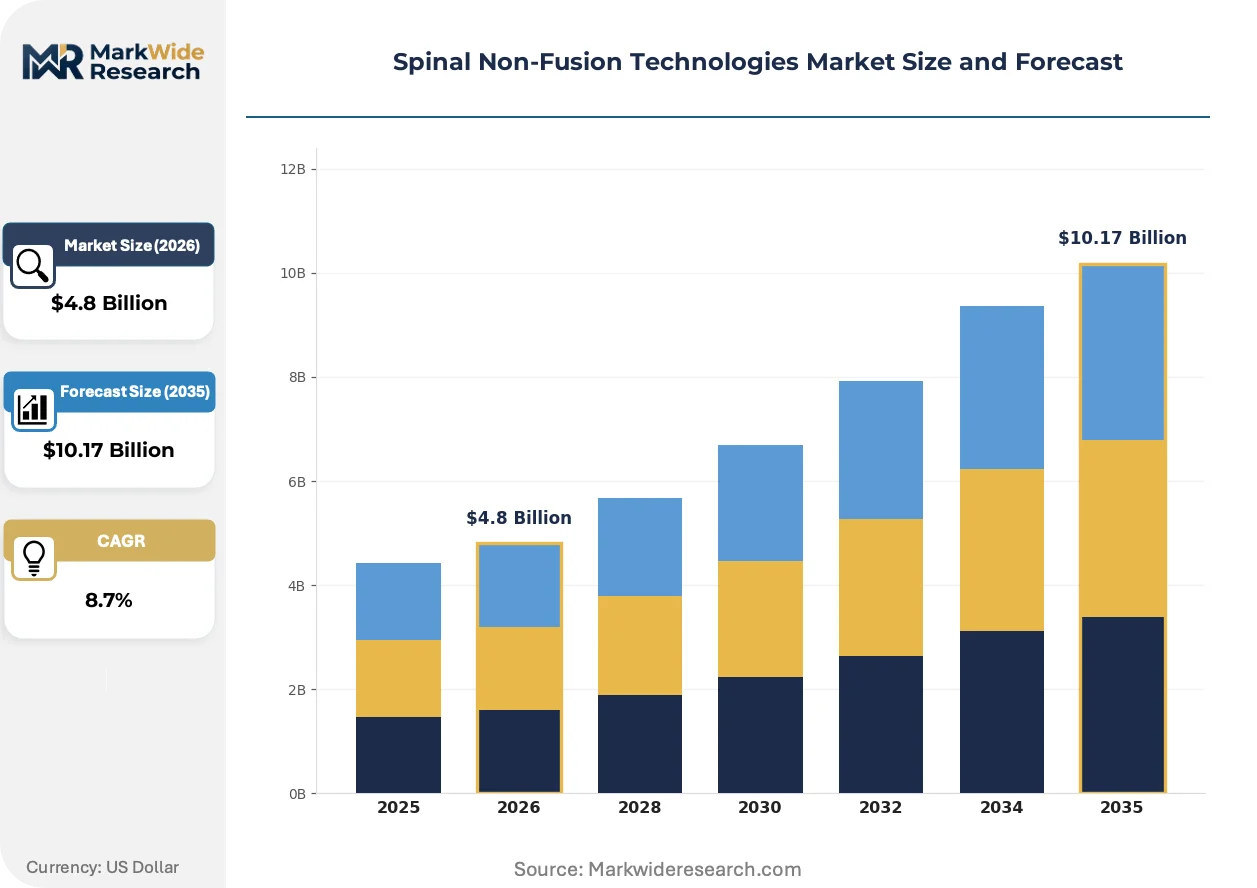
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Discs, Dynamic Stabilization Devices, Bone Grafts, Biologics Application: Degenerative Disc Disease, Spinal Stenosis, Herniated Discs, Revision Surgery End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Ambulatory Surgical Centers Technology: Robotic Surgery, Minimally Invasive Surgery, Imaging Systems, Computer-assisted Navigation |
| Companies Covered | Medtronic, Stryker, NuVasive, Globus Medical, Zimmer Biomet, DePuy Synthes, Orthofix Medical, ZimVie, Centinel Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Non-Fusion Technologies Market Evolving Landscape
Three intersecting developments are restructuring competitive positioning: materials science advances in bearing surfaces, regulatory pathway evolution for breakthrough devices, and surgical venue migration toward outpatient settings.
Polyethylene-on-ceramic bearing couples are supplanting conventional metal-on-polyethylene constructs in cervical applications. High-volume orthopedic centers in the United States are adopting these configurations for reduced wear debris generation and extended implant longevity. This transition is compressing market share for legacy cobalt-chromium endplate designs while elevating ceramics suppliers into tier-one vendor status.
The FDA's breakthrough device designation pathway is accelerating premarket approval timelines for novel disc replacement systems with demonstrated superiority endpoints. Manufacturers are responding by front-loading clinical trial investment and prioritizing randomized controlled study designs over historical registry data. Cervical arthroplasty categories are experiencing the most pronounced regulatory velocity, with lumbar segments trailing due to complex biomechanical validation requirements.
Ambulatory surgical centers are consolidating procurement authority previously dispersed across hospital value analysis committees. Device manufacturers are restructuring field sales organizations to support direct contracting with facility administrators rather than individual surgeon relationships. This concentration is most visible in the United States southeastern and southwestern regions, where freestanding spine specialty centers are capturing lumbar decompression and single-level arthroplasty volume from acute care hospitals.
Spinal Non-Fusion Technologies Market Segmentation
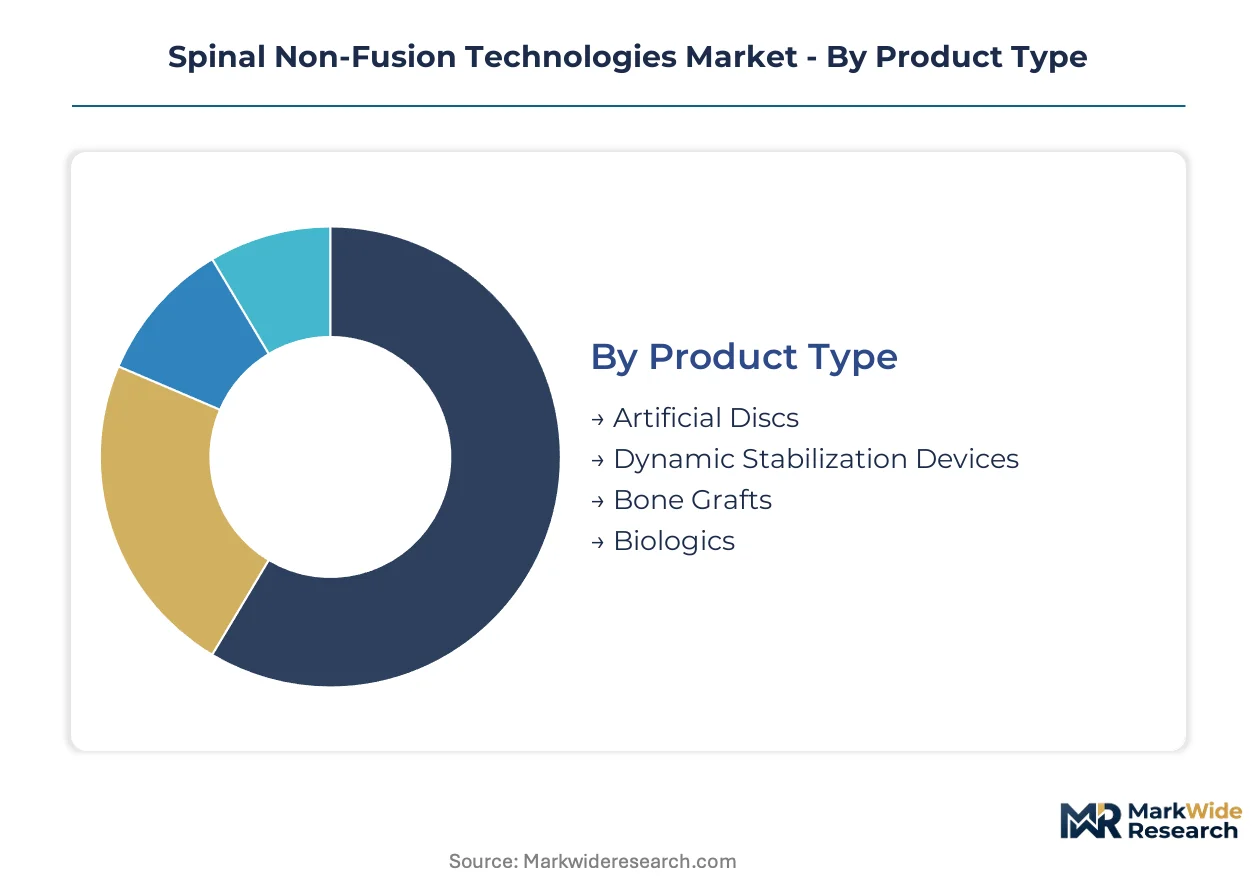
Segmentation in spinal non-fusion technologies reveals distinct margin architectures across implant categories, surgical venues, and enabling technologies. Understanding these divisions allows manufacturers to align R&D investment with reimbursement trajectories and procedural adoption curves.
Product Type:
Margin pools concentrate in bearing surface technologies where materials science differentiation commands premium pricing and long-term supply contracts.
- Artificial Discs:Ultra-high molecular weight polyethylene cores paired with titanium or cobalt-chromium endplates dominate revenue contribution. United States ambulatory surgical centers are expanding cervical and lumbar disc replacement volumes as commercial payer coverage broadens prior authorization pathways.
- Dynamic Stabilization Devices:Pedicle screw-based flexible rod systems and interspinous spacers preserve segmental motion while limiting adjacent-level stress. Demand is climbing fastest for hybrid constructs combining dynamic stabilization with artificial disc replacement in multilevel pathology protocols.
- Bone Grafts:Demineralized bone matrix and synthetic ceramic scaffolds serve interbody fusion adjunct applications.
- Biologics:Bone morphogenetic protein formulations and platelet-derived growth factor therapies accelerate osseointegration.
The dominant share belongs to Artificial Discs, while Dynamic Stabilization Devices is closing the gap fastest.
Application:
Procedure volumes track directly to aging demographics and symptomatic disease prevalence, with pathology-specific reimbursement codes shaping site-of-service economics.
- Degenerative Disc Disease:Symptomatic disc collapse with radiculopathy or myelopathy represents the foundational indication for motion-preserving implants. United States Medicare and commercial payer coverage expansion for cervical arthroplasty is accelerating patient access and reducing out-of-pocket burden.
- Spinal Stenosis:Central canal and foraminal narrowing drives demand for decompression combined with stabilization. Lateral single-position surgery workflows are gaining preference for reduced operative time and hospital length of stay in high-volume orthopedic centers.
- Herniated Discs:Discectomy with or without implant placement addresses acute radicular symptoms.
- Revision Surgery:Adjacent-level degeneration and implant failure cases require complex reconstruction.
Degenerative Disc Disease captures the largest procedure volume, though Spinal Stenosis applications are expanding most quickly as minimally invasive techniques mature.
End User:
Capital intensity and reimbursement differentials are fragmenting procurement authority across acute care and outpatient venues.
- Hospitals:Academic medical centers and community hospitals retain complex multilevel and revision case volumes. The United States hospital outpatient department setting awaits potential CMS national coverage determination expansion for lumbar disc arthroplasty to unlock procedural growth.
- Ambulatory Surgical Centers:Freestanding spine specialty facilities are consolidating lumbar decompression and single-level arthroplasty volume from acute care hospitals. Direct contracting with device manufacturers is replacing traditional value analysis committee structures in southeastern and southwestern United States markets.
- Outpatient Clinics:Physician office-based settings handle diagnostic and conservative management.
- Rehabilitation Centers:Post-acute facilities manage functional recovery protocols.
Hospitals maintain the dominant share, yet Ambulatory Surgical Centers are gaining share fastest as venue migration accelerates.
Technology:
Per-case disposable economics and capital equipment amortization create divergent margin structures across enabling technology categories.
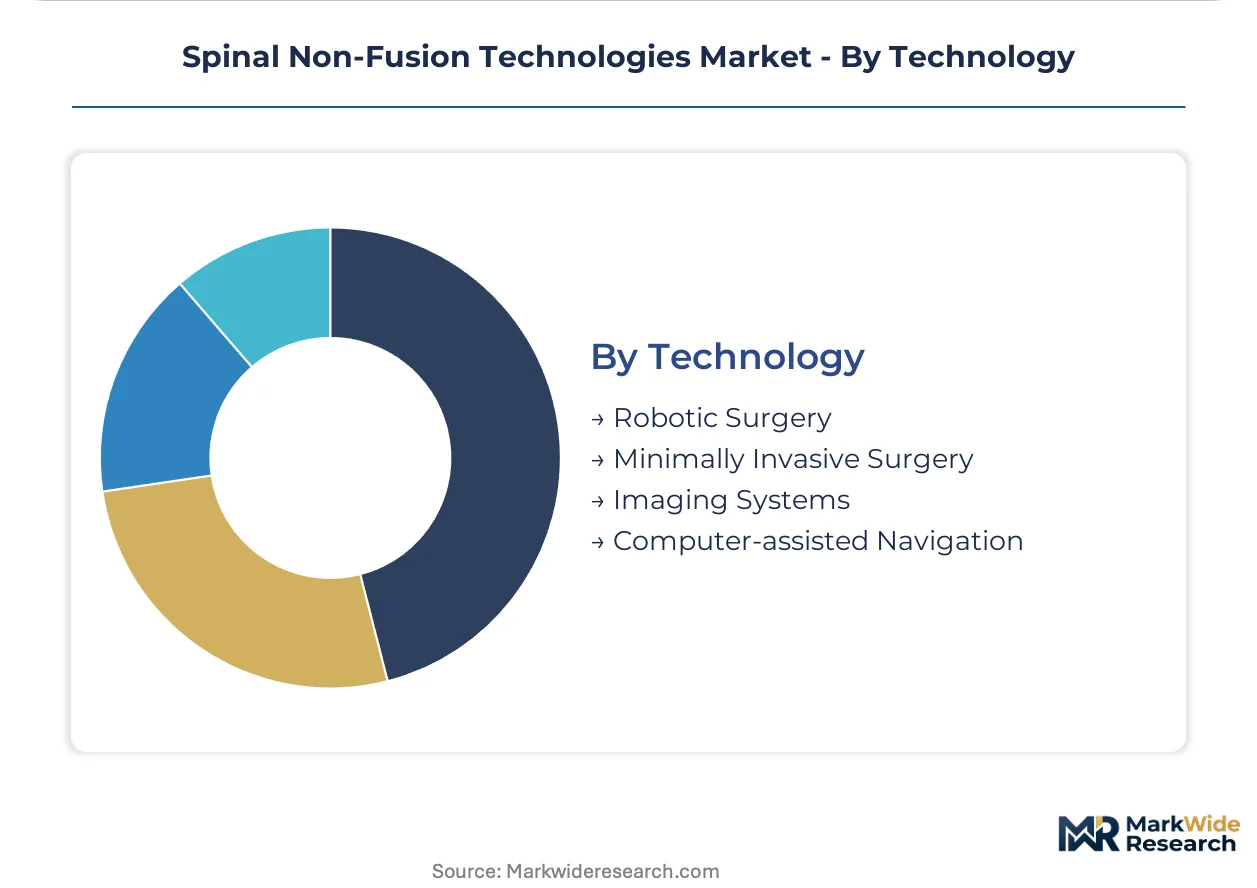
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous instrumentation reduce tissue disruption and accelerate recovery. This technology leads procedural adoption across cervical and lumbar applications due to established surgeon training pathways and favorable reimbursement.
- Robotic Surgery:Navigation-assisted implant placement platforms command the highest capital intensity and disposable economics. Ambulatory surgical center balance sheet constraints are slowing technology diffusion despite demonstrated precision benefits.
- Imaging Systems:Intraoperative CT and fluoroscopy enable real-time visualization.
- Computer-assisted Navigation:Optical and electromagnetic tracking improves implant positioning accuracy.
Minimally Invasive Surgery holds the dominant share, while Robotic Surgery shows the steepest expansion trajectory as platform economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration clusters around established orthopedic manufacturing corridors where regulatory infrastructure and specialized fabrication capabilities co-locate. Device developers prioritize proximity to FDA and European Medicines Agency pathways, while emerging markets build capacity through targeted health technology investments.
United States
Aging demographics and commercial payer coverage expansion for cervical arthroplasty drive procedural volume concentration in ambulatory surgical centers. The FDA's breakthrough device designation pathway accelerates premarket approval timelines for novel disc replacement systems. High-volume orthopedic clusters in Texas and Florida capture lumbar decompression and single-level arthroplasty volume migrating from acute care hospitals.
Germany
Health Technology Assessment bodies impose stringent economic evidence requirements that filter market access for premium-tier implants. The European Medicines Agency's MDR conformity requirements extend time-to-market for Class III implantable devices. Manufacturing concentration in Baden-Württemberg supports precision machining of cobalt-chromium endplates and ceramic bearing surfaces.
Japan
PMDA regulatory frameworks emphasize long-term clinical follow-up for motion-preserving implants, elevating evidence thresholds above 510(k) equivalents. METI industrial policy supports domestic production of ultra-high molecular weight polyethylene cores through advanced polymer processing initiatives. Tokyo-Osaka medical device corridors anchor regional distribution networks across East Asian markets.
Switzerland
Swissmedic maintains rigorous post-market surveillance protocols that align with premium positioning strategies for bearing surface technologies. Precision engineering capabilities in the Lake Geneva region support micron-level tolerances for metallic endplate fabrication. Zürich and Basel clusters specialize in ceramic-on-polyethylene construct development for extended implant longevity applications.
Australia
TGA regulatory harmonization with FDA pathways reduces submission burden for United States-originated disc replacement systems. Public hospital procurement frameworks emphasize total cost of ownership metrics that favor reprocessed instrumentation and standardized implant geometries. Sydney and Melbourne spine specialty centers pioneer lateral single-position surgery workflows for reduced operative time.
Spinal Non-Fusion Technologies Market Competitive Landscape
Concentration sits with diversified orthopedic conglomerates that leverage integrated surgical robotics platforms and channel control through reprocessing arms. The competitive structure bifurcates between high-performance construct specifications and cost-optimized tiers, with premium positioning anchored by materials science differentiation and regulatory velocity. Strategic archetypes include robotics-integrated platform developers, sustainability-focused reprocessing operators, and lateral access workflow specialists. Dominant competitive moves encompass M&A for surgical planning software capabilities and capacity expansion into ambulatory surgical center direct contracting.
Among diversified orthopedic conglomerates, Medtronic, Stryker, and NuVasive occupy positions spanning the premium-to-standard tier spectrum. Medtronic represents the robotics-integrated platform archetype through its surgical navigation ecosystem. Stryker exemplifies sustainability-oriented competitive positioning via its reprocessing infrastructure. NuVasive anchors the lateral access specialization vector with single-position surgery workflow development. These three entities collectively illustrate how scale, channel control, and procedural efficiency define competitive differentiation in motion-preserving implant markets.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| NuVasive |
| Globus Medical |
| Zimmer Biomet |
| DePuy Synthes |
| Orthofix Medical |
| ZimVie |
| Centinel Spine |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for cobalt-chromium feedstock concentrate pricing power among titanium endplate fabricators in Baden-Württemberg and implant finishers in Warsaw, while ambulatory surgical center procurement consolidation compresses margin capture across polyethylene core assemblers.
Pricing Analysis
FDA premarket approval requirements dictate the pricing tier structure across cervical and lumbar disc replacement systems. Pricing stratifies across premium, standard, and economy tiers based on ISO 18192-1 fatigue testing certification level and bearing surface material specification. Cost compression in standard-tier constructs is intensifying because European MDR compliance investments force manufacturers to absorb notified body fees without passing through to constrained hospital buyers. Ambulatory surgical centers exhibit highest price sensitivity due to direct contracting authority and total cost of ownership metrics, while academic medical centers retain lowest sensitivity through bundled reimbursement protocols.
Supply Chain Analysis
Strait of Malacca transit chokepoints for ultra-high molecular weight polyethylene resin shipments from Singapore petrochemical hubs to Osaka polymer processing facilities elevate logistics risk for core manufacturers. Supply concentrates in Switzerland for micron-level metallic endplate machining, Germany for cobalt-chromium precision casting, and Japan for ceramic bearing surface sintering. Raw material dependencies center on titanium sponge from Ukrainian and Kazakh smelters, medical-grade polyethylene from Saudi and Thai polymer plants, and yttria-stabilized zirconia from Australian rare earth processors. Single-source vulnerability pervades ceramic powder supply. Distribution runs through orthopedic GPO consortiums in the United States and specialized device distributors in European hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from reprocessing programs and surgical planning software subscriptions is expanding faster than hardware unit economics, repositioning margin capture toward recurring-revenue layers.
For Market Incumbents: Fortify channel control through direct contracting infrastructure with ambulatory surgical center networks in the United States southeastern corridor, while deepening backward integration into titanium forging capacity to offset cobalt-chromium feedstock volatility. Threat substitution from lateral single-position surgery workflows demands counterinvestment in compatible retractor geometries. Certification leverage through FDA breakthrough device designation remains the priority defensive lever. For New Entrants and Emerging Players: Lead with hybrid construct development targeting multilevel pathology protocols, where artificial disc replacement and dynamic stabilization device integration remains underpenetrated relative to standalone fusion alternatives. The most penetrable white space sits in lumbar disc arthroplasty for ambulatory surgical centers awaiting CMS national coverage determination expansion. Go-to-market execution should anchor on surgical workflow training partnerships rather than capital equipment sales. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates seeking to divest non-core spine assets amid portfolio rationalization pressures. Long-term viability over the projection horizon hinges on reimbursement parity expansion and materials science differentiation durability. Acquisition archetypes include lateral access workflow specialists with established surgeon training ecosystems. The signal to watch is CMS national coverage determination timing for lumbar arthroplasty in hospital outpatient settings.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway Pursuit | Accelerated premarket approval compresses time-to-revenue for novel bearing surface configurations. |
| Ambulatory Surgical Center Direct Contracting | Bypassing hospital value analysis committees captures procedural volume migration in Texas and Florida clusters. |
| Hybrid Construct Platform Development | Integration of artificial discs with dynamic stabilization addresses multilevel pathology protocol convergence. |
| Ceramic Bearing Surface Scale-Up | Polyethylene-on-ceramic configurations command premium positioning through reduced wear debris generation. |
| Surgical Planning Software Companion Launch | Navigation-assisted implant placement platforms generate recurring revenue beyond disposable hardware economics. |
Research Methodology
Desk research of FDA 510(k) and PMA filings, ISO 18192-1 testing registries, and CMS national coverage determination records preceded structured interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, ambulatory surgical center utilization reports, and European Health Technology Assessment body publications. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Variance decomposition across product type, application pathology, end-user venue, and enabling technology segmentation dimensions informed CAGR derivation through segment-level growth rate reconciliation. Modeled inputs incorporated aging demographic projections, commercial payer coverage expansion trajectories, and regulatory pathway velocity differentials between cervical and lumbar arthroplasty categories. Volume and value outputs reflect reconciliation between implant shipment data and procedural claims analysis.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement parity expansion and ISO protocol harmonization would require recalibration. Forecasts reflect documented assumptions regarding regulatory approval timelines and surgeon training pipeline throughput. Practitioners should keep alternative scenarios live as CMS national coverage determination timing and European MDR notified body capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
Facial Implant Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Artificial Eye Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Ocular Adhesive Market