
 Automated Insulin Delivery Device Market | 2026-2036
Automated Insulin Delivery Device Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Insulin Delivery Device Market Insights
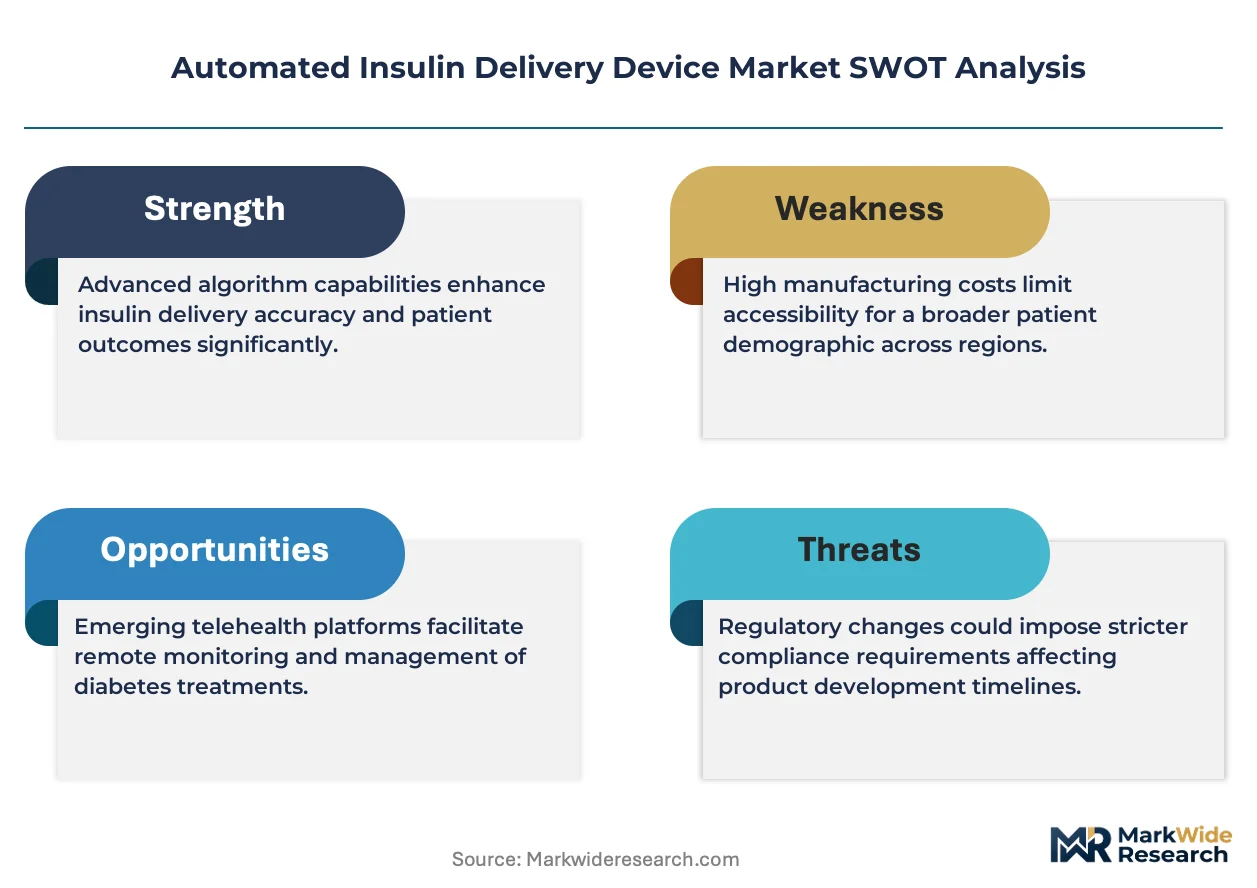
Silicone is restructuring pump chamber economics as manufacturers replace older elastomer formulations to improve insulin stability and extend wear duration. Medtronic plc leverages backward integration into sensor manufacturing to control supply timelines for its hybrid closed-loop platforms. Tandem Diabetes Care, Inc. competes through aggressive software update cadence that tightens glycemic control algorithms without hardware replacement cycles.
An automated insulin delivery device integrates a continuous glucose monitor, an insulin pump, and a control algorithm to modulate basal insulin delivery in real time based on sensor glucose readings, typically maintaining targets between 70-180 mg/dL with minimal user intervention. These systems serve primarily Type 1 diabetes patients requiring precise glycemic management to prevent microvascular complications. Closed-loop systems capture the dominant share of technology-based revenue as fully automated algorithms reduce hypoglycemic events versus hybrid alternatives. Home care providers represent the fastest-expanding end-user channel as reimbursement frameworks shift toward outpatient diabetes management.
FDA premarket review under the breakthrough devices program shapes product launch sequencing for US market entrants, while EU MDR clinical evaluation requirements extend certification timelines for automated systems. The country's national pharmaceutical regulator in Japan imposes additional local clinical trial mandates that delay commercialization relative to Western approvals. Stakeholders must monitor evolving payer evidence requirements that increasingly demand real-world glycemic outcome data beyond controlled trial endpoints.
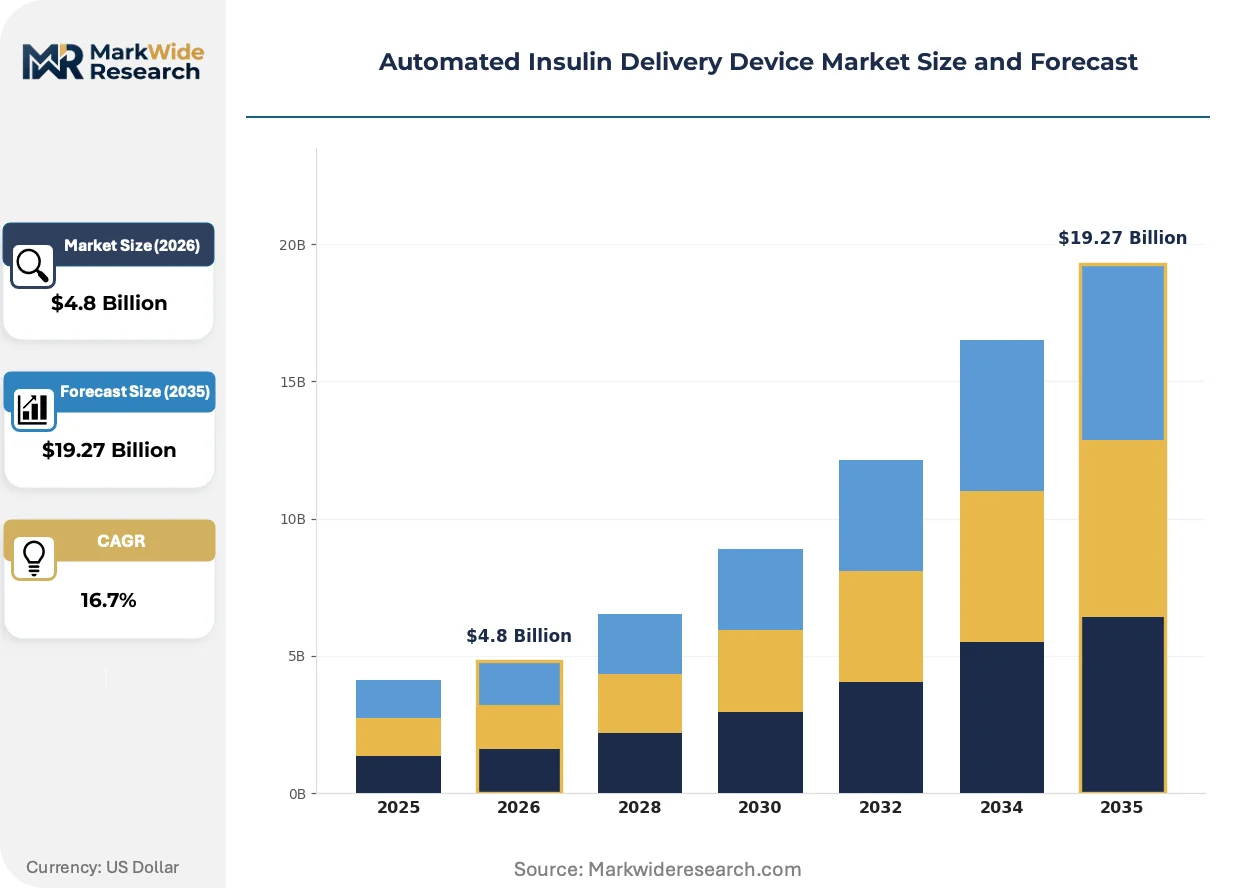
Market Dynamics
Closed-loop algorithm sophistication is compressing hardware replacement cycles as software updates deliver glycemic improvements without device swaps, shifting value capture from pump manufacturers toward algorithm developers and data platforms.
Growth Catalysts
- EU MDR breakthrough pathway:The EU MDR's tightened clinical evidence requirements are accelerating product development timelines as manufacturers front-load validation studies to secure priority review status for hybrid closed-loop systems.
- Pediatric Type 1 diabetes:Pediatric Type 1 diabetes patients represent the fastest-growing end-use adoption cohort as regulatory frameworks expand labeled indications for younger age groups and caregivers demand overnight hypoglycemia protection.
- Silicone pump chamber reformulation:Silicone is restructuring pump chamber economics as manufacturers replace older elastomer formulations to improve insulin stability and extend wear duration from three to seven days.
Market Restraints
- Sensor manufacturing concentration:Backward integration into glucose sensor production by dominant platform vendors creates supply bottlenecks for second-tier pump manufacturers lacking captive sensor supply.
- FDA premarket review friction:FDA breakthrough device designation pathways, while accelerating priority review, impose extensive predicate comparison requirements that extend preparation timelines for novel control algorithms.
- Insulin formulation thermal sensitivity:Ambient temperature excursions above 30°C degrade insulin potency in wearable pump reservoirs, limiting adoption in tropical climates without active cooling accessories.
Strategic Opportunities
- Home care channel expansion:Home care providers represent the fastest-expanding end-user channel as reimbursement frameworks shift toward outpatient diabetes management and remote patient monitoring integration.
- Dual-hormone platform convergence:Glucagon co-formulation with insulin in single-chamber pumps is creating next-generation closed-loop systems capable of automated hypoglycemia correction without carbohydrate intervention.
- Japan local trial mandate:The country's national pharmaceutical regulator imposes additional local clinical trial mandates that, once satisfied, create first-mover advantages for sponsors willing to front-load regional evidence generation.
Industry Challenges
- Algorithm validation talent scarcity:Control systems engineers with glucose-insulin kinetic modeling expertise command premium compensation, constraining development velocity for mid-tier manufacturers.
- Interoperability certification complexity:IEEE 11073 and Bluetooth LE medical device profile compliance testing extends hardware development timelines by eight to fourteen months for new pump entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Insulin Delivery Device Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Insulin Pumps, Smart Pens, Automated Systems End User: Patients, Hospitals, Clinics, Home Care Providers Technology: Closed-Loop Systems, Hybrid Systems, Wearable Devices, Mobile Applications Distribution Channel: Online Retail, Pharmacies, Medical Device Distributors, Direct Sales |
| Companies Covered | Medtronic plc, Tandem Diabetes Care, Inc., Insulet Corporation, Dexcom, Beta Bionics, Inc., Embecta Corp., Novo Nordisk A/S, Sanofi, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Insulin Delivery Device Market Trends and Innovations
Algorithm-driven personalization is displacing one-size-fits-all glycemic targets as machine learning models ingest continuous glucose trajectories to predict individual insulin sensitivity patterns and automate basal rate adjustments.
Disposable pump bodies is modularizing system architecture as manufacturers separate durable controller electronics from single-use insulin reservoirs and infusion sets, enabling patients to replace only consumable components while retaining capital-intensive control units for multi-year cycles. Home care providers and pediatric endocrinology practices are adopting these split-configuration systems at accelerated pace. This architecture is compressing per-patient lifetime revenue for hardware while expanding recurring consumable revenue streams and lowering patient switching costs.
FDA breakthrough device designation pathways are compressing commercialization timelines for sponsors demonstrating superior hypoglycemia reduction in controlled trials, though post-market surveillance requirements expand registry obligations. The industrial consequence is a bifurcation between well-capitalized sponsors capable of funding extended follow-up studies and smaller entrants constrained by registry maintenance costs. Pediatric indications and overnight closed-loop functionality are most affected, with sponsors prioritizing these endpoints in pre-submission meetings to secure expedited review.
Commercial payer coverage expansion for closed-loop systems in the United States is displacing cash-pay and patient assistance program reliance as evidence frameworks mature and pharmacy benefit managers carve out diabetes technology categories. This channel shift is consolidating purchasing influence among three national payers and their delegated medical device vendors. The concentration is most visible in employer-sponsored plans and Medicaid managed care contracts, where prior authorization requirements are standardizing around HbA1c threshold and hypoglycemia event documentation.
Automated Insulin Delivery Device Market Segmentation
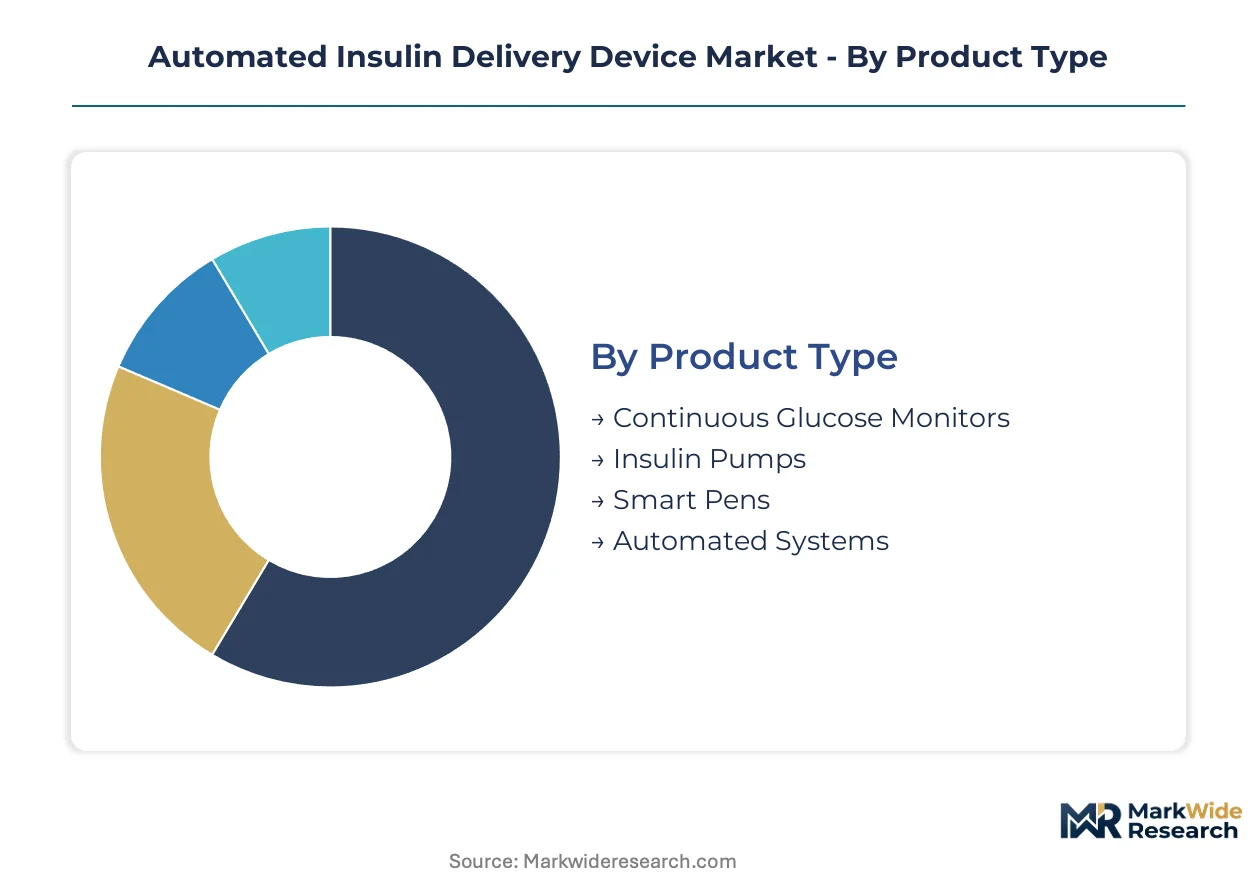
Segmentation in automated insulin delivery reveals how value migrates between hardware, software, and service layers. Manufacturers must align portfolio depth against reimbursement pathways that favor integrated systems over standalone components.
Product Type:
Standalone monitors and pumps serve patients building custom configurations, while pre-integrated automated systems dominate commercial channel procurement.
- Continuous Glucose Monitors:Electrochemical sensors measure interstitial glucose via subcutaneous filaments with 5-15 minute lag versus blood reference. Demand concentrates among Type 1 patients in the United States seeking real-time trend data for manual bolus decisions, though sensor calibration requirements frustrate pediatric caregivers overnight.
- Insulin Pumps:Motor-driven reservoir systems deliver basal rates and bolus doses through subcutaneous infusion sets, with modern variants accepting CGM input for suspend-before-low functionality. Adoption clusters in Germany and the Netherlands where statutory health insurance covers pump therapy without prior authorization thresholds.
- Smart Pens:Bluetooth-enabled injection devices log dose timing and amount to mobile applications, bridging patients not yet qualifying for pump reimbursement. Dose capture accuracy varies by injection site and depth.
- Automated Systems:Fully integrated closed-loop platforms combining sensor, pump, and algorithm in sealed ecosystems. Japan's PMDA imposes local clinical validation requirements that delay launch versus FDA breakthrough pathways.
Insulin pumps lead volumes today; automated systems are gaining share fastest.
End User:
Reimbursement eligibility criteria and care setting infrastructure determine which patient populations access which technology tiers.
- Patients:Individual purchasers drive cash-pay segments for smart pens and refurbished pumps in markets with limited public coverage. Out-of-pocket sensitivity limits attachment rates for premium consumables.
- Hospitals:Inpatient glycemic management programs deploy temporary insulin infusion systems for perioperative glucose control. Bundled payment models discourage capital investment in permanent closed-loop installations.
- Clinics:Pediatric endocrinology practices in France and the United Kingdom prescribe hybrid closed-loop systems as first-line therapy for new-onset Type 1 cases, leveraging national health technology assessment favorable rulings.
- Home Care Providers:Remote patient monitoring platforms integrate automated insulin delivery data for proactive intervention. Medicare Advantage plans in the United States increasingly contract with regional home health agencies for diabetes technology management.
Individual patients dominate current installed base; home care providers show steepest expansion trajectory.
Technology:
Algorithm autonomy separates premium positioning from assistive tools requiring persistent user engagement.
- Closed-Loop Systems:Fully automated basal rate modulation without patient-initiated bolus requirements, maintaining glucose targets through predictive insulin dosing and suspend functions. Regulatory complexity limits available vendors.
- Hybrid Systems:Automated basal adjustment with meal bolus announcement requirements, representing the dominant reimbursed configuration across European statutory health systems. User adherence to carbohydrate counting determines outcome variance.
- Wearable Devices:Patch pumps and disposable infusion sets emphasizing discretion and water resistance. Skin adhesion failures in humid climates drive return rates and brand switching.
- Mobile Applications:Smartphone-based control interfaces and data visualization platforms, increasingly mandatory for system configuration. FDA software-as-medical-device oversight extends validation timelines for algorithm updates.
Hybrid systems anchor current revenue; closed-loop configurations are climbing the fastest.
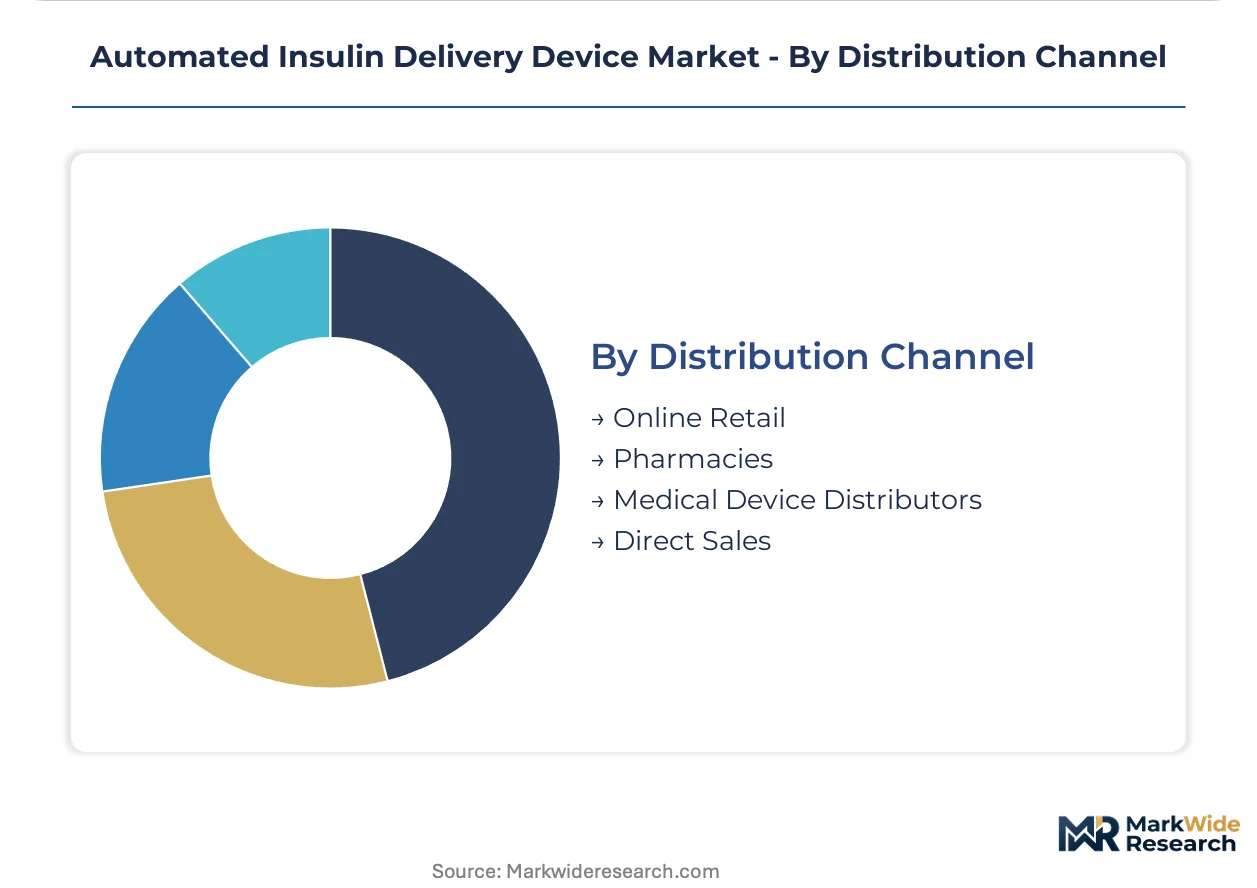
Distribution Channel:
Channel selection reflects payer integration depth and patient acuity requirements.
- Online Retail:Direct-to-consumer sales of smart pens, CGM sensors, and accessories bypass prescription requirements in select jurisdictions. Subscription models for consumables build recurring revenue.
- Pharmacies:Community and hospital pharmacy networks handle reimbursed pump and sensor fulfillment, with prior authorization processing creating fulfillment delays. Central fill operations consolidate inventory for national chains.
- Medical Device Distributors:Specialized logistics providers manage capital equipment delivery, installation, and training for automated systems. Field clinical specialist support differentiates distributor value.
- Direct Sales:Manufacturer-employed representatives target academic medical centers and integrated delivery networks with bundled system proposals. Long sales cycles require dedicated key account management.
Pharmacies capture the largest transaction volume; direct sales to health systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors the global automated insulin delivery device industry through concentrated sensor manufacturing and algorithm development clusters serving North American and European markets.
United States
Commercial payer coverage expansion for closed-loop systems and Medicare Advantage remote monitoring contracts drive demand concentration. FDA breakthrough device designation pathways compress review timelines for pediatric indications. The Boston-Cambridge corridor hosts algorithm development centers where control systems engineers refine predictive insulin dosing models.
Germany
Statutory health insurance coverage without prior authorization thresholds accelerates pump therapy adoption among Type 1 diabetes patients. EU MDR clinical evaluation requirements extend certification timelines for automated systems. The Munich medical technology cluster supports validation studies for hybrid closed-loop platforms targeting European market entry.
Japan
Pediatric endocrinology practices generate demand for overnight hypoglycemia protection in younger patient cohorts. PMDA imposes additional local clinical trial mandates that delay commercialization relative to Western approvals. The Tokyo-Osaka corridor concentrates regulatory consulting expertise for sponsors navigating Japan's pharmaceutical approval pathways.
United Kingdom
National Health Service technology assessment favorable rulings position hybrid closed-loop systems as first-line therapy for new-onset Type 1 cases. MHRA post-Brexit regulatory divergence creates parallel submission requirements for EU-UK market access. The Oxford-Cambridge life sciences arc hosts clinical trial sites generating real-world glycemic outcome data.
Netherlands
Integrated diabetes care networks and outpatient management reimbursement frameworks expand home care provider adoption. CE marking under EU MDR requires extended clinical evidence documentation for algorithm-driven devices. The Eindhoven health technology ecosystem supports disposable pump body manufacturing for modular system architectures.
Automated Insulin Delivery Device Market Competitive Landscape
Backward integration into sensor manufacturing dominates the current landscape as platform vendors secure captive glucose monitoring supply. The vendor base concentrates around integrated closed-loop ecosystems rather than standalone component suppliers. Three archetypes define competitive positioning: diversified medical technology conglomerates with diabetes divisions, pure-play insulin delivery specialists, and continuous glucose monitor-first entrants expanding into pump integration. M&A activity and strategic algorithm licensing agreements represent the primary competitive moves reshaping market structure.
Among diversified medical technology conglomerates, Medtronic plc exemplifies the vertically integrated archetype through in-house sensor production. Tandem Diabetes Care, Inc. occupies a position within the pure-play insulin delivery specialist tier. Dexcom represents the sensor-first expansion archetype as CGM-native vendors pursue pump integration partnerships.
| Leading Market Players |
|---|
| Medtronic plc |
| Tandem Diabetes Care, Inc. |
| Insulet Corporation |
| Dexcom |
| Beta Bionics, Inc. |
| Embecta Corp. |
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| Others |
Pricing and Supply Chain Analysis
Commercial payer concentration in the United States consolidates purchasing power among three national pharmacy benefit managers, forcing manufacturers toward subscription-based pricing models that bundle hardware, sensors, and algorithm access into predictable per-patient monthly fees.
Pricing Analysis
Silicone elastomer and electrochemical sensor substrate costs pass through directly to automated system pricing, with FDA breakthrough designation tiers commanding premium positioning over standard 510(k) pathways. Price differentiation rests on algorithm autonomy level and pediatric indication breadth. Cost compression in consumable reservoirs intensifies as seven-day wear formulations displace three-day alternatives. Cash-pay patients in markets with limited reimbursement show highest price sensitivity, while employer-sponsored plans with carved-out diabetes technology categories absorb premium closed-loop systems without prior authorization friction.
Supply Chain Analysis
ISO 13485 and FDA Quality System Regulation compliance gates concentrate glucose sensor manufacturing in the United States, Malaysia, and Ireland, where cleanroom infrastructure and sterilization validation capabilities anchor production. The supply chain draws from platinum-group catalysts for electrochemical filaments, medical-grade silicone for pump chambers, and lithium-polymer cells for wearable power. Single-source vulnerability in subcutaneous sensor adhesive formulations creates exposure to tropical climate performance failures. Distribution runs through specialized medical device distributors with field clinical specialist networks rather than commodity logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough device designation pathways compound regulatory advantage into pricing power and channel access, with pediatric indication expansion serving as the primary demand accelerator across reimbursement frameworks.
For Market Incumbents: Hedge against algorithm commoditization by deepening in-house production of electrochemical sensors and securing exclusive adhesive formulation supply agreements. Defensive consolidation through acquisition of machine learning talent pools in the Boston-Cambridge corridor protects algorithm differentiation. Prioritize CE marking under EU MDR ahead of competitors to capture statutory health insurance channels in Germany and the Netherlands.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier entry point for smart pen and CGM accessory penetration before pursuing integrated closed-loop certification. White-space targets include home care provider remote monitoring integrations and tropical climate active cooling accessory development. A reimbursement-first go-to-market angle targeting Medicaid managed care contracts with documented hypoglycemia reduction evidence accelerates payer acceptance.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates with diabetes divisions are the most active acquirers in this space, seeking algorithm development teams and captive sensor manufacturing assets. Long-term viability over the next decade hinges on dual-hormone platform convergence and software update monetization models. Watch for FDA pediatric indication grants as inflection indicators for valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Pediatric indication priority review compresses commercialization timelines versus standard 510(k) pathways. |
| Backward Integration into Sensor Manufacturing | In-house electrochemical filament production insulates against supply bottlenecks for second-tier pump vendors. |
| Software Companion Development | Mobile application integration with automated basal modulation tightens glycemic control without hardware replacement. |
| Reimbursement Strategy Execution | Medicare Advantage remote monitoring contracts expand home care provider channel penetration. |
| CE Marking Pathway Acceleration | EU MDR clinical evaluation front-loading secures statutory health insurance access in Germany and Netherlands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pediatric endocrinologists, biomedical engineers at pump manufacturers, pharmacy benefit manager formulary directors, and GPO contracts managers with secondary validation against FDA 510(k) and breakthrough device filings, CMS Medicare reimbursement databases, EU MDR notified body certification records, and hospital procurement contract awards. Bottom-up patient population modeling and top-down revenue triangulation anchored segment-level estimates.
Segment-weighting approaches distributed value across product type, end user, technology tier, and distribution channel dimensions throughout the forecast period. CAGRs were derived from fitted growth curves applied to installed base expansion and consumable attachment rate trajectories. Algorithm update velocity and silicone pump chamber wear duration improvements served as technology-specific forecast inputs alongside reimbursement pathway expansion assumptions.
Regulatory approval delays, sensor adhesive performance failures in humid climates, and payer prior authorization requirement changes are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in FDA breakthrough designation grant rates or EU MDR notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Foot Massage Machine Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Global Concussion Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
South America C-Arms Market
Medical Devices
Microdebrider Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Vitrectomy Devices Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
MRI Coils Market