
 Gastroretentive Drug Delivery Systems Outsourcing Market | 2026-2036
Gastroretentive Drug Delivery Systems Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Gastroretentive Drug Delivery Systems Outsourcing Market Analytics
Buyer concentration among mid-sized pharmaceutical developers is broadening as more biotech firms without in-house manufacturing capabilities pursue gastroretentive programs. Catalent leverages integrated drug-product development campuses to capture early-phase outsourcing commitments. Lonza anchors European demand through specialized containment and modified-release expertise. Adare Pharma Solutions differentiates via proprietary gastroretentive technologies and taste-masking platforms.
Gastroretentive drug delivery systems employ buoyant, expandable, or mucoadhesive formulations to prolong gastric residence and enhance absorption of drugs with narrow absorption windows or poor colonic bioavailability. These systems typically incorporate hydroxypropyl methylcellulose, polycarbophil, or effervescent matrices engineered for specific density profiles below gastric fluid. Contract Manufacturing commands the largest service-type value pool due to capital-intensive specialized equipment requirements, while Research & Development segments expand fastest as sponsors seek integrated formulation-to-commercial partners. Extended Release formulations dominate product-type demand, though Controlled Release platforms capture premium pricing for narrow-therapeutic-index compounds.
FDA bioequivalence guidelines and EMA quality-by-design expectations shape formulation development protocols and documentation burdens for outsourced programs. CDSCO in India and NMPA in China enforce evolving GMP standards that determine which contract manufacturers qualify for international sponsor audits. Stakeholders must monitor regulatory divergence across FDA, EMA, and emerging-market agencies when selecting multi-regional manufacturing partners.
Market Dynamics
FDA bioequivalence standards for modified-release oral dosage forms are forcing pharmaceutical sponsors to seek specialized formulation partners with documented gastric-retentive expertise, compressing the qualified vendor pool and elevating technical barriers to market entry.
Growth Catalysts
- EMA Quality-by-Design Mandates:European sponsors now require integrated formulation-to-commercial partners capable of delivering design-space documentation, accelerating demand for full-service CDMO relationships over fragmented vendor chains.
- India:CDSCO GMP infrastructure upgrades and expanding technical labor pools in Hyderabad and Ahmedabad are attracting international formulation development work from mid-sized pharmaceutical developers lacking in-house capabilities.
- Mucoadhesive Polymers:Advances in polycarbophil and carbomer matrix engineering are enabling gastric residence times exceeding twelve hours for narrow-absorption-window compounds, opening therapeutic categories previously unsuited to oral delivery.
Market Restraints
- Specialized Equipment Concentration:High-shear granulators and fluid-bed coaters capable of effervescent matrix production remain concentrated among established European and North American equipment suppliers, limiting capacity expansion speed in emerging manufacturing hubs.
- Hydroxypropyl Methylcellulose Price Volatility:Pharmaceutical-grade HPMC supply depends on cellulose ether production concentrated in China, creating input cost instability for buoyant formulation developers.
- FDA Bioequivalence Study Burden:The agency's continued emphasis on scintigraphic gastric-emptying validation and pharmacokinetic bridging studies extends program timelines and elevates outsourcing costs for modified-release programs.
Strategic Opportunities
- Controlled Release for Narrow-Therapeutic-Index Compounds:Oncology and immunosuppressant developers seek premium-priced gastric-retentive platforms capable of zero-order release kinetics, creating margin expansion potential beyond standard extended-release formulations.
- Brazil:ANVISA's accelerating GMP harmonization with PIC/S standards positions São Paulo and Campinas contract manufacturers to capture Latin American gastroretentive outsourcing demand previously directed to North American vendors.
- 3D Printing Convergence:Fused deposition modeling of gastric-retentive geometries is decentralizing prototype development from centralized pilot plants to sponsor-integrated formulation laboratories, compressing design iteration cycles.
Industry Challenges
- Containment Engineering Talent Scarcity:Potent compound handling within gastric-retentive programs requires specialized isolator operation and cleaning validation expertise that outpaces current training pipeline output in India and Eastern Europe.
- Multi-Regional Audit Complexity:Sponsors selecting manufacturing partners must reconcile divergent FDA, EMA, and NMPA documentation expectations for modified-release stability protocols and process analytical technology implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastroretentive Drug Delivery Systems Outsourcing Market |
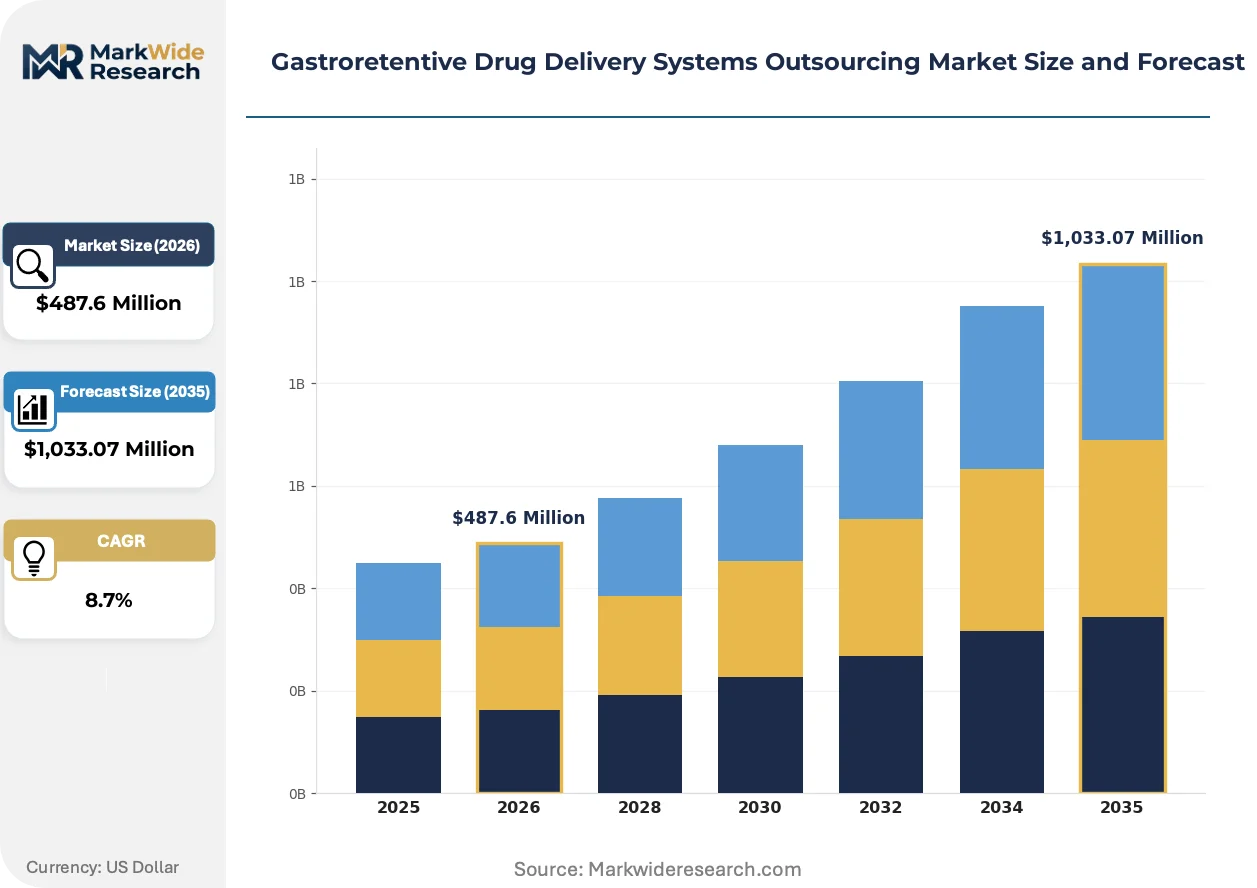
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Contract Manufacturing, Clinical Trials, Research & Development, Quality Control Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Product Type: Extended Release, Sustained Release, Controlled Release, Matrix Systems |
| Companies Covered | Aenova Group, Patheon, Catalent, Colorcon, Siegfried Holding, Lonza, Quotient Sciences, Adare Pharma Solutions, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastroretentive Drug Delivery Systems Outsourcing Market Evolving Landscape
Continuous manufacturing platforms and digital twin modeling are compressing formulation development cycles for gastric-retentive dosage forms, while regulatory agencies tighten documentation expectations for design-space verification.
Effervescent matrix technology employing sodium bicarbonate and citric acid is decentralizing gastric-retentive formulation development from centralized CDMO campuses to sponsor-integrated pilot facilities. Mid-sized biotech firms without captive manufacturing assets are adopting tabletop fluid-bed systems for rapid prototype iteration. This capability diffusion is compressing early-phase outsourcing timelines and elevating technical due diligence requirements for contract partner selection.
EMA's evolving expectations for in-vitro dissolution biorelevant media—specifically the adoption of physiologically relevant hydrodynamic conditions—are elevating analytical capability requirements across European formulation programs. Sponsors must now demonstrate hydrodynamic flow patterns mimicking human gastric motility during regulatory submissions. High-shear granulation process developers face the steepest compliance adaptation burden as legacy USP apparatus methods lose regulatory acceptance.
Biotech procurement departments are consolidating vendor relationships from fragmented formulation-analytical-manufacturing chains to single accountability partners with integrated quality systems. Early-phase sponsors previously engaging separate preformulation consultants and clinical manufacturing vendors now mandate campus-based continuity through commercial scale-up. This concentration pattern is most visible among Boston and San Francisco corridor developers pursuing 505(b)(2) regulatory pathways for reformulated assets.
Gastroretentive Drug Delivery Systems Outsourcing Market Segmentation
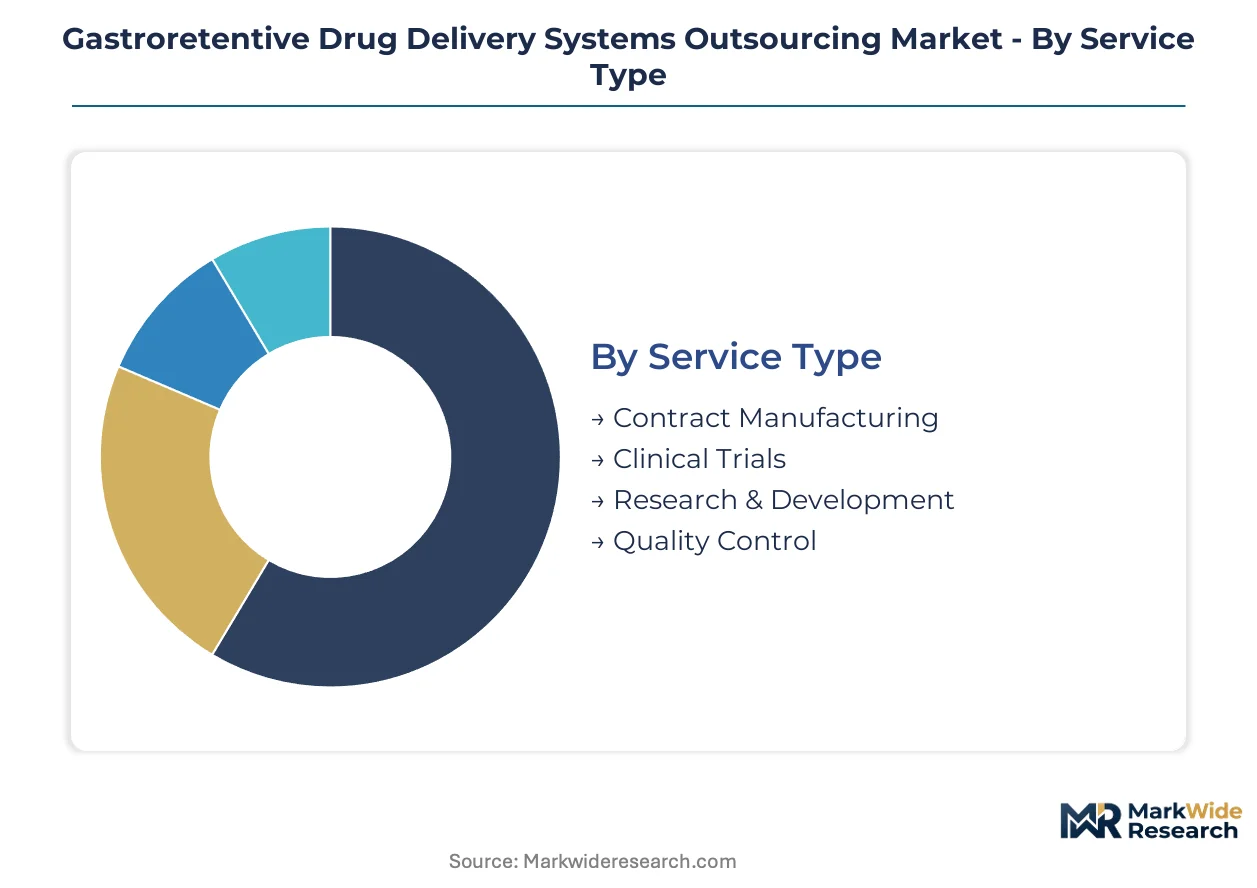
Gastroretentive outsourcing contracts bifurcate sharply between capital-intensive manufacturing services and knowledge-intensive development work, with each segment carrying distinct FDA bioequivalence documentation burdens. Sponsors selecting vendors must match program phase to service capability, as early-stage formulation support demands divergent technical assets from commercial-scale effervescent matrix production.
Service Type:
CDSCO and EMA audit frequencies concentrate heaviest on Contract Manufacturing facilities handling buoyant matrix production, while Research & Development segments face lighter inspection schedules but heavier design-space documentation requirements.
- Contract Manufacturing:High-shear granulators and fluid-bed coaters for effervescent matrix production require validated cleaning protocols and isolator containment for potent compounds. Demand clusters among mid-sized pharmaceutical developers in Boston and San Francisco corridors lacking captive GMP infrastructure, with FDA bioequivalence study timelines extending vendor qualification cycles.
- Research & Development:Preformulation screening and prototype iteration for mucoadhesive polymers demands rapid analytical turnaround and biorelevant dissolution modeling. Sponsors in India and China are consolidating fragmented consultant networks into integrated campus-based partnerships capable of design-space documentation.
- Clinical Trials:Scintigraphic gastric-emptying validation and pharmacokinetic bridging studies for modified-release programs.
- Quality Control:In-vitro dissolution testing under physiologically relevant hydrodynamic conditions per evolving EMA expectations.
Contract Manufacturing sits at the top of the volume ranking, with Research & Development climbing the fastest.
Delivery Mode:
Cost tiers separate oral gastroretentive platforms from parenteral alternatives, with intravenous and subcutaneous formats commanding premium pricing due to sterile manufacturing overhead and specialized containment requirements.
- Oral:Buoyant, expandable, and mucoadhesive formulations employing HPMC, polycarbophil, or effervescent matrices engineered for density profiles below gastric fluid. This segment absorbs the majority of outsourcing expenditure from biotech firms pursuing 505(b)(2) pathways for reformulated assets with narrow absorption windows.
- Intravenous:Sterile manufacturing of gastric-targeted injectable depot formulations requires isolator technology and aseptic processing validation that elevates cost structures substantially above oral platforms.
- Subcutaneous:Long-acting injectable formats with gastric-retentive kinetics for narrow-therapeutic-index compounds.
- Topical:Transdermal adjuncts to oral gastroretentive regimens for localized gastric therapy.
Oral delivery commands the dominant share of contract volume, with intravenous formats expanding most quickly among oncology developers.
End User:
Customer maturity stratifies outsourcing demand, with established pharmaceutical companies prioritizing multi-regional manufacturing partners while biotechnology firms seek integrated formulation-to-commercial continuity.
- Pharmaceutical Companies:Large sponsors with global portfolios require CDMOs capable of reconciling FDA, EMA, and NMPA documentation expectations for modified-release stability protocols. These buyers consolidate vendor relationships from fragmented chains to single accountability partners with integrated quality systems.
- Biotechnology Firms:Mid-sized developers without captive manufacturing assets drive fastest adoption of tabletop fluid-bed systems and sponsor-integrated pilot facilities for rapid prototype iteration.
- Research Institutions:Academic centers conducting mechanistic studies on gastric retention mechanisms.
- Contract Research Organizations:Specialized service providers managing bioequivalence study execution for sponsor programs.
Pharmaceutical Companies anchor the largest contract value, with Biotechnology Firms gaining share fastest as 505(b)(2) program proliferation accelerates.
Product Type:
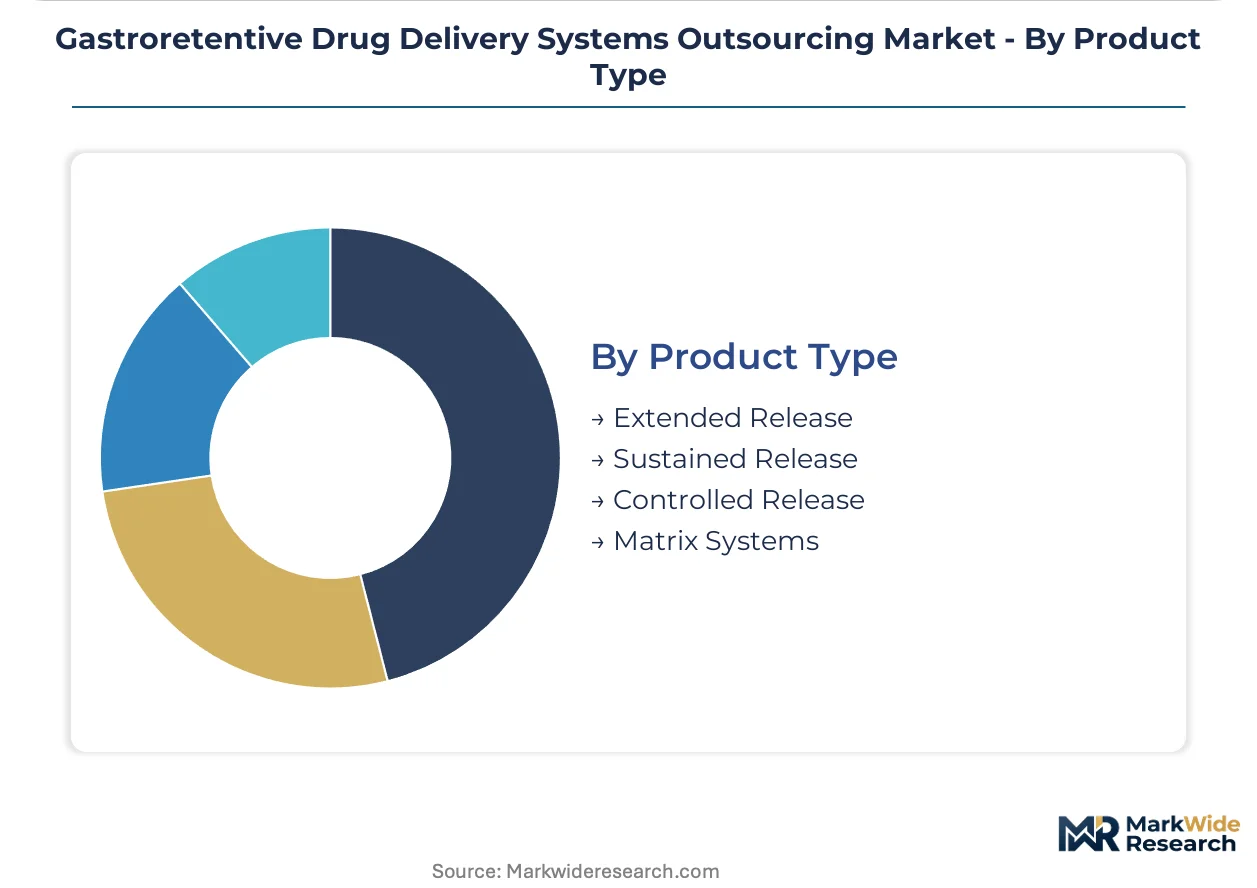
Margin structures diverge across release kinetics, with zero-order controlled release platforms capturing premium pricing for narrow-therapeutic-index compounds compared to first-order extended release alternatives.
- Extended Release:First-order release kinetics from hydrophilic matrix systems dominate commercial volume due to established manufacturing processes and broader therapeutic applicability. Hyderabad and Ahmedabad CDMOs compete aggressively on cost for standard HPMC-based formulations.
- Controlled Release:Zero-order kinetics enabling constant plasma concentrations for immunosuppressants and oncology compounds command pricing multiples above extended release formats. EMA quality-by-design mandates elevate documentation burdens for these programs.
- Sustained Release:Intermediate-duration profiles for compounds with moderate absorption window constraints.
- Matrix Systems:Structural platforms incorporating effervescent, floating, or mucoadhesive architectures.
Extended Release formulations hold the top volume position, with Controlled Release platforms recording the steepest expansion trajectory among narrow-therapeutic-index developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and process engineers cluster in established pharmaceutical corridors, with talent density determining where gastroretentive development work concentrates. CDMO site selection follows these workforce patterns, while regulatory harmonization efforts reshape which geographies qualify for multi-regional supply.
United States
FDA bioequivalence standards for modified-release dosage forms drive sponsor demand for documented gastric-retentive expertise. The agency's scintigraphic validation requirements compress qualified vendor pools. Greater Boston and San Francisco corridor developers pursue 505(b)(2) pathways, consolidating fragmented vendor chains into single accountability partnerships with integrated quality systems.
Germany
EMA quality-by-design mandates elevate documentation burdens for design-space verification. German sponsors require partners capable of delivering hydrodynamic flow pattern data mimicking human gastric motility. The Rhine-Main and Bavarian pharmaceutical clusters host formulation development campuses serving European immunosuppressant and oncology programs seeking zero-order release kinetics.
India
CDSCO GMP infrastructure upgrades and expanding technical labor pools attract international formulation development work. Hyderabad and Ahmedabad contract manufacturers compete aggressively on cost for standard HPMC-based extended release formulations. The country's national pharmaceutical regulator enforces evolving standards that determine qualification for international sponsor audits.
Switzerland
Swissmedic's alignment with PIC/S standards positions domestic CDMOs for narrow-therapeutic-index compound work. Basel and Zurich corridors concentrate containment engineering talent for potent gastroretentive programs. Specialized isolator operation expertise here outpaces training pipeline output in emerging manufacturing hubs.
Brazil
ANVISA's accelerating GMP harmonization with PIC/S standards redirects Latin American gastroretentive outsourcing demand. São Paulo and Campinas contract manufacturers capture programs previously directed to North American vendors. The country's national pharmaceutical regulator positions domestic facilities for regional supply chain consolidation.
Gastroretentive Drug Delivery Systems Outsourcing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service tiers, creating a bifurcated vendor base. Tier-one integrated players anchor multi-regional manufacturing relationships through campus-based continuity offerings. Mid-scale regional specialists capture cost-sensitive extended-release programs. Dominant competitive moves include strategic partnerships for technology access and capacity expansion in emerging manufacturing hubs.
Within the integrated full-service tier, Catalent and Lonza exemplify archetypes anchoring early-phase through commercial relationships. Adare Pharma Solutions occupies a specialist position through proprietary platform differentiation. These three represent distinct competitive vectors: integrated campus continuity, European containment expertise, and technology-enabled formulation architecture.
| Leading Market Players |
|---|
| Aenova Group |
| Patheon |
| Catalent |
| Colorcon |
| Siegfried Holding |
| Lonza |
| Quotient Sciences |
| Adare Pharma Solutions |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade hydroxypropyl methylcellulose flows from Chinese cellulose ether producers through formulation developers in India and European equipment manufacturers before reaching contract manufacturing pricing tiers for buoyant matrix gastroretentive systems. This input cost pathway concentrates pricing power upstream while compressing margins for standard extended-release formulations competing on cost.
Pricing Analysis
Bundled formulation-to-commercial service packages command premiums over fragmented vendor chains, particularly for EMA quality-by-design documentation and FDA bioequivalence study support. Three-tier pricing structure across premium, standard, and economy levels separates zero-order controlled release platforms for narrow-therapeutic-index compounds from commodity HPMC-based extended release formats. Pricing pressure stems from Hyderabad and Ahmedabad contract manufacturers competing aggressively on cost for standard formulations. Mid-sized biotech firms without captive manufacturing assets exhibit highest price sensitivity, while large pharmaceutical companies with global portfolios prioritize single accountability partnerships over unit cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for high-shear granulators and fluid-bed coaters mandate multi-supplier qualification across German, Swiss, and North American equipment vendors, limiting capacity expansion speed in emerging manufacturing hubs. Raw material dependencies center on pharmaceutical-grade HPMC from China, polycarbophil and carbomer mucoadhesive polymers from European specialty chemical producers, and effervescent matrix components from regional suppliers. Single-source vulnerability concentrates in isolator containment technology for potent compound handling. Distribution runs through campus-based integrated CDMO partnerships rather than fragmented consultant networks, with sponsors consolidating vendor relationships for design-space continuity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO GMP infrastructure upgrades and expanding technical labor pools in India attract international formulation development work at cost structures substantially below European containment engineering talent markets.
For Market Incumbents: Extend specialized isolator capacity in Basel and Zurich corridors to defend against emerging Indian CDMOs capturing standard extended-release programs. Anchor European demand through zero-order release kinetics expertise for oncology and immunosuppressant compounds. Invest in backward integration into proprietary mucoadhesive polymer platforms to differentiate from commodity formulation services.
For New Entrants and Emerging Players: Capture São Paulo and Campinas contract manufacturing demand as ANVISA GMP harmonization redirects Latin American gastroretentive outsourcing from North American vendors. Target tabletop fluid-bed system adoption among Boston and San Francisco corridor biotech firms pursuing rapid prototype iteration. Lead with sponsor-integrated pilot facility partnerships compressing early-phase outsourcing timelines.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with documented FDA bioequivalence study capabilities because qualified vendor pool compression elevates technical barriers to market entry. Platform consolidation across formulation development campuses serving 505(b)(2) pathways offers long-term viability. Watch EMA in-vitro dissolution biorelevant media adoption as signal for analytical capability investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Campus Expansion | Catalent and Lonza anchor multi-regional relationships through formulation-to-commercial continuity offerings. |
| Proprietary Technology Licensing | Adare Pharma Solutions differentiates via mucoadhesive polymer platforms and taste-masking capabilities. |
| Containment Engineering Talent Acquisition | Swiss CDMOs secure isolator operation expertise outpacing Indian and Eastern European training pipelines. |
| Regulatory Harmonization Positioning | Brazilian manufacturers capture Latin American demand through ANVISA PIC/S alignment. |
| 3D Printing Capability Integration | Fused deposition modeling decentralizes prototype development from centralized pilot plants to sponsor laboratories. |
Research Methodology
Bottom-up biotechnology firm and pharmaceutical company demand modeling reconciled against top-down CDMO capacity and regulatory filing tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, contract manufacturing procurement officers, and formulation scientists combined with secondary validation against FDA bioequivalence study documentation, EMA quality-by-design submissions, CDSCO GMP inspection records, and ClinicalTrials.gov gastroretentive program listings. Triangulation between sponsor-side demand signals and supplier-side capacity announcements ensures cross-verified outputs.
Historical trendline analysis of contract manufacturing and research & development service-type growth patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include service type, delivery mode, end user archetype, and product release kinetics. CAGRs derived from weighted capacity expansion announcements, sponsor pipeline disclosures, and regulatory approval velocity for modified-release oral dosage forms. Forecast inputs incorporate scintigraphic validation study volume trends and hydrodynamic dissolution modeling adoption rates.
Regulatory divergence across FDA, EMA, and NMPA documentation expectations, HPMC supply price volatility, and containment engineering talent scarcity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding GMP infrastructure upgrade timelines and sponsor consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Polyps Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Anal Fissure Treatment Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Gallstone Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market