
 South Korea ECG Market | 2026-2036
South Korea ECG Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea ECG Market Insights
South Korean medical device manufacturers is pivoting toward AI-enhanced diagnostic platforms to serve the country's aging demographic. GE Healthcare leverages deep learning algorithms embedded in resting ECG systems to reduce false positive rates in busy cardiology wards. Mediana Co., Ltd anchors its position through domestic manufacturing of Holter monitors tailored to Korean hospital procurement specifications. Nihon Kohden Corporation competes by sustaining a direct service network across Busan, Daegu, and Gwangju regional medical centers.
An electrocardiograph records the electrical activity of the heart through surface electrodes, typically capturing 12 leads at sampling rates exceeding 500 Hz to detect arrhythmias, ischemia, and conduction abnormalities. Portable ECG devices lead volume shipments as clinics outside Seoul prioritize point-of-care cardiac screening. ECG Patch segments capture expanding margin pools through subscription-based remote monitoring contracts with homecare agencies. Artificial Intelligence integration within cloud-based solutions represents the fastest-growing technology tier, enabling automated preliminary reads that reduce cardiologist review burdens.
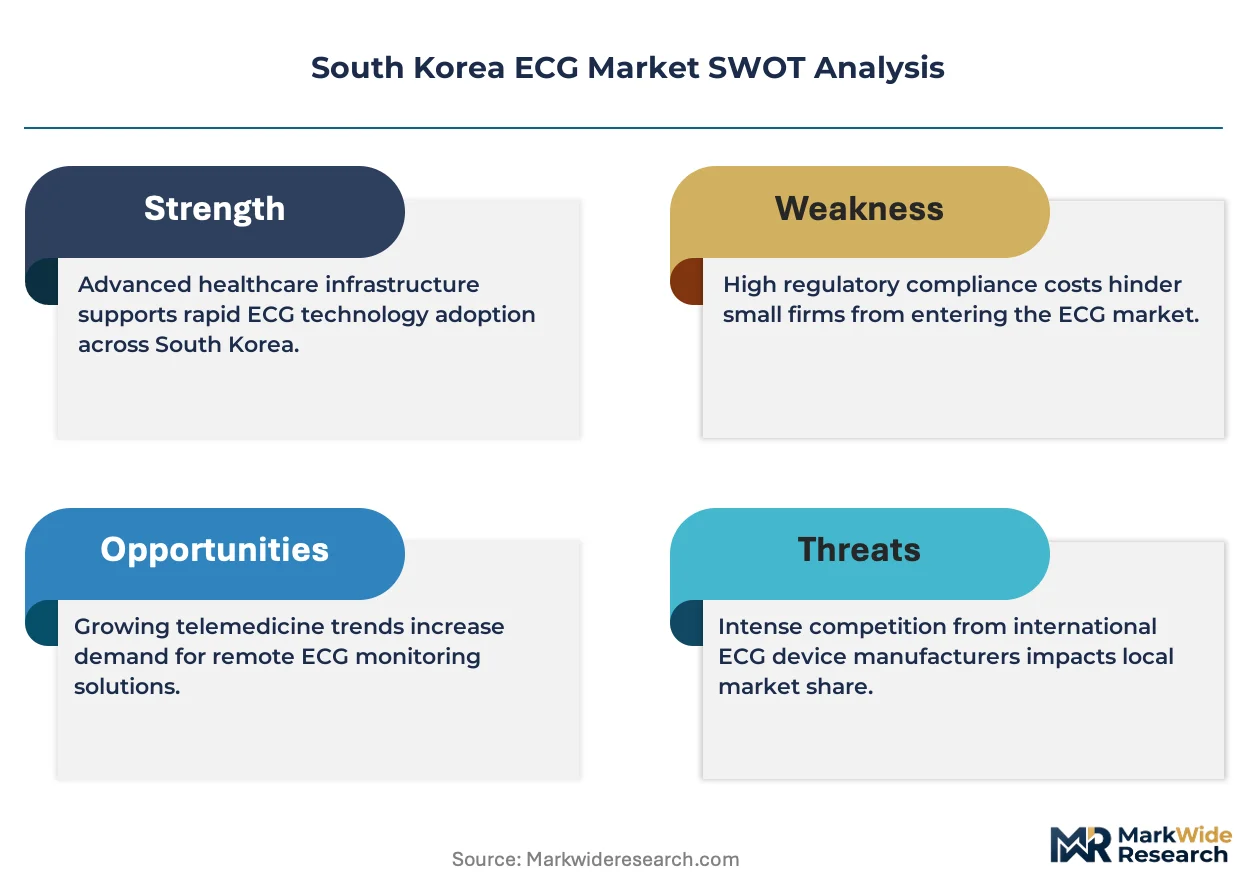
MFDS maintains stringent electrical safety and software validation standards for all ECG devices marketed domestically, while KHIDI promotes local innovation through reimbursement codes that favor domestically developed digital health technologies. The Ministry of Health and Welfare's telemedicine expansion directives directly shape demand for wireless connectivity-enabled ECG systems in rural provinces. Stakeholders must monitor how MFDS algorithm validation requirements evolve alongside AI diagnostic claims to preserve market access timelines.
Market Dynamics
AI-integrated diagnostic validation requirements from MFDS are compressing commercialization timelines for domestic manufacturers while simultaneously elevating technical barriers for foreign entrants seeking Korean market access.
Growth Catalysts
- Telemedicine Directives:Ministry of Health and Welfare expansion mandates for rural provinces are accelerating procurement of wireless-enabled ECG systems in Gangwon and Jeolla regions.
- Reimbursement Codes:KHIDI incentive structures favoring domestically developed digital health technologies are channeling R&D investment toward algorithm-native device architectures.
- Aging Demographics:South Korea's super-aged society trajectory is expanding continuous cardiac monitoring enrollment across Seoul metropolitan area integrated delivery networks.
Market Restraints
- Algorithm Validation Burden:MFDS software lifecycle documentation requirements for AI-diagnostic claims extend regulatory review cycles beyond traditional hardware-only submissions.
- Regional Supply Concentration:Critical semiconductor and sensor component sourcing remains concentrated in specific Busan-area electronics manufacturing clusters, creating geographic vulnerability.
- Substitution Pressure:Wearable photoplethysmography devices from consumer electronics manufacturers are capturing low-acuity cardiac rhythm monitoring outside institutional settings.
Strategic Opportunities
- Homecare Agency Contracts:ECG Patch subscription models with regional homecare networks in Daegu and Gwangju represent underpenetrated recurring revenue channels beyond hospital procurement.
- AI-Cloud Convergence:Integration of edge-computing diagnostics with centralized cardiologist workflow platforms enables automated preliminary read services for community clinic networks.
- Regional Medical Center Tier:Secondary hospitals in Daejeon and Ulsan lack continuous monitoring infrastructure, creating whitespace for mid-tier Holter monitor deployments.
Industry Challenges
- Cardiac Electrophysiologist Shortage:Interpretation bottlenecks in provincial hospitals limit utilization rates for acquired continuous monitoring equipment.
- Legacy System Interoperability:HIS integration complexity with decade-old hospital information systems in non-Seoul facilities delays AI-ECG deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea ECG Market |
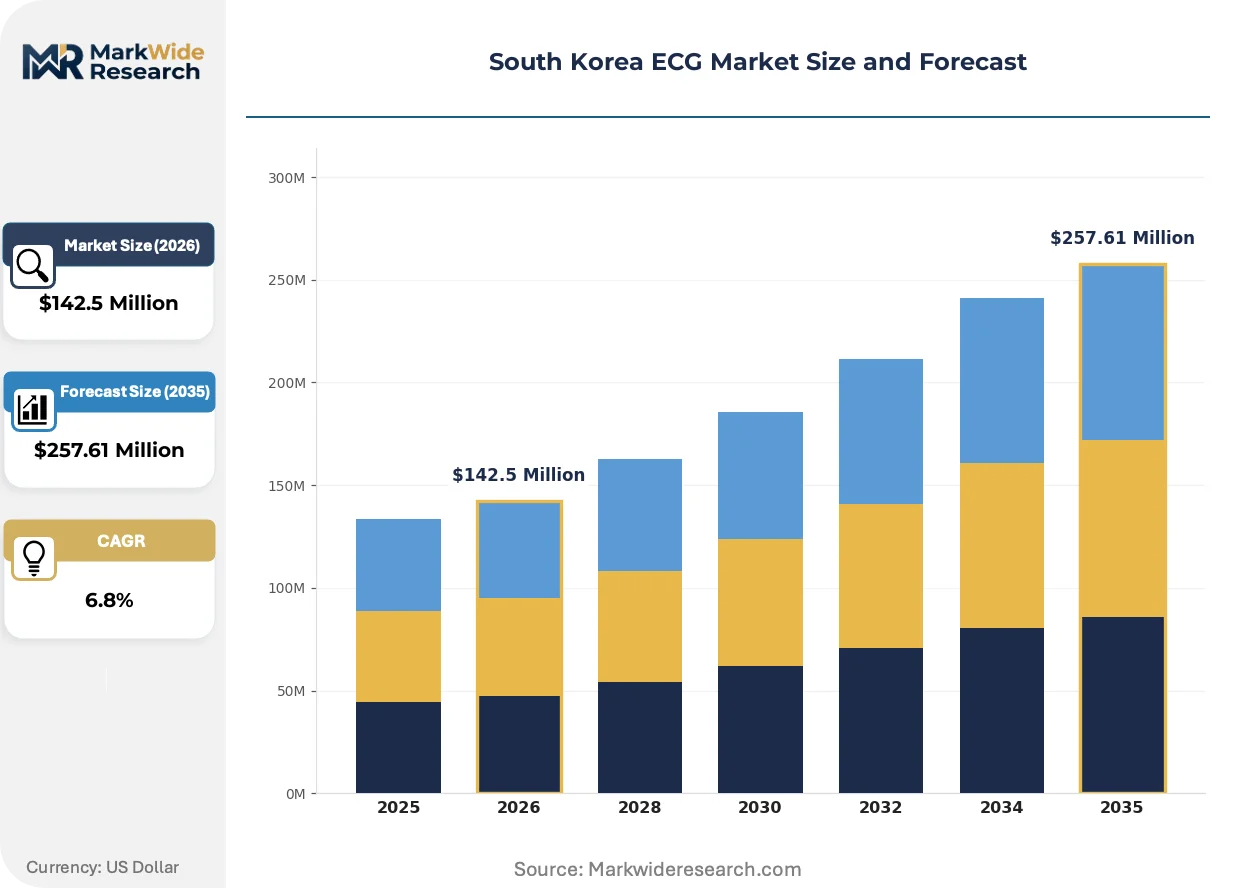
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable ECG, Holter Monitor, ECG Patch, Wearable Device Application: Cardiology, Remote Patient Monitoring, Telemedicine, Fitness Tracking End User: Hospitals, Clinics, Homecare, Research Laboratories Technology: Wireless Connectivity, Cloud-Based Solutions, Artificial Intelligence, Digital Signal Processing |
| Companies Covered | GE Healthcare, Mindray Medical International Limited, Nihon Kohden Corporation, Mediana Co., Ltd, Bionet Co., Ltd., Schiller AG, Koninklijke Philips N.V., Hill-Rom Holdings, Inc., Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea ECG Market Trends and Innovations
Deep learning inference at the point of care is compressing the traditional cardiologist review workflow, while regulatory frameworks evolve to accommodate algorithm-as-medical-device classifications.
Artificial intelligence embedded in resting ECG hardware is consolidating diagnostic responsibility from centralized reading centers toward bedside and clinic-based preliminary interpretation. Cardiology departments in tertiary Seoul hospitals are adopting these systems at accelerated procurement cycles. This consolidation is reducing dependency on off-hours cardiologist coverage while compressing time-to-diagnosis metrics for acute presentations.
MFDS algorithm change control guidelines are formalizing post-market surveillance obligations for machine-learning-based diagnostic devices marketed domestically. Manufacturers must now submit predetermined modification protocols before initial approval, locking architectural flexibility. Domestic developers are responding by modularizing algorithm components to isolate upgrade pathways within regulatory bounds.
Subscription-based remote monitoring contracts are displacing capital equipment purchases in homecare and post-acute settings. ECG Patch vendors are capturing margin pools through per-patient-month billing arrangements with regional health agencies. This shift is most visible in Gyeonggi Province integrated care pilots, where bundled payment structures favor continuous ambulatory monitoring over episodic clinic visits.
South Korea ECG Market Segmentation
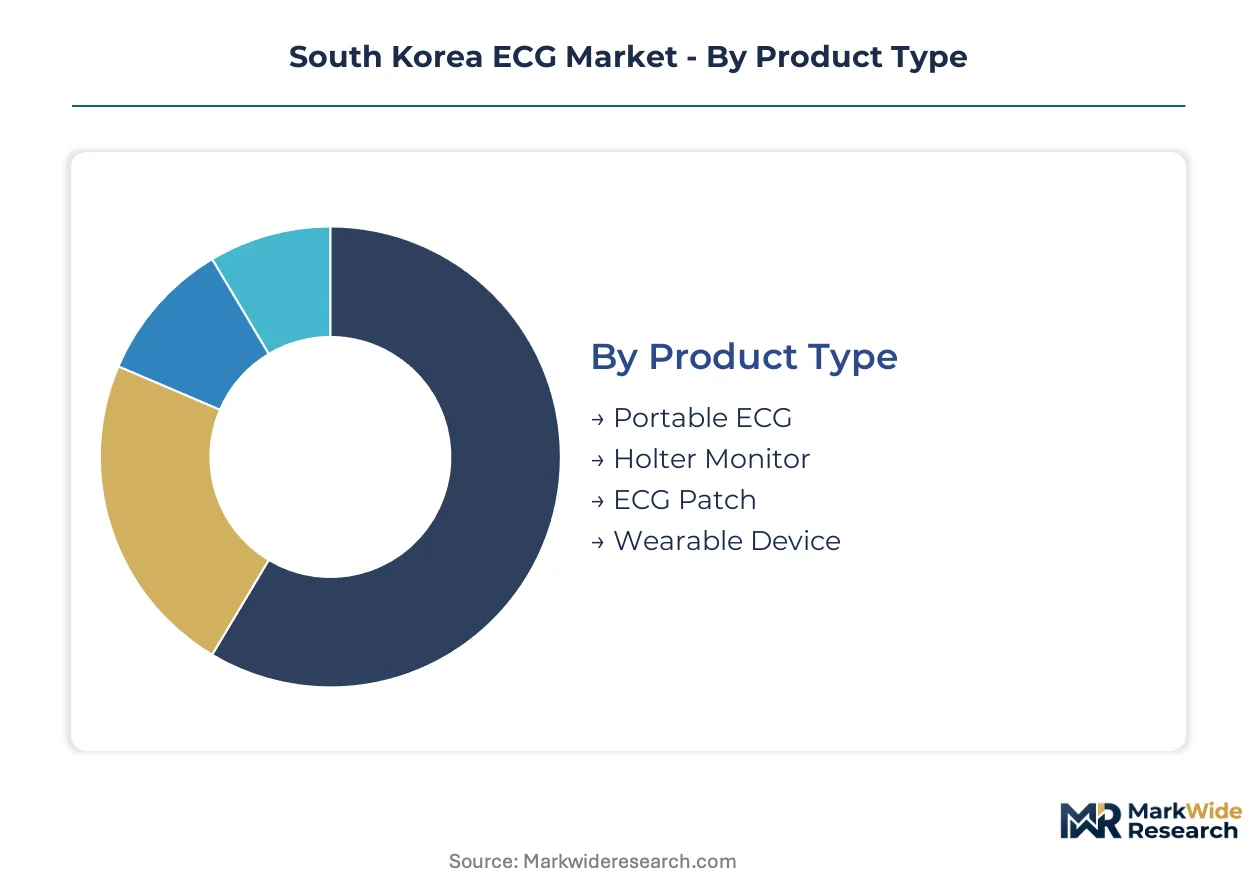
ECG device architectures in South Korea diverge sharply by capital requirements, with AI-integrated platforms demanding substantial R&D commitment while portable units prioritize manufacturing scale. Understanding these structural differences clarifies where procurement budgets concentrate across Seoul's tertiary networks versus provincial clinic tiers.
Product Type:
Capital intensity peaks in Holter monitor production lines, where multi-channel recording capabilities and extended battery architectures drive upfront tooling costs. Portable ECG and wearable categories require lower fixed investment but compete on component sourcing efficiency.
- Portable ECG:Compact 12-lead acquisition systems with integrated thermal printers dominate community clinic procurement in Gyeonggi Province. Daegu-area primary care networks prioritize these units for point-of-care arrhythmia screening where cardiologist coverage remains thin.
- Holter Monitor:Multi-day ambulatory recorders with 3-12 channel configurations anchor continuous monitoring programs at Seoul National University Hospital and Asan Medical Center. MFDS electrical safety validation requirements extend development cycles for domestic manufacturers seeking hospital procurement contracts.
- ECG Patch:Single-lead adhesive sensors with Bluetooth Low Energy transmission enable subscription-based remote monitoring models.
- Wearable Device:Consumer-grade form factors with PPG-ECG hybrid sensing face pricing pressure from Samsung and Apple ecosystem devices.
Most installed capacity flows through Holter Monitor segments. Expansion is steepest in ECG Patch categories.
Application:
Clinical utility determines reimbursement eligibility under KHIDI frameworks, with cardiology applications securing favorable fee schedules while fitness tracking sits outside insurance coverage.
- Cardiology:Diagnostic-grade 12-lead interpretation for ischemia and conduction abnormality detection remains the revenue core at Severance Hospital and Samsung Medical Center electrophysiology labs.
- Remote Patient Monitoring:Cloud-connected devices for post-discharge surveillance are gaining share fastest in Gangwon Province integrated care pilots where geographic isolation complicates follow-up access.
- Telemedicine:Real-time ECG transmission supports Ministry of Health and Welfare rural expansion mandates in Jeolla regions.
- Fitness Tracking:Wellness-oriented heart rate variability monitoring operates in direct-to-consumer channels without institutional procurement.
Cardiology captures the dominant revenue share. Remote Patient Monitoring is climbing the fastest as bundled payment structures mature.
End User:
Customer sophistication shapes device specification requirements, with hospitals demanding EMR integration and homecare agencies prioritizing patient adherence features over clinical depth.
- Hospitals:Tertiary centers in Seoul require FDA-equivalent or MFDS Class III certification with HIS interoperability for Cath lab and emergency department deployment.
- Clinics:Secondary facilities in Daejeon and Ulsan favor mid-tier Holter systems with simplified interpretation software to compensate for electrophysiologist shortages.
- Homecare:Regional agencies in Gwangju are piloting ECG Patch subscription models under per-patient-month billing arrangements.
- Research Laboratories:Academic medical centers deploy high-sampling-rate systems for arrhythmia mechanism studies with less emphasis on regulatory clearance speed.
Hospitals maintain the deepest installed base. Homecare is expanding most quickly through bundled payment pilots.
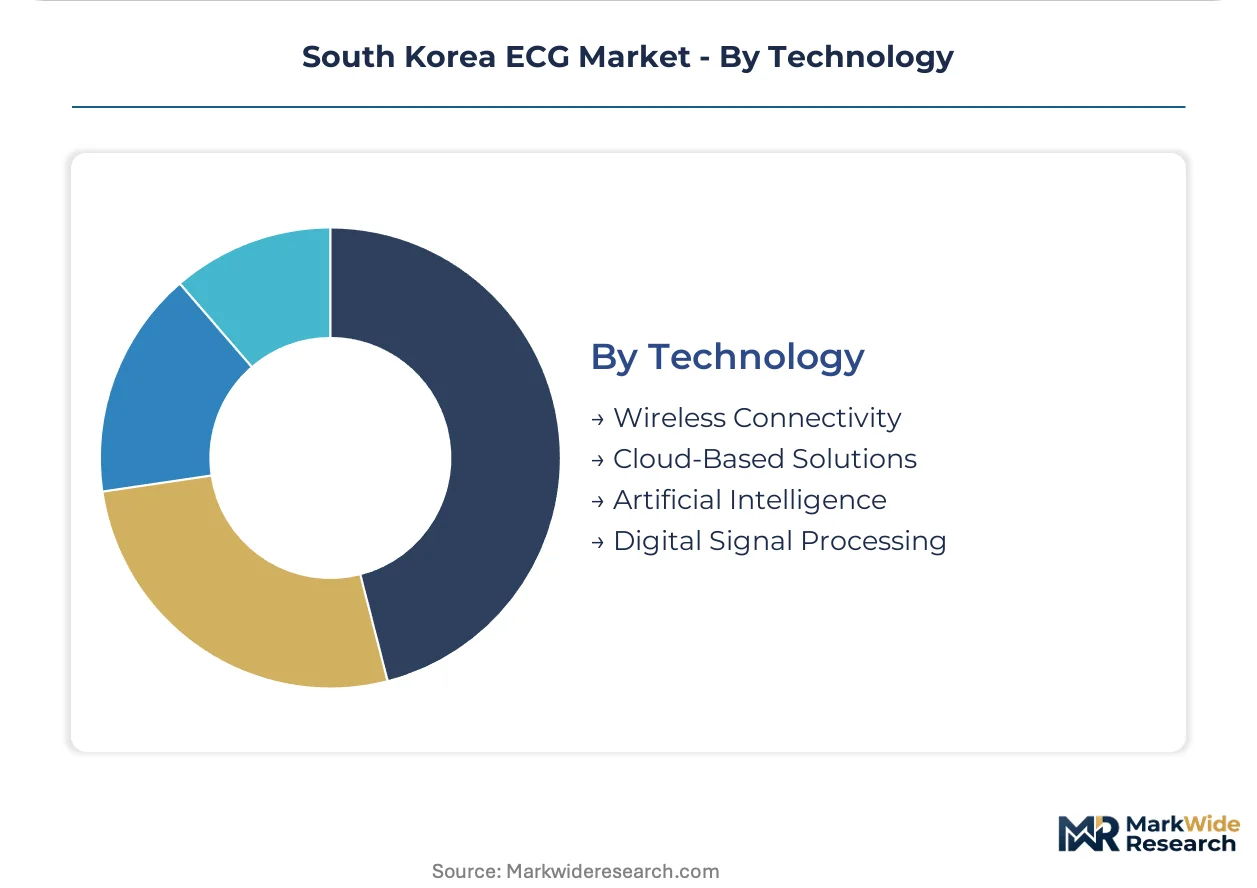
Technology:
Software validation burdens from MFDS algorithm change control guidelines concentrate investment in modular AI architectures that isolate upgrade pathways.
- Wireless Connectivity:Bluetooth 5.0 and LTE-M modules enable real-time transmission for telemedicine deployments in rural Gangwon clinics beyond fiber infrastructure reach.
- Cloud-Based Solutions:Centralized storage with automated preliminary read algorithms reduces cardiologist review burden at Seoul metropolitan area integrated delivery networks.
- Artificial Intelligence:Deep learning inference for arrhythmia classification requires extensive training dataset documentation under MFDS software lifecycle requirements.
- Digital Signal Processing:Noise reduction firmware for motion artifact suppression supports ambulatory recording quality in active patient populations.
Wireless Connectivity underpins the broadest installed footprint. Artificial Intelligence is gaining share fastest as regulatory frameworks formalize algorithm-as-device classifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's ECG market concentration diverges from Japan's distributed prefecture model, with procurement gravity pulling toward Seoul's integrated delivery networks rather than dispersing across regional medical centers.
Seoul Capital Area
Samsung Medical Center and Severance Hospital anchor diagnostic-grade ECG procurement, with AI-integrated platforms commanding premium placement in electrophysiology labs. MFDS Class III certification requirements shape vendor selection criteria. Bundled payment pilots in Gyeonggi Province satellite cities accelerate ECG Patch subscription adoption among homecare agencies.
Busan-Ulsan
Regional medical centers in Busan prioritize mid-tier Holter monitors to compensate for electrophysiologist shortages. The Ministry of Health and Welfare's telemedicine directives extend connectivity infrastructure to Ulsan coastal clinics. Daewoo Electronics manufacturing clusters supply sensor components to domestic device assemblers.
Daegu-Gyeongbuk
Primary care networks in Daegu favor portable ECG units for point-of-care arrhythmia screening where specialist coverage remains thin. KHIDI reimbursement codes channel investment toward domestically developed digital health platforms. Kyungpook National University Hospital serves as a validation site for algorithm-native device architectures.
Daejeon-Sejong
Secondary hospitals in this central corridor lack continuous monitoring infrastructure, creating whitespace for mid-tier deployments. The Korea Institute of Science and Technology anchors AI diagnostic research partnerships with device manufacturers. Sejong administrative city procurement favors wireless-enabled systems for rural outreach programs.
Gwangju-Honam
Regional homecare agencies in Gwangju pilot ECG Patch subscription models under per-patient-month billing arrangements. Geographic isolation in Jeolla provinces drives Ministry of Health and Welfare investment in real-time transmission capabilities. Chonnam National University Hospital validates cloud-based preliminary read algorithms for community clinic networks.
South Korea ECG Market Competitive Landscape
Domestic producers anchor the mid-tier equipment segment; multinational specialists hold premium diagnostic positions through direct service networks. Market structure tilts toward consolidation in AI-integrated platforms while fragmenting across portable device categories. Three archetypes dominate: algorithm-native developers, manufacturing-scale fabricators, and service-integrated multinationals. Capacity expansion in domestic production lines and strategic partnerships for cloud infrastructure represent the dominant competitive vectors.
Among multinational service-integrated specialists, GE Healthcare and Nihon Kohden Corporation exemplify the premium-tier positioning through sustained direct presence across regional medical centers. Mediana Co., Ltd occupies a distinctive anchor position as a domestic manufacturing-scale fabricator aligned with Korean hospital procurement specifications. These three entities represent the structural poles around which competitive dynamics organize: foreign technology leadership, regional service density, and domestic manufacturing compliance.
| Leading Market Players |
|---|
| GE Healthcare |
| Mindray Medical International Limited |
| Nihon Kohden Corporation |
| Mediana Co., Ltd |
| Bionet Co., Ltd. |
| Schiller AG |
| Koninklijke Philips N.V. |
| Hill-Rom Holdings, Inc. |
| Medtronic PLC |
| Others |
Pricing and Supply Chain Analysis
MFDS algorithm validation requirements for AI-integrated diagnostic claims are compressing procurement timelines at Seoul's tertiary hospitals, forcing manufacturers to absorb upfront software documentation costs that elevate entry-tier pricing while squeezing margins on legacy hardware-only devices.
Pricing Analysis
Direct-to-hospital procurement discounts dominate the channel structure, with distributor margins compressed to single-digit percentages for AI-integrated platforms while portable ECG units retain broader retail markups. Pricing stratifies across premium, standard, and economy tiers based on MFDS certification class and after-sales service bundling. Cost compression in the portable segment is intensifying because Samsung and Apple ecosystem devices are capturing low-acuity monitoring outside institutional settings. Community clinics in Daegu and Gwangju exhibit the highest price sensitivity, whereas Seoul's integrated delivery networks prioritize algorithm performance over unit cost.
Supply Chain Analysis
Semiconductor component sourcing rests on South Korean and Taiwanese foundry capacity, with analog front-end chips for ECG signal acquisition drawing from Japanese specialty producers in Tokyo and Osaka. Critical dependencies include medical-grade electrodes, lithium-polymer batteries, and Bluetooth Low Energy modules. Single-source vulnerability concentrates in Busan-area sensor manufacturing clusters exposed to regional logistics disruptions. Distribution runs through GPO contracts at tertiary hospitals and regional medical center procurement consortia in Daegu and Daejeon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's ECG market functions as a geographic-arbitrage opportunity where MFDS algorithm validation requirements create steeper technical barriers than FDA-equivalent pathways, favoring domestic developers with established regulatory relationships over foreign entrants facing extended review cycles.
For Market Incumbents: Anticipate substitution pressure from consumer-grade PPG wearables by modularizing AI architectures to isolate upgrade pathways within MFDS change control guidelines. Deepen backward integration into electrode and sensor component production to defend margin position against Busan-area supply concentration risks. Prioritize certification investment for Class III diagnostic claims that lock out mid-tier competitors from Seoul's tertiary hospital procurement. For New Entrants and Emerging Players: Cloud-based preliminary read services for community clinic networks offer the most penetrable white-space target, with Daejeon and Ulsan secondary hospitals lacking continuous monitoring infrastructure and electrophysiologist coverage. Subscription-based ECG Patch contracts with Gwangju homecare agencies represent a second entry vector under per-patient-month billing pilots. A direct-to-clinic digital sales channel bypasses GPO consolidation at tertiary centers. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-native developers possessing modular AI architectures and established MFDS relationships, positioned to capture share as software-as-device classifications formalize. Long-term viability hinges on recurring revenue models displacing capital equipment purchases across the projection horizon. Watch KHIDI reimbursement code revisions favoring domestically developed digital health technologies as the inflection signal for portfolio rebalancing toward Korean-anchored platforms.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Algorithm Validation Investment | Accelerates market access timelines for AI-integrated diagnostic platforms against foreign competitors. |
| Cloud Infrastructure Partnership | Enables automated preliminary read services that reduce cardiologist review burdens at Seoul metropolitan networks. |
| Electrode Component Backward Integration | Reduces exposure to Busan-area manufacturing cluster disruptions and stabilizes input cost structures. |
| Homecare Agency Subscription Model | Captures recurring revenue pools in Gwangju and Gyeonggi Province bundled payment pilots. |
| Regional Medical Center Tier Expansion | Addresses whitespace in Daejeon and Ulsan secondary hospitals lacking continuous monitoring infrastructure. |
Research Methodology
Bottom-up hospital and clinic procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and MFDS regulatory affairs specialists were validated against secondary sources including MFDS device registration databases, KHIDI reimbursement code filings, and hospital procurement records from Seoul National University Hospital and Asan Medical Center. Trade data from Korean customs authorities and medical device distributor financial disclosures provided cross-referencing anchors.
Historical trendline analysis of ECG device installations across Seoul metropolitan area integrated delivery networks established baseline penetration rates. The projection framework segments by product architecture, clinical application, end-user sophistication, and technology integration level, with CAGRs derived from regression analysis against aging demographic trajectories and telemedicine directive implementation timelines. Forecast inputs incorporate MFDS algorithm change control guideline evolution and KHIDI digital health incentive structure adjustments.
The model assumes a particular technology adoption path; alternative pathways for wearable photoplethysmography displacement of low-acuity ECG monitoring would alter the outlook. Forecasts reflect assumptions about MFDS validation timeline stability and semiconductor supply chain continuity. Regulatory restriction tightening on AI-diagnostic claims and electrophysiologist workforce expansion rates constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Connectivity Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Brachytherapy Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
T-Piece Resuscitator Market
Medical Devices
Midline Catheters Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
US Stethoscope Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Neuroprosthetics Market