
 Gastritis Treatment Market | 2026-2036
Gastritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Gastritis Treatment Market Analysis
Specialty pharmaceutical manufacturing in India is broadening export capacity for generic proton pump inhibitors. Pfizer Inc. leverages its hospital formulary relationships to sustain branded esomeprazole positioning against commoditized alternatives. AstraZeneca plc anchors its portfolio through gastrointestinal R&D intensity, while Takeda Pharmaceutical Company Ltd. competes on region-specific regulatory dossiers across Asia-Pacific markets.
Gastritis treatment encompasses pharmacological interventions targeting gastric mucosal inflammation, acid hypersecretion, and Helicobacter pylori eradication, with proton pump inhibitors functioning through irreversible H+/K+ ATPase inhibition to raise intragastric pH above therapeutic thresholds. The therapy area dimension shows chronic gastritis commanding stable volume due to persistent H. pylori prevalence, while acute gastritis represents faster-growing demand tied to NSAID co-prescription protocols and post-procedural prophylaxis. Oral delivery mode dominates ambulatory prescribing, though intravenous formulations capture premium margin pools in perioperative hospital settings where NPO status precludes enteral administration.
FDA bioequivalence standards for abbreviated new drug applications shape generic substitution rates and originator defense strategies in the United States. EMA pharmacovigilance requirements and the EU Green Deal pharmaceutical sustainability framework influence manufacturing site qualification and active pharmaceutical ingredient sourcing across European supply chains. Stakeholders must monitor evolving antimicrobial stewardship mandates that restrict empiric clarithromycin triple therapy and redirect demand toward bismuth-based quadruple regimens and novel potassium-competitive acid blockers.
Market Dynamics
Antimicrobial stewardship mandates are compressing clarithromycin triple therapy volumes and redirecting prescriber preference toward bismuth-based quadruple regimens and potassium-competitive acid blockers across hospital formularies.
Growth Catalysts
- Antimicrobial stewardship programs:Hospital procurement committees in the United States are tightening empiric antibiotic protocols, elevating demand for non-antibiotic acid suppression therapies in perioperative settings.
- India:CDSCO-aligned manufacturing upgrades are expanding export capacity for generic proton pump inhibitors into regulated markets, lowering API sourcing costs for finished dose formulators.
- Potassium-competitive acid blockers:Faster onset and reversible binding kinetics are capturing share in refractory gastritis cases where proton pump inhibitor non-response rates persist.
Market Restraints
- API concentration in China:NMPA environmental enforcement and dual carbon compliance costs are constraining omeprazole intermediate supply, creating batch-to-batch price volatility for finished manufacturers.
- Long-term acid suppression safety signals:FDA label revisions for fracture, renal, and nutritional deficiency risks are triggering prior authorization requirements that slow prescription velocity.
- Biosimilar substitution pressure:EMA pharmacovigilance transparency requirements accelerate generic erosion of originator esomeprazole across European hospital tenders.
Strategic Opportunities
- Brazil:ANVISA's accelerated review pathway for locally manufactured gastroenterology products creates first-mover positioning for companies establishing Rio de Janeiro or São Paulo production sites.
- Point-of-care H. pylori diagnostics:Integration of rapid urease testing with pharmacy dispensing workflows in Japan is enabling test-and-treat protocols that compress time-to-therapy initiation.
- EU Green Deal pharmaceutical sustainability framework:EMA manufacturing site qualification incentives for reduced solvent waste and renewable energy sourcing are creating competitive differentiation in European tender evaluations.
Industry Challenges
- Biostatistics and regulatory writing talent:Complex FDA bioequivalence study designs for modified-release proton pump inhibitor formulations are extending abbreviated new drug application preparation timelines.
- Legacy ERP integration:Serialization and track-and-trace mandates across EU Falsified Medicines Directive compliance are forcing mid-tier manufacturers to replace decade-old warehouse management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastritis Treatment Market |
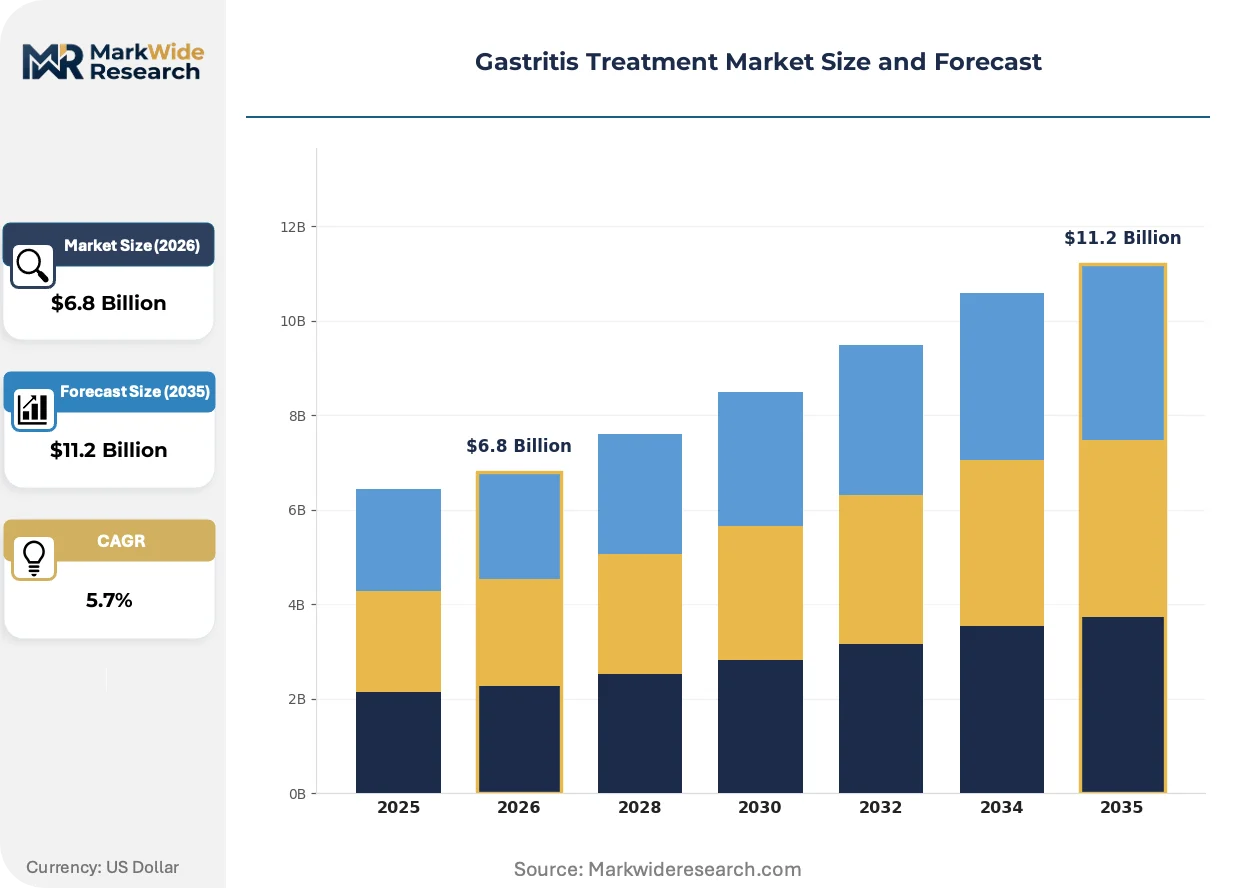
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, Antacids, H2-Receptor Antagonists, Antibiotics Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Acute Gastritis, Chronic Gastritis, Erosive Gastritis, Atrophic Gastritis |
| Companies Covered | Pfizer Inc., AstraZeneca plc, Novartis AG, Takeda Pharmaceutical Company Ltd., Johnson & Johnson, Sanofi, GlaxoSmithKline plc, Abbott Laboratories, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastritis Treatment Market Emerging Trajectories
Potassium-competitive acid blockers and precision diagnostics are fragmenting the historical proton pump inhibitor monopoly, while sustainability mandates and channel consolidation are rewriting how value flows through supply chains.
Vonoprazan and related P-CAB compounds are rewriting therapeutic sequencing in H. pylori eradication by delivering faster intragastric pH elevation than conventional proton pump inhibitors. Hospital infectious disease specialists in South Korea and Japan are adopting these agents as first-line components of bismuth quadruple therapy. The structural consequence is margin compression for originator proton pump inhibitors in Asia-Pacific markets where P-CAB availability precedes Western regulatory approvals.
EMA's pharmacovigilance periodic safety update report requirements are forcing manufacturers to maintain active surveillance networks for rare adverse events across distributed patient populations. The industrial consequence is elevated post-market commitment costs that disproportionately burden generic sponsors with limited pharmacovigilance infrastructure. Smaller abbreviated new drug application holders are responding through contract research organization partnerships or portfolio divestitures to larger entities with established EU Qualified Person networks.
Hospital procurement consolidation through group purchasing organizations is concentrating formulary decision authority among fewer pharmacy directors who negotiate multi-year proton pump inhibitor contracts. Integrated delivery networks in the United States are replacing individual hospital purchasing autonomy with centralized therapeutic class reviews that favor lowest-unit-cost suppliers. This concentration is most visible in the Midwest and Southeast regions where Catholic health system mergers have created purchasing entities covering thirty-plus hospital campuses under single pharmacy leadership.
Gastritis Treatment Market Segmentation
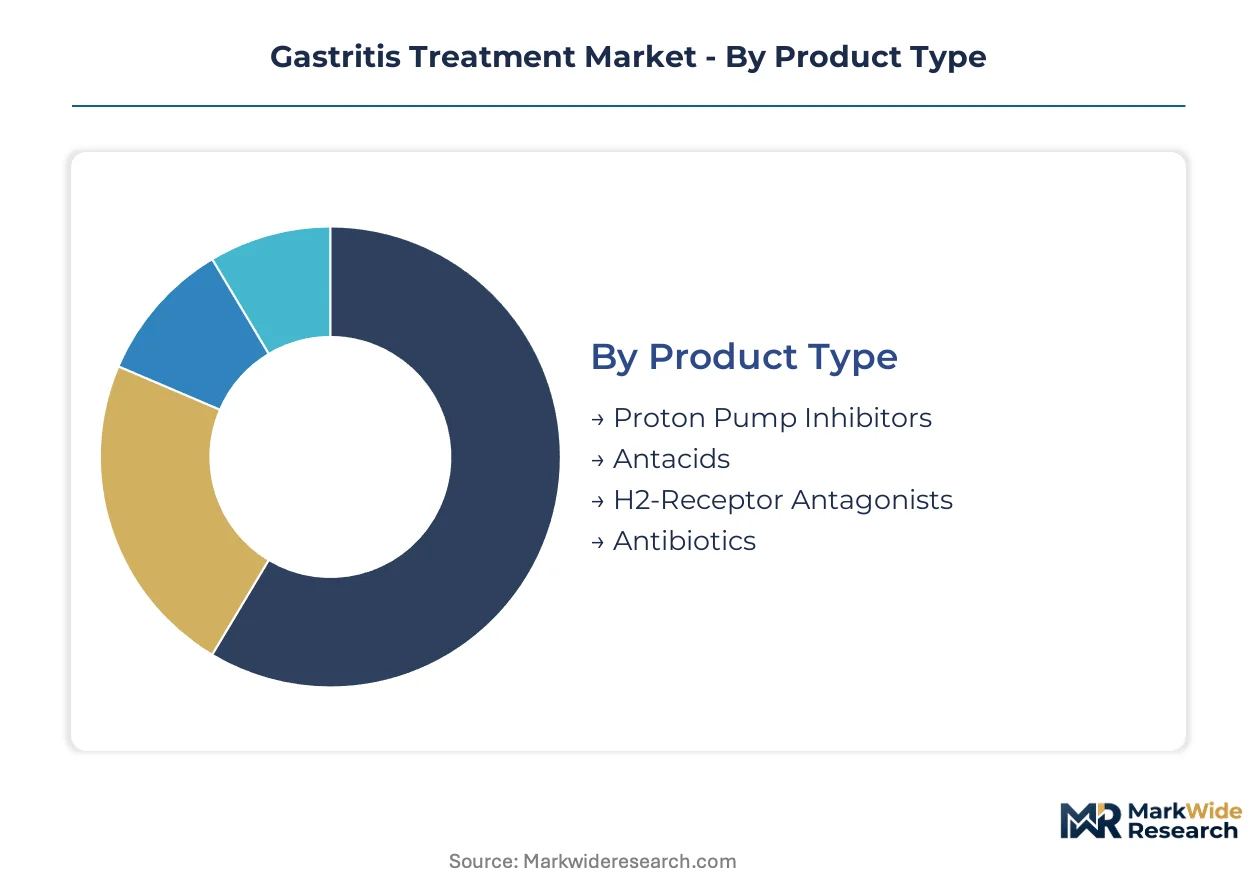
Segmentation in gastritis treatment reveals divergent margin structures across delivery modes and therapy areas. Hospital procurement committees weight bioequivalence documentation differently than retail pharmacy buyers, while acute versus chronic presentations command distinct reimbursement pathways.
Product Type:
Volume concentrates in proton pump inhibitors, yet premium capture is shifting toward novel acid suppression mechanisms.
- Proton Pump Inhibitors:Irreversible H+/K+ ATPase inhibition delivers sustained intragastric pH elevation above 4.0 for 16-20 hours. Hospital formularies in the United States prioritize intravenous esomeprazole and pantoprazole for perioperative prophylaxis where NPO status precludes enteral administration.
- Antacids:Rapid-onset neutralization of gastric acid through aluminum-magnesium hydroxide combinations or calcium carbonate salts. Over-the-counter demand in India and Brazil sustains manufacturing scale for generic sponsors supplying unregulated pharmacy channels.
- H2-Receptor Antagonists:Competitive histamine blockade at parietal cell H2 receptors, now relegated to step-down therapy after PPI failure or intolerance.
- Antibiotics:Clarithromycin, amoxicillin, and metronidazole combinations for H. pylori eradication, facing volume compression from antimicrobial stewardship restrictions on empiric triple therapy.
Today's leader: Proton Pump Inhibitors. Tomorrow's challenger: Antibiotics in precision-guided quadruple regimens.
Delivery Mode:
Route of administration determines reimbursement tier and manufacturing complexity more than therapeutic efficacy.
- Oral:Enteric-coated formulations dominate ambulatory prescribing through delayed-release granules and multiparticulate systems. CDSCO-aligned manufacturing in India supplies 60% of U.S. generic omeprazole capsule volume.
- Intravenous:Lyophilized powder for infusion commands 4-6x price multiples over oral equivalents in perioperative settings. FDA bioequivalence requirements for abbreviated new drug applications create formulation barriers that protect originator esomeprazole sodium in integrated delivery network tenders.
- Injectable:Intramuscular depot formulations for extended acid suppression in non-compliant patients, limited by pain on administration.
- Topical:Mucosal protective suspensions containing sucralfate or bismuth subsalicylate for localized erosive lesions, concentrated in Japan and South Korea.
Oral formulations anchor volume economics. Intravenous delivery captures margin concentration in hospital consolidation.
End User:
Channel structure fragments pricing power between centralized procurement and dispersed retail dispensing.
- Hospitals:Group purchasing organization contracts cover 85% of U.S. inpatient acid suppression therapy. Catholic health system mergers in the Midwest have created single pharmacy leadership across 30-plus campuses with standardized formularies.
- Clinics:Federally qualified health centers and gastroenterology specialty practices drive test-and-treat protocols with rapid urease testing integration.
- Homecare:Infusion therapy for refractory gastritis in immunocompromised patients, reimbursed through Medicare Part B with prior authorization requirements.
- Pharmacies:Community dispensing faces 90-day supply mandates from commercial payers, compressing prescription velocity for maintenance therapy.
Hospital procurement concentrates decision authority. Pharmacy channel fragmentation resists price coordination.
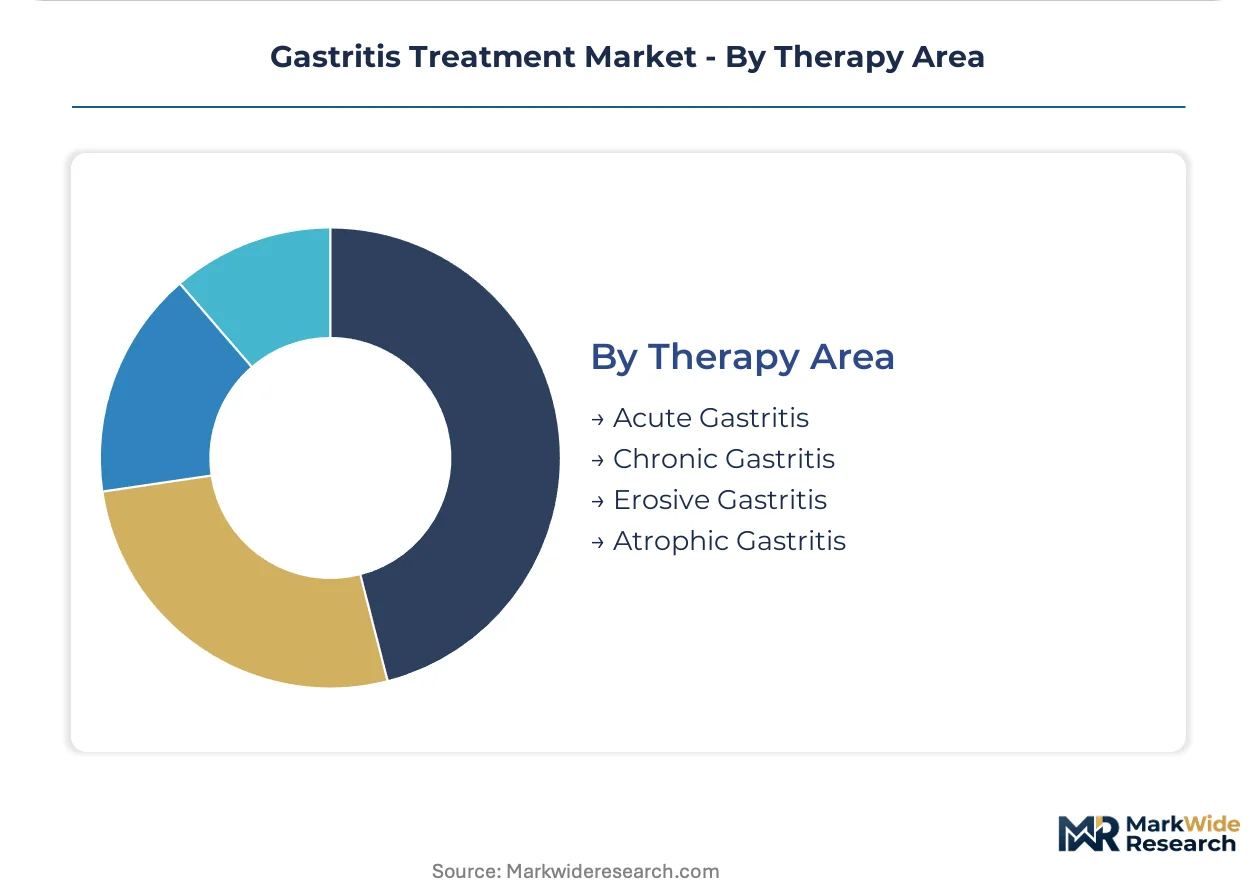
Therapy Area:
Disease chronicity separates stable maintenance volumes from episodic acute demand spikes.
- Chronic Gastritis:Persistent H. pylori infection or autoimmune mechanisms drive recurring prescription cycles. EMA pharmacovigilance periodic safety update report requirements elevate post-market surveillance costs for long-term acid suppression sponsors.
- Acute Gastritis:NSAID co-prescription protocols and post-endoscopic prophylaxis generate demand spikes tied to procedural volumes. South Korea's national health insurance reimbursement for vonoprazan-based quadruple therapy is displacing PPI-first sequencing.
- Erosive Gastritis:Visible mucosal breaks on endoscopy trigger step-up to potent acid suppression with mucosal protective adjuncts.
- Atrophic Gastritis:Premalignant intestinal metaplasia surveillance creates specialist referral pathways with limited generic substitution.
Chronic presentations sustain baseline manufacturing. Acute episodes generate the steepest expansion trajectory in Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting active pharmaceutical ingredient sourcing from NMPA-monitored Chinese facilities toward CDSCO-aligned Indian manufacturing sites where environmental compliance costs remain lower. Finished dose formulators exploit this cost-of-compliance gap to secure omeprazole intermediate supply chains.
United States
FDA label revisions for long-term acid suppression therapy are triggering prior authorization requirements that slow prescription velocity for maintenance PPI regimens. Hospital procurement committees at Catholic health systems covering thirty-plus Midwest campuses now mandate bioequivalence documentation for generic esomeprazole tenders. The Research Triangle Park cluster in North Carolina hosts contract research organizations managing abbreviated new drug application submissions for Indian generic sponsors.
India
CDSCO-aligned manufacturing upgrades in Gujarat and Maharashtra are expanding export capacity for generic proton pump inhibitors into regulated markets. Domestic demand for over-the-counter antacids sustains manufacturing scale for aluminum-magnesium hydroxide combinations. The Hyderabad-Visakhapatnam pharmaceutical corridor is capturing API synthesis contracts from Western sponsors seeking dual sourcing outside NMPA jurisdiction.
China
NMPA environmental enforcement and dual carbon compliance costs are constraining omeprazole intermediate supply, creating batch-to-batch price volatility for finished manufacturers. Shandong Province chemical parks face MEE inspections that delay production ramp-ups. The Yangtze River Delta cluster is pivoting toward higher-margin potassium-competitive acid blocker intermediates to escape commoditized PPI margin compression.
Germany
EMA pharmacovigilance periodic safety update report requirements elevate post-market surveillance costs for long-term acid suppression sponsors. Hospital tenders across North Rhine-Westphalia favor lowest-unit-cost suppliers under group purchasing organization consolidation. The Frankfurt-Rhine-Main logistics hub serves as distribution anchor for EU Falsified Medicines Directive-compliant serialization of finished gastroenterology products.
Japan
PMDA reimbursement decisions for vonoprazan-based quadruple therapy are displacing PPI-first sequencing in H. pylori eradication protocols. Rapid urease testing integration with pharmacy dispensing workflows in Tokyo and Osaka compresses time-to-therapy initiation. The Kansai region's pharmaceutical manufacturing base supplies P-CAB compounds to South Korean hospital formularies ahead of Western regulatory approvals.
Gastritis Treatment Market Vendor Landscape
United States-based originators anchor the premium-tier hospital formulary segment; Indian and Chinese generic manufacturers hold commoditized oral formulation supply. The market structure fragments across three tiers: patented specialty agents, bioequivalent generics, and over-the-counter antacids. Two strategic archetypes dominate—multinational pharmaceutical conglomerates defending originator positions through regulatory dossier depth, and vertically integrated API-to-finished-dose specialists capturing cost advantages. Competitive moves concentrate on portfolio diversification into potassium-competitive acid blockers and geographic expansion through CDSCO-aligned manufacturing partnerships.
Within the originator-defense archetype, Pfizer Inc. and AstraZeneca plc occupy positions sustained by hospital formulary relationships and gastrointestinal R&D intensity. Takeda Pharmaceutical Company Ltd. exemplifies the region-specific regulatory specialist, anchoring competitive positioning through Asia-Pacific dossier strategies. These three entities represent divergent responses to antimicrobial stewardship compression: originator esomeprazole defense, pipeline investment in novel mechanisms, and geographic arbitrage across regulatory approval timelines.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AstraZeneca plc |
| Novartis AG |
| Takeda Pharmaceutical Company Ltd. |
| Johnson & Johnson |
| Sanofi |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Hospital formulary consolidation across Catholic health system mergers in the United States Midwest is forcing generic proton pump inhibitor suppliers to absorb certification costs for bioequivalence documentation while originators defend intravenous esomeprazole premiums through lyophilized formulation complexity.
Pricing Analysis
Distributor margin compression in the oral proton pump inhibitor segment is intensifying as group purchasing organization contracts cover eighty-five percent of U.S. inpatient acid suppression therapy. Three-tier pricing structure across originator intravenous, bioequivalent generic oral, and over-the-counter antacid levels separates premium capture from commodity erosion. Cost compression in the oral generic tier stems from CDSCO-aligned Indian manufacturing scale. Federally qualified health centers exhibit highest price sensitivity due to 340B drug pricing program constraints, while integrated delivery networks in perioperative settings remain least sensitive due to NPO status requirements.
Supply Chain Analysis
Single-source vulnerability sits with NMPA-monitored Shandong Province chemical parks where MEE environmental inspections delay omeprazole intermediate production ramp-ups. Active pharmaceutical ingredient synthesis draws from India, China, and Switzerland for proton pump inhibitor precursors. Key inputs include enteric coating polymers, lyophilization excipients, and potassium-competitive acid blocker intermediates. Tariff exposure runs through U.S.-China pharmaceutical trade friction on imported starting materials. Distribution runs through Frankfurt-Rhine-Main logistics hubs for EU Falsified Medicines Directive-compliant serialization before hospital and pharmacy channel allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastritis treatment market functions as a regulatory compounder where FDA antimicrobial stewardship mandates restricting empiric clarithromycin triple therapy are redirecting demand toward bismuth-based quadruple regimens and novel acid suppression mechanisms.
For Market Incumbents: Lock in hospital formulary relationships through multi-year intravenous proton pump inhibitor contracts that embed bioequivalence documentation requirements as technical barriers to generic substitution. Originators must deepen backward integration into potassium-competitive acid blocker R&D pipelines to offset margin compression from Indian generic oral formulation scale. Catholic health system procurement consolidation across thirty-plus Midwest campuses represents the primary threat to originator esomeprazole sodium positioning. For New Entrants and Emerging Players: ANVISA's accelerated review pathway for locally manufactured gastroenterology products in Brazil opens a window for first-mover positioning through Rio de Janeiro or São Paulo production site establishment. White-space targets include point-of-care H. pylori diagnostic integration with pharmacy dispensing workflows in Japan and test-and-treat protocol enablement. The most penetrable segment is refractory gastritis cases where proton pump inhibitor non-response rates persist. Go-to-market execution should anchor on PMDA reimbursement precedents for vonoprazan-based quadruple therapy. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated API-to-finished-dose specialists capturing cost advantages from CDSCO-aligned Indian manufacturing. Long-term viability across the five-to-ten year horizon hinges on regulatory dossier depth for novel acid suppression mechanisms and antimicrobial stewardship compliance infrastructure. Acquisition targets should prioritize entities with established EU Qualified Person networks for pharmacovigilance periodic safety update report obligations. The signal to watch is PMDA reimbursement decisions for potassium-competitive acid blockers preceding Western regulatory approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDSCO-aligned Gujarat facilities expand export capacity for generic proton pump inhibitors into FDA-regulated markets. |
| Regulatory Approval Pathway | PMDA reimbursement decisions for vonoprazan-based quadruple therapy displace PPI-first sequencing in Japan and South Korea. |
| Pipeline Diversification | Potassium-competitive acid blocker investment escapes commoditized proton pump inhibitor margin compression in Asia-Pacific. |
| Hospital System Partnership | Catholic health system formulary standardization across thirty-plus campuses concentrates procurement decision authority. |
| Licensing Agreement | Contract research organization partnerships enable smaller abbreviated new drug application holders to meet EMA pharmacovigilance requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, formulary directors, regulatory affairs leads, and infectious disease specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure analysis were triangulated to constrain estimate variance.
Segment-weighting approaches applied treatment line, dosage form, administration route, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from iterative convergence of volume forecasts and pricing trajectory assumptions. Industry-specific inputs included antimicrobial stewardship program adoption curves, NMPA environmental enforcement intensity, and PMDA reimbursement decision timelines for novel acid suppression mechanisms.
Revisions become necessary when NMPA dual carbon compliance costs accelerate API sourcing shifts, FDA label revisions expand prior authorization requirements, or P-CAB regulatory approvals in Western markets materialize ahead of baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Polyps Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Gallstone Market
Gastroenterology
Digestive Health Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Pouchitis Treatment Market