
 Cowden Syndrome Market | 2026-2036
Cowden Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Cowden Syndrome Market Outlook
Genetic counselor workforce capacity is collapsing across major health systems, creating bottlenecks that constrain patient throughput for PTEN hamartoma tumor syndrome evaluations. Amgen Inc. leverages its oncology infrastructure to sustain clinical trial access for targeted therapy candidates in phosphatase-deficient malignancies. AstraZeneca Plc. anchors its position through biomarker-driven development programs that intersect hereditary cancer pathways. Novartis AG competes via specialized rare disease commercial units that navigate complex reimbursement for preventive surveillance protocols.
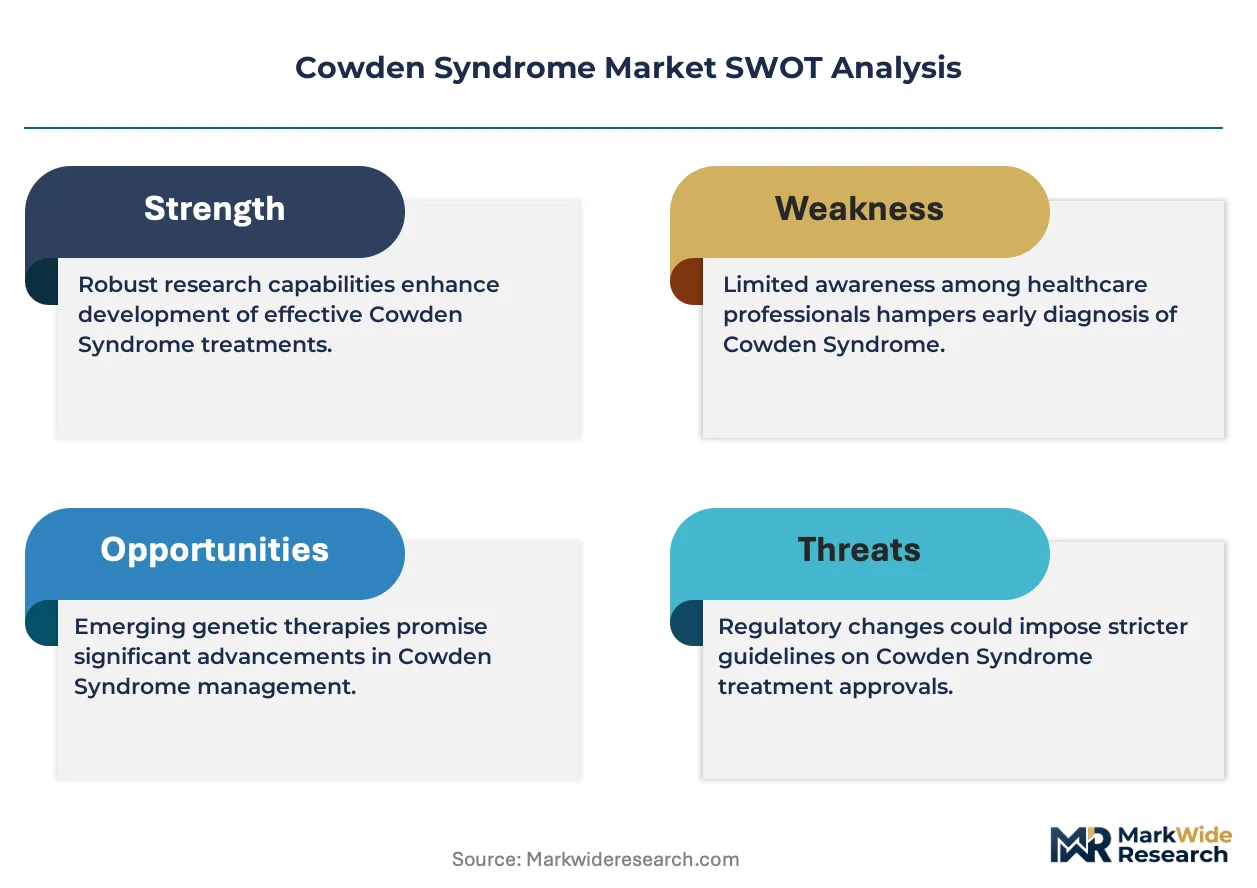
Cowden syndrome constitutes an autosomal dominant disorder characterized by germline mutations in the PTEN tumor suppressor gene, manifesting in multiple hamartomas across skin, mucous membranes, breast, thyroid, and gastrointestinal tissues with lifetime cancer risks exceeding standard population baselines. Diagnostic Tests represent the structural backbone of current revenue, with multi-gene hereditary cancer panels and PTEN-specific sequencing constituting the standard of care entry point. Therapeutic Agents command emerging margin pools as mTOR inhibitors and PI3K pathway modulators advance through orphan indication development, while Genetic Counseling Services face supply-constrained growth due to certified practitioner scarcity.
FDA orphan drug designation and breakthrough therapy pathways govern product development incentives, while HIPAA frameworks shape genetic data handling across telemedicine delivery channels. The country's national pharmaceutical regulator maintains stringent oversight of companion diagnostic co-development requirements for targeted therapeutics. Stakeholders must monitor evolving coverage determinations from Medicare and commercial payers regarding prophylactic surveillance schedules and their impact on service delivery economics.
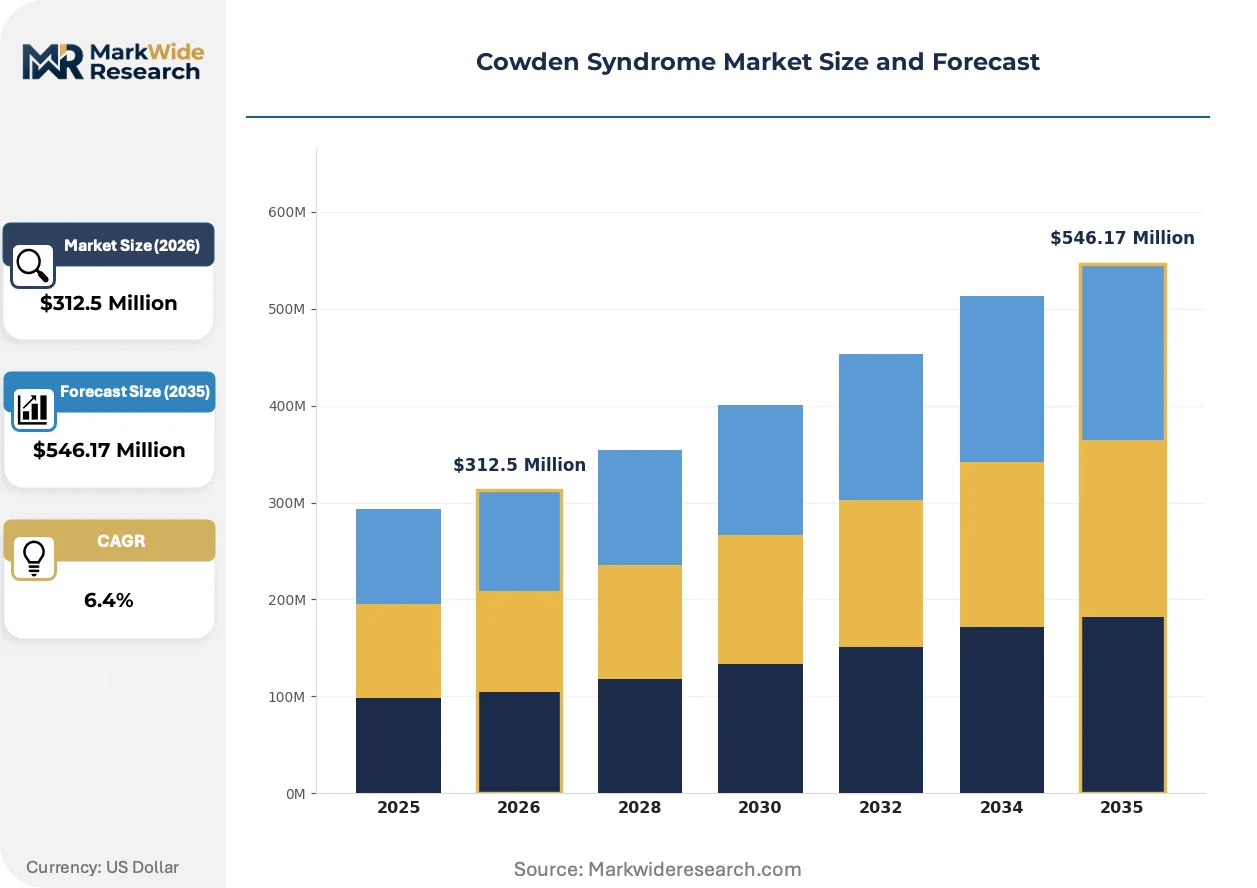
Market Dynamics
PTEN mutation screening integration into oncology protocols is compressing diagnostic timelines while simultaneously exposing severe genetic counselor workforce shortages that throttle patient throughput across major health systems.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate development timelines for mTOR inhibitors targeting phosphatase-deficient malignancies, drawing venture capital into rare disease pipelines.
- Multi-Gene Panel Diffusion:Hereditary cancer screening programs at tertiary care centers embed PTEN sequencing into standard-of-care workflows, expanding addressable testing volumes beyond symptomatic presentations.
- Telemedicine Genetic Counseling:HIPAA-compliant virtual consultation platforms extend specialist reach into underserved catchment areas, partially offsetting certified practitioner scarcity.
Market Restraints
- Genetic Counselor Supply Collapse:Certification program throughput constraints create 6-12 month appointment backlogs at major academic medical centers, capping service revenue expansion regardless of underlying disease prevalence.
- Reimbursement Fragmentation:Medicare coverage determinations for prophylactic surveillance schedules vary across MAC jurisdictions, generating administrative complexity that discourages standardized program deployment.
- Biomarker Complexity:PTEN variant of uncertain significance rates exceed actionable mutation yields, complicating clinical decision-making and elevating malpractice exposure for interpreting physicians.
Strategic Opportunities
- Artificial Intelligence Variant Interpretation:Machine learning classification tools trained on ClinVar-curated databases reduce VUS rates and accelerate reporting turnaround, enabling counselor workforce multiplication.
- Pharmacovigilance Data Monetization:Longitudinal PTEN patient registries capture natural history data that supports label expansion for PI3K pathway modulators in adjacent hamartoma syndromes.
- Employer-Sponsored Screening:Self-insured corporations in technology and finance sectors pilot hereditary cancer programs as differentiated benefits, creating direct-to-payer revenue channels outside traditional reimbursement.
Industry Challenges
- Laboratory Developed Test Harmonization:FDA's evolving stance on LDT oversight creates regulatory uncertainty for PTEN-specific assays, forcing parallel validation investments against potential IVD pathway requirements.
- Electronic Health Record Interoperability:Discrete genetic result capture across Epic, Cerner, and Meditech instances remains inconsistent, fragmenting surveillance reminder functionality and care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cowden Syndrome Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Therapeutic Agents, Genetic Counseling Services, Preventive Care Application: Oncology, Cardiology, Endocrinology, Pediatrics End User: Hospitals, Clinics, Research Institutions, Home Healthcare Delivery Mode: In-Hospital, Outpatient, Mobile Health, Telemedicine |
| Companies Covered | Amgen Inc., Eli Lilly and Company, AstraZeneca Plc., Bristol-Myers Squibb Company, Sanofi, AbbVie Inc., Novartis AG, GlaxoSmithKline Plc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cowden Syndrome Market Strategic Shifts
Liquid biopsy platforms and AI-powered variant classification are converging to reshape diagnostic economics, while regulatory pressure on companion diagnostic co-development intensifies timeline coordination between device and drug sponsors.
Cell-free DNA methylation profiling is miniaturizing into multi-cancer early detection panels that incorporate PTEN promoter hypermethylation signatures. Community oncology practices in the United States are piloting these assays for surveillance monitoring in hamartoma tumor syndrome patients. This technology is miniaturizing the tissue acquisition bottleneck that previously confined molecular monitoring to academic centers with embedded interventional radiology.
The FDA's breakthrough therapy designation pathway now explicitly requires pre-submission alignment on companion diagnostic strategy, compressing the feedback loop between CDER and CDRH. Drug sponsors face mandatory co-development timelines that extend overall program duration by 12-18 months but reduce post-approval labeling risk. Targeted therapy developers in the PI3K/mTOR class are restructuring clinical trial protocols to accommodate this parallel track requirement.
Direct-to-consumer genetic testing platforms are capturing incidentally discovered PTEN variants, shifting diagnostic entry points away from specialty genetics clinics. Primary care physicians in integrated delivery networks now receive unsolicited alerts from external laboratories, forcing workflow adaptation without reimbursement for interpretation services. Kaiser Permanente and Geisinger Health have deployed automated triage protocols to manage this inbound volume.
Cowden Syndrome Market Segmentation
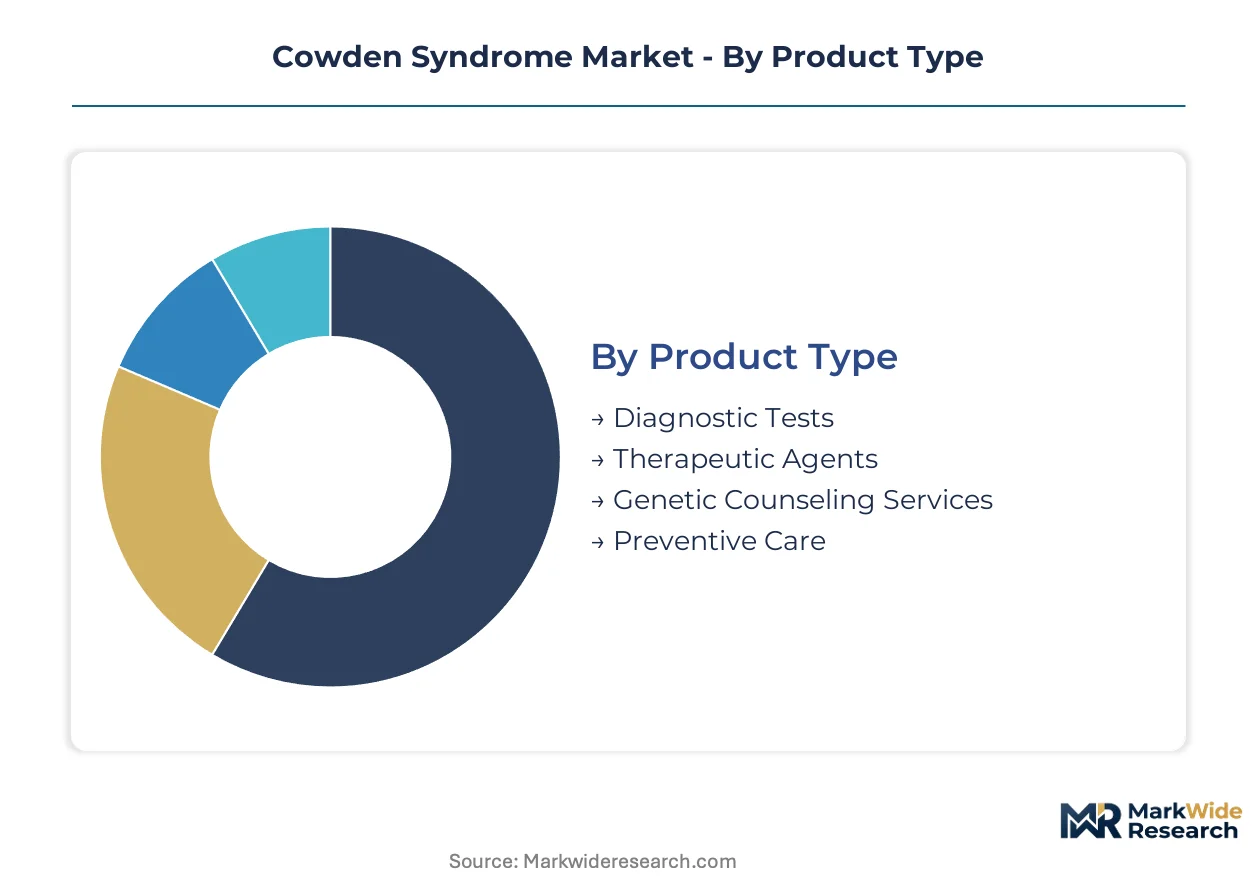
Segmentation in Cowden syndrome markets reflects divergent regulatory pathways: FDA governs diagnostic assays and therapeutics through distinct centers, while genetic counseling operates under state licensure frameworks. Understanding these structural divisions clarifies where margin pools concentrate and which segments face reimbursement friction.
Product Type:
FDA's Center for Devices and Radiological Health oversees in vitro diagnostics through premarket notification and approval pathways, while CDER governs small-molecule therapeutics under orphan drug incentives.
- Diagnostic Tests:Multi-gene hereditary cancer panels and PTEN-specific sequencing assays constitute the clinical entry point. Academic medical centers in the United States anchor demand volumes as screening protocols expand beyond symptomatic index cases.
- Therapeutic Agents:mTOR inhibitors and PI3K pathway modulators target phosphatase-deficient malignancies. Development programs concentrate in sponsor organizations with existing oncology infrastructure.
- Genetic Counseling Services:Certified practitioner scarcity constrains throughput regardless of underlying disease prevalence.
- Preventive Care:Prophylactic surveillance schedules generate recurring service revenue across tertiary care networks.
Diagnostic Tests handles the majority of throughput; Therapeutic Agents is expanding most quickly on share.
Application:
Clinical utility varies sharply across specialties, with oncology commanding the deepest reimbursement codes and pediatrics facing developmental indication constraints.
- Oncology:Breast, thyroid, and endometrial malignancy surveillance drives protocol adoption. Major cancer centers embed PTEN screening into hereditary risk assessment workflows.
- Cardiology:Arrhythmogenic right ventricular cardiomyopathy associations expand cardiovascular genetics referrals. Electrophysiology practices at Cleveland Clinic and Mayo Clinic pilot cascade screening.
- Endocrinology:Thyroid nodule management guidelines incorporate germline testing thresholds.
- Pediatrics:Developmental delay and macrocephaly presentations trigger early evaluation. Children's hospitals navigate consent complexities for predictive testing in minors.
Oncology captures the dominant revenue position; Pediatrics shows the steepest expansion trajectory.
End User:
Site-of-care economics hinge on technical infrastructure for molecular diagnostics and specialist availability for interpretation.
- Hospitals:Integrated delivery networks consolidate testing volume through centralized laboratories. Tertiary centers anchor specialized hereditary cancer program development.
- Clinics:Community oncology practices outsource complex variant interpretation to reference laboratories.
- Research Institutions:Natural history registries and biomarker discovery programs attract NIH and foundation funding.
- Home Healthcare:Remote specimen collection kits expand access for geographically dispersed families.
Hospitals dominate absolute transaction volume; Home Healthcare is gaining share fastest among alternative sites.
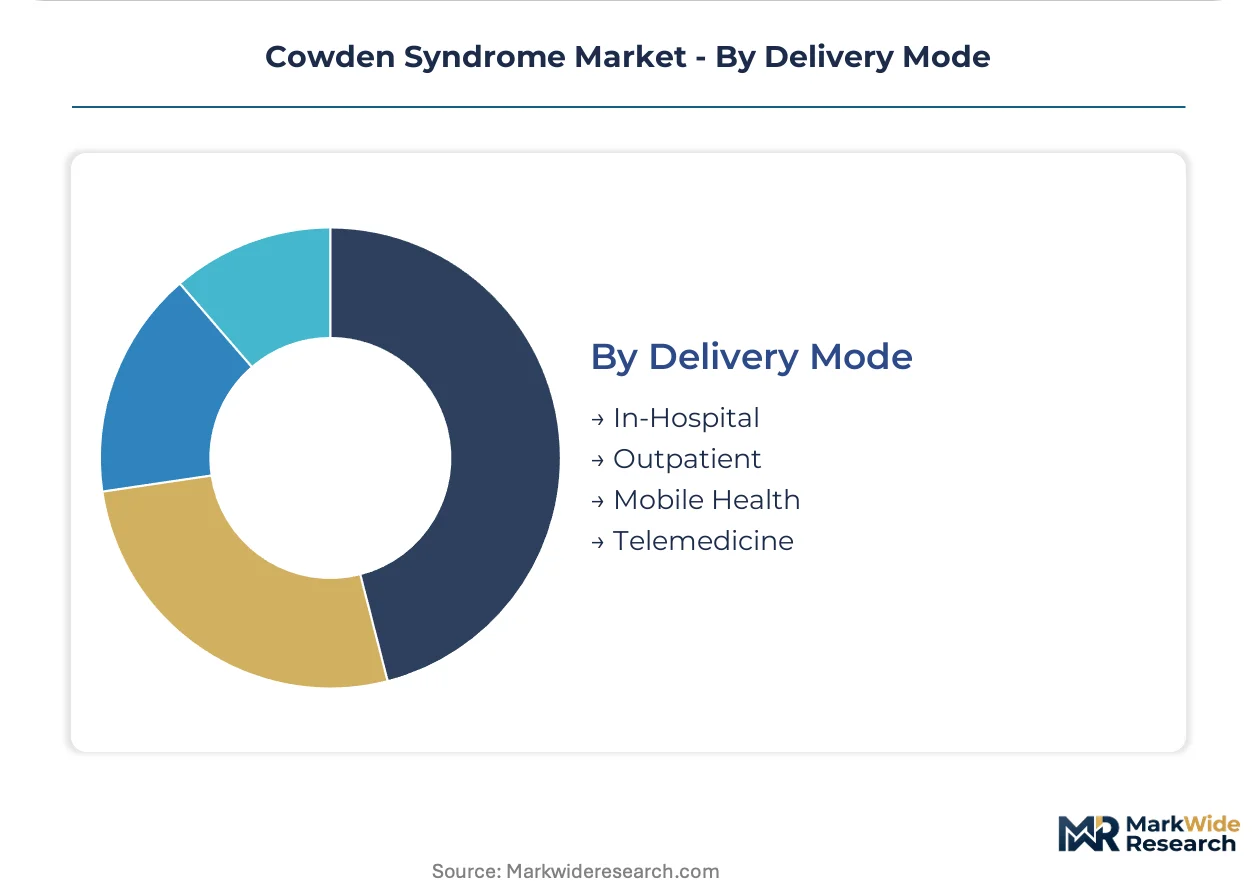
Delivery Mode:
HIPAA compliance requirements and state telemedicine licensure create operational friction for virtual service expansion.
- In-Hospital:Traditional site for diagnostic confirmation and multidisciplinary tumor board coordination.
- Outpatient:Genetics clinics manage longitudinal surveillance scheduling across subspecialty referrals.
- Mobile Health:Community screening programs reach rural catchment areas with limited specialist density.
- Telemedicine:HIPAA-compliant platforms extend genetic counselor reach. Kaiser Permanente and Geisinger Health deploy automated triage protocols for externally identified variants.
In-Hospital retains the largest service footprint; Telemedicine is climbing the fastest on penetration metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and companion diagnostic pathways anchor commercial activity in the United States, while tertiary care networks in Germany and Japan advance parallel hereditary cancer program development. Diagnostic test volumes concentrate where integrated delivery networks embed PTEN mutation screening into standard oncology protocols.
United States
Mayo Clinic and Cleveland Clinic anchor specialized hereditary cancer program volumes across the Midwest. Medicare coverage determinations for prophylactic surveillance schedules vary across MAC jurisdictions, generating administrative complexity. Kaiser Permanente deploys automated triage protocols for externally identified PTEN variants across its integrated California network.
Germany
EMA orphan designation pathways attract development programs for mTOR inhibitors targeting phosphatase-deficient malignancies. The country's national pharmaceutical regulator maintains stringent oversight of companion diagnostic co-development requirements. Heidelberg University Hospital and Charité Berlin anchor molecular diagnostics throughput for hereditary tumor syndromes.
Japan
PMDA breakthrough therapy designation explicitly requires pre-submission alignment on companion diagnostic strategy. METI funding supports rare disease registry infrastructure that captures natural history data for PTEN hamartoma tumor syndrome patients. Keio University Hospital and National Cancer Center Tokyo pilot cascade screening protocols for thyroid malignancy surveillance.
United Kingdom
NHS England hereditary cancer service specifications embed PTEN testing into regional genetics laboratory networks. GDPR frameworks shape genetic data handling across telemedicine delivery channels for remote genetic counseling. Manchester Centre for Genomic Medicine and Guy's Hospital London coordinate multidisciplinary tumor board coordination for complex variant interpretation.
Switzerland
Swissmedic streamlined pathways for orphan indications accelerate market access for PI3K pathway modulators. University Hospital Zurich and University Hospital Geneva anchor specialized surveillance program volumes for hamartoma tumor syndrome patients. The country's pharmaceutical cluster supports biomarker-driven development programs intersecting hereditary cancer pathways.
Cowden Syndrome Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with oncology majors leveraging existing infrastructure against emerging rare disease commercial units. Diagnostic assay developers compete on turnaround time and variant classification accuracy, while therapeutic sponsors navigate companion diagnostic co-development timelines. Strategic archetypes include integrated oncology majors, specialized rare disease units, and precision diagnostic platforms. Competitive moves center on biomarker-driven portfolio expansion and telemedicine-enabled genetic counseling reach extension.
Within the integrated oncology tier, Amgen Inc. and AstraZeneca Plc. occupy positions that exemplify infrastructure leverage for targeted therapy development, while Novartis AG represents the specialized rare disease commercial unit archetype navigating complex reimbursement for preventive surveillance protocols. These entities anchor competitive positioning across the phosphatase-deficient malignancy development landscape without dominating any single segment.
| Leading Market Players |
|---|
| Amgen Inc. |
| Eli Lilly and Company |
| AstraZeneca Plc. |
| Bristol-Myers Squibb Company |
| Sanofi |
| AbbVie Inc. |
| Novartis AG |
| GlaxoSmithKline Plc. |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Six-to-twelve month genetic counselor appointment backlogs at major academic medical centers concentrate pricing power with tertiary care networks that can guarantee patient throughput, while diagnostic laboratories compete on turnaround time rather than absolute price. This supply-constrained environment rewards integrated delivery networks with captive counseling capacity and punishes standalone testing facilities forced to absorb external interpretation costs.
Pricing Analysis
Geographic price spreads for PTEN sequencing assays widen substantially between Medicare MAC jurisdictions, with prophylactic surveillance schedule coverage determinations creating reimbursement arbitrage across state lines. Three-tier pricing structure across comprehensive hereditary cancer panels, PTEN-specific sequencing, and variant confirmation testing reflects test complexity and clinical utility differentiation. Pricing pressure stems from reference laboratory consolidation as community oncology practices outsource interpretation rather than maintain in-house geneticists. Self-insured employers in technology and finance sectors demonstrate lowest price sensitivity due to benefits differentiation positioning, while Medicaid programs face highest cost-containment scrutiny.
Supply Chain Analysis
Just-in-time specimen logistics dominate diagnostic testing workflows, though strategic stockpiling of PTEN-specific reagents occurs at centralized reference laboratories to buffer against FDA LDT oversight uncertainty. Manufacturing concentration for next-generation sequencing platforms centers on the United States, Germany, and Japan, with reagent kits drawing from Singapore and South Korea production facilities. Critical dependencies include semiconductor components for sequencing instruments, fluorophore-conjugated probes, and CRISPR-based enrichment reagents. Single-source vulnerability in cloud-based variant interpretation software creates operational risk for laboratories without offline backup systems. Distribution runs through integrated delivery network central laboratories, with direct-to-patient specimen collection kits expanding through specialty couriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation pathways for PI3K/mTOR inhibitors are compressing companion diagnostic co-development timelines, creating a regulatory inflection that rewards synchronized device-drug strategies over sequential launches.
For Market Incumbents: Shield existing oncology infrastructure advantages by embedding PTEN mutation screening into standard hereditary cancer protocols before liquid biopsy platforms miniaturize tissue acquisition requirements. Vertical integration into genetic counseling workforce development—through training program endowments or captive telemedicine platforms—addresses the certification bottleneck that threatens patient throughput expansion. Defensive patent landscaping around AI-powered variant classification tools prevents algorithmic disruption of interpretation revenue streams. For New Entrants and Emerging Players: Lead with employer-sponsored screening programs in self-insured technology and finance corporations, where direct-to-payer channels bypass traditional Medicare reimbursement fragmentation. Pediatric developmental delay presentations represent the most penetrable entry point, as macrocephaly-triggered evaluations occur outside established oncology referral networks. Go-to-market positioning should emphasize HIPAA-compliant telemedicine platforms that extend genetic counselor reach into rural catchment areas with specialist scarcity. For Investors and Strategic Acquirers: Long-term, this sits as a rare disease infrastructure play because orphan drug incentives and companion diagnostic mandates create durable competitive moats around integrated device-drug developers. Acquisition targets should display biomarker-driven development programs intersecting hereditary cancer pathways with existing regulatory affairs capacity. The signal to watch is FDA draft guidance on LDT oversight, which would force parallel validation investments and accelerate consolidation among reference laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA CDER-CDRH alignment requirements compress feedback loops between drug and device sponsors. |
| AI Variant Interpretation Platform | Machine learning tools trained on ClinVar databases reduce VUS rates and multiply counselor workforce capacity. |
| Longitudinal Patient Registry | Natural history data capture supports label expansion for PI3K pathway modulators in adjacent hamartoma syndromes. |
| Telemedicine Genetic Counseling Scale-Up | HIPAA-compliant virtual platforms extend specialist reach into underserved catchment areas with practitioner scarcity. |
| Employer-Sponsored Screening Pilot | Direct-to-payer revenue channels in self-insured corporations bypass Medicare MAC jurisdiction fragmentation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across genetic counselors, molecular pathologists, oncology clinical trial investigators, and hereditary cancer program administrators. Secondary validation drew from FDA orphan drug designation databases, ClinicalTrials.gov PTEN-specific protocol registrations, Medicare coverage determination repositories, and hereditary cancer panel utilization data from major reference laboratories. Bottom-up testing volume estimates were triangulated against top-down pharmaceutical development pipeline valuations.
Across the analysis window, forecasts modeled product type segmentation across diagnostic tests, therapeutic agents, genetic counseling services, and preventive care surveillance, with application splits across oncology, cardiology, endocrinology, and pediatrics. CAGRs were derived from adoption curve modeling of multi-gene panel diffusion rates and companion diagnostic co-development timeline compression. Industry-specific inputs included genetic counselor certification program throughput constraints and Medicare MAC jurisdiction coverage variation patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA orphan drug incentive continuity or companion diagnostic pathway stability would require recalibration. Forecasts reflect assumptions regarding telemedicine licensure harmonization and LDT oversight finalization. Revision becomes warranted when genetic counselor workforce expansion crosses certification program capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Von Hippel-Lindau Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Alzheimer Disease Market