
 Helicobacter Pylori Infections Treatment Market | 2026-2036
Helicobacter Pylori Infections Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Helicobacter Pylori Infections Treatment Market Foresight
Multi-source API procurement is rebalancing toward qualified secondary suppliers as primary manufacturers face capacity constraints. Pfizer Inc leverages its established clarithromycin supply chains to sustain volume leadership in triple-therapy formulations. Takeda Pharmaceutical Company Limited anchors its position through deep integration with Japanese academic medical centers for susceptibility-guided protocols.
Helicobacter pylori infections treatment encompasses pharmacological regimens targeting gram-negative spiral bacteria colonizing gastric mucosa, typically combining proton pump inhibitors with two or more antibiotics to achieve eradication rates above 80% in compliant patients. The primary commercial purpose centers on preventing peptic ulcer recurrence, reducing gastric adenocarcinoma risk, and resolving mucosa-associated lymphoid tissue lymphoma. Combination therapy generates the dominant revenue pool due to guideline-mandated multi-drug approaches, while antibiotics face margin compression from generic saturation and resistance-driven protocol shifts. Diagnostic laboratories represent the fastest-growing end user segment as non-invasive stool antigen and urea breath testing displace endoscopic biopsy for initial detection.
FDA antimicrobial stewardship requirements and EMA pharmacovigilance frameworks restrict empirical clarithromycin prescribing, forcing manufacturers toward culture-guided therapy and novel agent development. China's NMPA has accelerated review pathways for potassium-competitive acid blockers paired with next-generation antibiotics, redirecting R&D investment toward Asia-Pacific registration trials. Stakeholders must monitor resistance surveillance data and regulatory label restrictions to anticipate which regimen classes will retain reimbursement access.
Market Dynamics
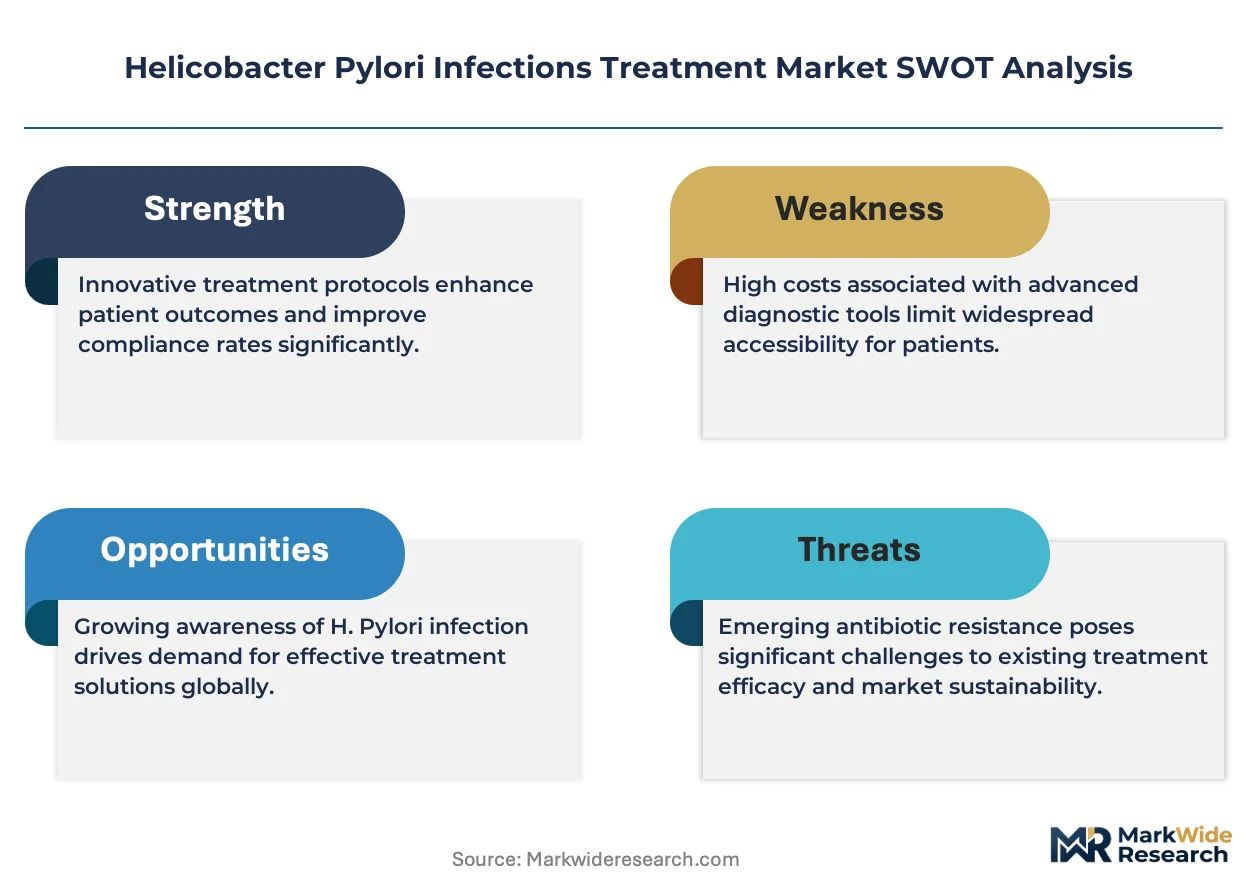
Clarithromycin resistance rates exceeding 30% in major treatment populations are forcing protocol abandonment and accelerating susceptibility-guided therapy adoption across hospital systems.
Growth Catalysts
- China's gastric cancer screening expansion:Mass eradication campaigns in high-prevalence provinces are creating sustained demand for combination therapy kits and diagnostic bundles.
- Potassium-competitive acid blocker (P-CAB) approval pathways:NMPA accelerated review frameworks are shortening development timelines for next-generation acid suppression paired with novel antibiotics.
- Stool antigen testing standardization:Non-invasive diagnostic protocols are expanding treatable patient pools beyond endoscopy-limited populations in primary care settings.
Market Restraints
- API supply concentration:Qualified secondary suppliers face capacity constraints as primary clarithromycin manufacturers throttle output, creating procurement bottlenecks for triple-therapy formulators.
- EMA pharmacovigilance tightening:Post-market surveillance requirements for macrolide antibiotics are extending compliance timelines and elevating documentation costs for empirical prescribing.
- Metronidazole substitution pressure:Rising bismuth-based quadruple therapy adoption is compressing margins for legacy proton pump inhibitor plus clarithromycin combinations.
Strategic Opportunities
- Vonoprazan-amoxicillin dual therapy:Japan's PMDA breakthrough designation pathway offers regulatory precedent for antibiotic-sparing regimens now entering Phase III in the United States.
- Diagnostic-therapeutic bundling:Integrated stool antigen plus treatment kit models are penetrating pharmacy-direct channels in South Korea and Taiwan.
- Culture-guided protocol reimbursement:Germany's G-BA is evaluating susceptibility testing mandates that would shift payment toward precision-matched antibiotic selection.
Industry Challenges
- Microbiology laboratory capacity:Culture and antimicrobial susceptibility testing requires specialized technician training that hospital systems in rural China and India cannot scale rapidly.
- Multi-site protocol harmonization:Academic medical centers running investigator-initiated trials face IRB fragmentation when coordinating susceptibility-guided therapy studies across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicobacter Pylori Infections Treatment Market |
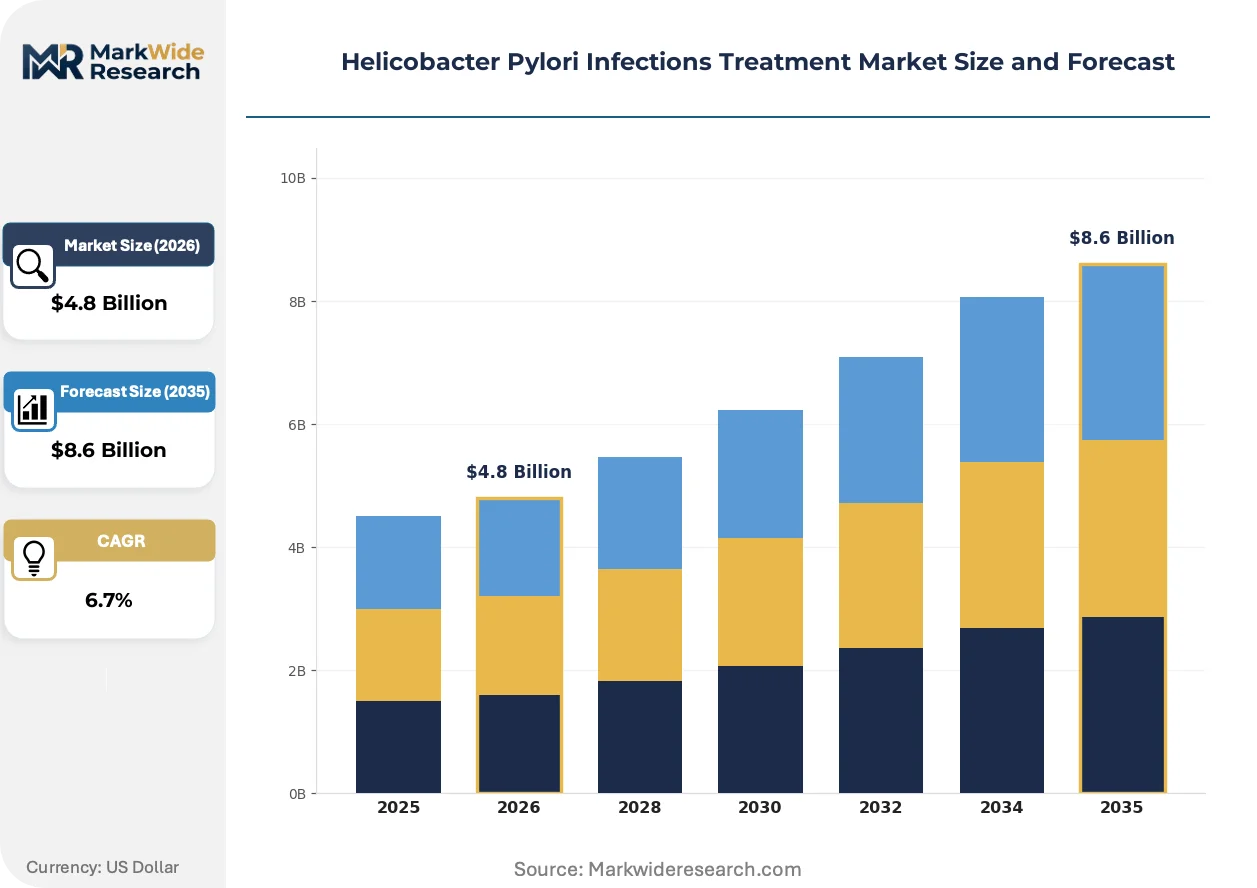
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Proton Pump Inhibitors, Bismuth Compounds, Combination Therapy End User: Hospitals, Clinics, Homecare, Diagnostic Laboratories Delivery Mode: Oral, Intravenous, Sublingual, Topical Treatment Duration: Short-term, Long-term, Maintenance Therapy, episodic |
| Companies Covered | Pfizer Inc, AbbVie Inc, Takeda Pharmaceutical Company Limited, Phathom Pharmaceuticals, RedHill Biopharma, Cumberland Pharmaceuticals, Eisai Co., Ltd., Merck & Co., Inc., AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicobacter Pylori Infections Treatment Market Shifts & Advancements
Resistance surveillance data is actively restructuring prescribing authority, shifting decision-making from empirical protocols toward laboratory-validated regimens and novel acid suppression chemistry.
Molecular resistance testing via polymerase chain reaction is consolidating clinical workflow around rapid clarithromycin and fluoroquinolone susceptibility determination. Hospital laboratories in Beijing and Shanghai are adopting same-day turnaround platforms that displace culture-based methods. This capability is consolidating procurement decisions toward integrated diagnostic-therapeutic vendors capable of delivering both testing infrastructure and matched drug supply.
FDA antimicrobial stewardship guidance issued under the Combating Antibiotic-Resistant Bacteria initiative restricts clarithromycin-first empirical therapy to documented susceptible populations. Manufacturers must now support culture or molecular testing infrastructure to maintain formulary access. Triple-therapy formulations face the steepest reimbursement pressure in Medicare and Medicaid populations where resistance prevalence exceeds guideline thresholds.
Hospital procurement committees are consolidating antibiotic selection authority under infectious disease stewardship programs, compressing individual physician discretion. This centralization is displacing traditional pharmaceutical representative detailing with outcomes-based contracting tied to eradication rate guarantees. The shift is most visible in United States academic medical centers and Japanese university hospitals where quality metrics determine formulary tier placement.
Helicobacter Pylori Infections Treatment Market Segmentation
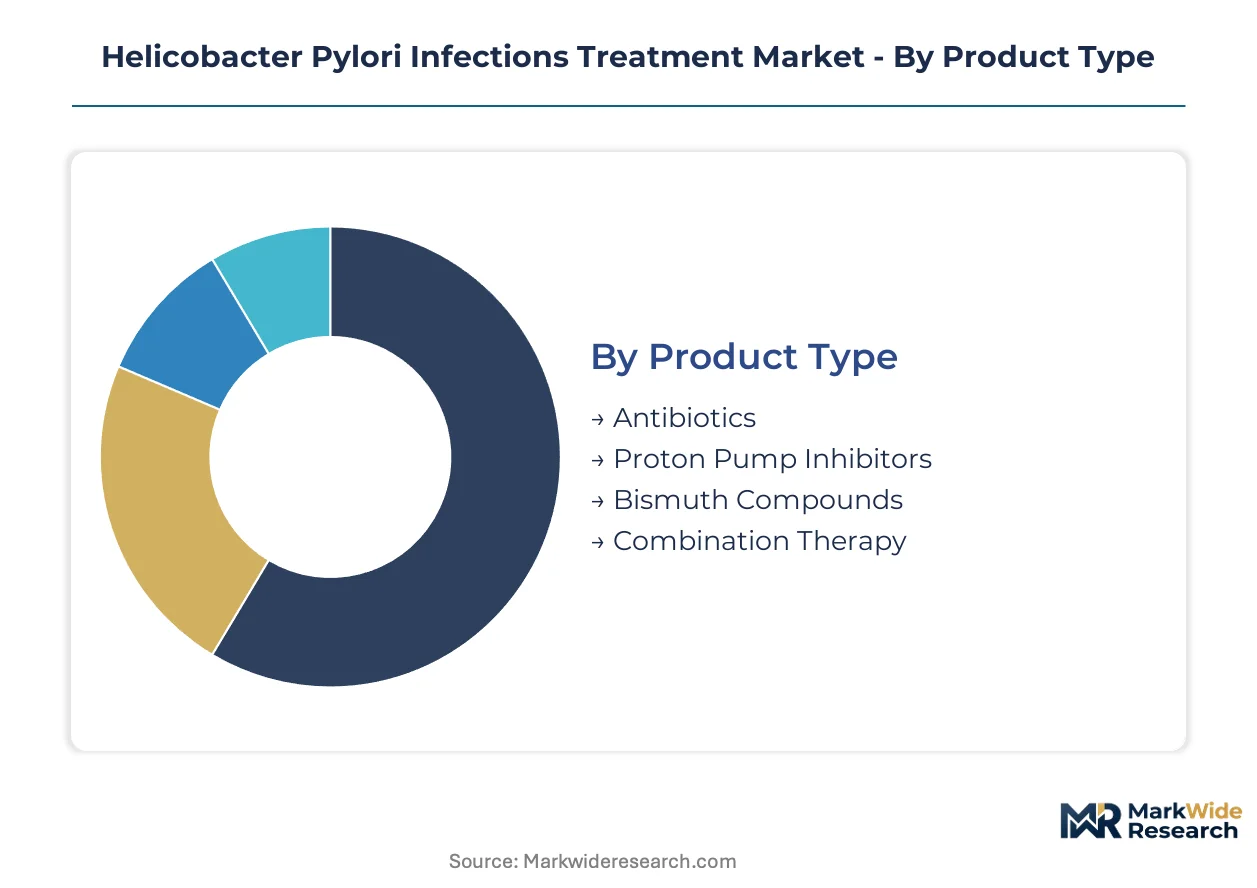
Segmentation in H. pylori treatment reveals how resistance patterns and diagnostic access reshape commercial opportunity across product forms and care settings. Procurement committees now weight eradication rate guarantees over unit economics when selecting regimen categories.
Product Type:
Volume concentrates in legacy combination formats, while premium capture shifts toward resistance-sparing novel chemistry.
- Combination Therapy:Multi-drug kits pairing proton pump inhibitors with dual antibiotics dominate hospital procurement due to guideline-mandated protocols. China's gastric cancer screening programs drive mass procurement of standardized triple-therapy bundles in provincial hospital systems.
- Antibiotics:Clarithromycin, amoxicillin, and metronidazole face margin compression from generic saturation and rising resistance-driven protocol abandonment. EMA pharmacovigilance tightening extends compliance timelines for macrolide prescribing across European hospital networks.
- Proton Pump Inhibitors:Omeprazole and esomeprazole remain backbone agents for acid suppression in standard regimens.
- Bismuth Compounds:Bismuth subsalicylate anchors quadruple therapy alternatives where clarithromycin resistance exceeds clinical thresholds.
Today's leader: Combination Therapy. Tomorrow's challenger: Bismuth Compounds.
End User:
Care setting determines diagnostic sophistication required and reimbursement pathway complexity.
- Diagnostic Laboratories:Non-invasive stool antigen and urea breath testing displace endoscopic biopsy, expanding treatable pools beyond gastroenterology-limited populations. South Korean and Taiwanese pharmacy-direct channels now bundle rapid testing with treatment kit fulfillment.
- Hospitals:Academic medical centers consolidate antibiotic authority under infectious disease stewardship programs with outcomes-based contracting tied to eradication guarantees. Japanese university hospitals use quality metrics to determine formulary tier placement.
- Clinics:Primary care settings in China's high-prevalence provinces manage mass eradication campaign logistics.
- Homecare:Oral regimen completion monitoring and patient adherence support services.
Diagnostic Laboratories are climbing the fastest as testing standardization penetrates primary care.
Delivery Mode:
Patient compliance requirements and bioavailability considerations shape route selection across regimen classes.
- Oral:Dominant route for all standard eradication regimens, with film-coated tablets and granule formulations optimizing gastric acid stability.
- Intravenous:Reserved for severe complications or nil-per-os hospitalization scenarios.
- Sublingual:Rapid absorption alternatives for nausea-compromised patients.
- Topical:Limited application in mucosal protective adjunct therapies.
Oral maintains absolute volume dominance. Sublingual offers niche premium capture for compliance-challenged populations.
Treatment Duration:
Duration selection balances eradication probability against resistance amplification risk and patient adherence decay.
- Short-term:7-14 day standard eradication courses generate the dominant prescription volume.
- Long-term:Extended protocols for refractory infections with documented antimicrobial susceptibility.
- Maintenance Therapy:Suppression regimens for recurrent ulcer disease without re-eradication indication.
- Episodic:Symptom-driven retreatment approaches in resource-constrained settings lacking diagnostic confirmation.
Short-term commands current procurement spend. Long-term protocols gain eligibility as susceptibility-guided therapy expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's diagnostic-therapeutic cluster anchors commercial activity, with gastric cancer screening programs and resistance surveillance infrastructure concentrating procurement authority in eastern China's hospital networks.
China
Gastric cancer screening expansion in Shandong and Liaoning provinces drives mass eradication procurement. NMPA accelerated review pathways for potassium-competitive acid blocker combinations redirect R&D investment toward domestic registration trials. Beijing and Shanghai academic medical centers adopt same-day molecular susceptibility testing platforms.
United States
Academic medical centers consolidate antibiotic authority under infectious disease stewardship programs. FDA antimicrobial stewardship guidance restricts clarithromycin-first empirical therapy to documented susceptible populations. Boston and New York hospital networks negotiate outcomes-based contracting tied to eradication rate guarantees.
Japan
PMDA breakthrough designation for vonoprazan-amoxicillin dual therapy establishes regulatory precedent for antibiotic-sparing regimens. Tokyo and Osaka university hospitals use quality metrics to determine formulary tier placement. Susceptibility-guided protocols deepen integration with domestic pharmaceutical supply chains.
Germany
G-BA evaluation of susceptibility testing mandates shifts reimbursement toward precision-matched antibiotic selection. EMA pharmacovigilance tightening extends compliance timelines for macrolide prescribing. Berlin and Munich hospital procurement committees centralize formulary decisions under stewardship programs.
South Korea
Pharmacy-direct diagnostic-therapeutic bundling penetrates primary care channels. MFDS standardization of stool antigen testing expands treatable patient pools beyond gastroenterology-limited populations. Seoul metropolitan laboratories consolidate procurement toward integrated testing infrastructure vendors.
Helicobacter Pylori Infections Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue novel acid suppression chemistry and diagnostic-therapeutic integration. The market structures around legacy triple-therapy formulators, P-CAB developers, and diagnostic bundling specialists. Three archetypes dominate: multinational pharmaceutical incumbents with clarithromycin supply chains, biotechnology firms advancing susceptibility-guided protocols, and integrated diagnostic-therapeutic vendors. Competitive moves concentrate on strategic partnerships for testing infrastructure deployment and portfolio diversification toward resistance-sparing regimens.
Within the multinational incumbent tier, Pfizer Inc and Takeda Pharmaceutical Company Limited exemplify contrasting geographic anchoring strategies. Pfizer leverages established supply chain infrastructure for volume leadership in combination therapy formulations. Takeda occupies a position defined by deep academic medical center integration in its domestic market. Phathom Pharmaceuticals represents the emerging archetype pursuing novel acid suppression chemistry through regulatory pathways established by precedent designations.
| Leading Market Players |
|---|
| Pfizer Inc |
| AbbVie Inc |
| Takeda Pharmaceutical Company Limited |
| Phathom Pharmaceuticals |
| RedHill Biopharma |
| Cumberland Pharmaceuticals |
| Eisai Co., Ltd. |
| Merck & Co., Inc. |
| AstraZeneca PLC |
| Others |
Supply & Pricing Matrix
Captive supply of clarithromycin API through in-house fermentation capacity anchors both Pfizer's procurement position and its pricing power in triple-therapy formulations. This backward integration insulates volume leaders from spot-market volatility while compressing margins for non-integrated generic assemblers competing on procurement cost alone.
Pricing Analysis
API cost pass-through from primary clarithromycin manufacturers to finished-dose formulators intensifies as qualified secondary suppliers face capacity constraints. Three-tier pricing structure across premium novel-acid-blocker combinations, standard proton-pump-inhibitor triple therapies, and economy generic dual therapies stratifies procurement committees by eradication-rate guarantees versus unit economics. Pricing pressure stems from metronidazole substitution in bismuth-based quadruple protocols displacing legacy macrolide combinations. Hospital systems exhibit highest price sensitivity due to stewardship-mandated outcomes contracting, while specialty pharmacy-direct channels in South Korea absorb moderate premiums for diagnostic-therapeutic bundling.
Supply Chain Analysis
China's NMPA domestic-content preferences for potassium-competitive acid blocker registration trials redirect active pharmaceutical ingredient sourcing toward qualified domestic fermentation facilities. Supply concentration in India, China, and Italy for clarithromycin and amoxicillin intermediates draws from fermentation-derived bulk chemicals and synthetic chemistry capabilities. Single-source vulnerability concentrates in specialized bismuth salt processing for quadruple therapy alternatives. Distribution runs through hospital procurement committees under infectious disease stewardship authority, with pharmacy-direct channels penetrating primary care in East Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Helicobacter Pylori Infections Treatment Market compounds steadily as gastric cancer screening program expansion in high-prevalence Asian provinces sustains demand for eradication regimens regardless of broader pharmaceutical cyclicality.
For Market Incumbents: Deepen integration with molecular diagnostic infrastructure vendors to secure formulary tier placement as FDA and EMA stewardship mandates shift procurement toward susceptibility-guided protocols. Anchor capacity expansion in China's eastern hospital network cluster to capture NMPA accelerated review pathway benefits for potassium-competitive acid blocker combinations. Defend against margin compression by locking long-term API supply agreements before secondary supplier constraints tighten further. For New Entrants and Emerging Players: Diagnostic laboratory partnerships offer the most penetrable channel for novel regimen introduction, as Beijing and Shanghai academic medical centers consolidate procurement authority under integrated testing-treatment vendors. Target Germany's G-BA susceptibility-testing mandate evaluation window to establish precision-matched antibiotic selection capabilities before reimbursement shifts solidify. Pursue pharmacy-direct bundling models proven in South Korean primary care as the go-to-market angle for stool antigen testing standardization. For Investors and Strategic Acquirers: Roll-up economics work for regional diagnostic-therapeutic integrators because hospital procurement centralization under stewardship programs favors vendors offering matched testing infrastructure and drug supply. Long-term viability centers on resistance surveillance data assets that predict protocol obsolescence. Watch clarithromycin resistance rate thresholds in Medicare populations as the inflection signal for triple-therapy reimbursement restriction timing.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Bundling | Seoul pharmacy-direct channels validate integrated stool antigen plus treatment kit fulfillment models. |
| P-CAB Regulatory Pathway Acceleration | NMPA breakthrough frameworks shorten development timelines for vonoprazan-amoxicillin dual therapy candidates. |
| Culture-Guided Protocol Infrastructure | Germany's G-BA mandate evaluation shifts reimbursement toward precision-matched antibiotic selection capabilities. |
| Molecular Susceptibility Testing Deployment | Beijing and Shanghai hospital laboratories adopt same-day PCR platforms displacing culture-based methods. |
| API Supply Chain Backward Integration | Captive fermentation capacity insulates volume leaders from clarithromycin spot-market volatility and procurement bottlenecks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical market sizing triangulated volume estimates across the analysis window.
Historical reference periods anchored the forecast framework to resistance surveillance trend lines and regulatory guidance issuance timelines rather than arbitrary calendar breakpoints. Segmentation dimensions modeled include treatment regimen class, diagnostic methodology, end-user care setting, and regional regulatory cluster. CAGRs derived from protocol adoption curve analysis incorporating susceptibility-guided therapy penetration rates and gastric cancer screening program expansion trajectories.
Revisions become necessary when clarithromycin resistance thresholds exceed guideline-mandated protocol abandonment points, NMPA or FDA regulatory pathways shift for novel acid suppression chemistry, or API supply concentration triggers procurement disruption in triple-therapy manufacturing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Polyps Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Anal Fissure Treatment Market