
 Digestive Health Products Market | 2026-2036
Digestive Health Products Market Size, Share, and Industry Trends Forecast 2026-2036
Digestive Health Products Market Intelligence
Personalized nutrition subscription services based on microbiome analysis is expanding the definition of digestive health products beyond simple supplements. This shift creates new revenue models focused on recurring customer relationships. Danone SA leverages its extensive portfolio of fermented dairy and plant-based products to capture this trend. Bayer AG competes by applying its pharmaceutical research capabilities to develop clinically-supported consumer health solutions. Meanwhile, Chr. Hansen Holding A/S specializes in supplying microbial strains to other manufacturers, anchoring a critical part of the supply chain.
Digestive health products encompass a category of functional foods and dietary supplements containing probiotics, prebiotics, and enzymes. Probiotic formulations are often specified by Colony Forming Units (CFUs) at the time of manufacture to ensure efficacy. The primary purpose of these products is to support or modulate the gut microbiota to improve digestive function and overall wellness. While Probiotics constitute the largest product type, the Prebiotics segment is growing rapidly due to its role in nourishing beneficial gut bacteria. The Adults end-user segment remains the largest consumer base for these products.
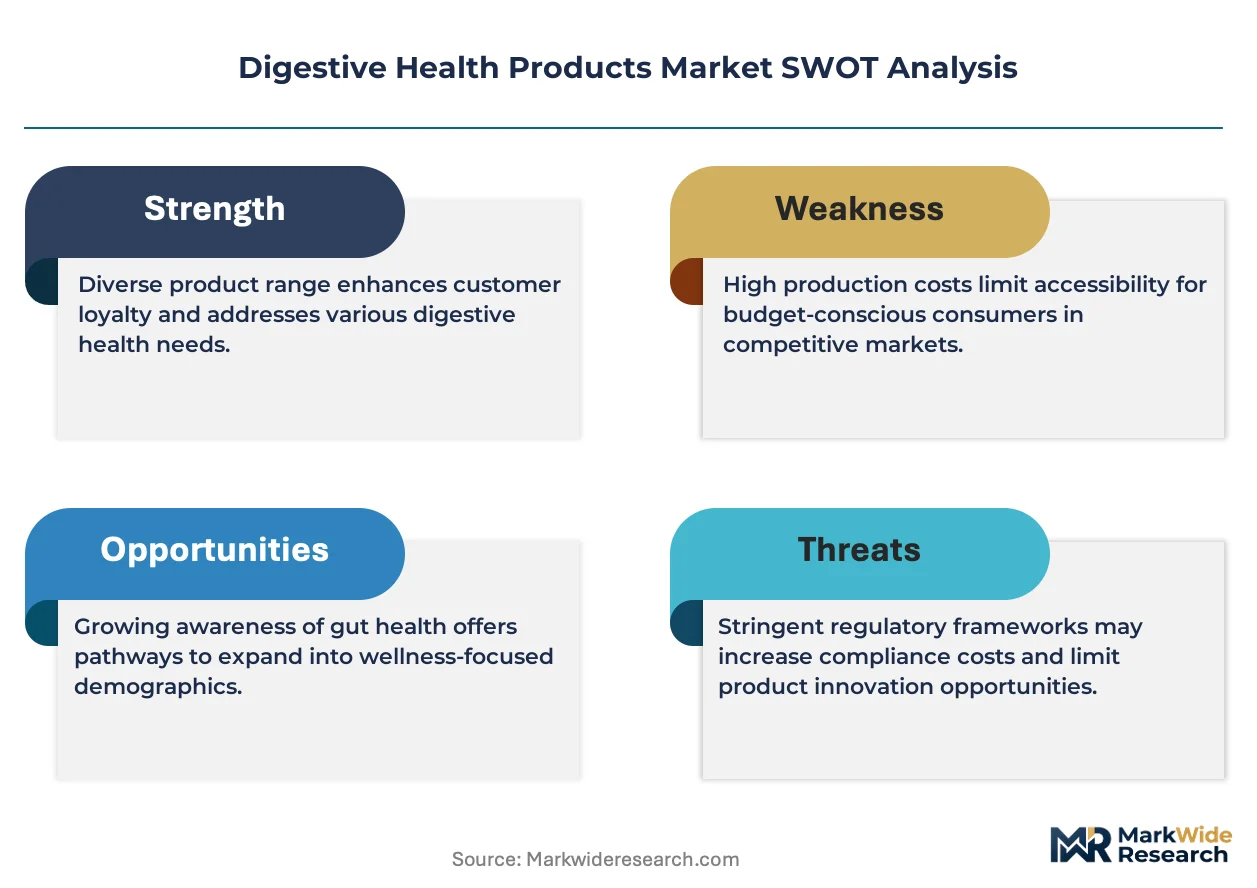
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) create stringent requirements for health claims and ingredient safety. These regulations govern what benefits can be marketed to consumers, directly shaping product formulation and labeling strategies. In Asia, frameworks in countries like Japan and South Korea also influence market access. Success for manufacturers depends on navigating these complex international standards while investing in clinical research to validate product efficacy for specific health outcomes.
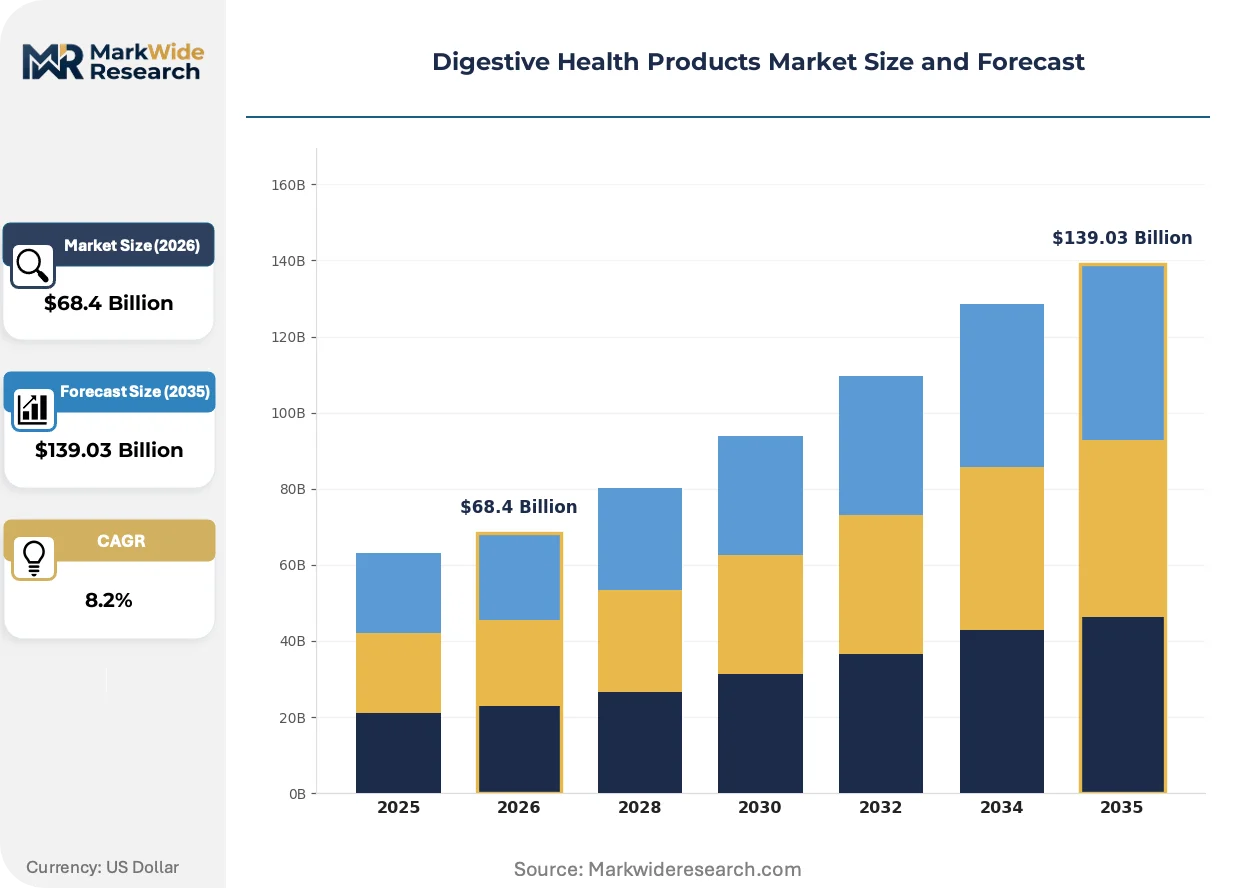
Market Dynamics
The convergence of food science and pharmaceutical research is the central force shaping the market, demanding higher standards of clinical evidence for consumer products and blurring lines between supplements and preventative health solutions.
Growth Catalysts
- Synbiotic Formulations:Combining prebiotics and probiotics enhances survivability and efficacy, meeting consumer demand for multifunctional products with superior performance benefits.
- Aging Demographics:Seniors in countries like Japan and Germany seek targeted products for age-related digestive issues, immune decline, and overall wellness maintenance.
- Regulatory Clarity:Japan's FOSHU (Foods for Specified Health Uses) system provides a clear pathway for marketing products with validated health claims, encouraging R&D investment.
Market Restraints
- Health Claim Scrutiny:The European Food Safety Authority (EFSA) maintains a high bar for approving health claims, limiting marketing language and requiring extensive scientific dossiers.
- Strain Viability:Maintaining specified Colony Forming Unit (CFU) counts through manufacturing, shipping, and shelf-life presents significant technical and logistical hurdles.
- Consumer Education Gap:Misinformation and a crowded marketplace create confusion, making it difficult for consumers to differentiate effective, science-backed products from imitators.
Strategic Opportunities
- Gut-Brain Axis Research:Emerging science linking gut microbiota to mental wellness and cognitive function opens new product development avenues beyond traditional digestive support.
- Personalized Nutrition Platforms:Direct-to-consumer services using microbiome analysis to create custom formulations represent a high-growth channel with strong customer retention.
- Market Entry in Brazil:Brazil's growing middle class and increasing health awareness, supported by ANVISA's evolving functional food regulations, offer expansion potential.
Industry Challenges
- Clinical Validation Costs:The expense and long timelines for human clinical trials required to substantiate specific health claims are significant operational hurdles for manufacturers.
- IP Protection:Securing intellectual property for novel microbial strains and their specific health applications is complex and highly competitive in a fast-moving field.
- Supply Chain Integrity:Maintaining the cold chain for certain live probiotic products to ensure viability from the factory to the consumer is a logistical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digestive Health Products Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $139.03 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Digestive Enzymes, Fiber Supplements Application: Gut Health, Weight Management, Nutritional Support, Immune Support End User: Adults, Children, Seniors, Athletes Distribution Channel: Pharmacies, Online Retailers, Supermarkets, Health Stores |
| Companies Covered | Nestle SA, Danone SA, Bayer AG, BASF SE, Arla Foods amba, Yakult Honsha Co. Ltd, Cargill Inc, Abbott Laboratories, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digestive Health Products Market Strategic Shifts & Innovations
Product development is shifting from broad-spectrum supplements to targeted, evidence-backed formulations. This evolution is driven by deeper scientific understanding of the microbiome and the technological means to manipulate it with precision.
Precision fermentation is the core technology used to produce specific postbiotic compounds and novel probiotic strains. Functional food and beverage manufacturers are rapidly adopting this process to create next-generation ingredients. This technology is modularizing product design, enabling formulators to assemble specific gut-modulating components to achieve targeted health outcomes like immune support or metabolic regulation.
The US Food and Drug Administration's evolving stance on Live Biotherapeutic Products (LBPs) is creating a clearer distinction between supplements and pharmaceutical-grade interventions. This regulatory development pressures manufacturers to either invest in drug development pathways or carefully position their products within dietary supplement guidelines. Probiotic products making disease-related claims are most affected by this clarification.
Subscription-based business models are gaining traction, directly linking consumers with manufacturers. This model often bypasses traditional retail, using at-home microbiome testing kits to offer personalized product recommendations and recurring deliveries. The shift is most visible in the United States, where a digitally native consumer base actively seeks customized wellness solutions.
Digestive Health Products Market Segmentation
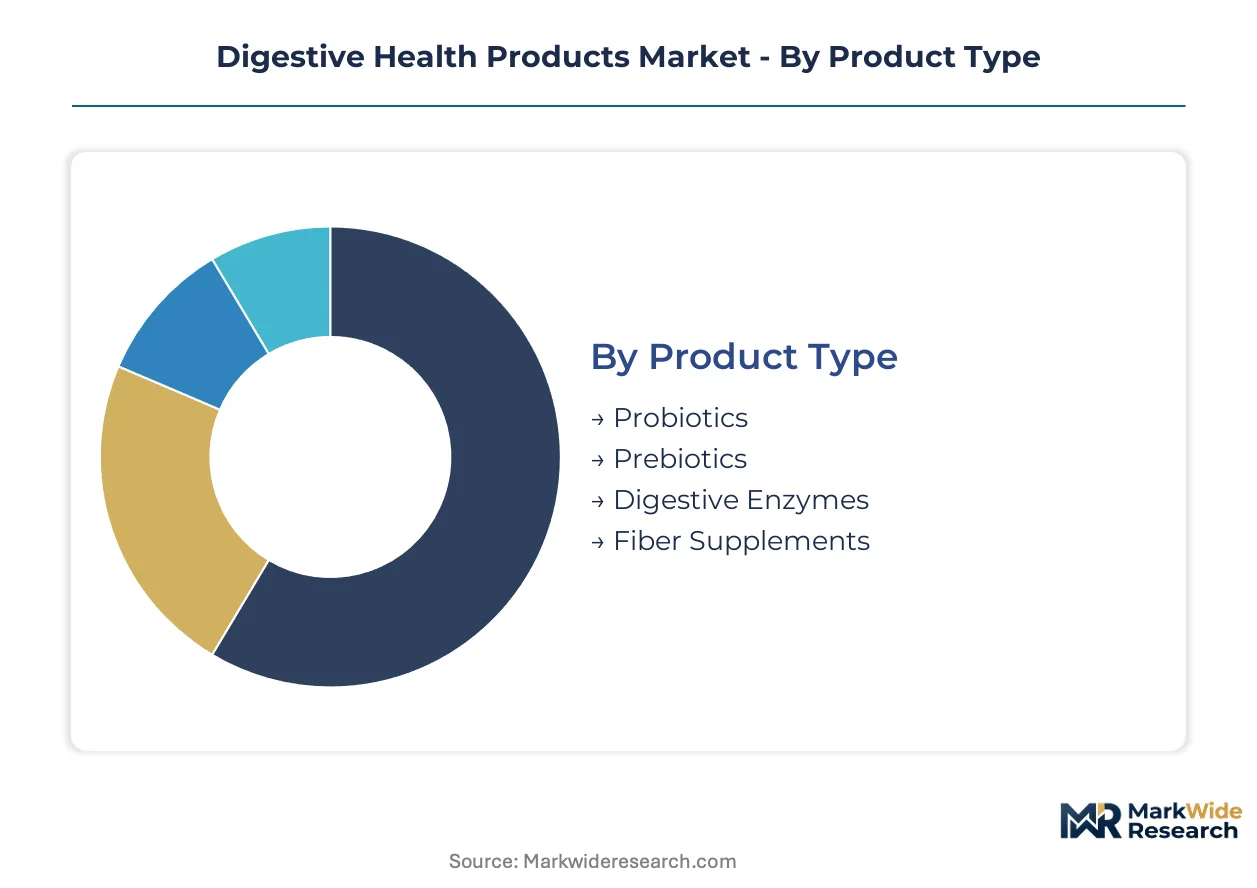
Segmentation provides a structured view of the Digestive Health Products Market, revealing distinct consumer needs and product functionalities. This analysis helps manufacturers tailor offerings and optimize market entry strategies for specific niches. Understanding these segments is critical for identifying areas of high demand and competitive advantage within the industry.
Product Type:
The product type segmentation differentiates standalone supplement formats from those integrated into functional foods, reflecting varying formulation complexity and consumer delivery methods.
- Probiotics:These formulations contain live microorganisms, often specified by Colony Forming Units (CFUs), intended to confer a health benefit to the host. Demand concentrates in the Adults segment, driven by a desire for improved digestive function and overall wellness.
- Prebiotics:Non-digestible food ingredients that selectively stimulate the growth or activity of beneficial microorganisms already residing in the colon. The segment is expanding rapidly, fueled by research highlighting its role in nourishing gut bacteria and supporting synbiotic product development.
- Digestive Enzymes:Supplements containing enzymes like amylase, lipase, and protease aid in breaking down food macronutrients. These products support individuals with dietary intolerances or age-related digestive decline.
- Fiber Supplements:Products providing dietary fiber, such as psyllium or inulin, promote bowel regularity and support gut health. Consumers use these for general digestive maintenance.
Probiotics leads volumes today; Prebiotics is gaining share fastest.
Application:
Application segmentation highlights specific health benefits consumers seek from digestive health products, influencing product claims and marketing focus.
- Gut Health:This application focuses on modulating the gut microbiota to optimize digestive function, alleviate discomfort, and maintain intestinal integrity. Demand for gut health products is widespread, with consumers seeking daily support for their digestive systems.
- Immune Support:Products targeting this application aim to enhance the body's natural defenses by leveraging the gut's significant role in immune system modulation. Research into the gut-brain-immune axis drives innovation in this segment, particularly among Seniors.
- Weight Management:Digestive health products in this category support metabolic processes and gut microbiota balance, potentially aiding weight regulation. Consumers seek these as part of broader wellness goals.
- Nutritional Support:This application encompasses products improving nutrient absorption or addressing deficiencies related to digestive issues. These often integrate into broader dietary regimens.
Demand for Gut Health remains consistent, while Immune Support demonstrates significant expansion.
End User:
End-user segmentation delineates consumer groups based on their specific physiological needs and purchasing behaviors, guiding product formulation and packaging.
- Adults:This segment represents the largest consumer base, seeking general digestive wellness, occasional relief from discomfort, and preventive health solutions. The broad appeal of these products across the adult population drives substantial market volume.
- Seniors:This demographic increasingly seeks targeted products for age-related digestive issues, immune decline, and overall wellness maintenance. Countries like Japan and Germany show pronounced demand for specialized formulations catering to this group.
- Children:Products for children focus on supporting gut development, addressing common digestive upsets, and boosting immunity. These often come in palatable formats.
- Athletes:This segment uses digestive health products to optimize nutrient absorption, reduce exercise-induced gut distress, and support recovery. Performance enhancement is a primary driver.
The Adults demographic represents the largest consumer base, with Seniors showing pronounced growth.
Distribution Channel:
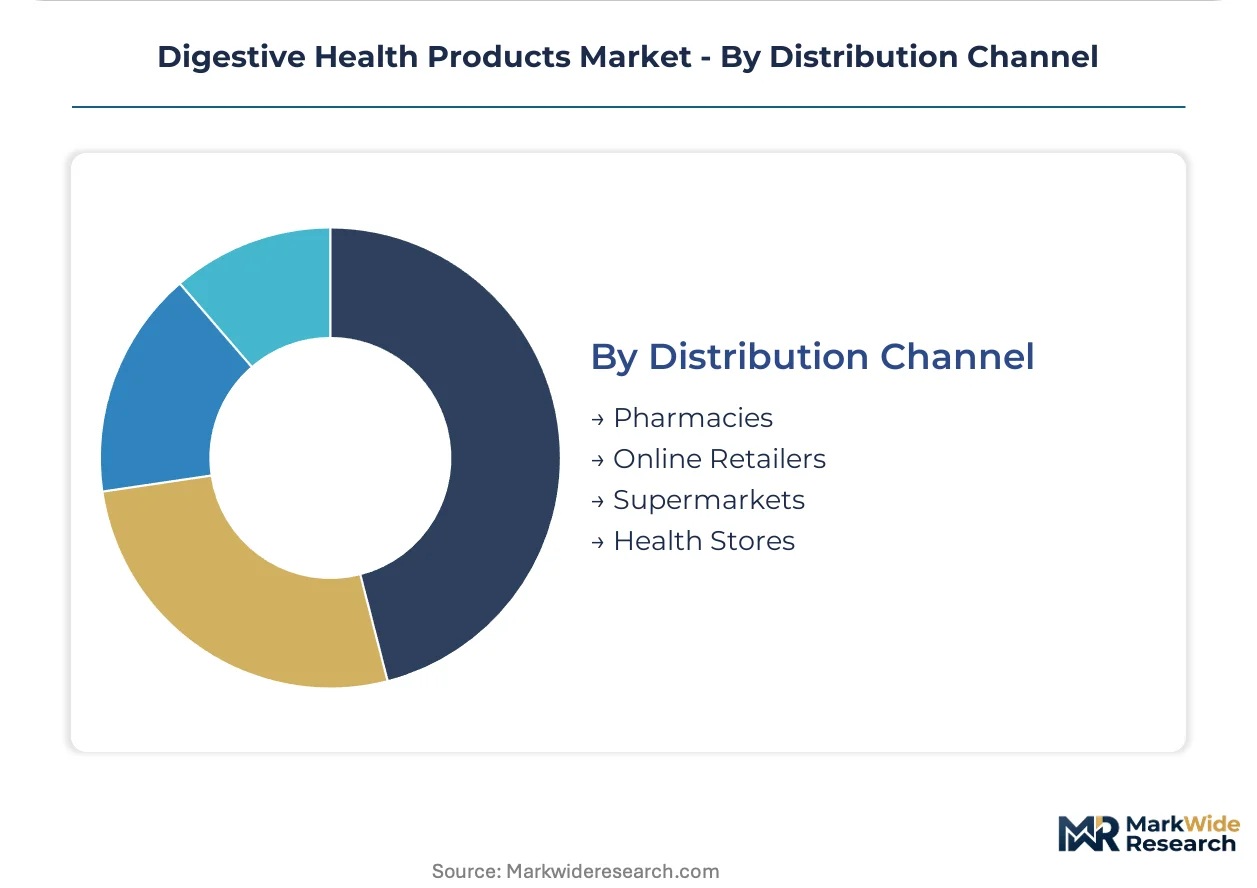
Distribution channel analysis reveals primary avenues through which digestive health products reach consumers, influencing market accessibility and brand visibility.
- Online Retailers:E-commerce platforms provide extensive product choices, competitive pricing, and convenience, appealing to a digitally native consumer base. This channel facilitates personalized nutrition subscription services and direct-to-consumer models, particularly in the United States.
- Supermarkets:These broad-access retail environments offer a wide array of functional foods and supplements, benefiting from high foot traffic and consumer familiarity. Supermarkets remain a primary point of purchase for mass-market digestive health products.
- Pharmacies:This channel provides a trusted environment for consumers seeking health-related advice and specialized digestive health products. Pharmacists often recommend specific brands.
- Health Stores:Specialized health food stores and wellness boutiques cater to consumers seeking natural, organic, or niche digestive health solutions. These stores emphasize product purity.
Traditional retail outlets maintain a strong presence, but digital platforms are capturing a rising share of transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's mature functional foods market and aging population drive significant demand for digestive health products, while the United States exhibits strong growth in personalized nutrition services. Both countries showcase distinct regulatory approaches influencing product development and market access. This regional diversity underscores varied consumer needs and industry responses across key global markets.
Japan
Japan's aging demographic and established functional foods market drive demand for digestive health solutions. The FOSHU system provides a clear regulatory pathway for products with validated health claims. Tokyo's research institutions actively develop synbiotic formulations and targeted nutritional support.
United States
The United States market benefits from consumers seeking customized wellness solutions and personalized nutrition. The US Food and Drug Administration (FDA) distinguishes between supplements and Live Biotherapeutic Products. Tech hubs foster direct-to-consumer services and microbiome analysis platforms.
Germany
German consumers show strong interest in clinically supported consumer health solutions for age-related digestive issues. The European Food Safety Authority (EFSA) maintains stringent requirements for health claims. Munich and Berlin are centers for pharmaceutical research, where companies apply scientific rigor.
Brazil
Brazil's growing middle class and increasing health awareness contribute to expansion potential in digestive health. ANVISA's evolving functional food regulations create a structured environment for market entry. São Paulo's consumer health sector sees increased investment in localized product formulations.
South Korea
South Korea emphasizes health and wellness, with consumers seeking functional foods and supplements for gut health and immune support. The Ministry of Food and Drug Safety (MFDS) regulates health functional foods, requiring scientific evidence. Seoul's biotech industry develops novel probiotic strains and personalized dietary interventions.
Digestive Health Products Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the market's competitive structure. The industry displays a tiered structure, with established food and pharmaceutical giants alongside specialized biotech firms. Strategic archetypes include large diversified consumer health companies, focused probiotic ingredient suppliers, and agile personalized nutrition startups. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and product offerings.
Diversified consumer health conglomerates, such as Nestle SA, occupy significant market positions through extensive product portfolios and global distribution networks. Danone SA, a major player, leverages its expertise in fermented dairy and plant-based products to capture trends in digestive health. Bayer AG exemplifies the pharmaceutical research approach, applying its scientific capabilities to develop clinically supported consumer health solutions and ingredients. These entities anchor various segments, from functional foods to specialized dietary supplements.
| Leading Market Players |
|---|
| Nestle SA |
| Danone SA |
| Bayer AG |
| BASF SE |
| Arla Foods amba |
| Yakult Honsha Co. Ltd |
| Cargill Inc |
| Abbott Laboratories |
| Chr. Hansen Holding A/S |
| Others |
Cost & Logistics Intelligence
Specialized microbial strains, as a key raw material, significantly influence product formulation costs, translating into tiered pricing for premium synbiotic products downstream. Cold chain logistics further add to the cost structure for live probiotic formulations.
Pricing Analysis
Capacity additions in Asia, particularly in probiotic strain fermentation, are reshaping price floors for bulk ingredients. Value-based and subscription models dominate, with pricing differentiated by clinical validation and personalized formulation. Pricing pressure intensifies in the mass-market segment due to generic competition. Adults seeking general wellness are price-sensitive, while seniors and personalized nutrition subscribers accept higher prices.
Supply Chain Analysis
Domestic content mandates in certain Asian markets are reshaping sourcing strategies for digestive health ingredients. Supply concentrates in China and South Korea for novel microbial strains and functional fibers, relying on specialized fermentation facilities globally. Cold chain integrity for live probiotics presents a significant logistical chokepoint. Omnichannel distribution, balancing online platforms with traditional retail, characterizes downstream delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digestive Health Products Market offers significant margin expansion opportunities, primarily driven by the shift towards personalized nutrition platforms. These platforms command premium pricing through customized, evidence-backed formulations.
For Market Incumbents:
Acquire specialized biotech firms with novel microbial strain IP to counter agile personalized nutrition startups. Invest in rigorous human clinical trials to validate specific health claims, leveraging existing R&D capabilities. Diversify product portfolios to include targeted synbiotic formulations for specific demographics like Seniors. Control key distribution channels to maintain market visibility against new entrants.
For New Entrants and Emerging Players:
ANVISA's evolving functional food regulations in Brazil open a window for novel product introductions. Target the United States' digitally native consumer base with personalized microbiome analysis services. Focus on niche applications like gut-brain axis products for mental wellness. A direct-to-consumer model, integrating at-home testing kits, provides a strong go-to-market angle.
For Investors and Strategic Acquirers:
Consolidation pressure builds where scientific validation and regulatory compliance are paramount for market access. Long-term viability favors companies with strong clinical evidence and intellectual property for novel strains. Target specialized ingredient suppliers or personalized nutrition platforms with robust customer retention. FDA's evolving stance on Live Biotherapeutic Products serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Validates specific health claims, driving premium pricing and consumer trust. |
| Personalized Nutrition Platform Launch | Captures high-value recurring revenue through tailored consumer solutions. |
| Microbial Strain IP Acquisition | Secures proprietary technology for next-generation probiotic and synbiotic formulations. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail, enabling direct feedback and stronger customer relationships. |
| Regulatory Pathway Investment (e.g., FOSHU) | Accelerates market access in mature functional food markets like Japan. |
Research Approach
Direct dialogue with R&D directors, regulatory affairs specialists, product managers, and supply chain leads informed primary insights. This qualitative input was rigorously validated through extensive secondary research, including FDA filings, EFSA opinions, academic journals, and company annual reports. A comprehensive bottom-up and top-down triangulation approach ensured data accuracy and consistency across all market segments.
A bottom-up approach aggregated segment-level data, validated against top-down market sizing across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and distribution channel. Compound annual growth rates were derived from historical trends and projected market dynamics, integrating microbiome research advancements and consumer health awareness trends as key inputs.
Revisions become necessary when significant regulatory shifts, such as the FDA's stance on Live Biotherapeutic Products, materialize. Forecasts reflect assumptions based on current market dynamics; supply chain disruptions or unforeseen scientific breakthroughs could alter projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market
Gastroenterology
Global Gastrointestinal Stent Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Polyps Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Digestive Health Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market