
 Global Autoimmune Treatment Market | 2026-2036
Global Autoimmune Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autoimmune Treatment Market Foresight
Capital-intensity divergence between platform biologic manufacturers and small-molecule specialists is collapsing as biosimilar competition compresses margins across both categories. AbbVie leverages its immunology franchise infrastructure to sustain manufacturing scale advantages in monoclonal antibody production. Roche anchors its position through diagnostic-therapeutic integration in rheumatology and multiple sclerosis protocols. Bristol-Myers Squibb differentiates via checkpoint inhibitor expertise that extends into overlapping autoimmune indications.
Autoimmune treatment encompasses pharmacological interventions designed to modulate pathological immune responses, including biologics manufactured through mammalian cell culture systems requiring cold-chain distribution at two-to-eight degrees Celsius. These therapies primarily serve to interrupt cytokine signaling, deplete targeted lymphocyte populations, or suppress broader immune activation in chronic conditions. Monoclonal antibodies occupy the dominant margin pool due to premium pricing and extended dosing intervals that improve adherence. Biologics represent the fastest-expanding category as subcutaneous delivery formats reduce infusion center dependency. Disease-Modifying Antirheumatic Drugs maintain mature volume positions in cost-sensitive reimbursement environments despite biosimilar erosion.
FDA, EMA, and WHO frameworks collectively shape approval pathways, post-market surveillance obligations, and manufacturing quality standards for autoimmune therapies across jurisdictions. The EU MDR and FDA's evolving biosimilar interchangeability guidance are tightening evidence requirements that directly influence product labeling and market access timelines. Stakeholders must monitor how regulatory convergence on real-world evidence standards reshapes competitive positioning for novel mechanisms in lupus and Sjogren's Syndrome.
Market Dynamics
Biosimilar entry is compressing originator pricing power across tumor necrosis factor inhibitors and interleukin antagonists, forcing incumbents to defend position through formulation innovation and site-of-care expansion rather than patent exclusivity alone.
Growth Catalysts
- Subcutaneous delivery platforms:Self-administration formats reduce infusion center dependency and expand addressable patient populations in rural and suburban catchments across the United States, Germany, and Japan.
- EMA's evolving biosimilar interchangeability guidance:Streamlined substitution protocols in European markets accelerate physician comfort with switching, expanding volume access for follow-on biologics in rheumatology and dermatology.
- Specialty infusion network expansion:United States-based ambulatory infusion centers are adding capacity in secondary cities, creating new prescribing nodes for intravenous biologics in multiple sclerosis and inflammatory bowel disease.
Market Restraints
- Plasma-derived input volatility:Immunoglobulin therapies face supply uncertainty from donor pool concentration in the United States and Germany, with fractionation capacity acting as a binding constraint during demand surges.
- EMA MDR compliance burden:Device-drug combination products for subcutaneous administration face extended technical documentation requirements and notified body backlogs, delaying market entry for next-generation autoinjectors.
- Small-molecule JAK inhibitor safety surveillance:FDA black-box warnings on thromboembolic events have constrained prescriber enthusiasm, creating a ceiling on oral therapy penetration despite convenience advantages over injectables.
Strategic Opportunities
- India's biologics manufacturing capacity:Contract development and manufacturing organizations in Hyderabad and Bengaluru are building mammalian cell culture capabilities to serve European and North American markets seeking supply diversification.
- EU AI Act diagnostic pathways:Algorithmic tools for predicting treatment response in lupus nephritis qualify for streamlined conformity assessment, creating first-mover advantage for integrated diagnostic-therapeutic platforms.
- Home nursing channel development:Subcutaneous biologics enable direct-to-patient distribution models with cold-chain integrity maintained through specialized logistics partnerships, bypassing traditional hospital outpatient dependency.
Industry Challenges
- Cell line development expertise scarcity:Mammalian expression system optimization for complex glycosylation patterns requires rare skill sets concentrated at a handful of academic centers and established biologics manufacturers.
- Multi-jurisdiction pharmacovigilance harmonization:Divergent FDA, EMA, and PMDA requirements for real-world safety data collection force redundant surveillance infrastructure, inflating post-market compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autoimmune Treatment Market |
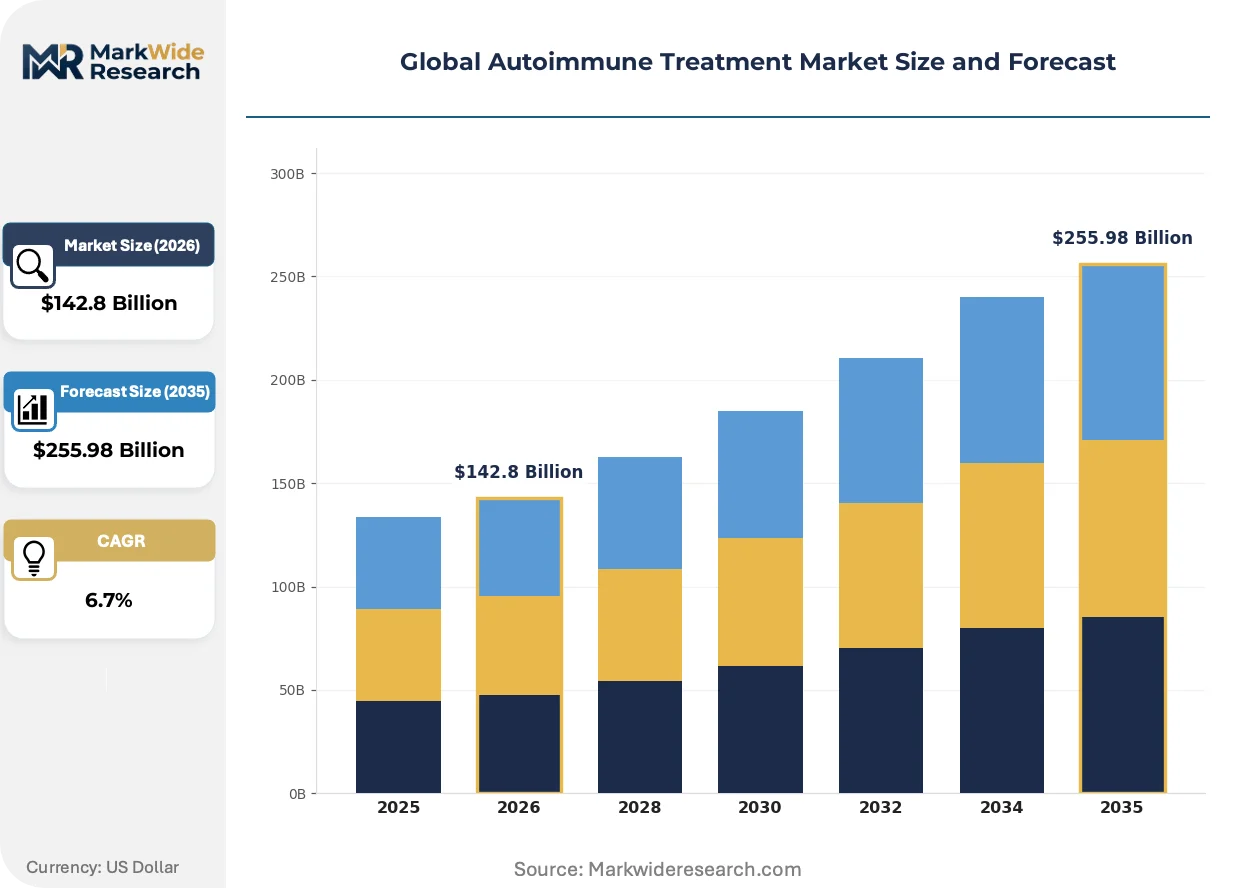
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $255.98 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Immunosuppressants, Corticosteroids, Disease-Modifying Antirheumatic Drugs, Biologics Therapy Area: Rheumatoid Arthritis, Lupus, Multiple Sclerosis, Psoriasis, Inflammatory Bowel Disease, Sjogren's Syndrome End User: Specialty Clinics, Research Laboratories, Rheumatology Centers, Outpatient Facilities Delivery Mode: Intravenous, Subcutaneous, Oral, Topical, Intramuscular |
| Companies Covered | AbbVie, Johnson & Johnson, Roche, Pfizer, Amgen, Bristol-Myers Squibb, AstraZeneca, Novartis, Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autoimmune Treatment Market Shifts & Advancements
Platform technologies are collapsing the traditional boundary between small-molecule and biologic development timelines, while regulatory convergence on real-world evidence standards is rewriting the competitive playbook for novel mechanism approval.
Bispecific antibody constructs are displacing monospecific formats in clinical pipelines for refractory rheumatoid arthritis and psoriatic arthritis. Large academic medical centers in the United States and university hospitals in Germany are accelerating enrollment in Phase II trials for these modalities. The technology is displacing legacy combination regimens that required sequential administration of separate agents, compressing treatment burden and site-of-care costs.
EMA's Medical Device Regulation implementation is tightening clinical evidence requirements for pre-filled syringes and wearable injectors used in chronic immunology indications. Manufacturers must now submit biological safety and human factors data that exceeds prior directive standards, extending development timelines by twelve to eighteen months for combination product submissions. Rheumatology practices in France and the Netherlands are delaying procurement decisions pending clarity on MDR certificate availability, creating temporary demand pauses for device-dependent therapies.
Hospital pharmacy committees are consolidating formulary control over high-cost biologics, shifting purchasing authority from individual prescribers to centralized value-assessment bodies. Integrated delivery networks in the United States are deploying therapeutic interchange protocols that override physician brand preference when biosimilar equivalents demonstrate equivalent immunogenicity profiles. This concentration is most pronounced in Medicare Advantage populations in Florida and Texas, where risk-bearing entities capture full margin from molecule selection decisions.
Global Autoimmune Treatment Market Segmentation
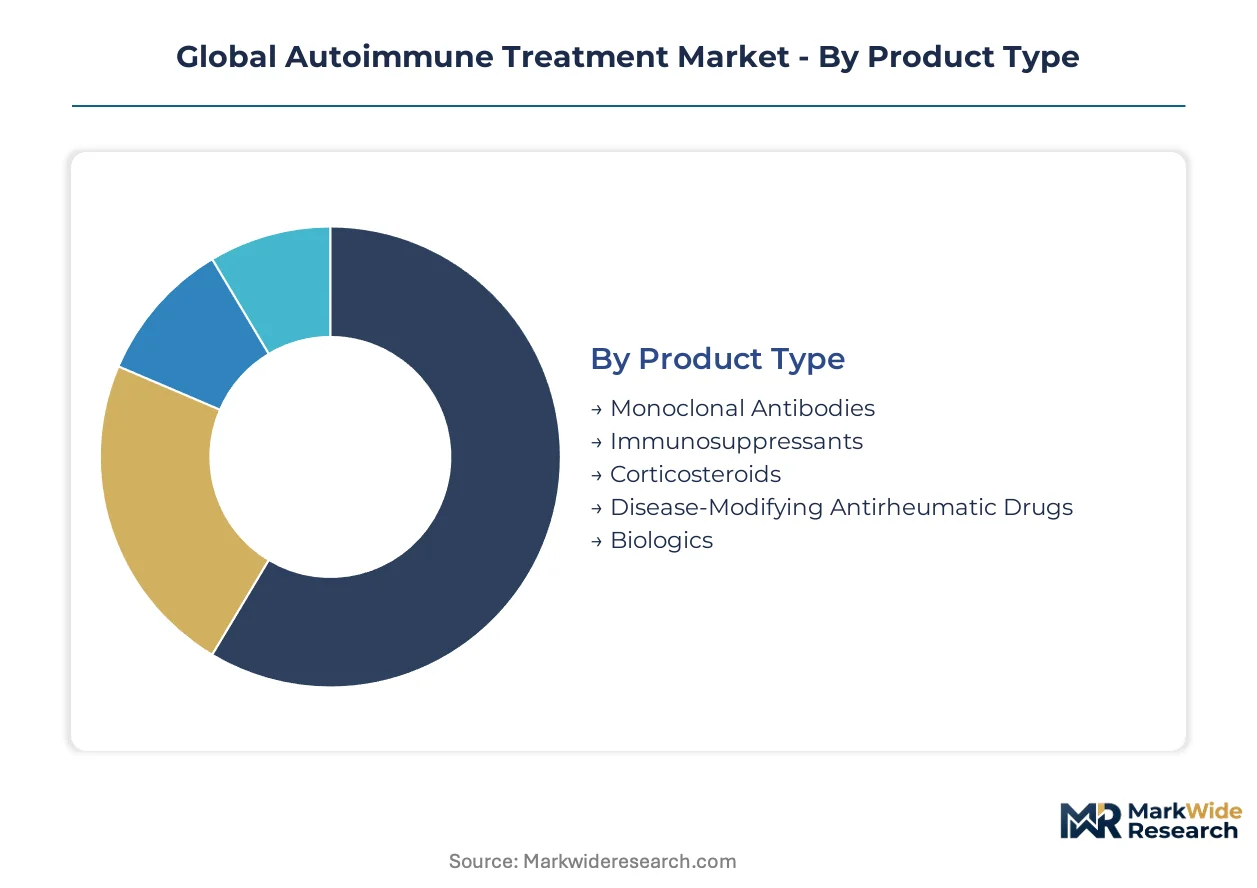
Autoimmune treatment segmentation reveals how pricing power, reimbursement pathways, and site-of-care economics fragment across product formats and delivery technologies. Understanding these divisions exposes where manufacturers can defend margin and where commoditization pressures concentrate.
Product Type:
Margin pools cluster in biologic formats commanding premium reimbursement through specialty pharmacy channels and protected cold-chain logistics.
- Monoclonal Antibodies:Engineered immunoglobulins targeting specific cytokine receptors or lymphocyte surface markers. United States specialty infusion networks in Florida and Texas drive concentrated demand for intravenous formulations with extended dosing intervals that reduce patient burden.
- Biologics:Protein-based therapeutics manufactured through mammalian cell culture requiring two-to-eight degrees Celsius distribution integrity. Self-administered subcutaneous devices are expanding addressable populations in German and Japanese suburban markets where infusion center access is limited.
- Immunosuppressants:Small-molecule agents suppressing broad immune activation through calcineurin or mTOR pathway inhibition.
- Corticosteroids:Synthetic glucocorticoid compounds managing acute inflammatory flares across multiple indications.
- Disease-Modifying Antirheumatic Drugs:Conventional synthetic agents including methotrexate and sulfasalazine maintaining volume positions in cost-sensitive reimbursement environments.
Monoclonal antibodies hold installed capacity. Biologics are rotating up the share rankings.
Therapy Area:
Volume concentration follows disease prevalence and diagnostic infrastructure maturity across major markets.
- Rheumatoid Arthritis:Chronic symmetric polyarthritis driven by autoantibody-mediated joint destruction. United States Medicare Advantage formularies and German statutory health insurance funds shape prescribing patterns for TNF inhibitors and IL-6 antagonists.
- Multiple Sclerosis:Demyelinating central nervous system disease with relapsing-remitting and progressive subtypes. French and Italian hospital neurology departments concentrate infusion capacity for anti-CD20 monoclonal antibodies.
- Lupus:Systemic autoimmune disease with heterogeneous organ involvement complicating trial design.
- Psoriasis:Chronic skin and joint inflammation with well-established biologic response criteria.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis requiring endoscopic monitoring alongside pharmacological management.
- Sjogren's Syndrome:Exocrine gland autoimmune attack with limited approved targeted therapies.
Rheumatoid arthritis commands the deepest formulary investment. Multiple sclerosis is climbing fastest in per-patient revenue contribution.
End User:
Site-of-care economics and prior authorization control points determine channel profitability.
- Specialty Clinics:Dedicated immunology and rheumatology practices managing complex biologic regimens. United States independent rheumatology groups in Texas and Arizona are consolidating into platform networks to negotiate directly with pharmacy benefit managers.
- Outpatient Facilities:Hospital-affiliated infusion centers capturing facility fees alongside drug reimbursement. German university hospital outpatient departments leverage integrated diagnostic-therapeutic protocols for multiple sclerosis patient capture.
- Rheumatology Centers:Academic and community-based practices with ultrasound and infusion capabilities.
- Research Laboratories:Clinical trial sites and reference laboratories supporting biomarker development.
Specialty clinics hold installed prescribing relationships. Outpatient facilities are rotating up the share rankings.
Delivery Mode:
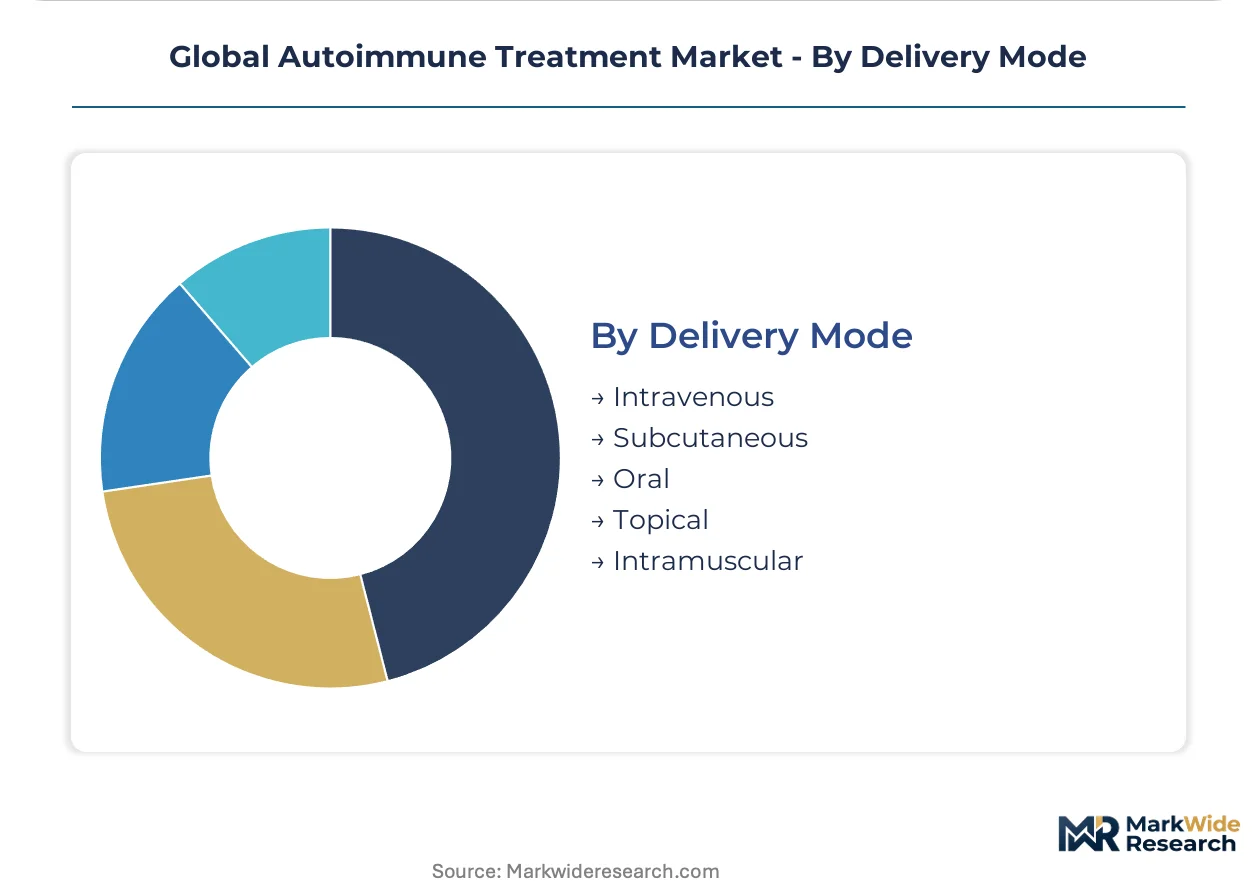
Convenience premiums and cold-chain requirements create divergent margin structures across administration formats.
- Subcutaneous:Self-administered injection via pre-filled syringe or wearable device enabling home delivery models. Japanese and United States rural patient populations drive expansion as infusion center dependency limits access.
- Intravenous:Infusion center administration with facility fee capture and nursing supervision requirements. German and French hospital outpatient departments maintain capacity concentration for rituximab and ocrelizumab protocols.
- Oral:Small-molecule formulations including JAK inhibitors facing FDA safety surveillance constraints.
- Topical:Localized corticosteroid and calcineurin inhibitor applications for limited skin involvement.
- Intramuscular:Depot formulations extending dosing intervals for corticosteroid maintenance.
Intravenous holds installed capacity. Subcutaneous is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in autoimmune therapeutics reflect concentrated manufacturing in developed economies and rising import dependency across emerging markets seeking supply diversification for biologics and biosimilars.
United States
Specialty infusion networks in Florida and Texas drive concentrated demand for intravenous biologics, while Medicare Advantage formularies consolidate purchasing authority under risk-bearing entities. FDA interchangeability guidance for biosimilars accelerates substitution protocols in rheumatology and dermatology. Boston's biologics manufacturing cluster anchors mammalian cell culture capacity serving domestic and export markets.
Germany
Statutory health insurance funds shape prescribing patterns for TNF inhibitors and IL-6 antagonists through centralized value assessment. EMA MDR compliance requirements extend technical documentation timelines for autoinjector combination products. Munich and Frankfurt host fractionation capacity for immunoglobulin therapies facing donor pool concentration constraints.
Japan
Rural patient populations drive expansion of subcutaneous self-administration formats where infusion center access is limited. PMDA requirements for real-world safety data collection shape post-market surveillance infrastructure. The Kanto region maintains diagnostic-therapeutic integration protocols in university hospital neurology departments.
India
Contract development organizations in Hyderabad and Bengaluru build mammalian cell culture capabilities to serve European and North American supply diversification strategies. CDSCO regulatory pathways for biosimilar approval attract manufacturing investment. The country's biologics export capacity is rotating up in global supply chain rankings.
United Kingdom
Hospital pharmacy committees consolidate formulary control over high-cost biologics under integrated care system frameworks. NICE technology appraisals determine reimbursement access for novel mechanisms in lupus and multiple sclerosis. The Golden Triangle research corridor accelerates enrollment in Phase II trials for bispecific antibody constructs.
Global Autoimmune Treatment Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates commanding immunology franchise infrastructure and diagnostic-therapeutic integration capabilities. The competitive structure spans three tiers: platform biologic manufacturers defending manufacturing scale advantages, small-molecule specialists facing margin compression from biosimilar entry, and emerging biosimilar developers exploiting streamlined EMA interchangeability protocols. Dominant competitive moves include site-of-care expansion to capture facility fees and formulation innovation extending dosing intervals.
Within the platform biologic tier, AbbVie, Roche, and Bristol-Myers Squibb exemplify divergent defensive strategies. AbbVie represents manufacturing scale concentration in monoclonal antibody production. Roche anchors diagnostic-therapeutic integration positioning in rheumatology protocols. Bristol-Myers Squibb occupies a position translating checkpoint inhibitor expertise into overlapping autoimmune indications.
| Leading Market Players |
|---|
| AbbVie |
| Johnson & Johnson |
| Roche |
| Pfizer |
| Amgen |
| Bristol-Myers Squibb |
| AstraZeneca |
| Novartis |
| Eli Lilly |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between specialty infusion networks and biologics manufacturers lock in supply access while capping price volatility for intravenous monoclonal antibodies. These contracts tether hospital outpatient departments to originator products even as biosimilar alternatives pressure list prices across rheumatology and dermatology indications.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the autoimmune treatment market. Price differentiation rests on cold-chain certification grade and dosing interval convenience, with subcutaneous autoinjectors commanding brand premiums over intravenous equivalents. Pricing pressure stems from EMA biosimilar interchangeability protocols accelerating physician switching in European markets. Medicare Advantage risk-bearing entities exhibit highest price sensitivity, while academic medical centers maintain lowest sensitivity due to formulary control independence.
Supply Chain Analysis
Mammalian cell culture capacity concentration in Boston, Basel, and Singapore underwrites global biologics output for autoimmune indications. Production draws from Chinese hamster ovary cell lines, single-use bioreactor systems, and plasma-derived immunoglobulin fractionation inputs. Single-source vulnerability concentrates in German and United States donor pools for immunoglobulin therapies. Distribution runs through cold-chain logistics partnerships maintaining two-to-eight degrees Celsius integrity from manufacturing sites to specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autoimmune treatment market sits at a platform-economics inflection where diagnostic-therapeutic integration protocols in German university hospitals and United States integrated delivery networks are collapsing traditional silos between biomarker testing and biologic prescribing.
For Market Incumbents: Shield manufacturing scale advantages by deepening backward integration into mammalian cell line development capabilities concentrated at academic centers in Boston and Basel. Lock in site-of-care expansion through exclusive capacity reservation agreements with ambulatory infusion networks in Florida and Texas, neutralizing biosimilar substitution threats through formulation innovation that extends dosing intervals beyond follow-on biologic reach.
For New Entrants and Emerging Players: Anchor in India's contract development and manufacturing organization capacity in Hyderabad and Bengaluru, exploiting supply diversification demand from European and North American markets seeking geographic risk distribution. Target subcutaneous delivery device development for lupus and Sjogren's Syndrome indications where approved targeted therapies remain limited, pursuing streamlined EU AI Act diagnostic-therapeutic platform conformity assessment as regulatory differentiation.
For Investors and Strategic Acquirers: Bispecific antibody construct developers with Phase II enrollment acceleration in United States academic medical centers represent priority acquisition archetypes. Long-term viability hinges on regulatory convergence toward real-world evidence standards that reward integrated diagnostic-therapeutic platforms over standalone biologic molecules. Watch EMA MDR certificate availability timelines for autoinjector combination products as inflection signal for device-dependent therapy market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Mammalian cell culture capacity expansion in Boston and Singapore secures supply continuity for monoclonal antibody output. |
| Regulatory Approval Pathway | EU AI Act streamlined conformity assessment creates first-mover positioning for algorithmic treatment response prediction tools. |
| Pipeline Diversification | Bispecific antibody constructs in refractory rheumatoid arthritis displace legacy combination regimens and compress site-of-care costs. |
| Licensing Agreement | Diagnostic-therapeutic integration protocols in German university hospitals anchor biomarker-guided biologic selection workflows. |
| Reimbursement Strategy | Medicare Advantage formulary placement in Florida and Texas determines volume capture under risk-bearing entity control. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across United States, German, and Japanese markets. Secondary validation drew from SEC 10-K disclosures, CMS Medicare utilization data, and GPO contract repositories. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Variance decomposition across therapy area, product format, delivery mode, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume-price elasticity modeling incorporating biosimilar entry curves, interchangeability adoption rates, and site-of-care shift parameters. Forecast inputs included EMA MDR implementation timelines, FDA interchangeability guidance evolution, and specialty infusion network capacity expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained biosimilar approval velocity and stable cold-chain logistics cost structures; material deviation in plasma-derived input availability or JAK inhibitor safety surveillance intensity would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act diagnostic pathway interpretation and PMDA real-world evidence requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Microwave Ablation Market