
 Ultrasound Gastroscopes Market | 2026-2036
Ultrasound Gastroscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Gastroscopes Market Outlook
Software-defined imaging analytics subscription tiers is consolidating revenue models across the ultrasound gastroscopes landscape. Olympus Corporation leverages its endoscope manufacturing scale to anchor premium hardware-software bundles in academic medical centers. KARL STORZ competes through rigid endoscope heritage extended into ultrasound-compatible platforms for hybrid operating rooms. Medtronic navigates the service layer through capital-light leasing structures that reduce upfront hospital expenditure.
Ultrasound gastroscopes combine high-frequency ultrasonic transducers with flexible endoscopic delivery systems, typically operating at 5-20 MHz to generate real-time cross-sectional images of gastrointestinal wall layers and adjacent organs for diagnostic and interventional procedures. The instruments enable fine-needle aspiration and therapeutic delivery under direct sonographic visualization. Therapeutic gastroscopes command margin concentration due to integrated instrument channels and electrosurgical compatibility required for advanced interventional endoscopy. Diagnostic procedures represent the volume base, though surgical guidance applications are expanding fastest as hospitals adopt intraoperative EUS for staging and margin assessment.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment and post-market surveillance for ultrasound endoscope systems entering European clinical settings. ISO 13485 quality management standards underpin manufacturing consistency across OEM and contract manufacturer networks. Stakeholders must monitor evolving reimbursement codes for endoscopic ultrasound procedures across Medicare and commercial payers to anticipate capital equipment purchasing cycles.
Market Dynamics
Software-defined imaging analytics is compressing traditional hardware-centric revenue models across the ultrasound gastroscopes landscape, forcing manufacturers to restructure around recurring subscription architectures rather than capital equipment sales cycles.
Growth Catalysts
- FDA 510(k) Clearance Pathways:Streamlined premarket notification processes for endoscopic ultrasound devices accelerate product development timelines and reduce regulatory uncertainty for manufacturers targeting the United States market.
- Hybrid Operating Room Expansion:Hospital infrastructure investments in integrated surgical suites create demand for ultrasound-compatible platforms that bridge diagnostic and interventional workflows.
- Pancreatic and Biliary Imaging Demand:Rising procedural volumes for gastrointestinal malignancy staging drive capital allocation toward therapeutic gastroscopes with fine-needle aspiration capabilities.
Market Restraints
- Capital Equipment Intensity:High upfront acquisition costs for therapeutic gastroscopes strain hospital budgets, particularly in community health systems with limited interventional endoscopy volumes.
- Supply Concentration Risk:German manufacturing clusters dominate precision transducer production, creating geographic vulnerability in component sourcing for North American and Asian OEMs.
- Technical Limitation in Depth Resolution:Operating frequency trade-offs between 5-20 MHz ranges constrain simultaneous optimization of superficial wall layer detail and deep organ penetration.
Strategic Opportunities
- EU Medical Device Regulation Tailwinds:MDR-mandated post-market surveillance and notified body conformity assessment create competitive moats for established manufacturers with robust quality management systems.
- Intraoperative EUS Adoption:Surgical guidance applications represent underpenetrated white space as hospitals integrate endoscopic ultrasound for real-time staging and margin assessment during oncologic resections.
- Artificial Intelligence Convergence:Machine learning-powered image interpretation layered onto hardware platforms enables automated lesion detection and measurement standardization.
Industry Challenges
- Interventional Endoscopy Skill Gap:Fine-needle aspiration and therapeutic delivery under sonographic visualization require specialized training pipelines that academic medical centers struggle to scale.
- ISO 13485 Certification Timelines:Quality management system audits and manufacturing consistency validations extend product launch schedules for contract manufacturer networks.
- Reimbursement Code Fragmentation:Divergent procedural coding across Medicare and commercial payers complicates hospital capital planning and equipment utilization forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Gastroscopes Market |
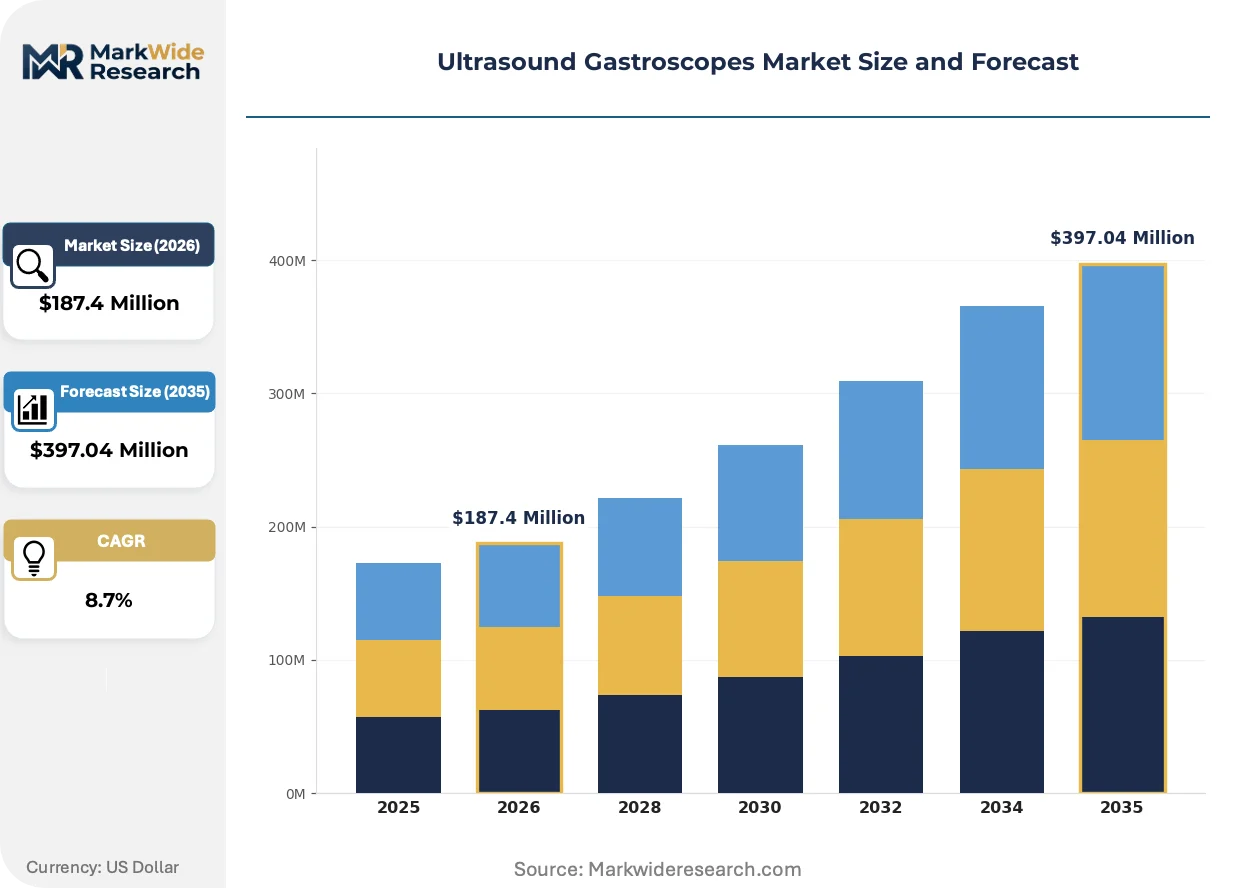
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Gastroscopes, Conventional Gastroscopes, Therapeutic Gastroscopes, Ultrasound Gastroscopes End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Application: Diagnostic Procedures, Therapeutic Procedures, Surgical Guidance, Biopsy Procedures Technology: Digital Imaging, Fiber Optic, Miniaturized Sensors, Advanced Processing |
| Companies Covered | Medtronic, KARL STORZ, Olympus Corporation, Steris, Cook Medical, FUJIFILM Holdings Corporation, Boston Scientific Corporation, CONMED Corporation, PENTAX Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Gastroscopes Market Strategic Shifts
Digital-native imaging platforms are displacing analog signal processing architectures across the ultrasound gastroscopes value chain, compressing development cycles and enabling over-the-air feature upgrades that extend equipment lifespans beyond traditional depreciation schedules.
Linear array transducers with electronic beam steering are rewriting performance benchmarks for superficial gastrointestinal wall imaging. Academic medical centers in Germany and Japan are deploying these platforms for sub-millimeter layer differentiation in early neoplasia detection. The technology is compressing the gap between diagnostic confidence and histopathological confirmation, reducing repeat endoscopy rates.
The EU Medical Device Regulation is mandating unique device identification and enhanced post-market clinical follow-up for ultrasound endoscope systems entering European clinical settings. Manufacturers must maintain systematic vigilance data and periodic safety update reports across their device portfolios. High-risk therapeutic gastroscopes face the steepest compliance burden, with notified body scrutiny intensifying for electrosurgical-compatible platforms.
Service unbundling is fragmenting traditional capital-plus-maintenance contracts into discrete software subscription, hardware lease, and per-procedure consumable tiers. Hospital procurement functions in the United States are negotiating these modular arrangements to align cash outflows with utilization volumes. Community health systems lacking dedicated interventional endoscopy programs favor this structure to mitigate stranded asset risk.
Ultrasound Gastroscopes Market Segmentation
Ultrasound gastroscope procurement patterns diverge sharply across clinical settings and technical specifications. Capital allocation decisions hinge on whether institutions prioritize diagnostic throughput, interventional capability, or research-grade imaging resolution.
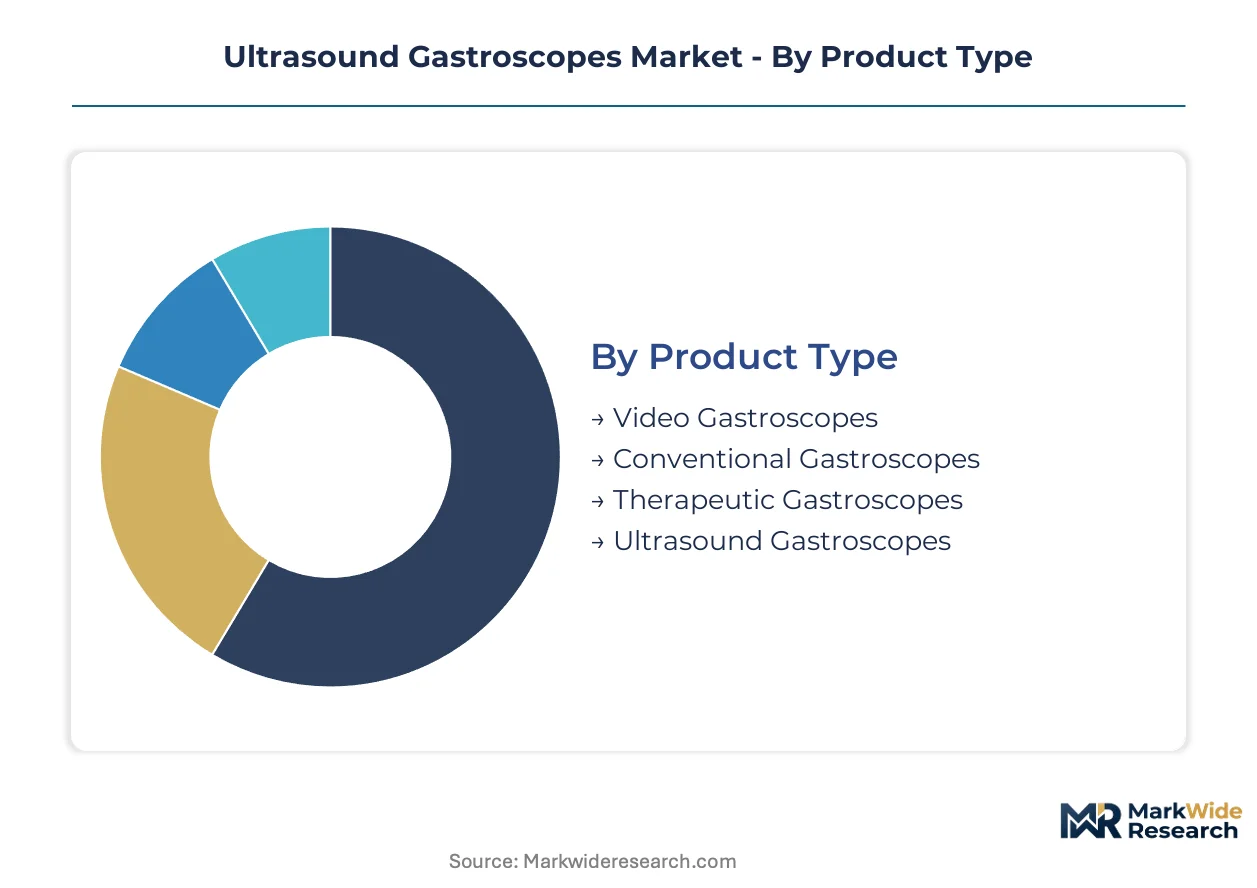
Product Type:
Capital intensity escalates dramatically from basic visualization platforms to full-spectrum therapeutic systems with integrated ultrasound and electrosurgical channels.
- Video Gastroscopes:High-definition digital sensors deliver real-time mucosal visualization with white-light and narrow-band imaging modes. Community hospitals in Germany standardize on these platforms for routine upper GI screening, constrained by reimbursement ceilings that limit upgrade frequency.
- Therapeutic Gastroscopes:Multi-channel architectures accommodate biopsy forceps, injection needles, and electrosurgical instruments while maintaining sonographic capability. Academic medical centers in Japan deploy these for endoscopic submucosal dissection, where instrument channel diameter and irrigation flow rates determine procedural feasibility.
- Conventional Gastroscopes:Fiber-optic bundles provide cost-efficient entry-level visualization for high-volume screening programs.
- Ultrasound Gastroscopes:Curved linear array transducers operating at 5-20 MHz enable real-time cross-sectional imaging of gastrointestinal wall layers and adjacent organs.
Most installed capacity flows through Video Gastroscopes. Expansion is steepest in Therapeutic Gastroscopes.
End User:
Procurement authority concentrates differently across settings—centralized capital committees govern hospital purchases while clinic acquisitions follow physician preference item pathways.
- Hospitals:Integrated health systems negotiate enterprise-wide contracts bundling equipment, software subscriptions, and technical service. German university hospitals anchor demand for hybrid operating room configurations that merge endoscopic ultrasound with surgical navigation systems.
- Diagnostic Centers:Ambulatory surgery centers prioritize throughput metrics and rapid turnover capabilities. United States-based multi-site operators favor leasing structures that convert capital expenditure to per-procedure costs aligned with CMS reimbursement cycles.
- Clinics:Solo and group practices concentrate on portable systems with simplified maintenance requirements.
- Research Institutions:Preclinical and clinical trial units demand customizable imaging protocols and raw data export capabilities.
Volume concentrates in Hospitals. Procurement velocity is climbing fastest at Diagnostic Centers.
Application:
Reimbursement coding fragmentation across procedure types creates divergent equipment utilization economics and replacement cycle timing.
- Diagnostic Procedures:Screening and surveillance endoscopy with ultrasound augmentation for submucosal lesion characterization. Japanese national screening programs for gastric cancer drive installed base density, where detection sensitivity thresholds mandate frequent platform refresh cycles.
- Surgical Guidance:Intraoperative EUS for real-time tumor staging and margin assessment during oncologic resections. German surgical oncology departments integrate these workflows into pancreatic and hepatobiliary protocols, requiring compatibility with sterile field requirements.
- Therapeutic Procedures:Fine-needle aspiration, celiac plexus neurolysis, and cyst drainage under sonographic guidance.
- Biopsy Procedures:Tissue acquisition for histopathological confirmation with needle trajectory optimization.
Procedure volume clusters in Diagnostic applications. Investment intensity is shifting toward Surgical Guidance.
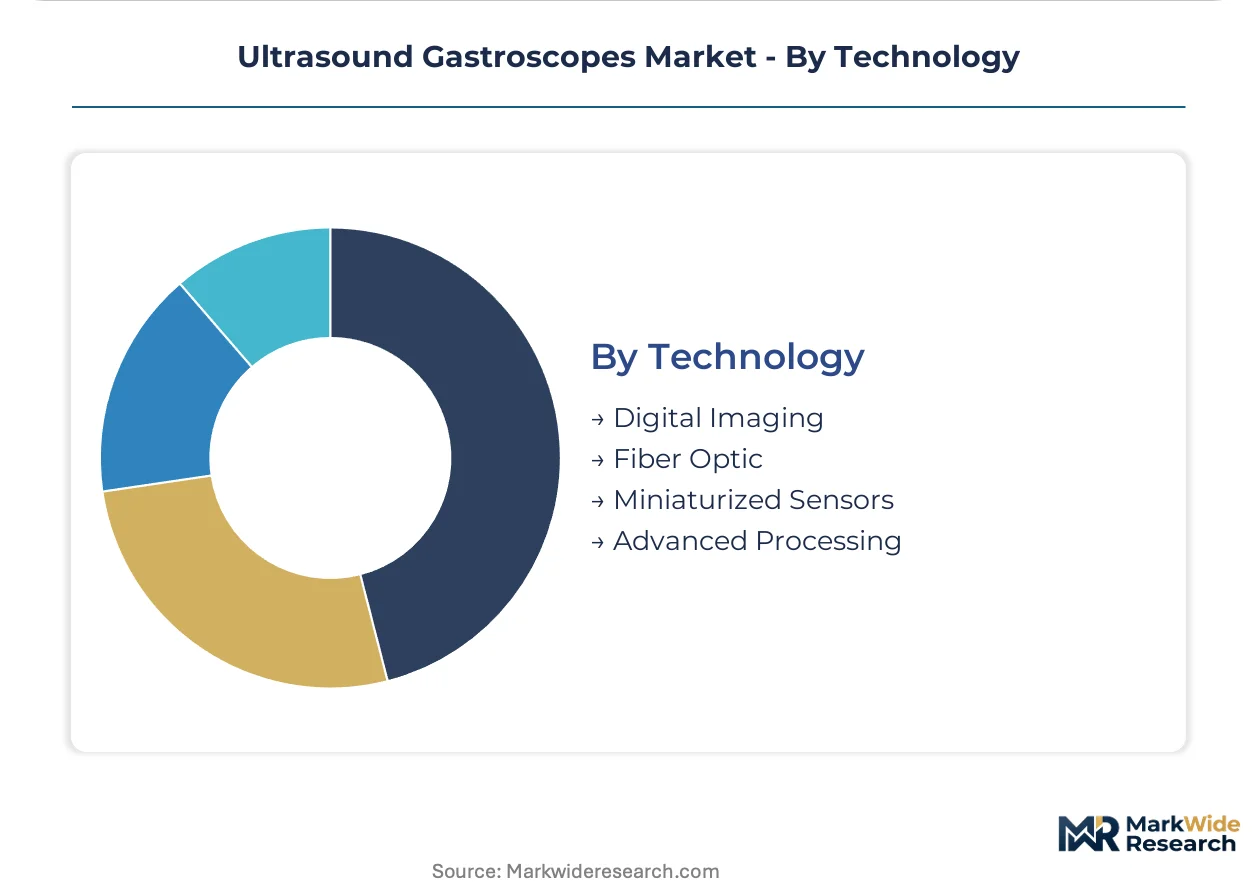
Technology:
Platform architecture choices determine upgrade pathways—proprietary ecosystems lock in subsequent purchasing decisions while open standards preserve flexibility.
- Digital Imaging:CMOS and CCD sensors with computational enhancement algorithms for contrast and edge definition. United States academic centers demand AI-compatible platforms with standardized DICOM output for integration with institutional PACS infrastructure.
- Advanced Processing:Real-time image reconstruction, noise reduction, and automated lesion detection pipelines. Japanese OEMs lead in embedding machine learning inference directly on device, reducing latency for time-critical interventional decisions.
- Fiber Optic:Traditional illumination and image transmission through coherent fiber bundles for cost-sensitive deployments.
- Miniaturized Sensors:Reduced-diameter transducer assemblies enabling pediatric and transnasal applications.
Deployment concentrates in Digital Imaging. Capability investment is accelerating most quickly in Advanced Processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters supply transducer assemblies to United States hospitals, while Japan's academic medical centers drive therapeutic procedure innovation. Regulatory pathways in both markets shape equipment certification timelines and capital procurement cycles.
United States
FDA 510(k) premarket notification pathways streamline clearance for endoscopic ultrasound devices, reducing regulatory uncertainty for manufacturers. Medicare reimbursement codes for EUS procedures influence hospital capital planning and equipment utilization forecasting. Academic medical centers in Boston and the Research Triangle anchor demand for hybrid operating room configurations with integrated surgical navigation.
Germany
EU Medical Device Regulation mandates notified body conformity assessment and enhanced post-market surveillance for ultrasound endoscope systems. KARL STORZ maintains manufacturing and clinical training infrastructure in Tuttlingen, anchoring precision transducer production for European and export markets. University hospitals in Munich and Heidelberg drive adoption of intraoperative EUS for pancreatic and hepatobiliary oncology protocols.
Japan
PMDA regulatory frameworks govern medical device approval timelines for endoscopic ultrasound platforms. National gastric cancer screening programs mandate high detection sensitivity thresholds, accelerating platform refresh cycles in Tokyo and Osaka metropolitan areas. Olympus Corporation leverages endoscope manufacturing scale to serve domestic academic medical centers with premium hardware-software bundles.
China
NMPA medical device registration requirements shape market entry timelines for international ultrasound gastroscope manufacturers. Hospital infrastructure investments in tier-one cities create demand for diagnostic and interventional endoscopy platforms. Shanghai and Beijing medical centers integrate EUS workflows into gastrointestinal malignancy staging protocols.
India
CDSCO medical device regulations govern import and distribution of endoscopic ultrasound equipment. Private hospital chains in Mumbai and Delhi expand interventional endoscopy programs, driving capital allocation toward therapeutic gastroscopes with fine-needle aspiration capabilities. Diagnostic centers concentrate procurement decisions on throughput metrics and rapid turnover capabilities.
Ultrasound Gastroscopes Market Competitive Environment
Top-tier vendors anchor premium hardware-software bundles in academic medical centers, while mid-tier specialists compete on capital-light leasing structures and service unbundling. The vendor base stratifies across three archetypes: diversified medical technology conglomerates with endoscope manufacturing heritage, rigid endoscope specialists extending into ultrasound-compatible platforms, and interventional device companies navigating the service layer. Competitive moves concentrate on M&A for imaging analytics capabilities and strategic partnerships for AI-powered lesion detection.
Within the diversified conglomerate tier, Olympus Corporation and FUJIFILM Holdings Corporation occupy positions anchored by endoscope manufacturing scale and digital imaging heritage. KARL STORZ exemplifies the rigid-to-flexible extension archetype, leveraging precision transducer production from its German manufacturing base. Medtronic represents the capital-light service model, structuring leasing arrangements that convert upfront expenditure to recurring revenue streams aligned with hospital utilization patterns.
| Leading Market Players |
|---|
| Medtronic |
| KARL STORZ |
| Olympus Corporation |
| Steris |
| Cook Medical |
| FUJIFILM Holdings Corporation |
| Boston Scientific Corporation |
| CONMED Corporation |
| PENTAX Medical |
| Others |
Value Chain & Pricing Dynamics
Captive transducer production in Germany anchors both supply security and premium pricing power for therapeutic gastroscope manufacturers serving academic medical centers. This backward integration into precision ultrasonic component manufacturing insulates leading OEMs from input volatility while supporting hardware-software bundle premiums.
Pricing Analysis
Capacity additions in China's diagnostic equipment sector are reshaping price floors for entry-level ultrasound gastroscopes, compressing margins on conventional platforms while therapeutic systems maintain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared therapeutic systems with electrosurgical compatibility from basic diagnostic platforms and refurbished legacy units. Price differentiation rests on ISO 13485 certification tier and instrument channel specifications. Pricing pressure stems from hospital procurement committees demanding per-procedure leasing models. Community health systems exhibit highest price sensitivity; hybrid operating room programs show lowest.
Supply Chain Analysis
Regional distribution centers in Tuttlingen, Stuttgart, and Singapore coordinate hub-and-spoke patterns for precision transducer assemblies and endoscopic insertion tube components. Manufacturing concentrates in Germany, Japan, and the United States for curved linear array transducers, CMOS imaging sensors, and electrosurgical instrument channels. Raw material dependencies include piezoelectric ceramics, specialized optical fibers, and medical-grade polymers. Single-source vulnerability in 5-20 MHz transducer crystal supply creates concentration risk. Distribution runs through manufacturer-direct sales for hospital systems and specialized medical device distributors for ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasound gastroscopes market represents a late-cycle quality story as hospital capital allocation shifts toward surgical guidance platforms with integrated AI compatibility and enhanced post-market surveillance documentation.
For Market Incumbents: Deploy software subscription layering to defend installed base relationships against capital-light leasing entrants. Consolidate position through ISO 13485 certification investments that create MDR compliance moats. Backward integration into transducer crystal supply reduces single-source exposure. Channel control through exclusive clinical training partnerships protects academic medical center relationships. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass entrenched GPO contracts and accelerate ambulatory surgery center penetration. White-space concentrates in portable diagnostic platforms for community gastroenterology practices lacking interventional endoscopy volumes. Target India's private hospital chains expanding EUS programs in Mumbai and Delhi. Partner with regional distributors for CDSCO registration support and service infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for imaging analytics specialists because software-defined platforms fragment traditional hardware revenue pools and create recurring revenue multiples. Five-to-ten year viability hinges on AI-powered lesion detection capabilities replacing manual interpretation. Target acquisition archetype: digital-native imaging platforms with FDA 510(k) pathway experience. Monitor NMPA registration timelines for international manufacturers as inflection signal for China market access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification streamlining reduces regulatory uncertainty for therapeutic platform launches in United States academic centers. |
| CE Marking Pathway Investment | EU MDR conformity assessment builds competitive moats through enhanced post-market surveillance and unique device identification mandates. |
| Hospital System Partnership | Enterprise-wide contracts bundling equipment, software subscriptions, and technical service secure multi-year revenue visibility. |
| Software Companion Development | AI-powered image interpretation layered onto hardware enables automated lesion detection and measurement standardization for clinical workflows. |
| Reimbursement Strategy | CPT code optimization for endoscopic ultrasound procedures aligns capital equipment purchasing cycles with Medicare and commercial payer schedules. |
Study Parameters
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records; plus trade data from German medical device export statistics — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, end user, application, and technology dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume and value modeling with cross-validation against installed base refresh cycles and procedural volume trajectories. Forecast inputs incorporated hybrid operating room infrastructure investment pipelines and evolving EU MDR compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for AI-embedded imaging platforms would alter the outlook if regulatory validation timelines extend or clinical acceptance lags. Forecasts reflect documented assumptions regarding reimbursement stability and transducer manufacturing capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Global Gastrointestinal Stent Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Crohns Disease Therapeutics Market