
 Opioid Induced Constipation Treatment Market | 2026-2036
Opioid Induced Constipation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Opioid Induced Constipation Treatment Market Outlook
Asset-light licensing and royalty-based partnership structures are reshaping competitive dynamics in gastrointestinal therapeutics, enabling smaller developers to retain intellectual property while outsourcing commercial infrastructure. Takeda Pharmaceutical Company Limited leverages its established gastroenterology salesforce to sustain hospital formulary access across multiple continents. Pfizer Inc. anchors its position through manufacturing scale and broad therapeutic portfolio cross-selling. Shionogi & Co Ltd differentiates via concentrated R&D investment in peripheral-acting mu-opioid receptor antagonists.
Opioid induced constipation treatment encompasses pharmacological and device-based interventions designed to counteract reduced gastrointestinal motility resulting from mu-opioid receptor activation in the enteric nervous system, with formulations typically targeting chloride channel activation, guanylate cyclase-C agonism, or selective opioid receptor antagonism to restore bowel function without compromising central analgesia. Prescription medications dominate value capture due to patent-protected novel mechanisms and mandatory prescriber involvement, while medical devices represent an emerging structural category where bioelectronic stimulation and implanted neuromodulation systems are gaining procedural traction in refractory populations. Oral delivery mode retains the largest volume footprint, though intravenous formulations command premium positioning in acute care transitions where rapid onset offsets higher administration costs.
The FDA's REMS program for extended-release opioids and EMA's pharmacovigilance requirements for bowel dysfunction reporting collectively elevate the standard of care documentation, creating compliance-driven demand for combination therapy protocols that integrate laxation management into initial opioid prescribing. Health Canada and Australia's TGA maintain aligned vigilance systems that reinforce multinational protocol standardization for hospital and homecare segments. Stakeholders must monitor evolving pharmacoeconomic thresholds for combination therapy reimbursement as payers tighten prior authorization criteria across public and private coverage frameworks.
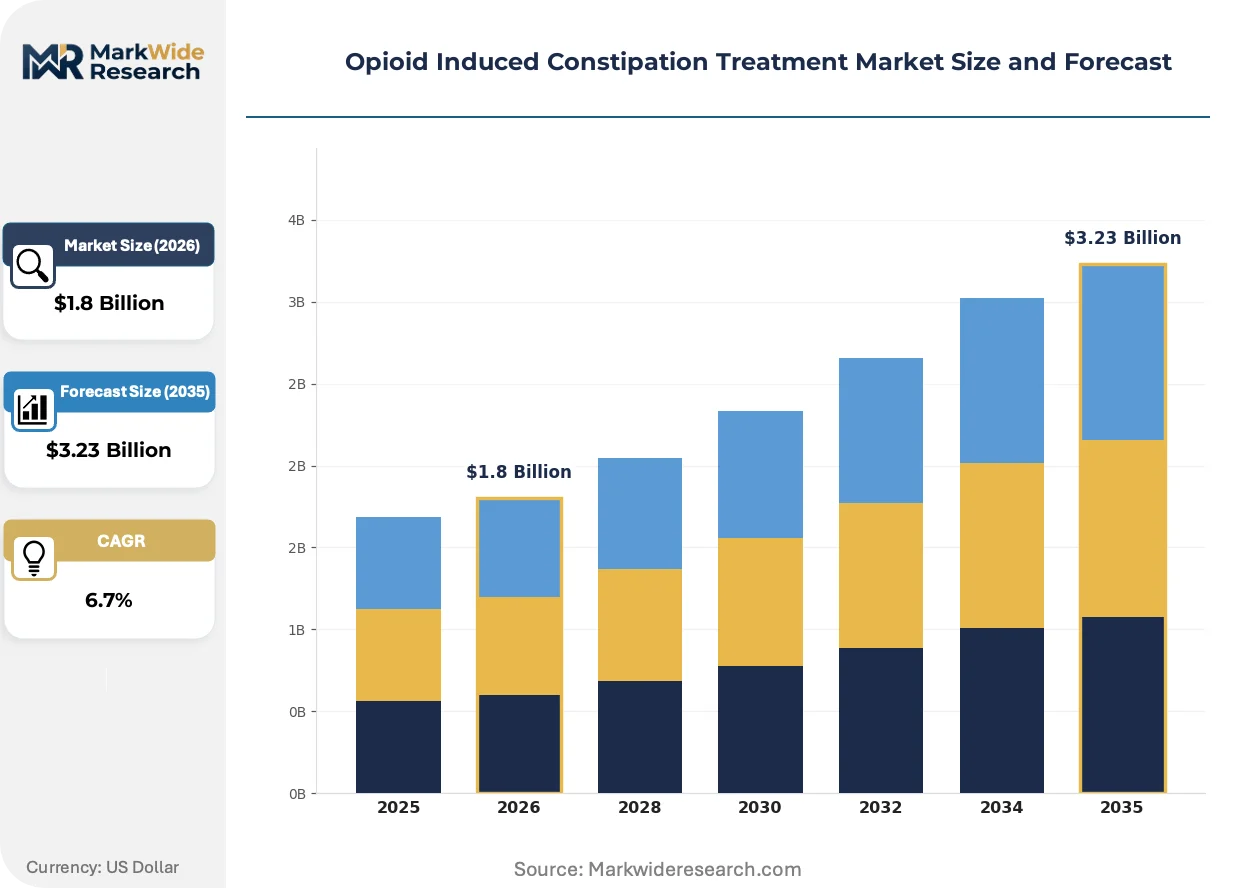
Market Dynamics
The FDA's REMS requirements for extended-release opioids are forcing hospital systems to bundle constipation prophylaxis into initial pain management protocols, creating structural demand pull for peripherally acting mu-opioid receptor antagonists and chloride channel activators.
Growth Catalysts
- Oncology pain management expansion:Hospital-based cancer centers in the United States are integrating targeted laxative protocols into standard-of-care pathways for patients on high-dose opioid regimens.
- EMA pharmacovigilance mandates:Bowel dysfunction reporting requirements across European member states are elevating documentation standards and driving combination therapy adoption.
- Homecare segment maturation:Subcutaneous formulations enabling self-administration are extending treatment continuity beyond acute care transitions.
Market Restraints
- Prior authorization tightening:Private and public payers in the United States are erecting formulary barriers to novel mechanisms, favoring generic osmotic laxatives.
- API supply concentration:Active pharmaceutical ingredient manufacturing for guanylate cyclase-C agonists clusters in China, exposing sponsors to geopolitical and quality audit risks.
- Central analgesia trade-off fears:Prescriber hesitation around opioid receptor antagonism limits penetration in palliative care settings where pain control dominates clinical priorities.
Strategic Opportunities
- Refractory population devices:Bioelectronic stimulation systems for patients failing pharmacological intervention represent an underdeveloped procedural category with premium reimbursement potential.
- Japan's aging demographic:METI-supported chronic pain management initiatives are expanding the addressable patient base for combination therapies in East Asia's most mature pharmaceutical market.
- Digital therapeutic bundling:Smartphone-based bowel diary apps paired with prescription initiation are creating adherence-linked reimbursement models in German statutory health insurance.
Industry Challenges
- Gastroenterology-specialized salesforce scarcity:Recruitment of hospital liaison personnel with dual expertise in oncology and GI therapeutics constrains launch velocity for novel entrants.
- REMS compliance infrastructure:Mandatory prescriber certification and patient registry maintenance impose fixed cost burdens that disadvantage smaller developers without Takeda-scale operational platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioid Induced Constipation Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, OTC Products, Dietary Supplements, Medical Devices Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Homecare Settings, Nursing Facilities Treatment Approach: Pharmacological Therapy, Non-Pharmacological Therapy, Combination Therapy, Supportive Care |
| Companies Covered | AstraZeneca plc, Pfizer Inc., Takeda Pharmaceutical Company Limited, Shionogi & Co Ltd, Bausch Health Companies Inc., Merck & Co Inc, RedHill Biopharma Ltd., Mallinckrodt Pharmaceuticals, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioid Induced Constipation Treatment Market Strategic Shifts
Digital health integration and mechanism-of-action diversification are compressing development timelines while expanding the addressable patient population beyond traditional oral laxative responders.
Implanted gastric neuromodulation systems are digitizing the management algorithm for refractory cases. Academic medical centers in the United States are piloting these devices in patients who have exhausted peripheral-acting mu-opioid receptor antagonist options. The technology is digitizing patient-reported outcome capture and enabling remote therapeutic monitoring that reduces emergency department utilization.
Health Canada's alignment with FDA REMS documentation standards is harmonizing North American prescribing protocols. This regulatory convergence is simplifying cross-border clinical trial design and accelerating sponsor submissions for combination indications. Canadian provincial formularies are responding by loosening step-therapy requirements for patients with documented laxative failure.
Hospital procurement committees are unbundling constipation management from bundled pain management contracts. Oncology departments in Germany and France are negotiating standalone agreements for PAMORA agents rather than accepting bundled pharmacy allocations. This shift is most visible in tertiary care centers with dedicated supportive care divisions where clinical pharmacy oversight has expanded.
Opioid Induced Constipation Treatment Market Segmentation
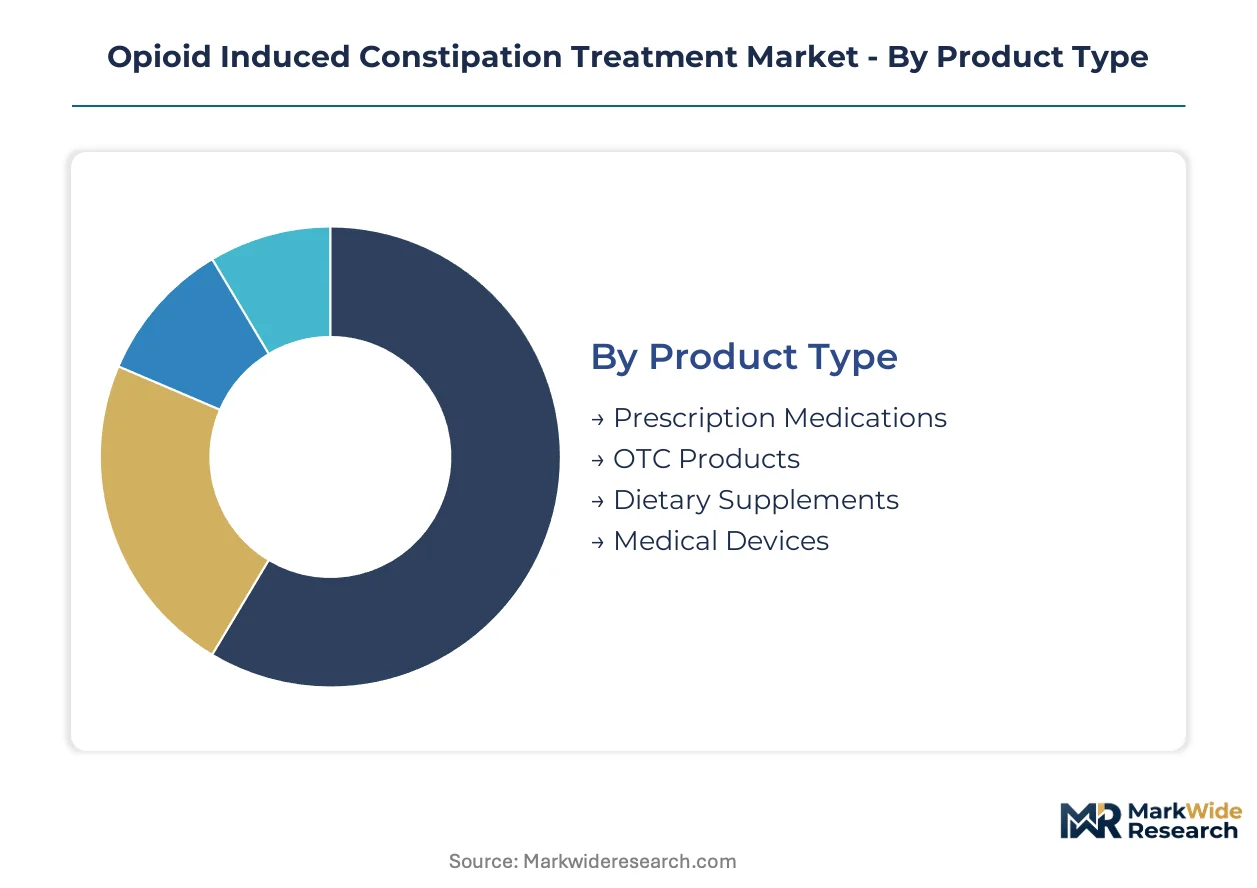
Segmentation in opioid induced constipation treatment reveals how reimbursement pathways, clinical setting economics, and mechanism-of-action preferences partition commercial opportunity. Each dimension exposes distinct margin structures and regulatory exposure profiles that shape portfolio prioritization.
Product Type:
The use-case spectrum spans acute rescue interventions through chronic maintenance regimens, with reimbursement intensity varying by prescriber control and patent status.
- Prescription Medications:Patent-protected PAMORAs and guanylate cyclase-C agonists command premium formulary positioning through mandatory prescriber involvement. Hospital oncology departments in the United States drive concentrated demand as REMS-compliant protocols bundle these agents into initial opioid prescribing.
- Medical Devices:Bioelectronic stimulation systems and implanted neuromodulation platforms address refractory populations failing pharmacological intervention. Tertiary care centers with dedicated supportive care divisions pilot these technologies where prior authorization barriers block novel drug access.
- OTC Products:Osmotic laxatives and stool softeners accessible without prescription dominate volume in homecare transitions but face margin compression from private label substitution.
- Dietary Supplements:Fiber formulations and probiotic blends occupy a regulatory gray zone with limited clinical validation, capturing patient self-directed demand outside reimbursed care pathways.
Established volume favors OTC products; emerging adoption favors prescription medications.
Delivery Mode:
Cost tier differentiation separates acute intervention premiums from chronic maintenance economies.
- Oral:Tablet and capsule formulations dominate outpatient dispensing volumes through pharmacy benefit coverage. Subcutaneous autoinjector development is compressing the acute-chronic boundary for self-administration.
- Intravenous:Hospital-administered formulations targeting rapid onset in perioperative and acute care transitions command the highest per-dose reimbursement. Oncology infusion centers represent concentrated demand nodes.
- Injectable:Intramuscular and subcutaneous depot formulations extend dosing intervals for nursing facility populations with medication adherence challenges.
- Transdermal:Patch-based delivery remains experimental for this indication, with limited commercial penetration due to absorption variability across opioid-induced gastrointestinal slowing.
Oral delivery captures the widest patient base; intravenous administration extracts the highest per-treatment value.
End User:
Customer type fragmentation reflects diverging procurement authority and clinical oversight intensity.
- Hospitals:Integrated cancer centers and surgical services drive protocol-standardized adoption of PAMORAs through pharmacy and therapeutics committee control. REMS documentation requirements concentrate prescribing within institutional settings.
- Homecare Settings:Subcutaneous formulation availability is extending treatment continuity post-discharge, though reimbursement fragmentation across Medicare Part B and commercial plans complicates access.
- Clinics:Pain management and gastroenterology specialty practices manage stable chronic populations with oral maintenance regimens, facing prior authorization friction for novel mechanisms.
- Nursing Facilities:Long-term care pharmacies negotiate bundled pricing for osmotic laxatives, with limited penetration of patent-protected agents due to per-diem reimbursement constraints.
Hospital procurement commands premium positioning; homecare expansion offers the steepest volume trajectory.
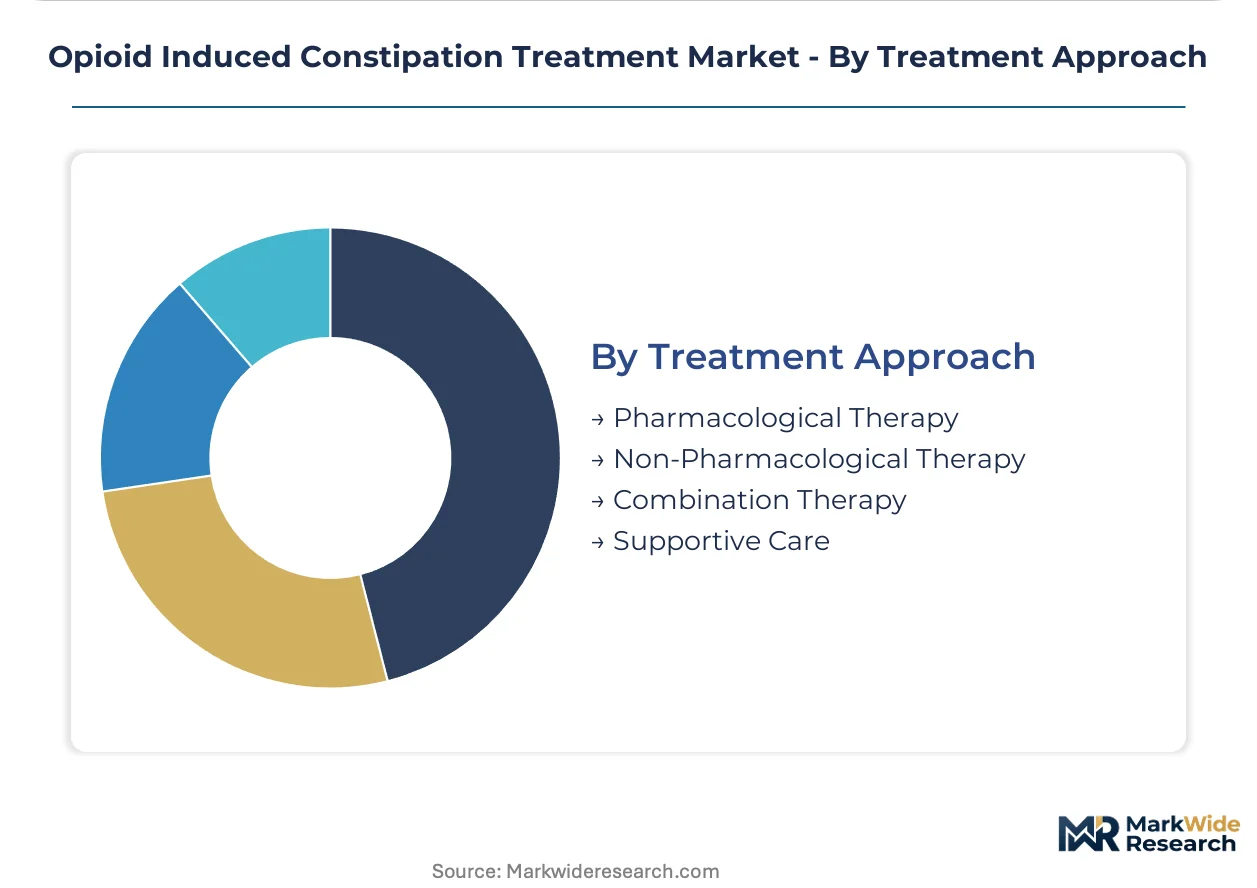
Treatment Approach:
Maturity gradients separate evidence-validated protocols from emerging combination strategies.
- Pharmacological Therapy:Mu-opioid receptor antagonism, chloride channel activation, and guanylate cyclase-C agonism constitute the validated armamentarium with established FDA and EMA approvals.
- Combination Therapy:Concurrent opioid analgesia with prophylactic laxation management is gaining protocol adoption as REMS requirements reshape initial prescribing patterns.
- Non-Pharmacological Therapy:Bioelectronic stimulation and behavioral interventions occupy adjunctive roles with limited standalone reimbursement.
- Supportive Care:Hydration protocols and dietary modification remain foundational but lack specific coding for standalone reimbursement.
Pharmacological therapy anchors current revenue; combination protocols are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in finished opioid induced constipation therapeutics, importing bulk active pharmaceutical ingredients while exporting patent-protected formulations to Canada, Germany, and Japan. European markets show balanced cross-border flows of guanylate cyclase-C agonists and peripheral-acting mu-opioid receptor antagonists between member states.
United States
Oncology pain management expansion and REMS-mandated bundling drive concentrated demand from hospital systems. FDA documentation requirements for extended-release opioids reshape prescribing patterns across integrated delivery networks. The Cleveland Clinic and MD Anderson Cancer Center anchor protocol standardization efforts in tertiary care.
Germany
Statutory health insurance reimbursement for digital therapeutic bundling creates unique access pathways. EMA pharmacovigilance mandates elevate bowel dysfunction reporting standards nationwide. Berlin and Munich hospital clusters pilot smartphone-based adherence monitoring linked to prescription coverage.
Japan
METI-supported chronic pain initiatives expand the addressable base for combination therapies. PMDA accelerated review pathways for supportive care agents compress regulatory timelines. Osaka and Tokyo metropolitan hospitals concentrate demand for subcutaneous autoinjector formulations.
Canada
Health Canada alignment with FDA REMS standards harmonizes North American prescribing documentation. Provincial formularies loosen step-therapy requirements for documented laxative failure cases. Toronto and Vancouver academic medical centers lead implanted neuromodulation pilot programs.
Australia
TGA vigilance systems reinforce multinational protocol standardization for homecare segments. Subcutaneous formulation reimbursement under Pharmaceutical Benefits Scheme extends treatment continuity post-discharge. Melbourne and Sydney pain management clinics concentrate demand for rapid-onset rescue interventions.
Opioid Induced Constipation Treatment Market Competitive Environment
On the supply side, the industry is consolidating around gastroenterology-specialized salesforces and REMS compliance infrastructure. Large-cap pharmaceutical companies anchor hospital formulary access through manufacturing scale and therapeutic portfolio breadth. Mid-cap developers occupy licensing-focused positions with concentrated R&D investment. Competitive moves center on asset-light partnership structures and digital therapeutic bundling to extend reach beyond traditional commercial infrastructure.
Within the large-cap tier, Takeda Pharmaceutical Company Limited and Pfizer Inc. exemplify divergent scale strategies. Takeda leverages established gastroenterology salesforce presence across multiple continents. Pfizer anchors positioning through manufacturing scale and broad therapeutic portfolio cross-selling. Shionogi & Co Ltd occupies a specialized position with concentrated investment in peripheral-acting mu-opioid receptor antagonists.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| Shionogi & Co Ltd |
| Bausch Health Companies Inc. |
| Merck & Co Inc |
| RedHill Biopharma Ltd. |
| Mallinckrodt Pharmaceuticals |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient manufacturing for guanylate cyclase-C agonists clusters in China, concentrating upstream margin capture with contract manufacturers while downstream value pools with patent-protected formulation sponsors in the United States and Japan. Hospital procurement committees exploit this bifurcation to extract volume discounts from finished goods suppliers while accepting pass-through API cost volatility.
Pricing Analysis
Hospital systems anchor pricing negotiations through pharmacy and therapeutics committee control, extracting tiered rebates based on formulary tier placement and REMS compliance documentation. Price differentiation hinges on patent status and prescriber certification requirements, with generic osmotic laxatives facing acute margin compression from private label substitution. Pricing pressure intensifies as Medicare Part D plans tighten prior authorization criteria for PAMORA agents. Oncology departments demonstrate lowest price sensitivity due to bundled pain management contracts, while nursing facilities exhibit highest sensitivity under per-diem reimbursement constraints.
Supply Chain Analysis
Extended payment terms from hospital procurement committees strain working capital for subscale API suppliers, forcing supply-chain finance facility adoption among Chinese contract manufacturers. Finished formulation production concentrates in the United States, Ireland, and Japan, drawing from concentrated precursor chemical feedstocks in China and India. Single-source vulnerability permeates guanylate cyclase-C agonist API supply following regulatory audit failures at a major Zhejiang facility. Distribution runs through specialty pharmacy channels for self-administered subcutaneous formulations, with hospital-based oncology infusion centers dominating intravenous product flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in early-cycle expansion as REMS-mandated bundling creates structural demand pull for prophylactic laxation protocols in hospital oncology departments.
For Market Incumbents: Entrench formulary positioning by deepening backward integration into PAMORA API production to offset Chinese supply concentration risk, while expanding REMS compliance infrastructure to capture smaller developers lacking certification bandwidth. Threat from asset-light licensing entrants with digital therapeutic bundling capabilities demands preemptive hospital data partnership investments. For New Entrants and Emerging Players: Pursue refractory population device categories where bioelectronic stimulation systems face limited incumbent competition and premium reimbursement potential. Japan's METI-supported chronic pain initiatives offer the most penetrable geography for subcutaneous autoinjector formulations. Go-to-market execution should anchor on academic medical center pilot programs generating peer-reviewed outcome data. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed gastroenterology-focused salesforce platforms lacking REMS infrastructure scale. Long-term viability over a multi-year horizon hinges on digital therapeutic bundling capabilities and hospital system data integration. Watch FDA guidance on combination indication pathways as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Infrastructure Expansion | Mandatory prescriber certification creates fixed-cost barriers favoring Takeda-scale operational platforms. |
| Digital Therapeutic Bundling | Smartphone-based bowel diary apps in Germany create adherence-linked reimbursement models. |
| Subcutaneous Autoinjector Development | Self-administration formats extend treatment continuity into homecare settings post-discharge. |
| Academic Medical Center Pilot Programs | Implanted neuromodulation trials at Cleveland Clinic generate evidence for refractory population access. |
| API Manufacturing Backward Integration | Upstream control over PAMORA precursors mitigates Zhejiang supplier concentration risk. |
Study Parameters
A standing panel of formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists provided ongoing calibration against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Primary interviews with oncology pharmacy directors and gastroenterology salesforce heads combined with bottom-up prescription volume triangulation against top-down therapeutic category spend estimates.
Scenario-bracketing framed analytical development across the projection horizon, modeling treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from patient population growth rates, opioid utilization intensity projections, and formulary access probability weightings. Forecast inputs incorporated REMS compliance cost trajectories and prior authorization denial rate trends by payer type.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital therapeutic bundling entrants or API supply chain reshoring initiatives would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
Opioid Withdrawal Treatment Market
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
US Ketamine Clinics Market
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Methadone Market
Addiction Treatment
Drug Free Depression Treatment Market